
 Canada Ophthalmology Drugs and Devices Market | 2026-2036
Canada Ophthalmology Drugs and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Ophthalmology Drugs and Devices Market Outlook
Buyer concentration across Canadian hospital networks is shifting as provincial health authorities consolidate ophthalmology procurement into centralized tenders. Johnson & Johnson Vision Care leverages its established contact lens and surgical portfolio to secure multi-year supply agreements with these aggregating buyers. Alcon Inc. anchors its position through dominance in cataract consumables and phacoemulsification equipment installed base across major teaching hospitals. Carl Zeiss Meditec AG differentiates via optical coherence tomography platforms that integrate with provincial electronic health record systems.
Ophthalmology drugs and devices encompass pharmaceutical formulations for intraocular pressure management, infection control, and inflammation suppression alongside precision instruments for corneal modification, retinal visualization, and lens extraction. Intraocular implants manufactured from hydrophobic acrylic or silicone materials require biocompatibility testing under ISO 11979 standards to ensure long-term endothelial cell tolerance. Antiglaucoma agents retain the largest revenue pool within drug categories due to chronic administration patterns, while retinal imaging technology captures expanding capital budgets as diabetic retinopathy screening expands under provincial diabetes strategies. Phacoemulsification systems represent a mature installed base with replacement cycles driving periodic revenue spikes.
Health Canada's Medical Devices Directorate governs pre-market licensing through the Medical Devices Regulations under the Food and Drugs Act, requiring clinical evidence for Class III and IV ophthalmic implants. The Canadian Standards Association maintains adoption of ISO 13485 quality management systems as a de facto market access condition for foreign manufacturers. Provincial formularies administered by bodies such as Ontario's Ministry of Health and British Columbia's PharmaCare determine reimbursement eligibility for antiglaucoma and anti-inflammatory drug classes. Stakeholders must monitor evolving evidence requirements for combination drug-device products as regulatory convergence between pharmaceutical and device frameworks accelerates.
Market Dynamics
Provincial health authority consolidation in Ontario and Quebec is compressing ophthalmology procurement into centralized tenders, forcing manufacturers to restructure account management around aggregated hospital networks rather than individual facilities.
Growth Catalysts
- Diabetic retinopathy screening mandates:Provincial diabetes strategies in Ontario and British Columbia are expanding fundus photography and optical coherence tomography deployment into primary care networks.
- ISO 13485 quality system adoption:The Canadian Standards Association maintains this standard as a de facto market access condition, streamlining entry for compliant foreign manufacturers.
- Cataract surgical volume concentration:Urban tertiary centers in Toronto, Montreal, and Vancouver generate sustained demand for phacoemulsification consumables and intraocular lens replacement cycles.
Market Restraints
- Silicone and acrylic raw material concentration:Hydrophobic acrylic and silicone feedstocks for intraocular lens manufacturing concentrate among a limited supplier base, creating input cost volatility.
- Health Canada Class III/IV clinical evidence requirements:The Medical Devices Regulations under the Food and Drugs Act impose lengthy pre-market licensing timelines for novel ophthalmic implants.
- Extended replacement cycles for phacoemulsification systems:Mature installed bases across major teaching hospitals compress capital equipment refresh revenue to 7-10 year intervals.
Strategic Opportunities
- Atlantic Canada network penetration:Underserved retinal clinics in Halifax and St. John's present whitespace for diagnostic imaging platform deployment.
- Combination drug-device regulatory convergence:Health Canada's accelerating framework alignment creates pathways for sustained-release intraocular implants.
- Provincial electronic health record integration:Optical coherence tomography platforms that interface with Ontario's eHealth infrastructure capture preferential procurement positioning.
Industry Challenges
- Vitreoretinal surgeon training pipeline constraints:Fellowship positions in Canadian academic medical centers fail to match replacement demand from retiring specialists.
- ISO 11979 biocompatibility testing timelines:Endothelial cell tolerance validation for novel intraocular lens materials extends development cycles by 18-24 months.
- Legacy phacoemulsification system interoperability:New consumable formats face integration friction with decade-old equipment bases in community hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Ophthalmology Drugs and Devices Market |
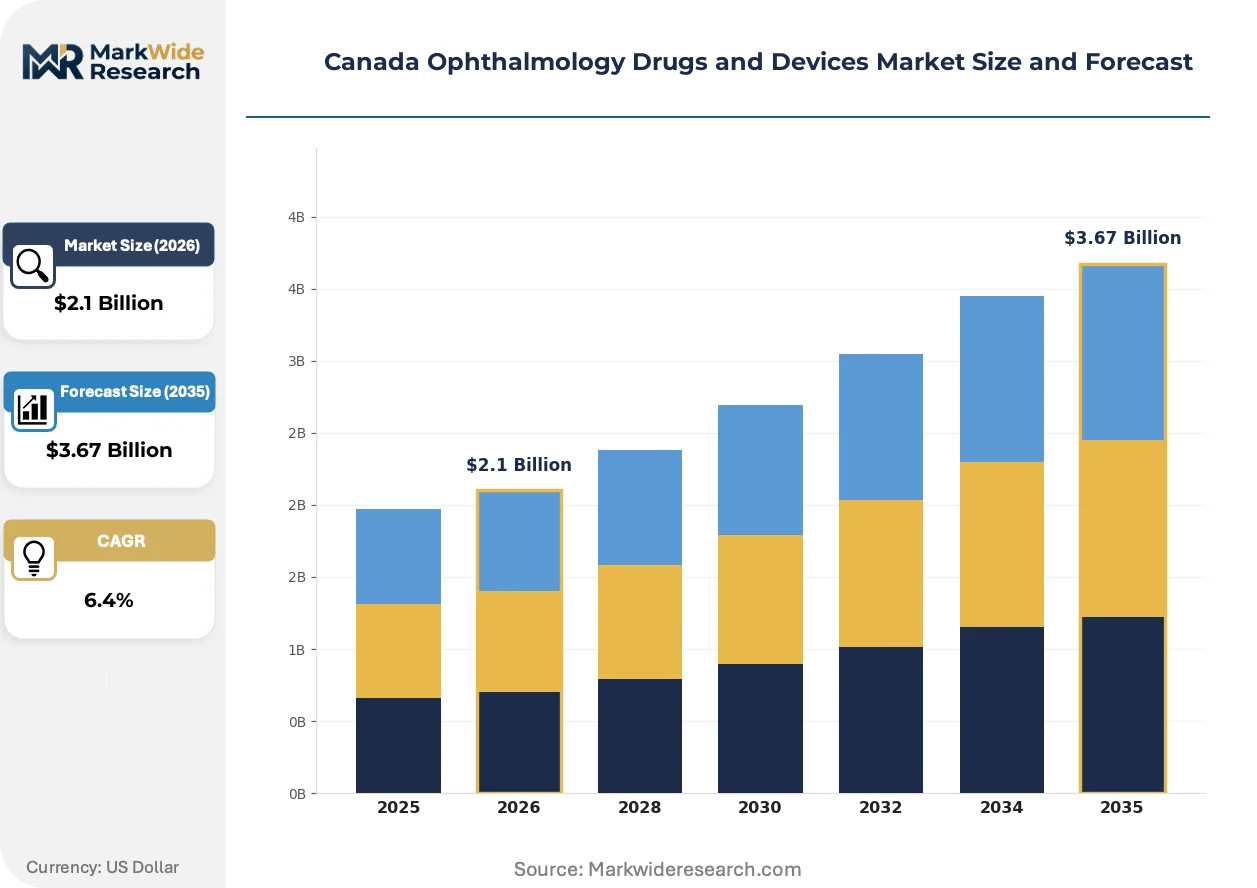
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiglaucoma Agents, Antibiotics, Anti-inflammatory Drugs, Intraocular Implants Technology: Laser Surgery, Optical Coherence Tomography, Phacoemulsification, Retinal Imaging Application: Cataract Surgery, Retinal Disorders, Glaucoma Treatment, Refractive Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions |
| Companies Covered | Johnson & Johnson Vision Care, Essilor, Alcon Inc., Topcon Corporation, Nidek Co. Ltd., Carl Zeiss Meditec AG, Novartis AG, Ziemer Group AG, Bausch Health Companies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Ophthalmology Drugs and Devices Market Strategic Shifts
Artificial intelligence integration and femtosecond laser adoption are compressing surgical variability while expanding diagnostic automation across Canadian ophthalmology workflows.
Femtosecond laser-assisted cataract surgery is rewriting procedural standardization in academic medical centers. University Health Network in Toronto and McGill University Health Centre have adopted these platforms for corneal incision and lens fragmentation. The technology is rewriting cost structures by reducing phacoemulsification energy requirements and standardizing outcomes across trainee surgeons.
Health Canada's Medical Devices Directorate has tightened pre-market review pathways for intraocular lenses and diagnostic imaging systems under the Medical Devices Regulations. Manufacturers now face expanded clinical evidence requirements for Class III ophthalmic implants. The regulatory shift most affects silicone-hydrogel lens developers seeking expedited approval timelines.
Provincial tender aggregation is consolidating purchasing authority under Ontario's Ministry of Health and Quebec's centralized health authority frameworks. Independent community hospitals lose negotiating leverage as multi-year supply agreements concentrate with network-level procurement officers. This behavioral shift is most visible in cataract consumable contracting across the Greater Toronto Area hospital alliances.
Canada Ophthalmology Drugs and Devices Market Segmentation
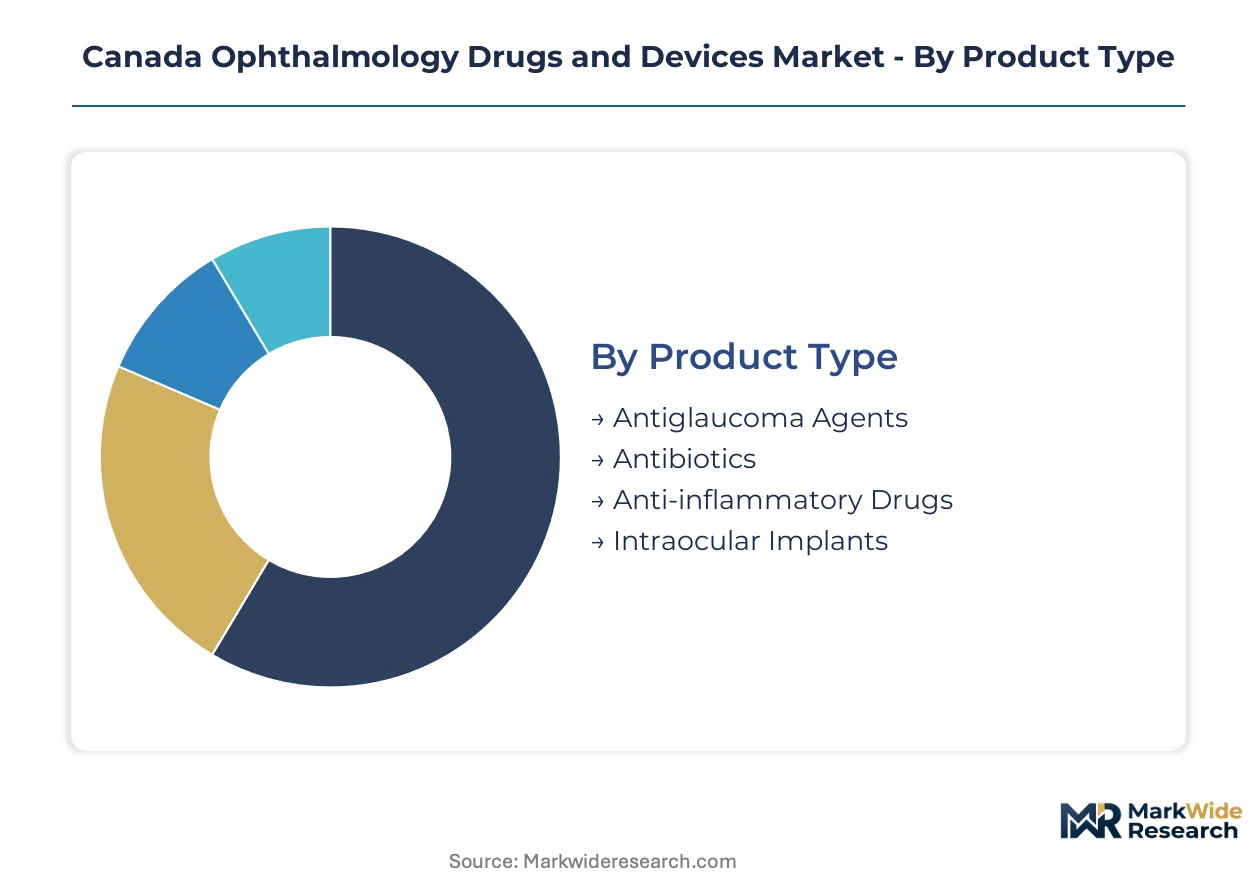
Canada's ophthalmology market fragments along product, technology, application, and end-user dimensions that each carry distinct procurement pathways. Provincial health authority consolidation favors segments with standardized tender compliance and electronic health record interoperability.
Product Type:
Supply concentration among hydrophobic acrylic and silicone feedstock suppliers shapes manufacturing economics across all product categories.
- Antiglaucoma Agents:Pharmaceutical formulations for intraocular pressure management include prostaglandin analogs, beta-blockers, and carbonic anhydrase inhibitors. Chronic administration patterns generate recurring revenue streams concentrated in urban tertiary centers across Toronto and Montreal where patient volumes sustain formulary placement.
- Intraocular Implants:Hydrophobic acrylic and silicone lenses require ISO 11979 biocompatibility validation for endothelial cell tolerance. Health Canada's Medical Devices Directorate imposes extended pre-market licensing timelines for novel materials, compressing developer pipelines.
- Antibiotics:Fluoroquinolone and aminoglycoside formulations target post-surgical infection prophylaxis.
- Anti-inflammatory Drugs:Corticosteroid and NSAID formulations manage postoperative inflammation.
Antiglaucoma agents absorb the bulk of installed capacity; intraocular implants are expanding most quickly.
Technology:
Capital equipment replacement cycles and provincial screening mandates drive divergent investment patterns across technology categories.
- Optical Coherence Tomography:Non-invasive retinal imaging platforms generate cross-sectional tissue visualization for diabetic retinopathy and macular degeneration diagnosis. Ontario's provincial diabetes strategy is deploying these systems into primary care networks, accelerating fundus photography integration with eHealth infrastructure.
- Phacoemulsification:Ultrasonic lens fragmentation systems represent a mature installed base with 7-10 year replacement cycles. University Health Network and McGill University Health Centre anchor demand for next-generation platforms with femtosecond laser compatibility.
- Laser Surgery:Femtosecond and excimer platforms enable corneal modification and lens fragmentation.
- Retinal Imaging:Fundus photography and angiography systems support screening program expansion.
Phacoemulsification retains the deepest installed base; optical coherence tomography shows the steepest expansion trajectory.
Application:
Procedure volume concentration in urban academic medical centers creates asymmetric demand distribution across application segments.
- Cataract Surgery:Lens extraction and replacement procedures generate the highest surgical volumes across Canadian ophthalmology. Hospital network consolidation in Ontario and Quebec is compressing procurement into centralized tenders for consumables and intraocular lenses.
- Retinal Disorders:Diabetic retinopathy, age-related macular degeneration, and retinal detachment interventions require specialized vitreoretinal surgical capacity. Fellowship training pipeline constraints at Canadian academic medical centers limit specialist availability.
- Glaucoma Treatment:Medical and surgical management of intraocular pressure spans pharmaceutical and procedural interventions.
- Refractive Surgery:Elective corneal modification procedures operate outside provincial health coverage frameworks.
Cataract surgery absorbs the bulk of installed capacity; retinal disorders are climbing the fastest.
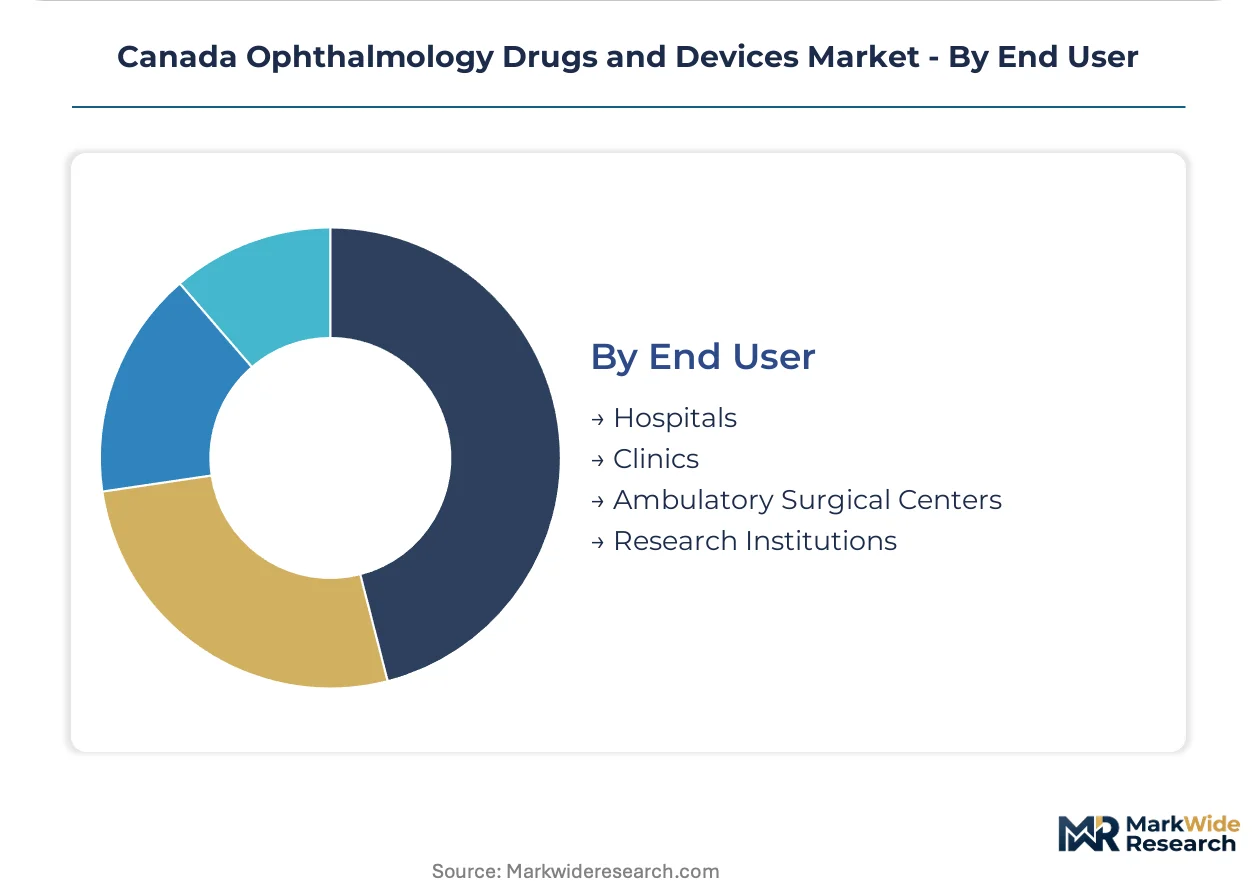
End User:
Procurement authority migration from individual facilities to provincial network administrators restructures vendor relationship economics.
- Hospitals:Tertiary academic medical centers in Toronto, Montreal, and Vancouver concentrate surgical volumes and specialized retinal clinics. Provincial health authority frameworks are aggregating purchasing power across formerly independent institutions.
- Clinics:Community ophthalmology practices and specialized retinal clinics in Halifax and St. John's present whitespace for diagnostic imaging deployment. Atlantic Canada networks remain underserved relative to central Canadian density.
- Ambulatory Surgical Centers:Outpatient cataract and refractive procedure facilities operate with streamlined capital requirements.
- Research Institutions:University-affiliated centers drive clinical trial recruitment for novel intraocular lens materials.
Hospitals absorb the bulk of installed capacity; clinics are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Ontario and Quebec where provincial health authority frameworks aggregate procurement for cataract and glaucoma procedures. British Columbia and Alberta anchor diagnostic imaging expansion through diabetes screening mandates. Atlantic Canada presents whitespace for retinal clinic development.
Ontario
University Health Network and Sunnybrook anchor surgical volumes for femtosecond laser-assisted cataract procedures. Health Canada's Medical Devices Directorate licenses Class III intraocular implants through extended clinical evidence pathways. Toronto's hospital alliances consolidate multi-year supply agreements for phacoemulsification consumables.
Quebec
McGill University Health Centre drives adoption of next-generation diagnostic platforms for retinal disorders. The province's centralized health authority framework compresses ophthalmology procurement into network-level tenders. Montreal's academic medical centers generate sustained demand for optical coherence tomography systems.
British Columbia
Provincial diabetes strategies deploy fundus photography into primary care networks across Vancouver Coastal Health. PharmaCare determines reimbursement eligibility for antiglaucoma agents through evidence-based formulary reviews. Vancouver's specialized retinal clinics cluster diagnostic imaging capacity for age-related macular degeneration.
Alberta
Calgary and Edmonton tertiary centers concentrate vitreoretinal surgical capacity for complex retinal detachment interventions. The province's health authority structures procurement for intraocular lenses through standardized tender compliance. Fellowship training pipeline constraints at University of Alberta limit specialist availability for expanding patient volumes.
Atlantic Canada
Halifax and St. John's present undersupplied markets for optical coherence tomography deployment in community retinal clinics. Nova Scotia's health authority administers provincial formulary placement for anti-inflammatory ophthalmic drugs. Queen Elizabeth II Health Sciences Centre anchors the region's limited vitreoretinal surgical capacity.
Canada Ophthalmology Drugs and Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue diagnostic imaging integration and combination drug-device convergence. Market structure consolidates around multinational portfolios with installed base advantages in phacoemulsification and contact lens categories. Three archetypes dominate: diversified healthcare conglomerates with surgical and pharmaceutical arms, precision optics specialists with diagnostic platform expertise, and regional distributors with provincial tender compliance capabilities. Competitive moves center on multi-year supply agreement negotiation with aggregated hospital networks and regulatory pathway optimization for Class III implant licensing.
Among diversified healthcare conglomerates, Johnson & Johnson Vision Care and Alcon Inc. exemplify portfolio breadth spanning consumables, capital equipment, and pharmaceutical formulations. Carl Zeiss Meditec AG occupies a position among precision optics specialists, representing diagnostic imaging platform integration with electronic health record infrastructure. These three anchors illustrate how competitive positioning depends on provincial tender compliance and Health Canada licensing timelines rather than product-specific differentiation alone.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care |
| Essilor |
| Alcon Inc. |
| Topcon Corporation |
| Nidek Co. Ltd. |
| Carl Zeiss Meditec AG |
| Novartis AG |
| Ziemer Group AG |
| Bausch Health Companies Inc. |
| Others |
Value Chain & Pricing Dynamics
Multinational healthcare conglomerates with vertically integrated surgical and pharmaceutical portfolios anchor supply discipline and pricing power across Canadian ophthalmology procurement. Their control over hydrophobic acrylic feedstock sourcing and phacoemulsification installed bases shapes how provincial health authorities negotiate multi-year supply agreements.
Pricing Analysis
High-volume consumables trade on thin margins while capital equipment and novel implants command premium pricing. Three-tier pricing structure across premium, standard, and economy levels differentiates by Health Canada licensing tier and ISO 13485 certification status. Cost compression in standard-tier intraocular lenses is intensifying because Ontario's centralized tenders aggregate purchasing power across hospital networks. Community hospitals exhibit acute price sensitivity compared to academic medical centers that prioritize femtosecond laser compatibility.
Supply Chain Analysis
Single-source vulnerability sits with hydrophobic acrylic and silicone feedstock suppliers concentrated in the United States, Germany, and Japan. Manufacturing draws from specialized polymer resin inputs, precision optical components, and ultrasonic transducer assemblies. Tariff exposure on imported intraocular lens materials threatens margin stability for foreign manufacturers serving Health Canada's Class III licensing pathways. Distribution runs through provincial health authority procurement frameworks that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canadian ophthalmology is becoming a vertical-integration race where control over silicone-hydrogel material supply and electronic health record interoperability determines long-term positioning. Players are pursuing backward integration into biocompatible polymer manufacturing to secure input cost stability.
For Market Incumbents: Cement multi-year supply agreements with Ontario's hospital alliances before Quebec completes its procurement consolidation. Lock in femtosecond laser-compatible phacoemulsification upgrade cycles at University Health Network and McGill University Health Centre. Acquire Atlantic Canada distributor networks to preempt emerging diagnostic imaging entrants. For New Entrants and Emerging Players: The mid-tier pricing gap between Carl Zeiss Meditec AG premium platforms and refurbished legacy systems offers entry whitespace. Target Halifax and St. John's retinal clinics with optical coherence tomography platforms featuring simplified eHealth integration. Lead with provincial diabetes screening program compliance to bypass incumbent installed base advantages. For Investors and Strategic Acquirers: Health Canada's publication of combination drug-device guidance documents is the leading indicator that sustained-release intraocular implant developers will command acquisition premiums. Focus on mid-cap specialists with ISO 11979 biocompatibility validation completed but lacking commercial scale. Watch for fellowship training pipeline expansion announcements at Canadian academic medical centers as capacity constraint relief signals.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class III Licensing Pathway | Accelerated pre-market review unlocks novel silicone-hydrogel implant commercialization. |
| Provincial EHR Integration Partnership | Ontario eHealth interoperability secures preferential diagnostic imaging procurement positioning. |
| Atlantic Canada Clinic Network Expansion | Halifax and St. John's whitespace captures underserved retinal screening demand. |
| Biocompatible Polymer Backward Integration | In-house hydrophobic acrylic production insulates against feedstock cost volatility. |
| Fellowship Training Pipeline Investment | University-affiliated vitreoretinal capacity expansion addresses specialist shortage constraints. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and provincial formulary directors combined with Health Canada Medical Devices Directorate licensing databases, Ontario Ministry of Health tender documents, and Canadian Standards Association certification records. Bottom-up surgical volume modeling and top-down pharmaceutical expenditure estimates underwent triangulation validation.
Granularity-level modeling distinguished product type, technology platform, application procedure, and end-user facility tier across the projection horizon. Cataract surgery volumes, diabetic retinopathy screening penetration, and phacoemulsification replacement cycles informed analytical framework construction. CAGRs derived from segmented volume projections weighted by provincial health authority procurement timelines.
Underlying measurement precision varies by segment; antiglaucoma agent pharmaceutical data carries tighter precision than emerging combination drug-device categories. Forecasts reflect assumptions about Health Canada regulatory convergence timing and provincial tender aggregation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Meibomian Gland Dysfunction Treatment Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Pseudotumor Cerebri Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Dacryocystitis Market
Ophthalmology
Eye Allergy Treatment Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market