
 Uveal Melanoma Market | 2026-2036
Uveal Melanoma Market Size, Share, and Industry Trends Forecast 2026-2036
Uveal Melanoma Market Analysis
Oncology-focused academic medical centers is collapsing the historical dominance of general ophthalmology practices as the primary referral channel for complex uveal melanoma cases. Immunocore Holdings leverages its T-cell receptor platform to anchor demand in bispecific immuno-oncology. Novartis sustains competitive presence through targeted therapy development pipelines. Eli Lilly and Company differentiates via radiopharmaceutical investments in ocular oncology.
Uveal melanoma constitutes a primary intraocular malignancy arising from melanocytes within the choroid, ciliary body, or iris, typically requiring multidisciplinary management combining plaque brachytherapy, enucleation, or systemic intervention based on tumor size, location, and metastatic risk stratification. Immunotherapy product types command expanding development investment as checkpoint inhibitors and T-cell engagers advance through clinical validation. Combination therapy modalities concentrate margin pools where localized plaque radiation integrates with systemic adjuvant protocols to address micrometastatic disease.
The FDA oversees orphan drug and breakthrough therapy designations that compress development timelines for novel uveal melanoma therapeutics, while the EMA parallels this through PRIME eligibility pathways in Europe. HIPAA governs real-world evidence collection from academic centers that supports post-market surveillance and label expansion for ocular oncology agents. Stakeholders must monitor regulatory divergence between FDA accelerated approval criteria and EMA conditional marketing authorization requirements when designing parallel submission strategies for metastatic uveal melanoma indications.
Market Dynamics
Academic medical centers are consolidating complex uveal melanoma referrals away from general ophthalmology practices, concentrating specialized care within tertiary oncology networks and reshaping patient flow dynamics across treatment pathways.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:The FDA's accelerated designation compresses clinical development timelines for novel immuno-oncology agents targeting metastatic disease, enabling earlier patient access to investigational therapies.
- T-Cell Receptor Engineering:Bispecific T-cell engager platforms are expanding therapeutic options beyond conventional checkpoint inhibition, creating new intervention points for high-risk patient populations.
- United States:Concentration of dedicated ocular melanoma treatment centers in Boston, Philadelphia, and Houston generates referral gravity that pulls complex cases from dispersed regional markets.
Market Restraints
- Specialized Radiopharmaceutical Supply:Limited production capacity for iodine-125 plaque sources and lutetium-based radioligands creates bottlenecks in localized radiation delivery.
- EMA Conditional Authorization Friction:Divergent evidentiary requirements between FDA accelerated approval and EMA conditional marketing authorization complicate parallel regulatory submissions for European market entry.
- Small Patient Cohorts:Ultra-rare disease prevalence restricts randomized trial enrollment, forcing reliance on single-arm studies that regulators scrutinize more heavily for durability claims.
Strategic Opportunities
- Adjuvant Therapy Protocols:Integration of systemic agents with plaque brachytherapy creates combination therapy margins where localized radiation addresses the primary tumor while systemic treatment targets micrometastatic seeding.
- Real-World Evidence Networks:HIPAA-governed data collection from academic centers supports post-market surveillance and label expansion without requiring additional prospective trials.
- Companion Diagnostic Development:Genomic risk stratification tools that identify high-metastatic-risk patients are creating segmented treatment pathways that match intervention intensity to disease biology.
Industry Challenges
- Ocular Oncology Specialist Shortage:Limited fellowship-trained physicians capable of managing complex cases creates access bottlenecks and extends referral-to-treatment intervals.
- Cross-Border Regulatory Harmonization:Divergent orphan drug incentive structures between the FDA and EMA force developers to maintain separate evidence-generation strategies for each jurisdiction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uveal Melanoma Market |
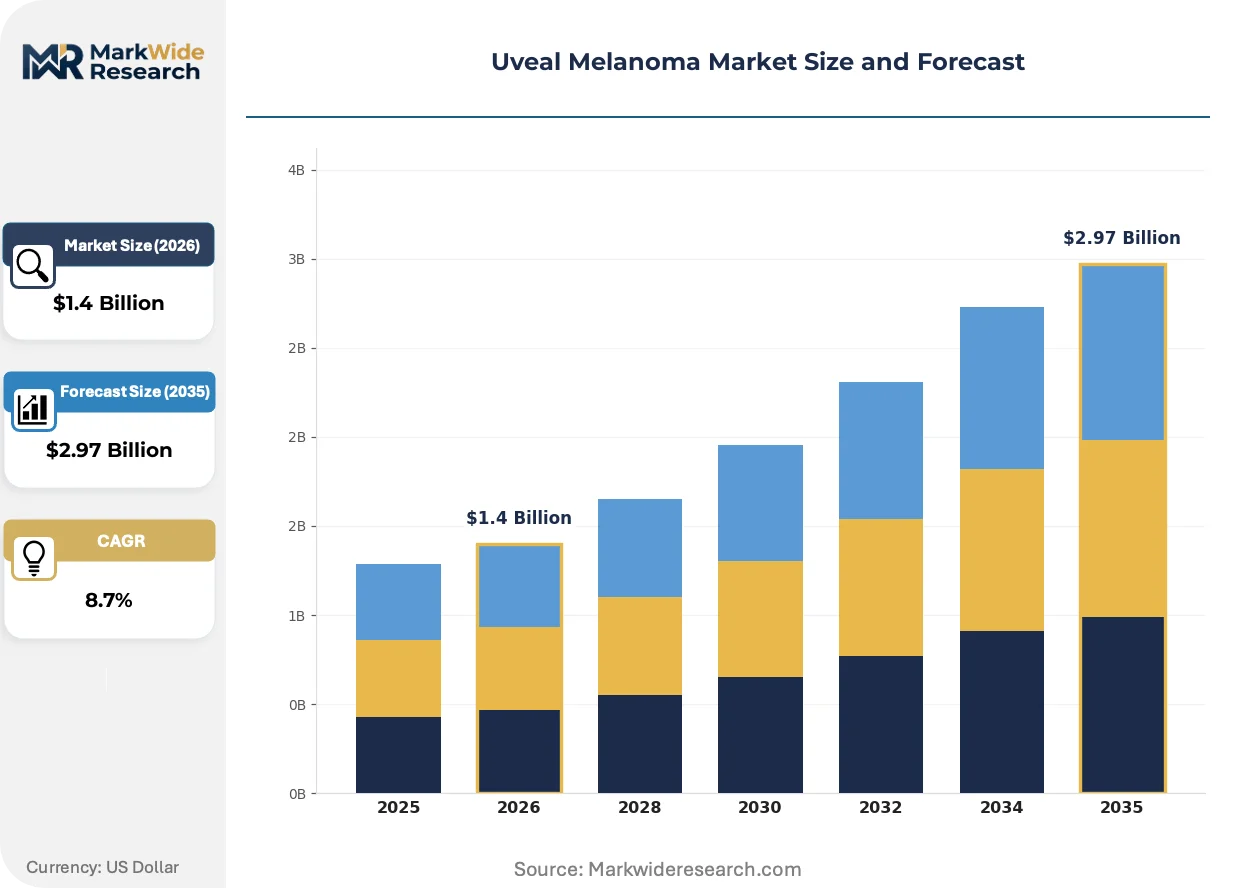
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiation Therapy, Surgical Treatment, Chemotherapy, Immunotherapy Therapy Area: Oncology, Ophthalmology, Medical Oncology, Surgical Oncology Care Setting: Hospitals, Outpatient Clinics, Specialty Centers, Research Institutions Treatment Modality: Localized Therapy, Systemic Therapy, Targeted Therapy, Combination Therapy |
| Companies Covered | Immunocore Holdings, Novartis, Eli Lilly and Company, Merck & Co., Pfizer, Aura Biosciences, IDEAYA Biosciences, AstraZeneca, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uveal Melanoma Market Emerging Trajectories
Therapeutic development is pivoting from cytotoxic agents toward precision immuno-oncology platforms, while regulatory frameworks adapt to accommodate smaller evidence bases for ultra-rare indications.
Adoptive cell therapy is decomposing the historical dominance of checkpoint inhibitors in metastatic uveal melanoma treatment. Academic medical centers in the United States are establishing dedicated cellular therapy units to administer tumor-infiltrating lymphocyte protocols. This technology is decomposing the standard-of-care timeline by enabling durable responses in patients who progress on prior systemic lines.
The FDA's Breakthrough Therapy designation is compressing development timelines for novel ocular oncology agents by enabling more frequent agency engagement and rolling review structures. Developers are prioritizing this pathway over standard orphan drug exclusivity mechanisms to accelerate commercial access. Metastatic indications are responding most aggressively, with sponsors structuring Phase 2 trials to support accelerated approval based on response rate endpoints.
Patient referral patterns are consolidating within specialized ocular oncology networks as general ophthalmology practices recognize case complexity limits. Community eye care providers are establishing formal referral agreements with academic centers rather than attempting local management. This channel concentration is most visible in the Northeastern United States, where proximity to Boston and Philadelphia treatment hubs enables same-day multidisciplinary consultation access.
Uveal Melanoma Market Segmentation
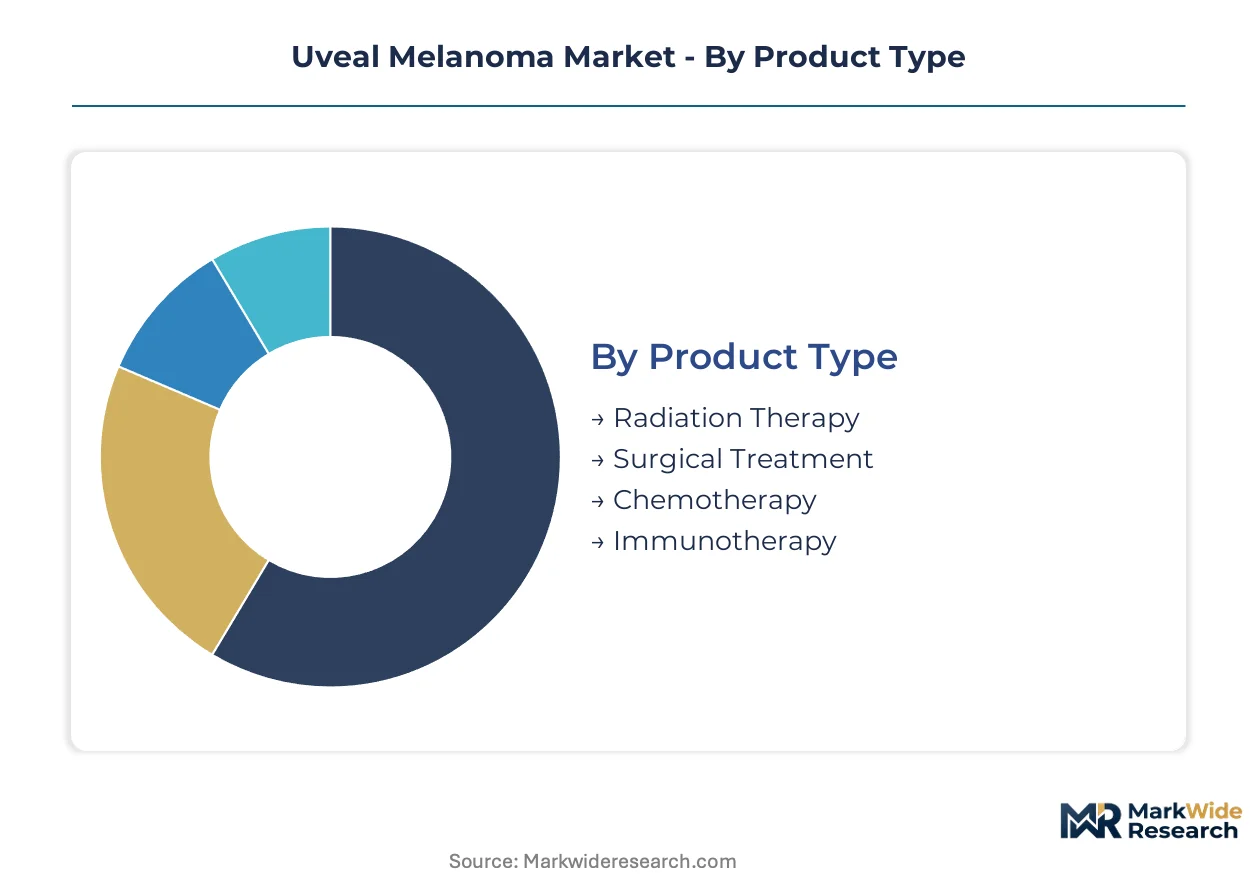
Segmentation in uveal melanoma reveals how margin pools concentrate around precision interventions versus commodity care. Treatment modality and care setting together determine reimbursement rates and patient access pathways across the disease continuum.
Product Type:
Margin pools concentrate in immunotherapy and targeted radiation platforms where orphan drug pricing applies and manufacturing complexity limits competition.
- Immunotherapy:T-cell receptor engineering and bispecific engagers command premium pricing through breakthrough therapy designations. Demand concentrates in academic medical centers at Massachusetts Eye and Ear, Wills Eye Hospital, and MD Anderson Cancer Center, driven by metastatic disease protocols requiring specialized cellular therapy infrastructure.
- Radiation Therapy:Iodine-125 plaque brachytherapy and proton beam platforms anchor localized treatment margins. Demand concentrates in dedicated ocular oncology units where physicist staffing and plaque customization capabilities create service differentiation against general radiation oncology departments.
- Surgical Treatment:Enucleation and local resection procedures represent established standards with compressed margins. Demand follows referral patterns to tertiary centers with ocular prosthetics integration.
- Chemotherapy:Cytotoxic regimens occupy declining share as checkpoint inhibitors displace historical standards. Demand persists in resource-constrained settings lacking cellular therapy access.
The dominant share belongs to radiation therapy, while immunotherapy is closing the gap fastest.
Therapy Area:
Volume flows through oncology-specialized channels rather than general ophthalmology, reshaping credentialing requirements and referral economics.
- Medical Oncology:Systemic therapy management for metastatic disease generates highest per-patient revenue through immuno-oncology agents. Demand concentrates in comprehensive cancer centers where phase 1 trial access attracts high-risk patient populations.
- Surgical Oncology:Resection and metastasectomy procedures integrate with systemic protocols. Demand follows hepatic-directed therapy centers managing the predominant metastatic pattern to the liver.
- Oncology:General oncology departments handle initial diagnosis and coordination. Demand reflects community penetration of ocular melanoma awareness programs.
- Ophthalmology:Diagnostic and surveillance functions retain importance despite care migration. Demand concentrates in retina specialists with ultrasound biomicroscopy capabilities.
Medical oncology captures the largest patient flow, while surgical oncology is expanding most quickly through hepatic intervention protocols.
Care Setting:
Reimbursement differentials favor inpatient-adjacent facilities where multidisciplinary tumor boards justify comprehensive billing codes.
- Specialty Centers:Dedicated ocular melanoma programs at academic medical centers command premium reimbursement through NCI-designated comprehensive cancer center status. Demand concentrates where plaque brachytherapy, systemic therapy, and clinical trials coexist on single campuses.
- Hospitals:General hospital oncology departments handle staging and initial systemic therapy. Demand reflects proximity to specialized referral networks.
- Research Institutions:Phase 1 and 2 trial sites attract traveling patients seeking investigational T-cell therapies. Demand concentrates at NIH-funded centers with active cellular therapy manufacturing.
- Outpatient Clinics:Community settings manage surveillance and stable disease monitoring. Demand follows patient preference for local access during extended follow-up periods.
Specialty centers hold the dominant position, though research institutions are gaining share fastest through expanded cellular therapy trials.
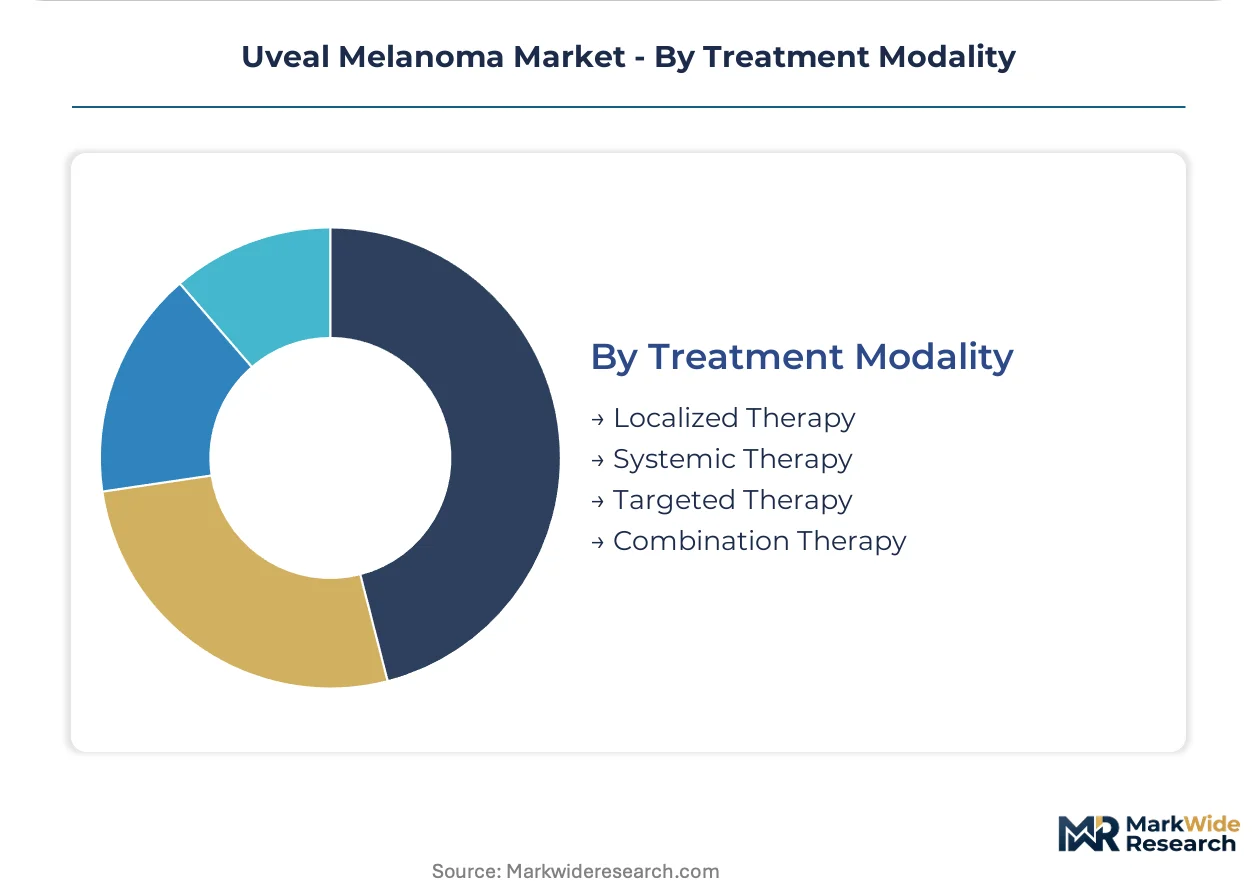
Treatment Modality:
Combination approaches generate stacked reimbursement where localized and systemic interventions bill sequentially rather than competitively.
- Combination Therapy:Integration of plaque brachytherapy with adjuvant systemic agents creates margin stacking. Demand concentrates in risk-stratified protocols identifying high-metastatic-risk patients through gene expression profiling.
- Targeted Therapy:MEK and PKC inhibitors address specific molecular subsets with companion diagnostic requirements. Demand follows biomarker testing penetration in academic pathology laboratories.
- Localized Therapy:Plaque brachytherapy and proton beam retain standard-of-care status for primary tumor control. Demand reflects radiation oncology physics capacity constraints.
- Systemic Therapy:Checkpoint inhibitors and adoptive cell therapy address metastatic disease. Demand concentrates in centers with hepatobiliary surgical oncology for liver-directed interventions.
Localized therapy maintains the largest installed base, while combination therapy is climbing the fastest as adjuvant protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialized ocular oncology networks concentrate patient referrals and clinical trial access in distinct national markets. Regulatory pathways and reimbursement structures vary substantially across jurisdictions, shaping where novel therapies launch first.
United States
FDA Breakthrough Therapy designations and orphan drug incentives attract developers to launch metastatic uveal melanoma trials domestically first. Massachusetts Eye and Ear, Wills Eye Hospital in Philadelphia, and MD Anderson Cancer Center in Houston anchor specialized treatment networks that pull complex cases from dispersed regional markets through formal referral agreements.
Germany
EMA centralized procedures and national reimbursement negotiations through the G-BA create predictable market access for novel ocular oncology agents. Heidelberg and Essen host leading ocular melanoma programs that integrate plaque brachytherapy with hepatic-directed interventions for liver-predominant metastatic patterns.
United Kingdom
NICE technology appraisals and Cancer Drugs Fund access schemes determine adoption timelines for systemic therapies. London's Royal Liverpool University Hospital and Moorfields Eye Hospital concentrate surgical oncology expertise and maintain active cellular therapy trial portfolios for high-risk patient populations.
Switzerland
Swissmedic's accelerated access pathways and premium reimbursement for orphan indications support early commercial launches. Basel and Zurich academic centers leverage proximity to pharmaceutical R&D headquarters to secure phase 1 and 2 trial participation for T-cell receptor engineering platforms.
France
ANSM early access programs and hospital-based drug procurement create favorable conditions for innovative immuno-oncology introductions. Paris and Lyon ocular oncology units participate actively in European consortium trials and maintain specialized plaque brachytherapy physics capabilities.
Uveal Melanoma Market Vendor Landscape
Player mix skews toward biopharmaceutical specialists with immuno-oncology platforms and diversified oncology portfolios. Market structure concentrates around developers holding breakthrough therapy designations and radiopharmaceutical capabilities. Strategic archetypes include T-cell receptor engineering specialists, targeted therapy developers, and radiopharmaceutical investors. Competitive moves center on clinical trial portfolio expansion and regulatory pathway prioritization.
Within the T-cell receptor engineering tier, Immunocore Holdings exemplifies platform-specialized development approaches. Novartis and Eli Lilly and Company occupy positions representing diversified pharmaceutical investment in ocular oncology pipelines. These three anchors illustrate how developers are concentrating resources on metastatic indications and combination therapy protocols.
| Leading Market Players |
|---|
| Immunocore Holdings |
| Novartis |
| Eli Lilly and Company |
| Merck & Co. |
| Pfizer |
| Aura Biosciences |
| IDEAYA Biosciences |
| AstraZeneca |
| Bristol-Myers Squibb |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at iodine-125 plaque manufacturing facilities in the United States and Germany shapes both supply concentration and minimum viable pricing for localized radiation delivery. Scale economies in radiopharmaceutical production create natural price floors that smaller academic centers struggle to negotiate against tertiary oncology networks with consolidated purchasing power.
Pricing Analysis
Cost-plus contracts with iodine-125 suppliers index to raw isotope spot markets, creating quarterly price volatility that academic medical centers hedge through multi-year offtake agreements. Orphan drug pricing for T-cell receptor therapies stratifies across breakthrough-designated premium tiers, standard-of-care checkpoint inhibitors, and economy-positioned cytotoxic remnants. Pricing pressure stems from Medicare reimbursement compression on plaque brachytherapy procedures. Community oncology practices exhibit highest price sensitivity due to limited patient volume to amortize fixed physics staffing costs.
Supply Chain Analysis
Inventory lead times for customized iodine-125 plaques extend 4-6 weeks due to physicist calibration requirements and isotope decay logistics. Manufacturing concentrates in the United States, Germany, and Switzerland where nuclear regulatory frameworks permit medical isotope handling. Supply chains draw from Canadian reactor-sourced molybdenum-99 and South African iodine-131 feedstocks. Single-source vulnerability permeates lutetium-177 radioligand production where two European facilities control global output. Distribution runs through hospital-based nuclear pharmacies with radioactive materials licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment through FDA Breakthrough Therapy and EMA PRIME designations creates substantial barriers to competitive replication.
For Market Incumbents: Fortify position by deepening backward integration into radiopharmaceutical manufacturing to secure iodine-125 supply against Canadian reactor maintenance cycles. Expand cellular therapy unit capacity at Massachusetts Eye and Ear and MD Anderson to capture referral consolidation from community ophthalmology practices threatened by adoptive cell therapy protocol complexity. For New Entrants and Emerging Players: Anchor in adjuvant therapy protocols where gene expression profiling creates addressable high-risk patient segments underserved by current localized-only treatment paradigms. Target research institution partnerships with NIH-funded centers lacking in-house cellular therapy manufacturing capabilities. Pursue companion diagnostic co-development strategies that lock in downstream therapeutic pull-through. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-specialized developers with T-cell receptor engineering capabilities and multiple ocular oncology indications in pipeline. Long-term viability rests on regulatory exclusivity durability and manufacturing scalability for personalized cellular therapies. Acquisition targets should display active Breakthrough Therapy designation momentum and established academic center investigator relationships. Watch for FDA advisory committee scheduling as inflection signal for accelerated approval probability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase 2 trials structured for accelerated approval compress development timelines for metastatic indications. |
| Regulatory Approval Pathway | Breakthrough Therapy designation enables rolling review and earlier FDA engagement than standard orphan drug routes. |
| Manufacturing Scale-Up | Cellular therapy unit expansion at academic medical centers addresses physicist and isotope handling bottlenecks. |
| Pipeline Diversification | Adjuvant therapy indications expand addressable patient population beyond metastatic disease alone. |
| Strategic Partnership | Companion diagnostic collaborations with academic pathology laboratories secure biomarker-driven patient selection. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA Breakthrough Therapy designation records, ClinicalTrials.gov ocular oncology protocols, and EMA PRIME eligibility decisions. Primary interviews engaged drug development executives at immuno-oncology platform companies, regulatory affairs leads navigating parallel FDA-EMA submissions, formulary directors at NCI-designated comprehensive cancer centers, and hospital procurement managers specializing in radiopharmaceutical sourcing. Secondary validation drew from SEC 10-K oncology pipeline disclosures, CMS Medicare reimbursement schedules for plaque brachytherapy, and GPO contract databases for iodine-125 procurement. Bottom-up patient flow modeling triangulated against top-down market sizing from tertiary referral network capacity analysis.
Segmentation dimensions modeled include treatment modality, care setting, therapy area, and product type across the projection horizon. Analytical framework incorporated gene expression profiling penetration rates, cellular therapy unit expansion trajectories, and orphan drug pricing elasticity assumptions. CAGRs derived from weighted average of epidemiological incidence projections, treatment rate evolution, and price indexation patterns. Industry-specific inputs captured hepatic-directed therapy adoption for liver-predominant metastatic patterns and real-world evidence network maturation for post-market surveillance.
Material uncertainties — regulatory divergence between FDA accelerated approval and EMA conditional authorization, isotope supply disruptions from aging reactor infrastructure, and cellular therapy manufacturing scale constraints — sit outside the modeled envelope. Forecasts reflect assumptions regarding referral pattern consolidation and reimbursement stability for combination therapy protocols. Revision becomes warranted when Breakthrough Therapy designation conversion rates to full approval cross historical oncology benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
Global Hemianopsia Market
Ophthalmology
Astigmatism Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
Retina Health Market
Ophthalmology
Dacryocystitis Market
Ophthalmology
Global Posterior Segment Eye Disorders Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Global Uveitis Treatment Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Japan Dry Eye Syndrome Market
Ophthalmology
Anterior Uveitis Market
Ophthalmology
Extended and Continuous Wear Lenses Market