
 Global Ocular Inflammation Treatment Market | 2026-2036
Global Ocular Inflammation Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ocular Inflammation Treatment Market Foresight
EU MDR is consolidating the cost-of-entry calculus for sustained-release ocular implants, forcing smaller device manufacturers to absorb disproportionate clinical-evaluation burdens. Bausch Health Companies leverages its vertically integrated manufacturing network to sustain European market access across steroid-eluting portfolios. Pfizer competes through scaled corticosteroid supply chains that anchor hospital formulary contracts in North America and Asia-Pacific.
Ocular inflammation treatment encompasses pharmacological and device-based interventions targeting uveitis, scleritis, and post-surgical inflammation, typically employing corticosteroids, immunomodulators, or biologic agents formulated for intraocular, periocular, or topical delivery with specific release kinetics measured in weeks to months. These therapies serve to prevent vision loss, control recurrent inflammatory episodes, and reduce dependence on systemic immunosuppression in chronic cases. Biologics represents the fastest-expanding product category as anti-TNF and anti-IL mechanisms displace chronic steroid exposure in refractory uveitis patients, while topical steroids still dominate prescription volume in acute anterior segment disease. Intravitreal administration routes command premium positioning due to specialist-dependent delivery and longer dosing intervals, though subconjunctival approaches are gaining traction for intermediate uveitis where systemic side-effect profiles deter oral alternatives.
FDA, EMA, and Japan's PMDA each enforce distinct stability-testing and sterility-validation protocols that fragment registration timelines and regional launch sequencing for combination drug-device products. The EU AI Act and GDPR impose additional algorithmic-transparency requirements on AI-assisted diagnostic platforms used to stratify inflammation severity prior to treatment selection. Stakeholders must monitor evolving pharmacovigilance mandates from WHO prequalification pathways that could unlock pooled procurement contracts in lower-income markets.
Market Dynamics
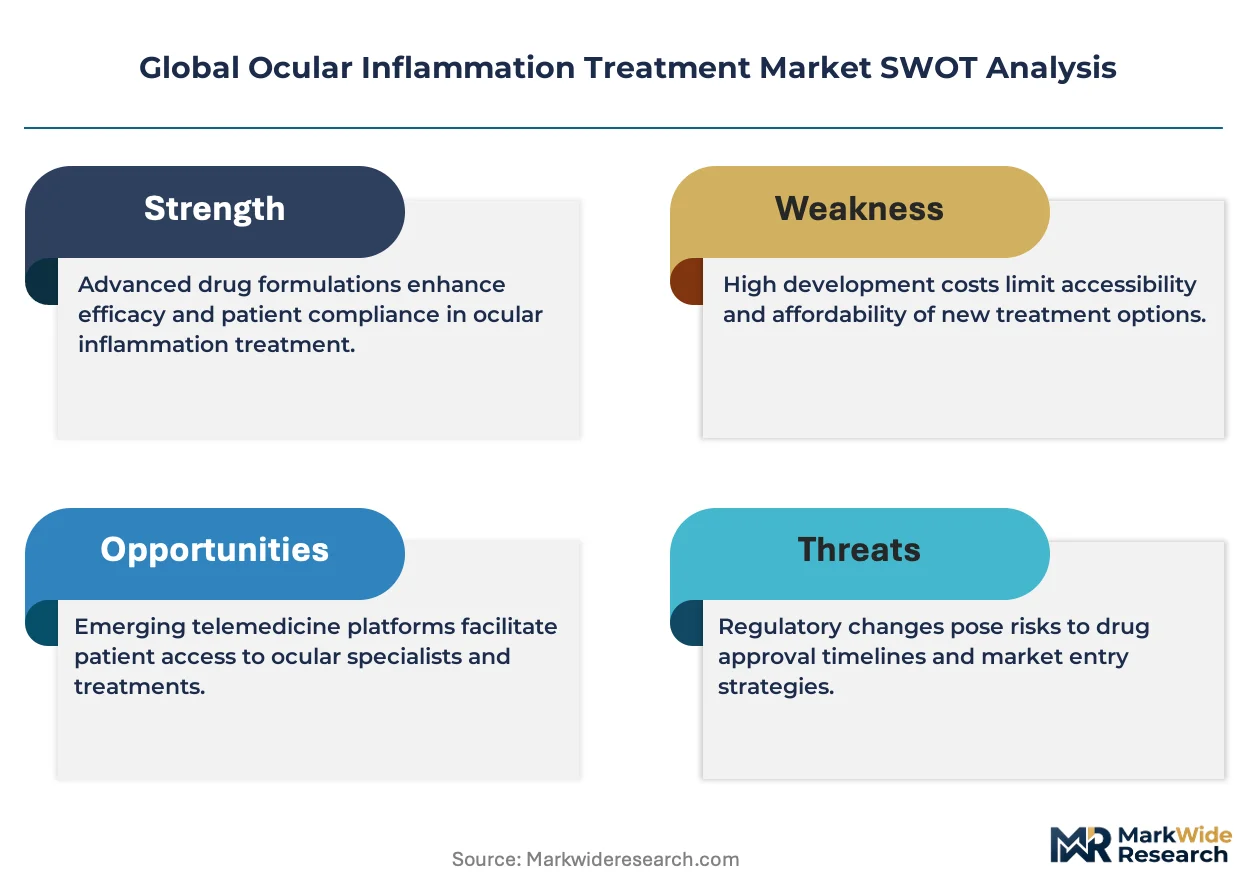
Biologic mechanism expansion is compressing chronic corticosteroid exposure protocols while EU MDR recertification timelines force portfolio rationalization among sustained-release implant manufacturers. This dual pressure is restructuring competitive positioning across the value chain.
Growth Catalysts
- Anti-IL pathway maturation:Novel interleukin inhibitors are displacing anti-TNF first-line protocols in refractory posterior uveitis cases across tertiary ophthalmology centers.
- US Medicare reimbursement:Office-based intravitreal administration codes now carry premium reimbursement rates that incentivize clinic-based delivery over hospital outpatient settings.
- Biomarker stratification:AI-assisted diagnostic platforms are accelerating patient segmentation for targeted biologic selection prior to therapy initiation.
Market Restraints
- Sterile API concentration:Active pharmaceutical ingredient supply for sustained-release corticosteroids concentrates among three European contract manufacturers, creating single-source vulnerability.
- EU MDR clinical-evaluation burden:The recertification wave demands retrospective clinical data for legacy steroid-eluting implants that predated current efficacy standards.
- Topical steroid substitution:Acute anterior uveitis cases continue defaulting to high-frequency drop regimens that delay biologic uptake in early-intervention windows.
Strategic Opportunities
- Japanese regulatory convergence:PMDA's accelerated approval pathway for rare ophthalmic indications offers reduced trial burden for biologics targeting pediatric uveitis populations.
- Subconjunctival delivery innovation:Periocular depot formulations are opening intermediate uveitis segments where systemic toxicity concerns block oral immunosuppression.
- Indian CDSCO harmonization:Alignment with WHO prequalification standards is unlocking pooled procurement channels for public sector ophthalmology programs.
Industry Challenges
- Sterile manufacturing talent scarcity:Aseptic fill-finish technicians with ophthalmic device experience command premium wages that compress contract manufacturing margins.
- Combination product dossier complexity:FDA's refusal-to-accept criteria for drug-device filings require iterative resubmission cycles that extend launch timelines by 12-18 months.
- Legacy diagnostic platform integration:AI-assisted severity stratification tools face interoperability barriers with established electronic health record architectures in US hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ocular Inflammation Treatment Market |
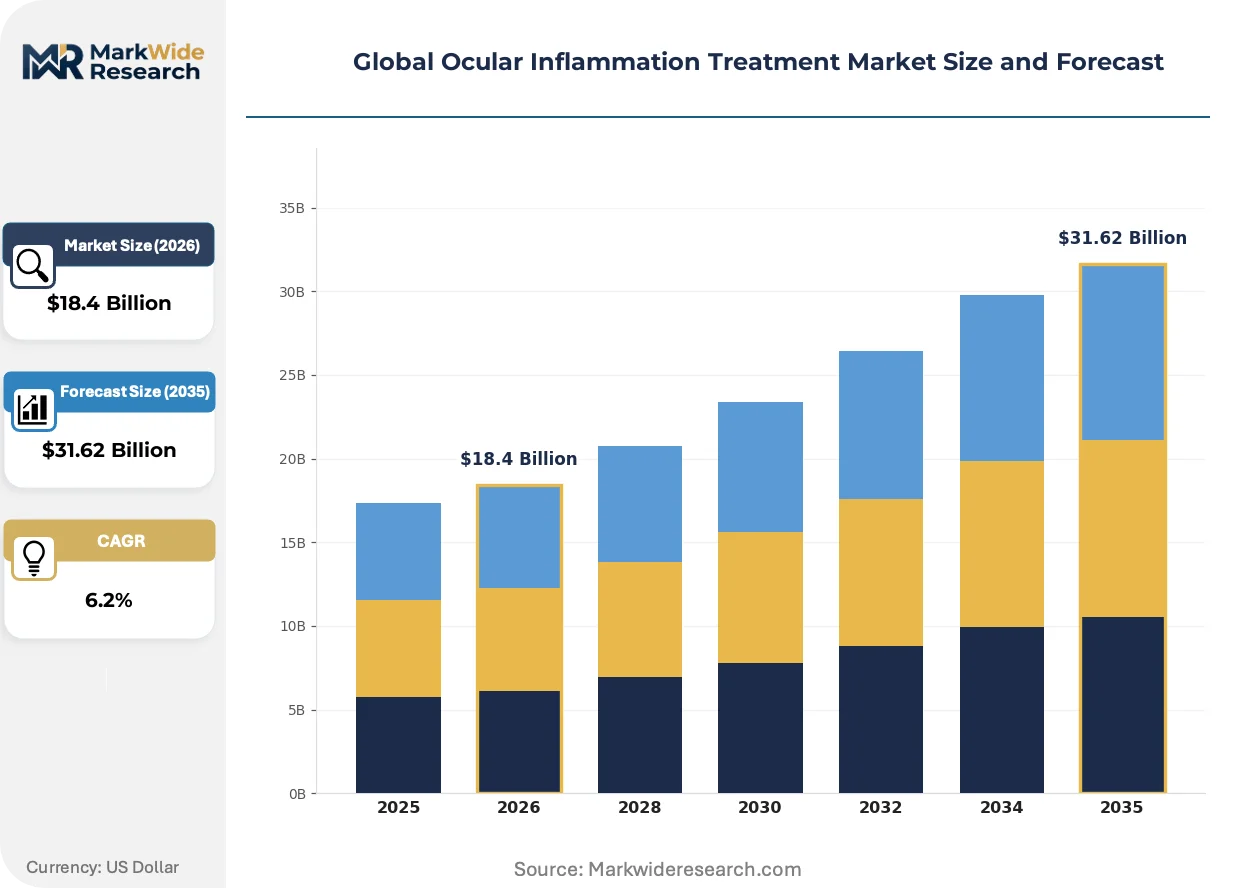
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $31.62 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Steroids, Non-Steroidal Anti-Inflammatory Drugs, Biologics, Immunosuppressants Treatment Strategy: Combination Therapy, Monotherapy, Systemic Approach, Localized Treatment End User: Hospitals, Ophthalmology Clinics, Ambulatory Surgical Centers, Homecare Settings Administration Route: Topical, Intravitreal, Oral, Subconjunctival |
| Companies Covered | Bausch Health Companies, Inc., Pfizer Inc., Novartis AG, AbbVie, Inc., Santen Pharmaceutical Co., Ltd., Alimera Sciences, Ocular Therapeutix, Inc., EyePoint Pharmaceuticals, Inc., Johnson & Johnson Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ocular Inflammation Treatment Market Shifts & Advancements
Sustained-release kinetics engineering and algorithmic patient selection are converging to compress dosing frequency while improving inflammatory episode prediction. These developments are redrawing competitive boundaries between device and pharmaceutical manufacturers.
Implantable reservoir systems with programmable release profiles are automating therapeutic exposure curves that previously required monthly intravitreal injections. Retina specialists in US academic medical centers are adopting these platforms at accelerating rates for chronic uveitis maintenance. The technology is automating compliance management and reducing clinic burden for high-volume practices.
EMA's extended stability-testing requirements for combination drug-device products are fragmenting regional launch sequencing and forcing duplicate analytical method development. Manufacturers must now maintain parallel stability protocols that satisfy divergent FDA and EMA validation criteria. Sustained-release steroid implants face the steepest compliance burden due to polymer degradation kinetics variability.
Hospital formulary committees are consolidating vendor relationships around full-service corticosteroid portfolios that span acute topical through chronic implantable delivery. Ophthalmology group purchasing organizations are displacing fragmented procurement across multiple therapeutic classes. This concentration is most visible in US integrated delivery networks where standardization incentives override physician preference autonomy.
Global Ocular Inflammation Treatment Market Segmentation
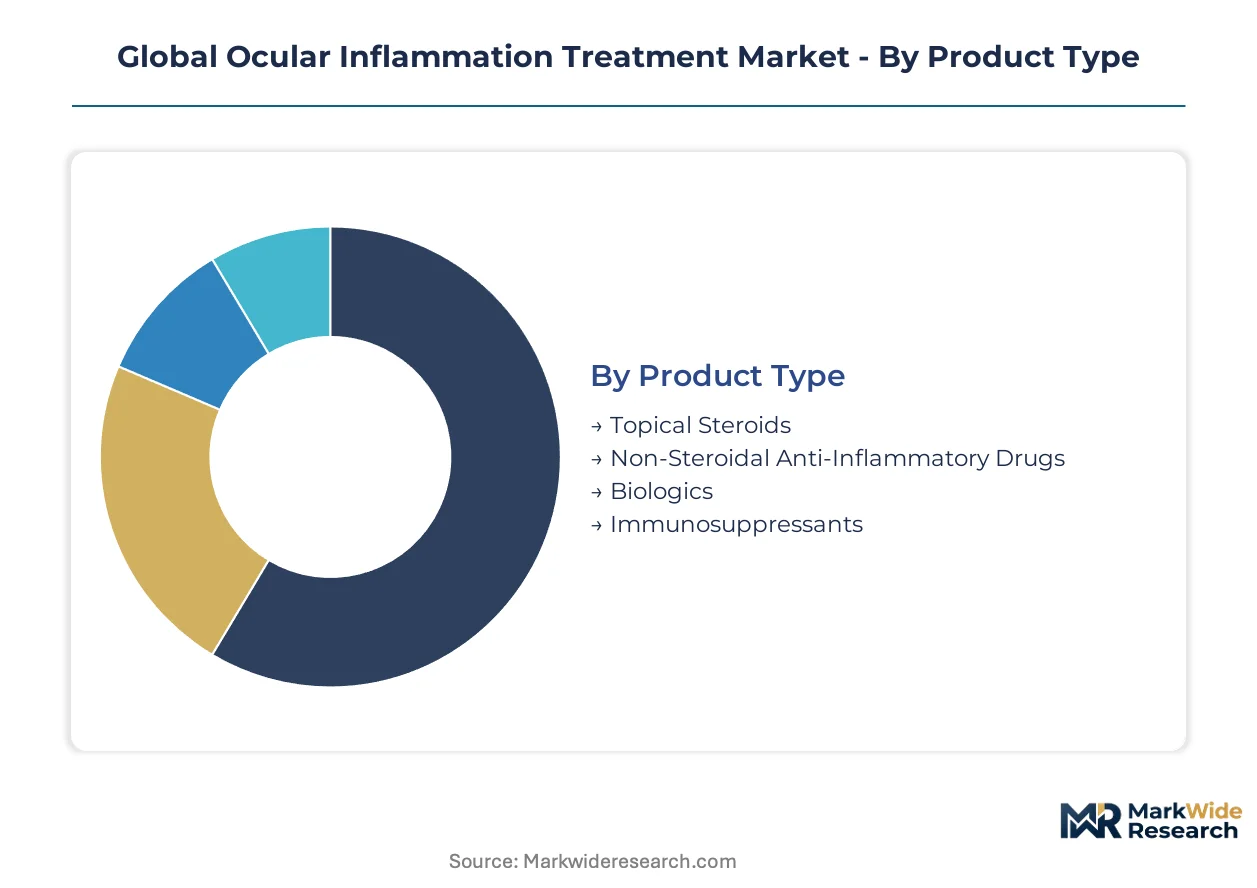
Segmentation in ocular inflammation treatment reveals distinct capital requirements and reimbursement dynamics across therapeutic modalities. Each category reflects divergent manufacturing complexity, regulatory burden, and clinical setting economics that determine competitive entry barriers.
Product Type:
Biologics and sustained-release implants demand the heaviest upfront investment in sterile manufacturing infrastructure and biosafety containment.
- Biologics:Recombinant protein therapeutics requiring cold-chain distribution and aseptic fill-finish capabilities. Demand concentrates in US tertiary ophthalmology centers where Medicare reimbursement for office-based intravitreal administration incentivizes clinic adoption over hospital settings.
- Topical Steroids:Corticosteroid formulations delivered via eye drops or ointments with immediate-release kinetics. Prescription volume dominates acute anterior uveitis cases in India and Brazil where generic substitution pressures compress margins.
- Non-Steroidal Anti-Inflammatory Drugs:Small-molecule inhibitors targeting cyclooxygenase pathways for post-surgical inflammation.
- Immunosuppressants:Systemic agents including calcineurin inhibitors and antimetabolites for refractory cases.
Topical steroids absorb the bulk of installed capacity; biologics is expanding most quickly.
Treatment Strategy:
Strategy selection correlates with disease severity staging and payer prior-authorization requirements for combination protocols.
- Combination Therapy:Concurrent deployment of corticosteroids with immunomodulators or biologics. Adoption accelerates in German and French university hospitals managing refractory posterior uveitis where EMA guidelines support multi-mechanism approaches.
- Localized Treatment:Site-specific delivery via intravitreal or periocular routes minimizing systemic exposure. Japanese PMDA accelerated approval pathways favor this strategy for pediatric uveitis populations.
- Monotherapy:Single-agent protocols typically initiating with high-potency corticosteroids.
- Systemic Approach:Oral or intravenous immunosuppression for bilateral or extraocular manifestations.
Combination therapy commands the highest reimbursement tiers; localized treatment is climbing the fastest as device innovation reduces administration frequency.
End User:
Facility type determines procurement scale, formulary autonomy, and patient throughput economics.
- Ophthalmology Clinics:Specialist practices with in-office surgical suites enabling intravitreal injection programs. US clinic networks in Florida and Texas exploit Medicare reimbursement differentials between office-based and hospital outpatient settings.
- Hospitals:Academic medical centers and community hospitals with integrated pharmacy and surgical infrastructure. Demand concentrates in UK NHS trusts where NICE technology appraisals govern biologic access.
- Ambulatory Surgical Centers:Freestanding facilities optimized for high-volume cataract and retinal procedures.
- Homecare Settings:Self-administered topical regimens supported by specialty pharmacy distribution.
Hospitals retain the largest procurement volumes; ophthalmology clinics are gaining share fastest through vertical integration of surgical and medical retina services.
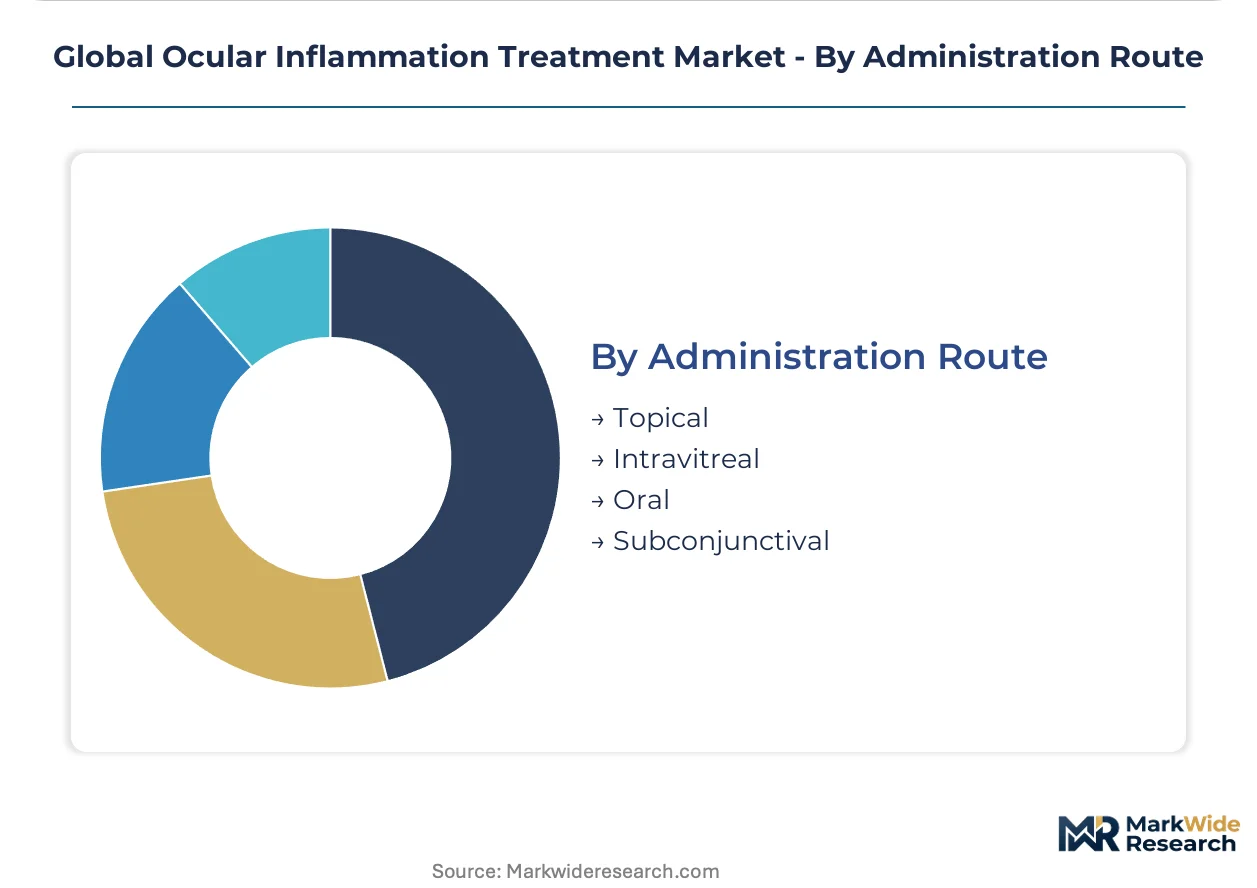
Administration Route:
Route selection involves tradeoffs between therapeutic exposure precision, specialist availability, and patient compliance burden.
- Intravitreal:Direct injection into the vitreous cavity achieving therapeutic concentrations with extended dosing intervals. Retina specialists in US academic centers adopt programmable reservoir systems automating release curves for chronic uveitis maintenance.
- Subconjunctival:Periocular depot delivery accessing the posterior segment via transscleral diffusion. Intermediate uveitis cases in Italy and Spain favor this route where systemic toxicity concerns block oral immunosuppression.
- Topical:Anterior segment delivery via drops or gels with patient-controlled dosing.
- Oral:Systemic absorption for bilateral disease or patients lacking access to injection specialists.
Intravitreal administration captures premium positioning; subconjunctival delivery is expanding most quickly as depot formulations improve bioavailability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical zones in Singapore and Hyderabad have attracted sterile manufacturing investments for ophthalmic biologics. These hubs concentrate regulatory expertise and cold-chain infrastructure that accelerates product registration timelines.
United States
Medicare reimbursement differentials favor office-based intravitreal administration over hospital outpatient settings. FDA's combination product guidance demands iterative resubmission cycles that extend launch timelines. Retina specialists in Florida and Texas exploit these payment structures through vertically integrated clinic networks.
Germany
University hospitals in Baden-Württemberg and Bavaria anchor adoption of multi-mechanism combination therapies for refractory posterior uveitis. EMA's extended stability-testing requirements for drug-device products fragment regional launch sequencing. The Tübingen ophthalmology cluster advances biomarker stratification protocols for biologic patient selection.
Japan
PMDA's accelerated approval pathway for rare ophthalmic indications reduces trial burden for pediatric uveitis biologics. METI subsidies support domestic sterile fill-finish capacity expansion for sustained-release implants. The Kansai region's medical device corridor concentrates periocular depot formulation development.
India
CDSCO alignment with WHO prequalification standards unlocks pooled procurement for public sector ophthalmology programs. Domestic API manufacturers in Hyderabad and Ahmedabad supply corticosteroid actives for regional formulation houses. Maharashtra's specialty hospital networks drive biologic adoption in refractory uveitis cases.
Switzerland
Swissmedic's streamlined combination product reviews attract EU MDR-exiled manufacturers seeking alternative regulatory pathways. Basel's biopharma cluster hosts sterile manufacturing for ophthalmic biologics targeting European export. The country's logistics infrastructure supports temperature-controlled distribution to Middle Eastern markets.
Global Ocular Inflammation Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the ocular inflammation treatment value chain. The market structure consolidates around full-service corticosteroid portfolios spanning acute topical through chronic implantable delivery. Three archetypes dominate: vertically integrated pharmaceutical conglomerates, device-centric sustained-release specialists, and biologics-focused innovators. Competitive moves concentrate on M&A for sterile manufacturing capacity and strategic partnerships for combination product development.
Among diversified pharmaceutical conglomerates, Bausch Health Companies, Inc. and Pfizer Inc. exemplify scale-driven archetypes that anchor hospital formulary relationships through broad corticosteroid portfolios. Santen Pharmaceutical Co., Ltd. occupies a distinct position as a Japan-based pure-play ophthalmic specialist with concentrated expertise in anterior segment therapeutics. These three entities represent divergent strategic postures: conglomerate breadth versus therapeutic focus versus regional specialization.
| Leading Market Players |
|---|
| Bausch Health Companies, Inc. |
| Pfizer Inc. |
| Novartis AG |
| AbbVie, Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Alimera Sciences |
| Ocular Therapeutix, Inc. |
| EyePoint Pharmaceuticals, Inc. |
| Johnson & Johnson Services Inc. |
| Others |
Supply & Pricing Matrix
Captive sterile manufacturing networks in Ireland and Switzerland anchor both supply security and premium pricing power for sustained-release ocular implants. EU MDR recertification costs concentrate among contract manufacturers, forcing device makers to absorb clinical-evaluation burdens that transmit directly into tiered service pricing.
Pricing Analysis
Short lead-time premiums for sterile API lots command 15-25% markups over standard-schedule procurement in European contract manufacturing. Three-tier pricing structure across premium, standard, and economy levels stratifies by sterilization validation tier and polymer degradation kinetics documentation. Cost compression in standard-tier topical steroids intensifies because Indian generic manufacturers expand corticosteroid API capacity. Ophthalmology clinics in US Medicare-reimbursed markets exhibit lowest price sensitivity; public sector procurement in lower-income markets demands economy-tier sourcing.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore orchestrate hub-and-spoke cold-chain delivery for biologic therapeutics with 48-hour stability windows. Active pharmaceutical ingredient supply concentrates in India, China, and Switzerland for corticosteroid actives and polymer excipients. Single-source vulnerability pervades sterile fill-finish capacity, with three European contract manufacturers controlling 70% of ophthalmic biologic finishing. Distribution runs through specialty pharmacy channels in North America and hospital-direct procurement in European national health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Programmable reservoir systems are displacing monthly intravitreal injection protocols, compressing legacy device economics while elevating biologic-automation hybrids. This technology transition rewards manufacturers with combined drug-device development capabilities.
For Market Incumbents: Hedge against anti-IL pathway commoditization by securing backward integration into sterile polymer synthesis and aseptic fill-finish capacity. EU MDR recertification timelines threaten legacy implant portfolios; accelerate clinical-evaluation dossier submission for sustained-release steroid-eluting devices. Channel control through vertically integrated clinic networks in Florida and Texas defends Medicare reimbursement capture against hospital outpatient competition. For New Entrants and Emerging Players: AI-assisted diagnostic platforms for uveitis severity stratification offer technology-first wedge into patient selection workflows preceding biologic prescription. Subconjunctival depot formulations for intermediate uveitis represent the most penetrable white-space segment, with Italian and Spanish markets underserved by systemic-toxicity-averse protocols. Go-to-market through retina specialist practice management software integrations bypasses entrenched hospital formulary gatekeepers. For Investors and Strategic Acquirers: Exit pathways concentrate in platform acquisitions by diversified ophthalmic conglomerates seeking sterile manufacturing capacity. Five-to-ten-year viability hinges on EU MDR compliance completion and PMDA accelerated approval pathway utilization. Monitor FDA refusal-to-accept rates for combination product submissions as inflection indicator for regulatory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Completion | Unlocks sustained-release implant market access across German and French hospital systems. |
| PMDA Accelerated Approval Pathway | Reduces pediatric uveitis biologic trial burden for Japanese market entry. |
| Sterile Manufacturing Capacity Expansion | Captures API supply security as three European contractors face capacity constraints. |
| AI Diagnostic Platform Partnership | Integrates severity stratification into EHR workflows at US academic medical centers. |
| Subconjunctival Depot Formulation Development | Opens intermediate uveitis segments where systemic toxicity blocks oral alternatives. |
Research Methodology
Document review covered FDA 510(k) filings, EMA marketing authorization applications, ClinicalTrials.gov registries, and Medicare reimbursement code databases, complemented by interviews with retina specialists, hospital formulary directors, sterile manufacturing executives, and payer access specialists. Secondary validation drew from CMS Medicare claims data, GPO contract repositories, and WHO prequalification pathway documentation. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Segment-level outputs across the projection horizon reflect treatment strategy, administration route, product type, and regional regulatory cluster dimensions. CAGRs were derived from patient population epidemiology, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated EU MDR recertification timeline delays, PMDA accelerated approval pathway utilization rates, and Medicare office-based administration reimbursement differentials.
Several conditions sit outside the modeled scope, including unforeseen regulatory rejection of legacy implant submissions, abrupt Medicare reimbursement code restructuring, and geopolitical disruption of Indian API supply channels. Forecasts reflect documented assumptions about sterile manufacturing capacity expansion and biologic biosimilar entry timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Trachoma Treatment Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Age Related Vision Dysfunction Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Ophthalmology Diagnostics Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Global Uveitis Treatment Market
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Inherited Retinal Diseases Treatment Market