
 Skin Care Emulsion Market | 2026-2036
Skin Care Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Care Emulsion Market Insights
Professional dermatology channels is repositioning skin care emulsion demand away from mass retail toward clinic-dispensed and medical-aesthetic formats. L'Oréal S.A. leverages its pharmacy network across France and Brazil to anchor clinical-grade emulsion distribution. Beiersdorf AG sustains R&D intensity in barrier-repair formulations through its Hamburg-based dermatology lab. Shiseido Company, Limited competes in prestige emulsion segments across Tokyo, Shanghai, and New York flagship channels.
Skin care emulsion denotes a biphasic liquid preparation with 10-35% internal oil phase dispersed in an aqueous continuous phase, stabilized by surfactant systems and functional actives, designed to deliver hydration, barrier support, or photoprotection with lighter skin-feel than creams. Moisturizers dominate volume due to daily-use frequency and broad demographic reach, while serums command premium positioning through concentrated active payloads. Hyaluronic acid formulations are gaining fastest in professional and premium direct-to-consumer channels, whereas glycerin-based economy emulsions remain mature with compressed margin pools.
The FDA oversees cosmetic safety under MoCRA-mandated adverse event reporting and facility registration, while the EU Cosmetics Regulation enforces banned substance lists and nanomaterial labeling across member states. REACH compliance for emulsion raw materials shapes supplier qualification timelines and reformulation costs for brands selling into Europe. Stakeholders must monitor evolving state-level fragrance disclosure laws in California and New York, as these precede broader federal rulemaking and directly impact formulation archives and packaging redesign cycles.
Market Dynamics
Professional dermatology channels are repositioning skin care emulsion demand away from mass retail toward clinic-dispensed and medical-aesthetic formats, tightening formulation standards and collapsing traditional distribution hierarchies.
Growth Catalysts
- MoCRA facility registration:The FDA's Modernization of Cosmetics Regulation Act mandates adverse event reporting and facility registration, professionalizing supply chains and favoring established manufacturers with compliance infrastructure.
- K-beauty export infrastructure:South Korea's rapid formulation-to-shelf cycles compress product development timelines and enable faster global distribution of novel emulsion formats.
- Barrier-repair R&D intensity:Hamburg-based dermatology laboratories advance lipid-replenishing emulsion science, expanding clinical indications beyond cosmetic hydration into therapeutic skin barrier support.
Market Restraints
- REACH raw material compliance:European Chemicals Agency registration timelines for emulsion ingredients extend supplier qualification periods and inflate reformulation costs for brands accessing EU markets.
- Fragrance disclosure mandates:California and New York state-level laws require expanded ingredient archiving and packaging redesign cycles, creating regulatory friction for multi-market portfolios.
- Glycerin-based economy compression:Mature mass-market segments face margin pool erosion as commodity surfactant systems encounter price competition from private-label alternatives.
Strategic Opportunities
- Hyaluronic acid premium channels:Concentrated active payloads command pricing power in professional dermatology clinics and direct-to-consumer prestige formats.
- EU nanomaterial labeling:The EU Cosmetics Regulation's nanomaterial disclosure requirements create first-mover advantages for brands with transparent supply chain documentation.
- Pharmacy network anchoring:Clinical-grade distribution through France and Brazil pharmacy channels enables medical-aesthetic positioning distinct from mass retail competition.
Industry Challenges
- Formulation archive migration:State-level fragrance disclosure laws in California and New York force systematic reconstruction of historical product documentation and packaging specifications.
- Surfactant system stabilization:Maintaining biphasic emulsion integrity across temperature variants demands specialized technical expertise increasingly concentrated among mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Care Emulsion Market |
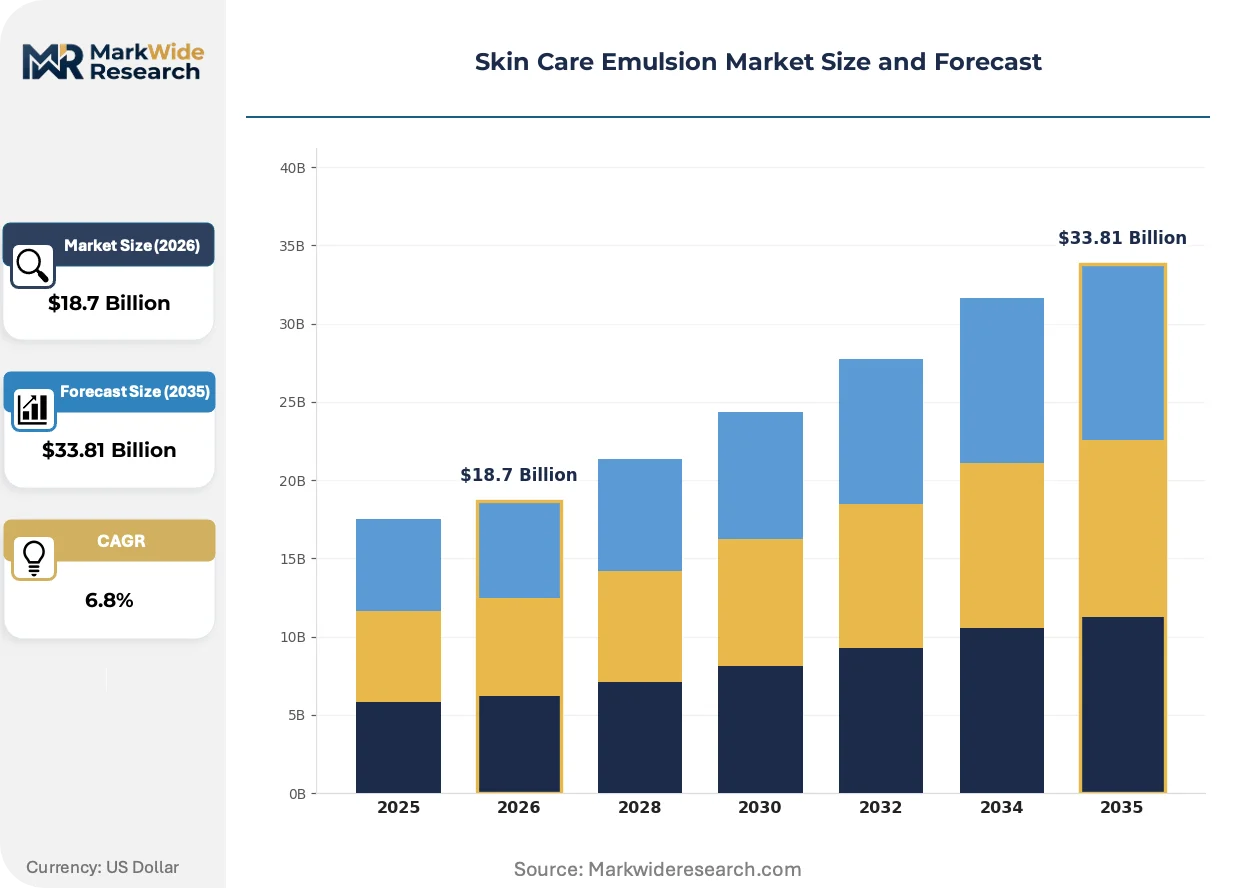
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Sunscreens, Serums, Lotions Ingredient Type: Natural Extracts, Hyaluronic Acid, Peptides, Glycerin End User: Women, Men, Teenagers, Professionals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | L'Oréal S.A., The Estée Lauder Companies Inc., Beiersdorf AG, Shiseido Company, Limited, Procter & Gamble, Unilever PLC, Johnson & Johnson, Kao Corporation, Amorepacific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Care Emulsion Market Trends and Innovations
Active ingredient delivery science and regulatory transparency mandates are compressing product development cycles while elevating clinical credibility requirements across all price tiers.
Encapsulated retinol and peptide complex delivery systems are electrifying professional emulsion formulations by enabling controlled-release kinetics previously unavailable in cosmetic-grade products. Prestige dermatology clinics in Seoul and New York adopt these technologies within six-month innovation cycles. The structural consequence is collapsing differentiation timelines between pharmaceutical and cosmetic skincare boundaries.
REACH compliance for emulsion raw materials shapes supplier qualification timelines and reformulation costs for brands selling into Europe. The European Chemicals Agency's substance evaluation protocols force ingredient substitution decisions that cascade through entire product portfolios. Mid-market manufacturers face the steepest adaptation burden as they lack dedicated regulatory affairs infrastructure.
Clinic-dispensed formats displace traditional retail purchasing for consumers seeking diagnostic-validated skincare regimens. Medical-aesthetic channels in Tokyo, Shanghai, and São Paulo bundle emulsion products with professional consultation services. This behavioral shift concentrates volume among pharmacy-affiliated dermatology networks and fragments traditional department store prestige positioning.
Skin Care Emulsion Market Segmentation
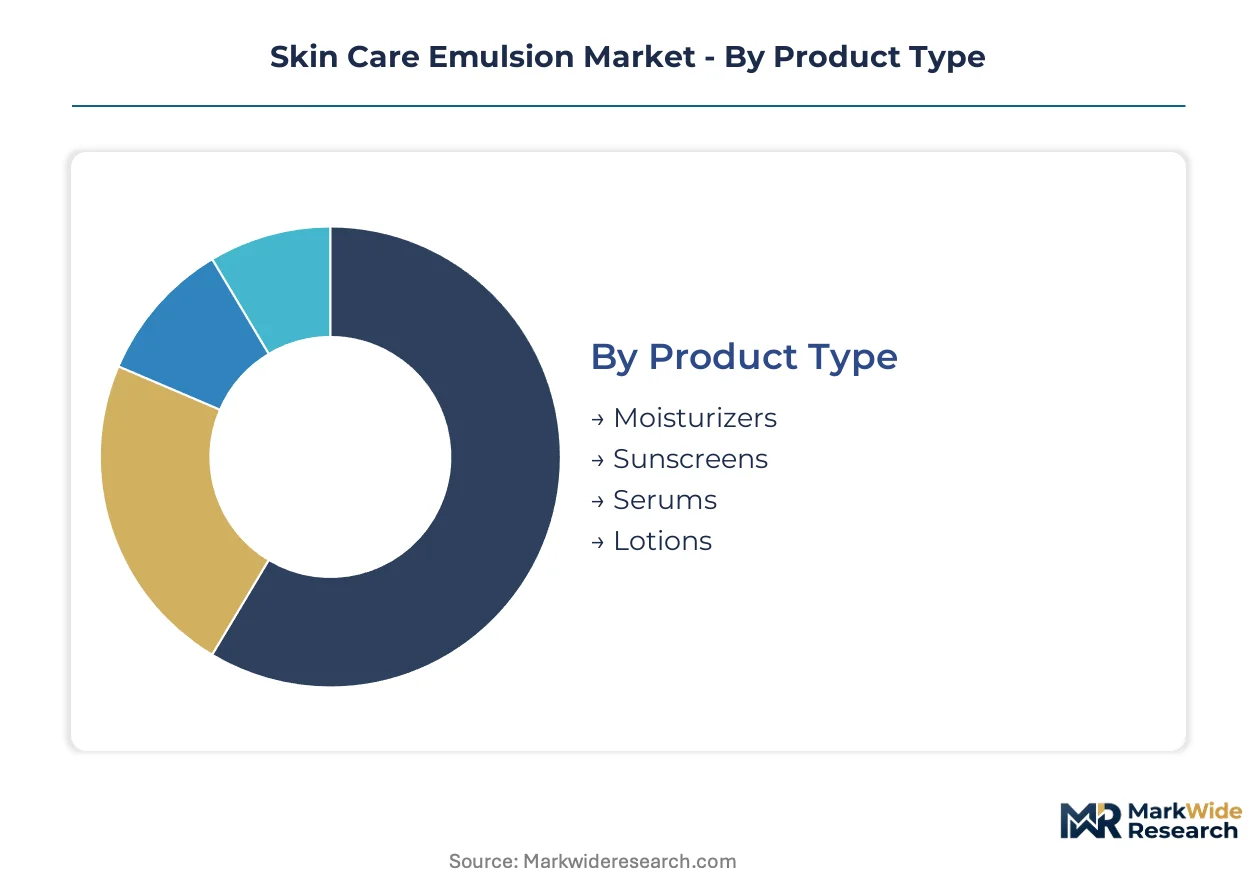
Emulsion segmentation reveals how formulation chemistry, user demographics, and channel access create distinct margin pools. Each dimension carries implications for R&D allocation, regulatory compliance burden, and pricing architecture.
Product Type:
Replacement cycles vary dramatically across emulsion formats, with daily-use products demanding continuous replenishment while treatment-grade formats command discretionary upgrade timing.
- Moisturizers:Biphasic aqueous-dominant formulations with 10-35% oil phase serve as foundational daily hydration. Mass-market penetration concentrates in South Korea and the United States, where K-beauty export infrastructure compresses formulation-to-shelf timelines for novel textures.
- Serums:Concentrated active-payload emulsions deliver peptides and antioxidants through stabilized micellar systems. Professional dermatology clinics in Tokyo and New York anchor demand, with diagnostic-validated regimens displacing traditional retail purchasing.
- Sunscreens:Photoprotective emulsions combine organic and mineral filters within biphasic matrices.
- Lotions:Lower-viscosity variants target body care applications with simplified surfactant stabilization.
Moisturizers sit at the top of the volume ranking, with serums climbing the fastest.
Ingredient Type:
Cost tier stratification separates commodity surfactant systems from advanced bioactive delivery platforms, reshaping supplier qualification requirements.
- Hyaluronic Acid:Cross-linked and multi-molecular weight variants enable tunable hydration kinetics within oil-in-water matrices. Prestige direct-to-consumer channels and professional clinics in Seoul and Shanghai drive specification intensity.
- Peptides:Signal and carrier peptide complexes require encapsulation technology for stability in emulsion environments. Hamburg-based dermatology laboratories advance controlled-release kinetics, expanding clinical indications into therapeutic barrier repair.
- Natural Extracts:Botanical actives from centella, green tea, and fermented substrates feature prominently in K-beauty formulations.
- Glycerin:Humectant-based economy emulsions face compressed margin pools as private-label alternatives proliferate in mass retail.
Glycerin formulations dominate absolute volume, while hyaluronic acid variants gain share fastest.
End User:
Application context and skin concern severity create distinct customer archetypes with divergent sensitivity to clinical credibility versus convenience.
- Women:Core demographic spanning preventive aging, barrier repair, and cosmetic hydration needs. Pharmacy network anchoring in France and Brazil enables medical-aesthetic positioning distinct from mass retail competition.
- Men:Simplified regimens and texture preferences drive demand for lightweight, fast-absorbing emulsion formats.
- Teenagers:Acne-prone skin indications favor non-comedogenic emulsion bases with oil-phase minimization.
- Professionals:Clinic-dispensed formats serve consumers seeking diagnostic-validated skincare bundled with consultation services.
Women represent the largest addressable base, with professionals expanding most quickly.
Distribution Channel:
Channel maturity determines margin capture, with digital-native formats compressing traditional distribution hierarchies while pharmacy networks tighten formulation standards.
- Pharmacies:Clinical-grade distribution through France and Brazil anchors medical-aesthetic positioning. L'Oréal S.A. leverages this network to separate dermatologist-recommended formats from mass retail alternatives.
- Online Retail:Direct-to-consumer platforms enable rapid global distribution of novel emulsion formats. South Korea's formulation-to-shelf infrastructure supports six-month innovation cycles for prestige launches.
- Specialty Stores:Flagship channels in Tokyo, Shanghai, and New York concentrate prestige positioning through experiential retail.
- Supermarkets:Mass-market glycerin-based economy emulsions face margin erosion from private-label substitution.
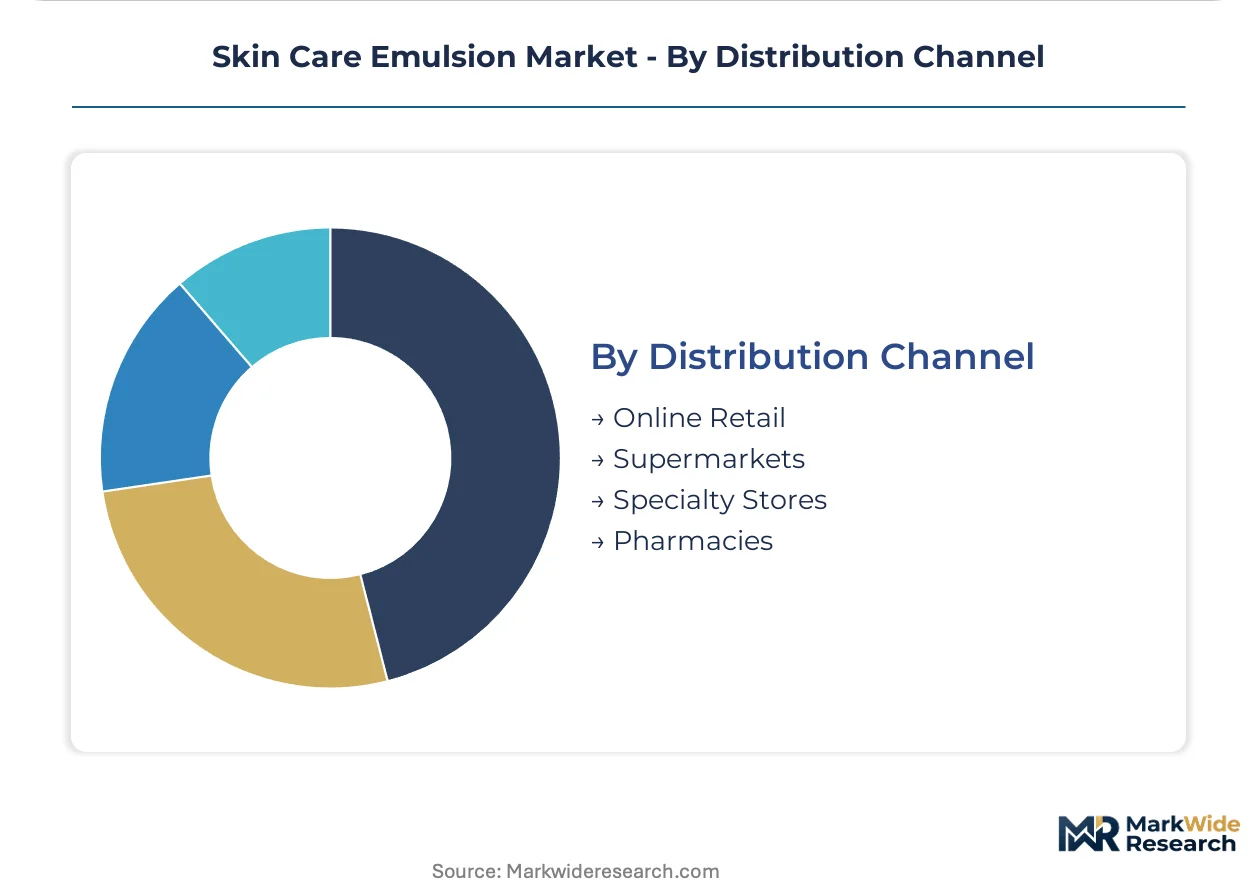
Pharmacies lead in value per transaction, with online retail scaling fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting emulsion manufacturing toward jurisdictions with streamlined cosmetic registration pathways, as REACH compliance costs in Europe and MoCRA facility mandates in the United States compress margins for mid-tier brands lacking dedicated compliance infrastructure.
South Korea
K-beauty export infrastructure enables six-month formulation-to-shelf cycles that outpace Western competitors. MFDS cosmetic safety standards enforce rigorous documentation while permitting rapid market entry for clinically substantiated claims. Seoul Capital Area clusters contract manufacturers serving global prestige brands with encapsulated active delivery systems.
United States
Professional dermatology channels displace mass retail through clinic-dispensed formats bundled with diagnostic consultation. FDA MoCRA mandates adverse event reporting and facility registration, professionalizing supply chains and favoring established manufacturers with compliance infrastructure. Greater Boston anchors medical-aesthetic innovation hubs developing therapeutic barrier-repair formulations.
France
Pharmacy network distribution anchors medical-aesthetic positioning distinct from mass retail competition. ANSM enforces strict ingredient disclosure requirements that cascade through packaging redesign cycles. Paris and Lyon concentrate R&D facilities advancing lipid-replenishing emulsion science for clinical-grade applications.
Japan
Prestige flagship channels in Tokyo concentrate experiential retail positioning for high-concentration active emulsions. METI standards govern quasi-drug classifications that blur pharmaceutical and cosmetic boundaries. Osaka-Kansai region hosts dermatology laboratories developing controlled-release peptide complexes for professional clinic adoption.
Brazil
Expanding private-label portfolios in dermatology clinics tighten formulation standards and compress traditional distribution hierarchies. ANVISA registration timelines for novel cosmetic ingredients extend supplier qualification periods. São Paulo anchors pharmacy-affiliated dermatology networks bundling emulsion products with professional consultation services.
Skin Care Emulsion Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with prestige dermatology clinics consolidating procurement around clinic-dispensed formats while mass retail fragments among private-label substitutes. The vendor base concentrates among three strategic archetypes: multinational conglomerates with pharmacy network anchoring, K-beauty specialists with rapid innovation cycles, and European dermatology laboratories with barrier-repair R&D intensity. Dominant competitive moves include geographic expansion into medical-aesthetic channels and portfolio diversification toward encapsulated active delivery systems.
Within the multinational conglomerate tier, L'Oréal S.A. and Beiersdorf AG occupy positions defined by pharmacy network leverage and dermatology laboratory infrastructure respectively. Shiseido Company, Limited exemplifies the prestige flagship archetype through experiential retail concentration in Tokyo, Shanghai, and New York. These three entities represent distinct strategic postures: French pharmacy anchoring, German R&D intensity, and Japanese flagship channel dominance.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| Beiersdorf AG |
| Shiseido Company, Limited |
| Procter & Gamble |
| Unilever PLC |
| Johnson & Johnson |
| Kao Corporation |
| Amorepacific Corporation |
| Others |
Pricing and Supply Chain Analysis
Surfactant system costs cascade from German and Japanese specialty chemical producers through three distinct pricing tiers, with hyaluronic acid raw material premiums concentrating in prestige clinic-dispensed formats while glycerin-based economy emulsions absorb commodity margin compression.
Pricing Analysis
Distributor margins in pharmacy networks anchor premium positioning for clinical-grade emulsions, with certification tier and volume scale driving price differentiation across formulations. Three-tier pricing structure across premium, standard, and economy levels reflects active payload concentration and channel access. Cost compression in mass-market glycerin segments intensifies because private-label substitution erodes branded positioning. Teenage and economy-tier consumers exhibit highest price sensitivity, while professional dermatology clinic procurement shows lowest elasticity.
Supply Chain Analysis
Encapsulated active ingredient supply rests on South Korean, German, and Japanese specialty chemical infrastructure serving global prestige brands. Hyaluronic acid cross-linking technology, peptide encapsulation systems, and lipid-replenishing emulsion bases constitute critical input dependencies. Single-source vulnerability concentrates in advanced delivery platform manufacturing. Distribution runs through pharmacy-affiliated dermatology networks in France and Brazil alongside direct-to-consumer platforms originating from Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skin care emulsion demand has shifted toward diagnostic-validated clinic formats, making premium specification adherence the defining competitive filter across all price tiers.
For Market Incumbents: Cement pharmacy network control in France and Brazil through exclusive formulation partnerships, insulating against emerging K-beauty direct-to-consumer entrants. Deepen backward integration into encapsulated active production to capture margin pools escaping to Japanese and German specialty chemical suppliers. Prioritize MoCRA compliance infrastructure as a barrier against mid-tier competitors lacking adverse event reporting capabilities.
For New Entrants and Emerging Players: Male-specific lightweight emulsion formats represent an underserved buyer archetype with minimal incumbent specialization beyond texture modifications. Professional consultation-bundled subscription models in São Paulo and Mexico City offer penetrable white-space targeting. Pursue white-label manufacturing partnerships with Seoul Capital Area contract manufacturers to compress formulation-to-shelf timelines.
For Investors and Strategic Acquirers: Roll-up economics work for regional dermatology clinic networks because fragmented pharmacy-affiliated distribution concentrates procurement decisions at the practice level. Five-to-ten year viability hinges on therapeutic barrier-repair claim substantiation capabilities. Monitor MFDS cosmetic safety standard enforcement intensity as the inflection signal for Korean manufacturing cost competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulated Active Delivery Platform Investment | Controlled-release kinetics from Hamburg and Osaka laboratories collapse pharmaceutical-cosmetic differentiation timelines. |
| Pharmacy Network Exclusive Distribution | L'Oréal's France-Brazil anchoring demonstrates medical-aesthetic positioning distinct from mass retail competition. |
| MoCRA Compliance Infrastructure Buildout | FDA facility registration mandates professionalize supply chains and favor established manufacturers with adverse event reporting systems. |
| K-Beauty Export Infrastructure Leverage | Seoul Capital Area six-month formulation-to-shelf cycles enable faster global distribution than Western competitors. |
| Barrier-Repair R&D Intensification | Hamburg-based dermatology laboratories expand clinical indications beyond cosmetic hydration into therapeutic skin support. |
Research Methodology
Bottom-up emulsion format modeling reconciled against top-down raw material supply tracking forms the analytical core of this study. Primary interviews with dermatology clinic procurement managers, pharmacy network category buyers, cosmetic R&D directors, contract manufacturing executives, and regulatory affairs specialists combined with secondary validation from MFDS cosmetic safety filings, ECHA REACH substance registrations, FDA MoCRA facility databases, and K-beauty export trade records. Top-down customs data and bottom-up channel shipment estimates triangulate volume figures.
Historical trendline analysis across emulsion chemistry evolution, channel migration patterns, and regulatory implementation timelines shaped projection assumptions. Segmentation dimensions modeled include product type, active ingredient payload tier, end-user demographic, and distribution channel access throughout the forecast period. CAGRs derive from fitted growth curves adjusted for regulatory compliance cost trajectories and K-beauty export infrastructure expansion rates.
Underlying measurement precision varies by segment; professional dermatology channel data carries tighter precision than fragmented direct-to-consumer estimates. Forecasts reflect assumptions about MoCRA enforcement intensity, REACH substance evaluation timelines, and K-beauty manufacturing capacity expansion. Regulatory implementation delays, raw material supply disruptions, or channel consolidation accelerations warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
United Kingdom Skincare Market
Skincare
Sensitive Skin Care Products Market
Skincare
Medicine Skin Care Market
Skincare
Skincare Serums Market
Skincare
Skin Antiseptic Market
Skincare
CBD Skin Care Market
Skincare
Personalized Skin Care Products Market
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Herbal Skincare Products Market
Skincare
Body Scrub Market
Skincare
Revitalizing Skin Wands Market
Skincare
Global Eczema Skin-Care Products Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Asia-Pacific Cosmeceutical Market
Skincare
Retinol Skincare Product Market