
 Global Oral Electrolyte Solutions Market | 2026-2036
Global Oral Electrolyte Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oral Electrolyte Solutions Market Foresight
Pediatric-grade formulation standards is bifurcating the competitive landscape into clinical and consumer channels. Abbott Laboratories leverages its hospital distribution network to sustain institutional contracts across North America. Sanofi competes through pharmacy-centric branding in European and African markets. Otsuka Pharmaceutical Factory dominates East Asian supply with manufacturing scale and JIS-compliant production lines.
Oral electrolyte solutions are water-soluble formulations containing sodium, potassium, chloride, and glucose in defined osmolarity ranges, manufactured through sterile blending and aseptic filling processes to restore fluid balance in dehydrated patients. The ready-to-use liquid segment anchors hospital procurement due to dosing precision and infection control requirements, while powder formats extend into home care through lower shipping weights and longer shelf stability. Glucose-based formulations occupy the largest share of pediatric applications, whereas amino acid-based variants are gaining traction in sports nutrition channels.
FDA medical food regulations, WHO oral rehydration therapy guidelines, and EMA borderline product classifications collectively determine whether formulations enter pharmacy, grocery, or clinical distribution pathways. India's CDSCO and FSSAI maintain parallel oversight of electrolyte products marketed as drugs versus foods, creating compliance complexity for multinational suppliers. Stakeholders must monitor evolving national pharmacopoeia monographs and sugar-tax legislation that could reclassify glucose-heavy formulations across key markets.
Market Dynamics
Pediatric-grade formulation standards are bifurcating distribution channels into clinical and consumer pathways, forcing manufacturers to maintain dual compliance portfolios under divergent WHO therapeutic guidelines and FDA medical food classifications.
Growth Catalysts
- Low-osmolarity WHO formulations:India's national health missions distribute these through public clinics, expanding institutional procurement volumes beyond private pharmacy channels.
- Dehydration management protocols:Emergency medicine departments in tertiary hospitals now stock ready-to-use liquids as first-line intervention for gastroenteritis cases.
- Sports nutrition amino acid variants:Fitness clubs and athletic programs are integrating these into recovery regimens, opening parallel demand outside medical indications.
Market Restraints
- Glucose input cost volatility:Corn-derived dextrose prices fluctuate with agricultural commodity cycles, compressing margins on high-volume pediatric formulations.
- East Asian manufacturing concentration:JIS-compliant production lines cluster in Japan and select Chinese provinces, creating single-source vulnerability for aseptic filling capacity.
- Substitution by intravenous therapy:Hospital protocols in developed markets default to IV fluids for moderate dehydration, limiting oral solution penetration in acute care settings.
Strategic Opportunities
- Sub-Saharan African clinic networks:Community health worker programs lack cold-chain infrastructure, creating demand for heat-stable powder sachets with extended shelf stability.
- EU sugar-tax legislation:Reformulation toward reduced-glucose or alternative-carbohydrate bases may preempt reclassification of existing products into taxed beverage categories.
- Telehealth prescription integration:Remote pediatric consultations are generating direct-to-home shipments of prescription-grade electrolytes, bypassing traditional pharmacy intermediaries.
Industry Challenges
- Aseptic filling technician scarcity:Sterile manufacturing facilities require certified operators for cleanroom environments, with training pipelines failing to match capacity expansion timelines.
- Dual CDSCO-FSSAI compliance:Products marketed across drug and food classifications in India demand parallel dossier submissions, extending registration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oral Electrolyte Solutions Market |
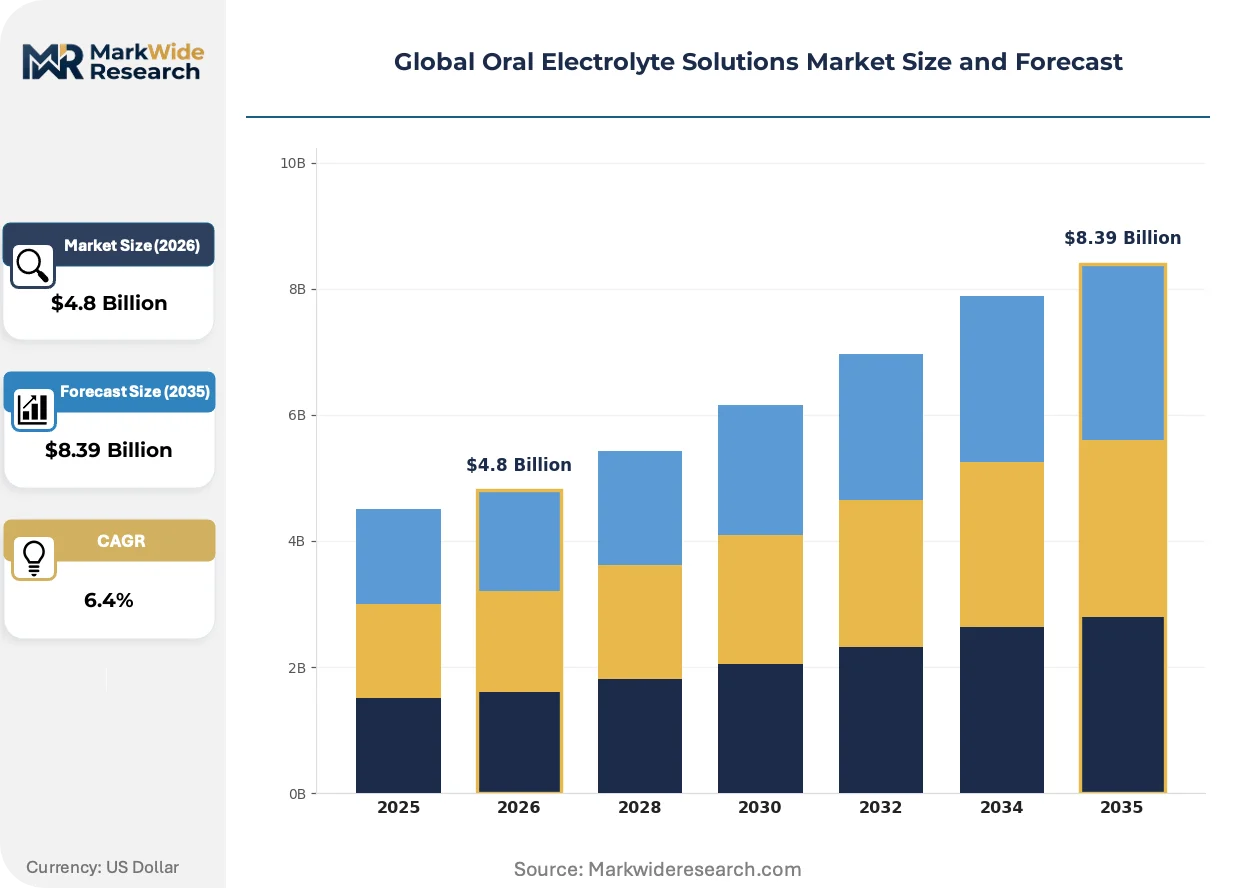
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Ready-to-Use Liquid, Concentrate, Effervescent Tablets Formulation: Glucose-Based, Amino Acid-Based, Mineral Complex, Herbal Extract Infused Application: Dehydration Management, Sports Nutrition, Pediatric Care, Elderly Hydration End User: Hospitals, Sports Facilities, Clinics, Home Care Providers |
| Companies Covered | Abbott Laboratories, Sanofi, Johnson & Johnson, Mead Johnson Nutrition, DripDrop Inc., Otsuka Pharmaceutical Factory, Nestlé Health Science, GlaxoSmithKline, Reckitt Benckiser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oral Electrolyte Solutions Market Shifts & Advancements
Formulation science and distribution logistics are converging to reshape how electrolyte products reach end-users, with stability engineering and regulatory navigation becoming core competitive capabilities rather than secondary operational concerns.
Ready-to-drink formats with ambient-temperature stability are displacing traditional cold-chain-dependent liquid products in institutional procurement. Hospital systems in Brazil and Mexico are adopting these for emergency stockpiles, eliminating refrigeration infrastructure requirements. This shift is displacing conventional supply arrangements that relied on regional dairy distributors for temperature-controlled last-mile delivery.
WHO oral rehydration therapy guideline revisions are tightening osmolarity specifications for pediatric indications. EMA borderline product classifications in parallel are forcing manufacturers to clarify whether formulations enter pharmacy or grocery channels before market entry. European suppliers are responding by submitting combined drug-food hybrid dossiers to preempt regulatory ambiguity.
Direct sourcing by hospital consortiums is consolidating procurement authority previously dispersed across individual pharmacy departments. Group purchasing organizations in the United States are negotiating multi-year supply agreements with manufacturers who demonstrate batch-level traceability. This concentration is most visible in pediatric hospital networks where formulary standardization reduces clinical variation in dehydration treatment protocols.
Global Oral Electrolyte Solutions Market Segmentation
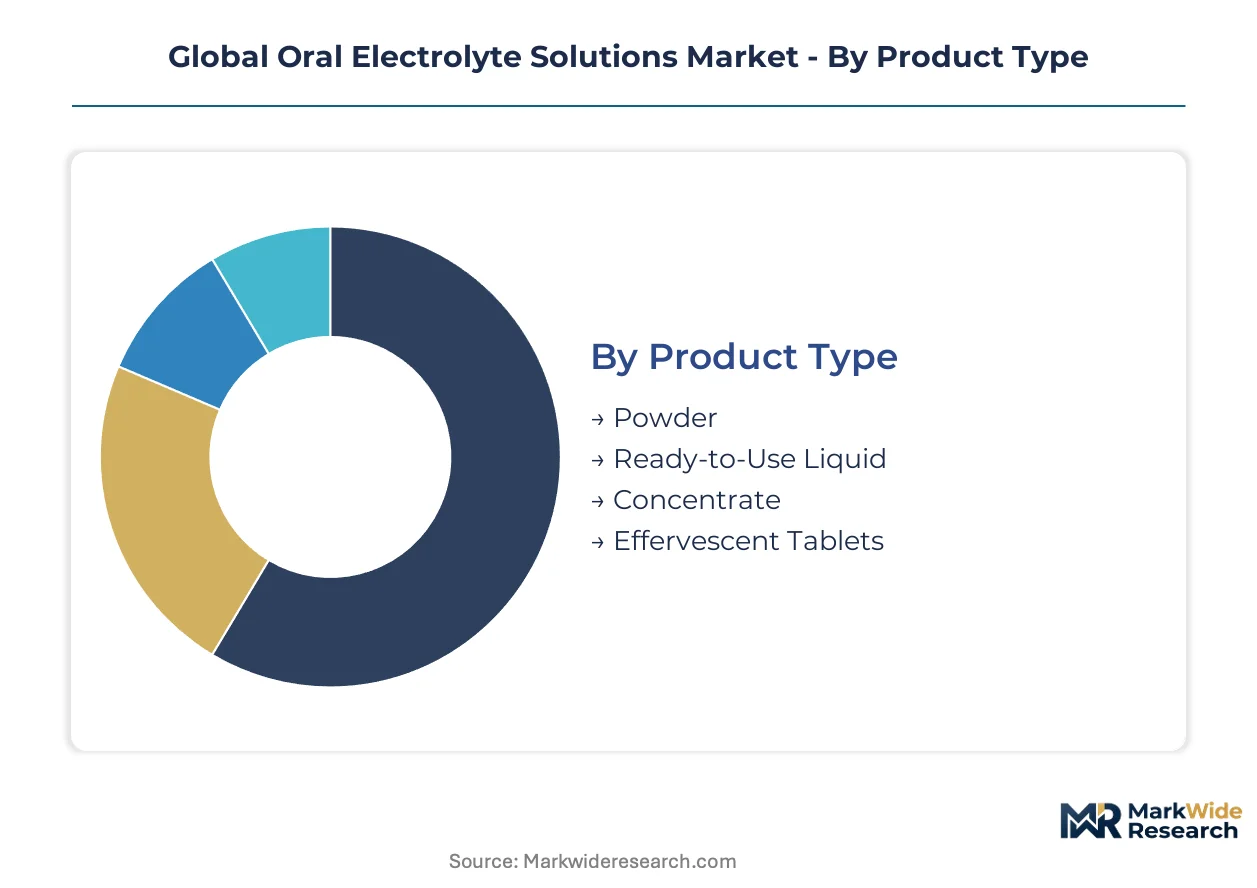
Segmentation in oral electrolyte solutions determines regulatory pathways, pricing architecture, and distribution infrastructure requirements. Manufacturers must align product specifications with end-use settings ranging from sterile hospital environments to uncontrolled home care conditions.
Product Type:
Substitution pressure from intravenous therapy and functional beverages varies sharply across delivery formats, with liquid formulations facing the strongest hospital-level displacement threat from IV alternatives.
- Ready-to-Use Liquid:Pre-mixed sterile solutions in sealed containers eliminate reconstitution errors and support infection control protocols in tertiary hospital emergency departments. Demand concentrates in Brazil and Mexico where hospital consortiums stockpile ambient-stable variants for disaster response, though cold-chain requirements in traditional distribution constrain rural penetration.
- Powder:Dried formulations packaged in single-serve sachets reduce shipping weight and extend shelf stability beyond liquid alternatives. India's national health missions distribute low-osmolarity powder sachets through public clinics lacking refrigeration infrastructure, while community health worker programs across Sub-Saharan Africa favor heat-stable formats for last-mile delivery.
- Concentrate:Dilution-required formulations offer dosing flexibility for institutional bulk preparation in large hospital systems.
- Effervescent Tablets:Rapid-dissolving solid formats target convenience-oriented consumers in pharmacy and grocery channels.
Ready-to-Use Liquid retains volume leadership; Powder holds the steepest expansion curve.
Formulation:
Cost tier stratification separates premium clinical-grade specifications from mass-market alternatives, with carbohydrate source selection driving both margin structure and regulatory classification risk.
- Glucose-Based:Corn-derived dextrose formulations dominate pediatric applications due to established osmolarity profiles in WHO oral rehydration therapy guidelines. Sugar-tax legislation in EU member states threatens reclassification into taxed beverage categories, pressuring manufacturers toward reduced-glucose reformulation.
- Amino Acid-Based:Protein-derived electrolyte blends support muscle recovery kinetics beyond basic hydration, gaining traction in sports nutrition channels across fitness clubs and athletic programs. Japanese suppliers leverage JIS-compliant production lines to manufacture clinical-grade amino acid variants for East Asian hospital networks.
- Mineral Complex:Multi-electrolyte blends without carbohydrate bases serve diabetic populations and ketogenic diet adherents.
- Herbal Extract Infused:Botanical-additive formulations occupy premium positioning in wellness-oriented retail channels.
Glucose-Based formulations command the largest installed base; Amino Acid-Based variants are climbing the fastest.
Application:
Customer type concentration shapes compliance requirements, with institutional purchasers demanding batch-level traceability that consumer channels rarely enforce.
- Pediatric Care:Low-osmolarity formulations meeting revised WHO specifications for childhood gastroenteritis treatment drive formulary standardization across pediatric hospital networks. Tightened osmolarity ranges bifurcate competitive positioning between clinical-grade suppliers and consumer-channel brands.
- Dehydration Management:Acute medical indications in emergency medicine departments favor ready-to-use liquids as first-line intervention, though hospital protocols in developed markets default to IV fluids for moderate cases.
- Sports Nutrition:Recovery-focused consumption patterns outside medical indications face lighter regulatory scrutiny but intense competition from functional beverages.
- Elderly Hydration:Age-specific formulations addressing diminished thirst response and polypharmacy interactions serve long-term care facilities.
Dehydration Management anchors procurement volumes; Sports Nutrition is expanding most quickly.
End User:
Supply concentration in East Asian aseptic filling capacity creates vulnerability for hospital and clinic channels dependent on sterile manufacturing, while home care bypasses these constraints through non-sterile powder formats.
- Hospitals:Group purchasing organizations in the United States negotiate multi-year supply agreements requiring demonstrated batch-level traceability and formulary standardization across pediatric networks. FDA medical food classifications determine whether products enter pharmacy or clinical distribution pathways.
- Clinics:India's CDSCO and FSSAI maintain parallel oversight of electrolyte products marketed as drugs versus foods, creating compliance complexity for multinational suppliers serving public clinic networks.
- Sports Facilities:Fitness clubs and athletic programs integrate amino acid-based variants into recovery regimens with lighter regulatory burden than medical channels.
- Home Care Providers:Telehealth prescription integration generates direct-to-home shipments bypassing traditional pharmacy intermediaries.
Hospitals dominate value capture; Home Care Providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aseptic filling capacity clusters in Japan and select Chinese provinces, creating single-source vulnerability for sterile oral electrolyte production while India's public health infrastructure drives volume consumption through national distribution programs.
United States
Hospital consortium purchasing concentrates procurement authority through group purchasing organizations negotiating multi-year supply agreements. FDA medical food classifications determine whether formulations enter pharmacy or clinical distribution pathways. Texas and California pediatric hospital networks drive formulary standardization for dehydration treatment protocols.
India
National health missions distribute low-osmolarity powder sachets through public clinics lacking refrigeration infrastructure. CDSCO and FSSAI maintain parallel oversight of products marketed as drugs versus foods, extending registration cycles for multinational suppliers. Maharashtra and Gujarat host distribution hubs serving clinic networks across western states.
Germany
EMA borderline product classifications force manufacturers to clarify pharmacy versus grocery channel entry before market launch. EU sugar-tax legislation pressures reformulation toward reduced-glucose bases to prevent beverage-category reclassification. Baden-Württemberg pharmaceutical clusters specialize in combined drug-food hybrid dossier preparation.
Brazil
Hospital systems adopt ambient-temperature-stable ready-to-use liquids for emergency stockpiles, eliminating refrigeration infrastructure requirements. ANVISA regulates electrolyte products crossing drug-food boundaries with classification protocols similar to European frameworks. São Paulo medical distributors consolidate procurement for southeastern hospital networks.
Japan
JIS-compliant production lines manufacture clinical-grade amino acid variants for East Asian hospital networks. METI industrial standards govern sterile manufacturing facility certification for cleanroom operations. Kanto region aseptic filling facilities supply institutional buyers across domestic and export markets.
Global Oral Electrolyte Solutions Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with hospital-grade formulation specialists commanding premium pricing while consumer-channel brands compete on volume scale. The market structure bifurcates between clinical procurement networks and retail pharmacy distribution, creating distinct compliance portfolios for each pathway. Three archetypes dominate: institutional formulary suppliers, consumer health brand owners, and regional manufacturing specialists with JIS or equivalent sterile production certification. Competitive moves center on multi-year hospital supply agreements and dual drug-food regulatory dossier submissions to preempt classification ambiguity.
Among diversified health science conglomerates, Abbott Laboratories and Johnson & Johnson occupy positions anchoring North American institutional procurement networks, while Otsuka Pharmaceutical Factory exemplifies the East Asian manufacturing specialist archetype with JIS-compliant sterile production capabilities. Sanofi represents the European pharmacy-centric brand owner model competing across African and European retail channels.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Sanofi |
| Johnson & Johnson |
| Mead Johnson Nutrition |
| DripDrop Inc. |
| Otsuka Pharmaceutical Factory |
| Nestlé Health Science |
| GlaxoSmithKline |
| Reckitt Benckiser |
| Others |
Supply & Pricing Matrix
Aseptic filling scale economies in Japan and select Chinese provinces concentrate sterile production capacity, creating price floors for hospital-grade formulations while compressing margins on commoditized powder sachets distributed through India's public clinic networks. This concentration bifurcates pricing power between institutional procurement channels demanding batch-level traceability and consumer segments competing on shipping-weight efficiency.
Pricing Analysis
FDA medical food classifications dictate the pricing tier structure across North American distribution, separating prescription-grade clinical formulations from grocery-channel wellness variants. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from glucose input cost volatility as corn-derived dextrose fluctuates with agricultural commodity cycles. Pediatric hospital networks exhibit lowest price sensitivity due to formulary standardization requirements, while home care powder segments face intense competition from functional beverages.
Supply Chain Analysis
Inventory lead times for sterile liquid formats stretch 8-12 weeks due to cleanroom certification requirements and aseptic filling technician scarcity. Supply concentrates in Japan, China, and India, with JIS-compliant production lines anchoring East Asian sterile capacity. Raw material dependencies center on pharmaceutical-grade glucose, amino acid isolates, and multi-layer barrier packaging films. Single-source vulnerability pervades aseptic filling capacity. Distribution runs through hospital group purchasing organizations in North America, pharmacy-centric networks in Europe, and government procurement systems in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oral electrolyte solutions market exhibits cyclical recovery characteristics as post-pandemic pediatric gastroenteritis caseloads normalize and India's national health missions expand institutional procurement volumes.
For Market Incumbents: Shield formulary positions in pediatric hospital networks through backward integration into glucose supply chains and accelerated WHO guideline compliance certification. IV fluid substitution in developed-market emergency departments threatens oral solution penetration. Capacity addition in Maharashtra distribution hubs secures Indian government contract renewals. For New Entrants and Emerging Players: Anchor in Sub-Saharan African clinic networks where community health worker programs lack cold-chain infrastructure and heat-stable powder sachets command premium positioning. Sports nutrition amino acid variants offer the most penetrable white-space as fitness clubs integrate recovery regimens outside medical indications. Direct-to-home telehealth prescription integration bypasses entrenched pharmacy intermediaries. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors East Asian manufacturing specialists with JIS-compliant sterile production capabilities and established East Asian hospital network relationships. Long-term viability hinges on regulatory dossier preparation capacity for dual drug-food classifications across CDSCO-FSSAI parallel oversight. Watch EU sugar-tax legislation progression as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Drug-Food Dossier Submission | Preempts CDSCO-FSSAI classification ambiguity for Indian market entry. |
| Heat-Stable Powder Reformulation | Extends shelf stability for Sub-Saharan African last-mile distribution. |
| Aseptic Filling Capacity Expansion | Addresses technician scarcity constraining sterile manufacturing output. |
| Telehealth Prescription Integration | Bypasses traditional pharmacy intermediaries for direct-to-home shipments. |
| Reduced-Glucose Base Development | Preempts EU sugar-tax reclassification into taxed beverage categories. |
Research Methodology
The analysis maps ready-to-use liquid, powder, concentrate, and effervescent tablet formats, each validated through hospital procurement managers, pharmacy category buyers, regulatory affairs specialists, and sterile manufacturing facility operators. Primary interviews with these stakeholders combined with secondary validation from FDA medical food filings, WHO oral rehydration therapy guideline revisions, CDSCO registration databases, and EMA borderline product classifications. Bottom-up volume triangulation against top-down value estimates ensures cross-verification across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, formulation chemistry, application indication, and end-user channel dimensions. CAGRs derive from segment-level growth trajectory aggregation. Forecast inputs incorporate India's national health mission expansion rates and WHO guideline revision implementation timelines.
Decision-makers should treat outputs as directional under stable regulatory classification assumptions and continued pediatric gastroenteritis caseload normalization; material deviation in glucose commodity cycles or IV fluid substitution rates would warrant model refresh. Forecasts reflect these base assumptions with acknowledged sensitivity to aseptic filling capacity constraints and dual drug-food compliance complexity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Sleep Supplement Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Global Beauty Supplements Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Nausea Relief Chews Market
Dietary Supplements
Vitamin D Deficiency Treatment Market
Dietary Supplements
Non-Hormonal Steroid Modulators Market
Dietary Supplements
Magnesium Glycinate Market