
 Artificial Iris Market | 2026-2036
Artificial Iris Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Iris Market Analytics
The ophthalmology clinic channel is rewriting how artificial iris products reach patients, with specialized surgical centers now controlling patient flow and procurement decisions. HumanOptics Holding AG leverages its European manufacturing base to sustain direct-to-clinic relationships across Germany and Austria. Kestrel Ophthalmics Inc. anchors its position through product specialization in trauma reconstruction devices. Ophtec BV differentiates via geographic dominance in the Benelux region and selective hospital partnerships.
An artificial iris is a biocompatible implant designed to replicate the structure and function of the human iris, typically manufactured from medical-grade silicone or polymethyl methacrylate with specific pupil diameter and fiber density parameters that modulate light entry to the retina. The primary commercial purpose spans both medical reconstruction after enucleation or trauma and cosmetic enhancement for congenital aniridia or iris defects. Iris prosthesis products lead the product type dimension due to established reimbursement codes and surgeon familiarity, while 3D printing technology within the technology segment represents the fastest-growing structural category as it enables patient-specific anatomical matching and reduces inventory carrying costs for manufacturers. Medical reconstruction dominates the application segment through sustained procedural demand, though cosmetic enhancement commands premium pricing tiers in private-pay markets.
The FDA's Class II medical device regulations in the United States, combined with the EU Medical Device Regulation (MDR) and CE marking requirements in Europe, collectively elevate compliance costs but simultaneously create barriers that favor established manufacturers with quality management systems. ISO 10993 biocompatibility testing standards further constrain material selection and supplier qualification processes across all commercial geographies. Stakeholders must monitor how evolving reimbursement policies for ocular prosthetics in major markets will reshape volume accessibility and manufacturer pricing power.
Market Dynamics
The artificial iris market pivots on 3D printing's capacity to collapse lead times for patient-specific implants while ophthalmology clinics consolidate procurement authority away from hospital systems. This technological shift compresses manufacturer inventory requirements and elevates direct-to-clinic commercial relationships as the dominant channel architecture.
Growth Catalysts
- FDA Class II device framework:The United States regulatory pathway rewards quality management system investments, creating durable competitive moats for manufacturers with established 510(k) clearance histories. This accelerates market entry barriers that protect incumbent positioning.
- 3D printing adoption:Additive manufacturing enables anatomically matched iris prosthesis production without mold inventory, reducing working capital requirements for specialized ocular implant centers. This technology is virtualizing traditional manufacturing constraints across European manufacturing bases.
- German ocular implant centers:Aging demographics and specialized surgical concentration in Munich, Heidelberg, and Berlin generate procedural volume density that supports premium product uptake and surgeon training pipelines.
Market Restraints
- Medical-grade silicone supply concentration:Raw material qualification under ISO 10993 biocompatibility standards constrains supplier switching, creating input cost volatility exposure for manufacturers dependent on European chemical suppliers.
- EU MDR compliance burden:The Medical Device Regulation's enhanced clinical evidence requirements extend certification timelines and elevate documentation costs, disproportionately affecting smaller manufacturers without dedicated regulatory affairs functions.
- Cosmetic contact lens substitution:Non-invasive aesthetic alternatives for congenital aniridia patients capture price-sensitive demand segments, limiting addressable market expansion in private-pay cosmetic applications.
Strategic Opportunities
- Japan's PMDA accelerated review pathway:The Pharmaceuticals and Medical Devices Agency's priority review designation for orphan ophthalmic conditions offers faster market access for trauma reconstruction devices targeting aniridia and coloboma patient populations.
- Benelux clinic network expansion:Underpenetrated specialized surgical centers in Belgium and Luxembourg present white space for direct distribution models bypassing traditional hospital procurement committees.
- Digital surgical planning integration:Convergence between 3D printing and preoperative imaging software creates bundled service opportunities where manufacturers capture recurring revenue from surgical planning subscriptions alongside hardware sales.
Industry Challenges
- Oculoplastic surgeon training scarcity:The specialized microsurgical skills required for iris prosthesis implantation limit procedural volume growth, constraining market expansion regardless of product availability or reimbursement coverage.
- CE marking transition timeline:Manufacturers face compressed MDR recertification deadlines that strain technical documentation resources and risk supply interruptions if legacy certificates expire before conformity assessment completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Iris Market |
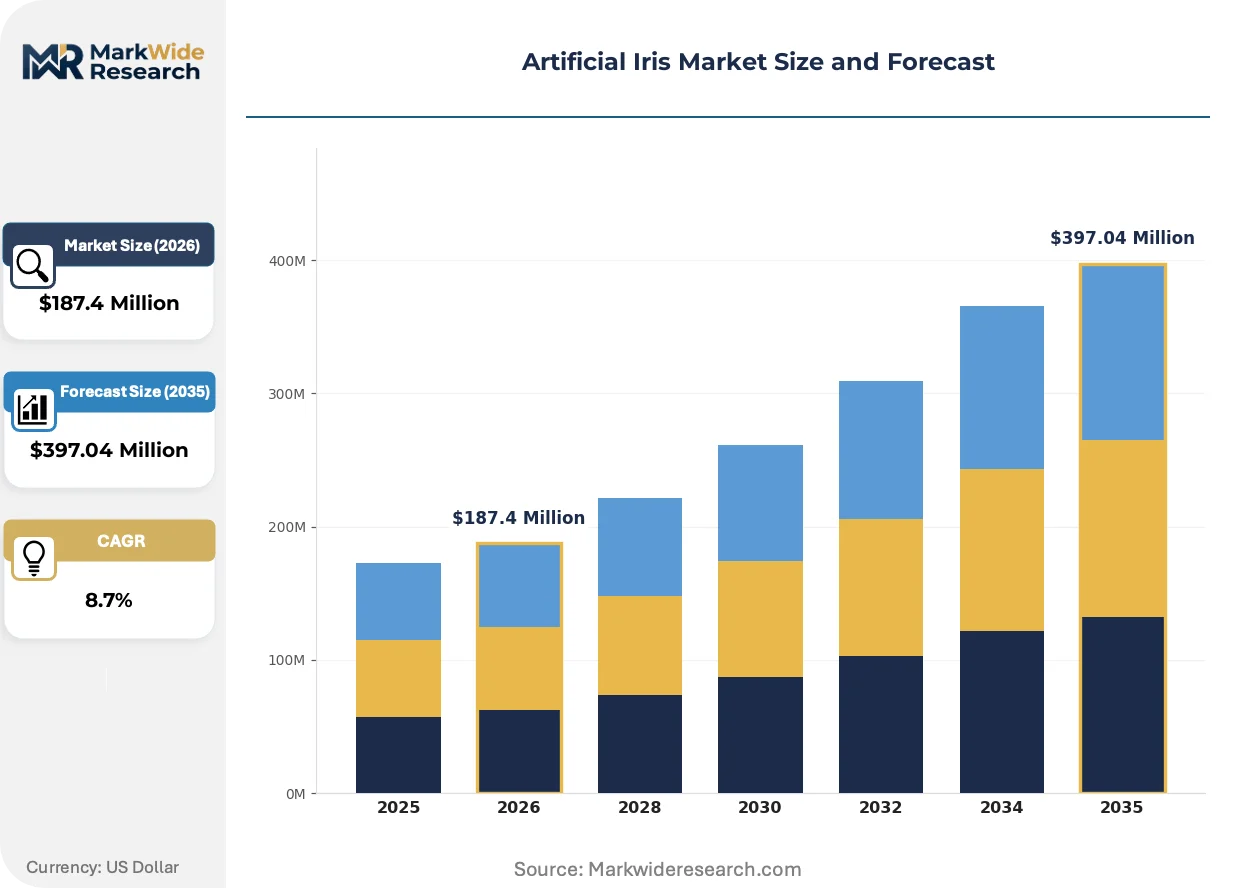
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
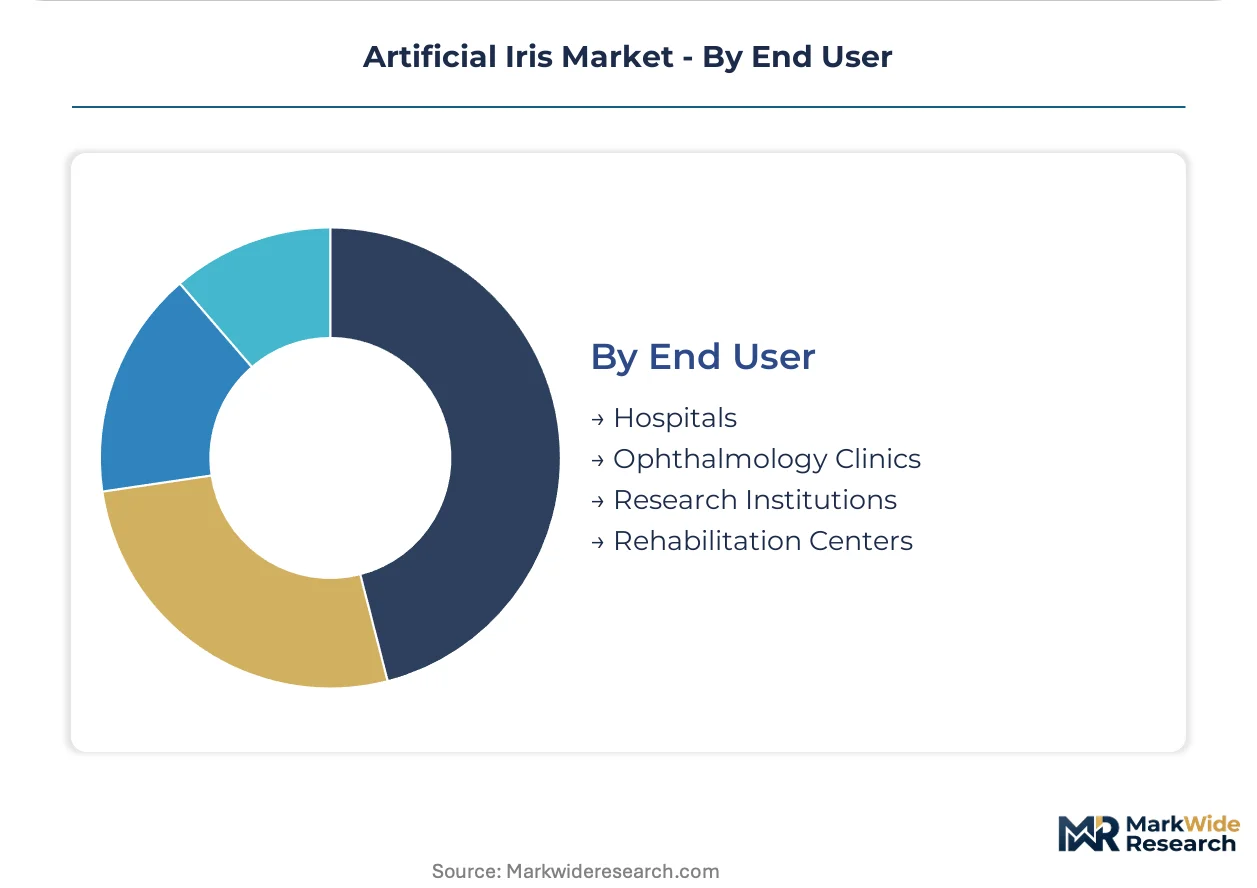
| Segmentation | Product Type: Custom Iris, Artificial Lens, Iris Prosthesis, Aesthetic Iris Technology: 3D Printing, Biocompatible Materials, Silicon-Based, Laser Technology Application: Cosmetic Enhancement, Medical Reconstruction, Trauma Recovery, Vision Correction End User: Hospitals, Ophthalmology Clinics, Research Institutions, Rehabilitation Centers |
| Companies Covered | HumanOptics Holding AG, REPER-NN LTD, Kestrel Ophthalmics Inc., VEO Ophthalmics, InsEYEt, LLC, Spectrum Surgical, Art Eyes, BrightOcular, Ophtec BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Iris Market Evolving Landscape
Digital manufacturing workflows and regulatory data harmonization are compressing product development cycles while redistributing value capture toward patient-matching capabilities and away from standardized inventory models.
3D printing technology is virtualizing traditional silicone molding processes for iris prosthesis production. Ophthalmology clinics in Germany and Austria are adopting this capability fastest, driven by direct manufacturer partnerships that eliminate distributor markups. The technology is virtualizing inventory economics by enabling on-demand production that collapses working capital requirements and reduces obsolescence risk for patient-specific anatomical variants.
The EU Medical Device Regulation's Unique Device Identification requirements are mandating end-to-end traceability systems for all implantable ocular devices. This policy forces manufacturers to retrofit legacy quality management systems with serialized production tracking and post-market surveillance infrastructure. Iris prosthesis products face the steepest compliance burden due to their implantable classification and small-batch production characteristics that complicate automated serialization.
Specialized surgical centers are consolidating procurement authority through multi-year direct purchasing agreements that displace traditional hospital supply chain intermediaries. This channel compression is most visible in the United States, where ambulatory surgery center networks negotiate volume commitments with manufacturers in exchange for price transparency and dedicated inventory allocation. The shift elevates clinical outcome data and surgeon training support as competitive differentiators over traditional distributor relationships.
Artificial Iris Market Segmentation
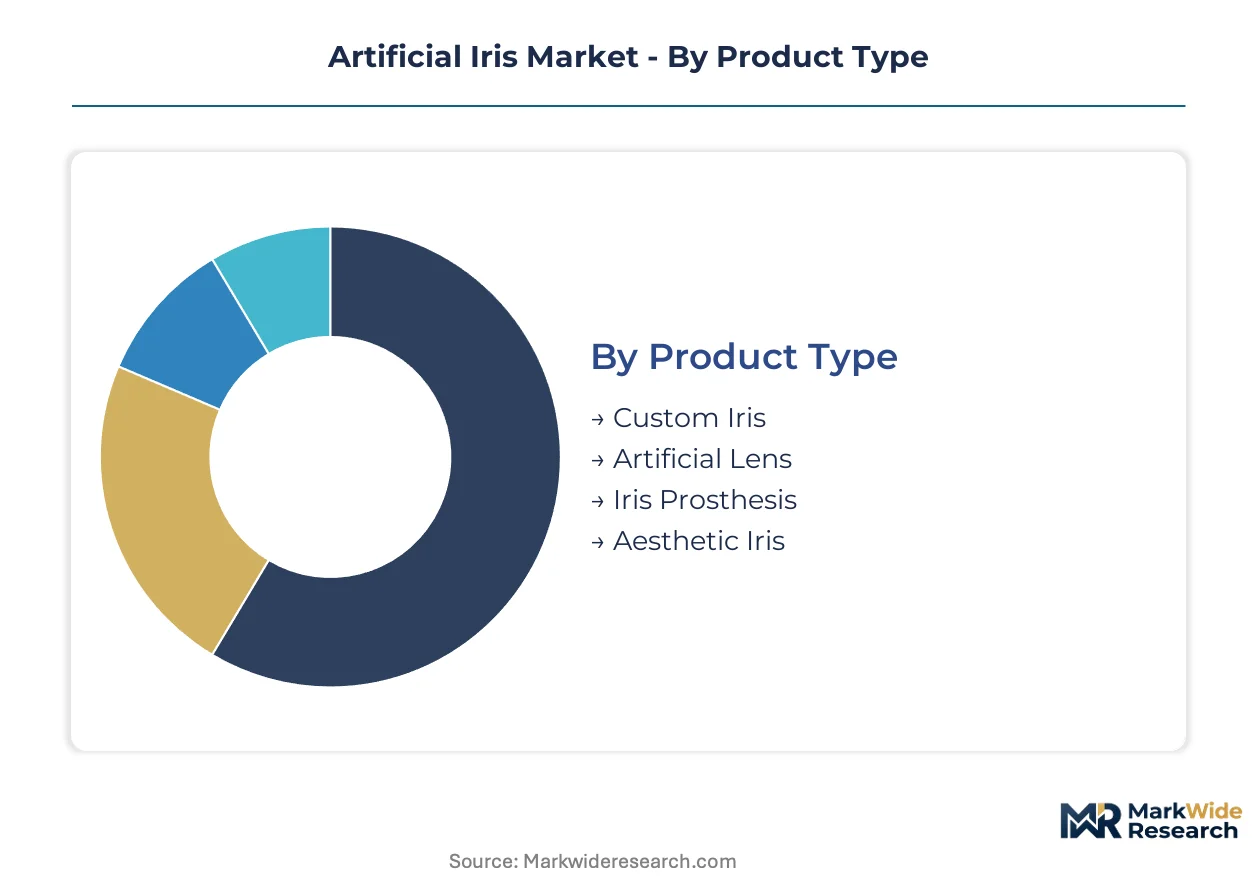
Artificial iris manufacturers must align service infrastructure with distinct segment requirements. Custom-fitted implants demand intensive preoperative consultation and postoperative adjustment support, while standardized products prioritize inventory velocity and distributor relationships.
Product Type:
After-sales-service intensity varies dramatically across product categories, with patient-matched solutions requiring ongoing ocularist collaboration and revision support that commodity-grade alternatives do not.
- Iris Prosthesis:Manufactured from medical-grade silicone or polymethyl methacrylate with standardized pupil diameters and fiber density parameters. Demand concentrates in German ocular implant centers and Austrian specialized surgical facilities where established reimbursement codes and surgeon familiarity sustain procedural volume. Postoperative adjustment protocols and long-term biocompatibility monitoring elevate service requirements for this segment.
- Custom Iris:Patient-specific anatomical matching requires 3D scanning integration and iterative color-matching consultations with ocularists. Private-pay cosmetic markets in the United States absorb premium pricing for congenital aniridia corrections, with direct-to-clinic relationships replacing traditional distributor markups. Each case demands dedicated surgical planning support and post-implantation pigment stability monitoring.
- Artificial Lens:Combines iris reconstruction with intraocular optical correction in single-device configurations. Trauma recovery applications in Japan's specialized ophthalmic centers drive adoption.
- Aesthetic Iris:Elective color modification for cosmetic purposes without medical indication. Price-sensitive demand segments face substitution pressure from non-invasive cosmetic contact lens alternatives.
Iris Prosthesis holds the largest share; momentum sits with Custom Iris as 3D printing collapses patient-matching lead times.
Technology:
Manufacturing cost tiers separate capital-intensive additive systems from conventional molding infrastructure, with technology choice determining working capital requirements and inventory obsolescence risk.
- 3D Printing:Additive manufacturing enables on-demand production of anatomically matched implants without mold inventory investment. Ophthalmology clinics in Germany and Austria adopt this capability fastest through direct manufacturer partnerships that eliminate working capital burdens and reduce obsolescence risk for patient-specific variants. Digital workflows compress lead times from weeks to days.
- Biocompatible Materials:Medical-grade silicone and polymethyl methacrylate formulations qualified under ISO 10993 standards constrain supplier switching and create input cost volatility exposure. European chemical suppliers dominate qualification pathways, with raw material concentration elevating compliance documentation requirements for batch-specific biocompatibility testing.
- Silicon-Based:Traditional elastomer molding processes for standardized iris prosthesis production. Established manufacturers leverage scale economies in high-volume trauma reconstruction markets.
- Laser Technology:Precision ablation and surface texturing for pigment integration and edge finishing. Specialized ocular implant centers deploy intraoperative laser systems for final fit adjustments.
Biocompatible Materials anchors current production; 3D Printing is gaining share fastest through inventory virtualization.
Application:
Volume concentration and margin structure diverge sharply between medical necessity and elective cosmetic segments, with reimbursement status determining addressable market accessibility.
- Medical Reconstruction:Post-traumatic and post-enucleation iris replacement procedures sustain procedural demand through established reimbursement pathways. United States ambulatory surgery centers and German ocular implant centers generate volume density that supports premium product uptake and dedicated surgeon training pipelines. Outcome data requirements and complication liability elevate manufacturer clinical support obligations.
- Cosmetic Enhancement:Congenital aniridia and iris defect corrections command premium pricing in private-pay markets where aesthetic outcome sensitivity justifies out-of-pocket expenditure. Price differentiation separates medical-grade reconstruction from elective color modification tiers, with non-invasive contact lens alternatives capturing budget-conscious demand.
- Trauma Recovery:Acute iris damage reconstruction following penetrating eye injury or surgical complication. Japan's PMDA priority review pathway accelerates market access for orphan ophthalmic conditions.
- Vision Correction:Combined optical and cosmetic iris reconstruction in aphakic or pseudophakic eyes. Specialized surgical centers in the United States concentrate multi-procedure volume.
Medical Reconstruction dominates volume; Cosmetic Enhancement carries the steepest expansion trajectory through premium pricing power.
End User:
Customer type determines procurement authority concentration and pricing transparency, with channel compression favoring direct manufacturer relationships over traditional distributor intermediaries.
- Ophthalmology Clinics:Specialized surgical centers now control patient flow and procurement decisions through multi-year direct purchasing agreements. United States ambulatory surgery center networks negotiate volume commitments with manufacturers in exchange for price transparency and dedicated inventory allocation. Clinical outcome data and surgeon training support displace traditional distributor relationships as competitive differentiators.
- Hospitals:Traditional procurement committees and supply chain intermediaries retain influence in trauma emergency settings and complex multi-specialty reconstructions. Consolidated purchasing organizations extract volume discounts that compress manufacturer margins.
- Research Institutions:Preclinical and clinical trial sites for novel iris prosthesis materials and 3D printing validation studies. Regulatory evidence generation partnerships with manufacturers.
- Rehabilitation Centers:Postoperative ocularist services and cosmetic fitting support for prosthetic iris patients. Benelux clinic networks present underpenetrated white space for service expansion.
Hospitals retain the largest installed base; Ophthalmology Clinics are climbing the fastest as procurement authority consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Class II medical device framework anchors the United States as the regulatory benchmark for artificial iris market entry, while specialized ocular implant centers in Germany and Japan concentrate procedural demand through aging demographics and trauma reconstruction volumes.
United States
Ambulatory surgery center networks consolidate procurement authority through multi-year direct purchasing agreements with manufacturers. FDA's 510(k) clearance pathway rewards quality management system investments, creating durable competitive moats for established players. Greater Boston and Pacific Northwest clusters concentrate specialized oculoplastic surgical training pipelines that sustain procedural volume growth.
Germany
Munich, Heidelberg, and Berlin generate the highest procedural density for iris prosthesis implantation in Europe. EU Medical Device Regulation's enhanced clinical evidence requirements extend certification timelines for manufacturers seeking CE marking renewal. Bavaria's specialized ocular implant centers drive premium product uptake through direct-to-clinic relationships that bypass traditional hospital procurement committees.
Japan
PMDA's priority review designation for orphan ophthalmic conditions accelerates market access for trauma reconstruction devices targeting aniridia and coloboma patient populations. Tokyo and Osaka metropolitan areas concentrate specialized ophthalmic surgical centers with established reimbursement pathways. Aging demographics sustain demand for post-traumatic iris replacement procedures.
Netherlands
Benelux clinic networks present underpenetrated white space for direct distribution models that bypass traditional hospital procurement intermediaries. CE marking requirements under EU MDR mandate end-to-end traceability systems for all implantable ocular devices. Eindhoven Region's manufacturing base supports medical-grade silicone supply qualification under ISO 10993 biocompatibility standards.
Australia
TGA's medical device approval framework aligns with international standards while maintaining distinct post-market surveillance requirements for implantable ocular devices. Sydney and Melbourne concentrate specialized ophthalmology clinics that control patient flow for cosmetic enhancement procedures. Private-pay markets absorb premium pricing for congenital aniridia corrections outside public reimbursement pathways.
Artificial Iris Market Competitive Landscape
Specialized European manufacturers and North American trauma reconstruction specialists split the market into distinct competitive territories defined by regulatory clearance history and surgeon training relationships. The vendor base concentrates around quality management system investments that satisfy FDA and EU MDR compliance burdens simultaneously. Three archetypes dominate: integrated ocular implant manufacturers with captive silicone supply, 3D printing-enabled custom prosthesis fabricators, and trauma-focused reconstruction device specialists. Competitive moves center on direct-to-clinic distribution partnerships and digital surgical planning integration that captures recurring revenue alongside hardware sales.
Among European-integrated manufacturers, HumanOptics Holding AG occupies a position exemplifying direct-to-clinic relationship models across German and Austrian specialized surgical centers. Kestrel Ophthalmics Inc. represents the trauma reconstruction specialist archetype with product focus on acute iris damage interventions. Ophtec BV anchors the Benelux geographic concentration through selective hospital partnerships and regional distribution control. These three entities illustrate how regulatory compliance investments and geographic clustering strategies create defendable market positioning.
| Leading Market Players |
|---|
| HumanOptics Holding AG |
| REPER-NN LTD |
| Kestrel Ophthalmics Inc. |
| VEO Ophthalmics |
| InsEYEt, LLC |
| Spectrum Surgical |
| Art Eyes |
| BrightOcular |
| Ophtec BV |
| Others |
Value Network & Pricing Analysis
European medical-grade silicone suppliers in Germany and the Netherlands concentrate raw material qualification pathways, anchoring margin pools with manufacturers who have secured ISO 10993 biocompatibility documentation and locked in multi-year offtake terms with specialized ocular implant centers.
Pricing Analysis
United States private-pay cosmetic procedures command three-to-fourfold premiums over reimbursed medical reconstructions in Germany and Japan. Pricing stratifies across premium custom-matched, standard prosthesis, and economy trauma-reconstruction tiers, with FDA 510(k) clearance history and surgeon training relationships as primary price differentiation drivers. Cost compression in the standard tier is intensifying as ambulatory surgery center networks consolidate procurement authority and demand price transparency. Price-sensitive demand concentrates in elective aesthetic applications where cosmetic contact lens alternatives capture budget-conscious segments.
Supply Chain Analysis
Contract manufacturing for iris prosthesis components concentrates with German and Austrian specialized polymer processors and Swiss precision machining houses. Medical-grade silicone and polymethyl methacrylate formulations draw from European chemical suppliers qualified under ISO 10993 standards, with pigment integration and surface texturing as critical downstream steps. Single-source vulnerability runs through legacy silicone suppliers facing recertification deadlines under EU MDR. Distribution runs through direct-to-clinic partnerships that displace traditional hospital supply chain intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial iris manufacturers face a service-attach inflection where digital surgical planning subscriptions and postoperative ocularist support expand faster than hardware unit economics, rewarding vendors who bundle recurring-revenue capabilities with implant sales.
For Market Incumbents: Pre-empt 3D printing-enabled custom fabricators by locking exclusive digital workflow partnerships with high-volume ophthalmology clinics in Germany and Austria. Secure backward integration into medical-grade silicone compounding to neutralize raw material cost volatility and ISO 10993 recertification risk. Defend against trauma-reconstruction specialists by embedding surgical planning software into clinician training pipelines. For New Entrants and Emerging Players: Belgium and Luxembourg's underpenetrated specialized surgical centers present immediate white-space for direct distribution models bypassing hospital procurement committees. Target Japan's PMDA priority review pathway for orphan ophthalmic conditions as the fastest regulatory on-ramp. Lead with trauma reconstruction devices where reimbursement pathways are established and surgeon relationships are transferable. For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with captive silicone supply and established CE marking infrastructure under EU MDR. Long-term viability across the analysis window favors vendors who have absorbed quality management system compliance costs and consolidated direct-to-clinic channels. Watch for inflection signals in 3D printing adoption rates at German ocular implant centers and PMDA submission volumes for trauma reconstruction devices.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Surgical Planning Integration | Bundles recurring software revenue with hardware sales at German specialized ocular implant centers. |
| EU MDR CE Marking Pathway | Secures market access continuity as legacy certificate expiration deadlines compress across European manufacturing bases. |
| Direct-to-Clinic Distribution Expansion | Bypasses hospital procurement committees and captures price transparency commitments from ambulatory surgery center networks. |
| Biocompatible Materials Backward Integration | Neutralizes ISO 10993 raw material qualification risk and silicone supply concentration exposure. |
| PMDA Priority Review Strategy | Accelerates orphan ophthalmic device market entry in Japan's trauma reconstruction segment. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with oculoplastic surgeons, ophthalmology clinic procurement directors, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Forecast inputs considered procedural volume trajectories across medical reconstruction and cosmetic enhancement applications, technology adoption curves for 3D printing versus traditional silicone molding, and channel shift dynamics between hospital systems and ambulatory surgery centers. Segmentation dimensions included product type, manufacturing technology, application indication, and end-user procurement authority. CAGRs were derived from regression analysis of historical procedural volumes and forward projection of reimbursement policy evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by 3D printing custom fabricators or vertical integration by trauma-reconstruction specialists would shift outcomes. Quarterly review of PMDA submission volumes, EU MDR recertification completion rates, and ambulatory surgery center network expansion metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Aesthetic Ophthalmology Device Market
Ophthalmology
Nystagmus Market
Ophthalmology
Global Hemianopsia Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
Laser Indirect Ophthalmoscope Market
Ophthalmology
Astigmatism Market
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Ophthalmic Eye Shield Market