
 Global Posterior Segment Eye Disorders Market | 2026-2036
Global Posterior Segment Eye Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Posterior Segment Eye Disorders Market Foresight
Project finance for ophthalmic ambulatory surgical centers is reconfiguring competitive dynamics across the posterior segment landscape. Regeneron Pharmaceuticals leverages its vertically integrated antibody platform to sustain manufacturing scale for anti-VEGF therapies. Alcon Inc. anchors the surgical instruments segment through specialized vitrectomy systems that dominate hospital procurement channels.
Posterior segment eye disorders encompass pathologies affecting the retina, choroid, and optic nerve, typically diagnosed through optical coherence tomography achieving axial resolutions of 5-7 micrometers for precise retinal layer visualization. These conditions demand interventions preserving photoreceptor integrity and preventing irreversible vision loss. Anti-VEGF therapy leads the treatment modality landscape as the standard of care for neovascular age-related macular degeneration, while biologics within the product type category capture expanding margin pools due to complex manufacturing requirements and patent-protected formulations. Drug delivery devices represent the fastest-growing treatment modality as sustained-release implants reduce injection burden for chronic retinal diseases.
The FDA regulates ophthalmic biologics under BLA pathways with stringent purity standards, while the EMA's MDR framework governs intraocular device certification across European markets. Japan's PMDA accelerates reviews for therapies addressing geographic atrophy, shaping regional product launch sequencing. Stakeholders must monitor evolving reimbursement thresholds for sustained-release formulations versus standard intravitreal injections as payors recalibrate value-based access criteria.
Market Dynamics
The posterior segment therapeutics landscape is reshaping around sustained-release drug delivery platforms that compress treatment frequency from monthly to semi-annual intervals, fundamentally altering patient adherence economics and clinic capacity planning across ophthalmology practices.
Growth Catalysts
- Biologics License Application Streamlining:The FDA's abbreviated pathway for ophthalmic biologics accelerates IND-to-approval timelines for anti-VEGF candidates, expanding the investigational pipeline for diabetic macular edema and retinal vein occlusion indications.
- Aging Demographics in Developed Economies:Japan, Germany, and the United States exhibit concentrated prevalence of neovascular age-related macular degeneration, driving treatment intensity per capita and specialty hospital infrastructure expansion.
- Optical Coherence Tomography:High-resolution imaging achieving 5-7 micrometer axial resolution enables earlier disease detection and treatment initiation, expanding addressable patient pools beyond symptomatic cohorts.
Market Restraints
- Recombinant Protein Manufacturing Concentration:Bulk biologics production clusters among contract manufacturers in Switzerland and Ireland, creating single-source vulnerability for anti-VEGF active pharmaceutical ingredients.
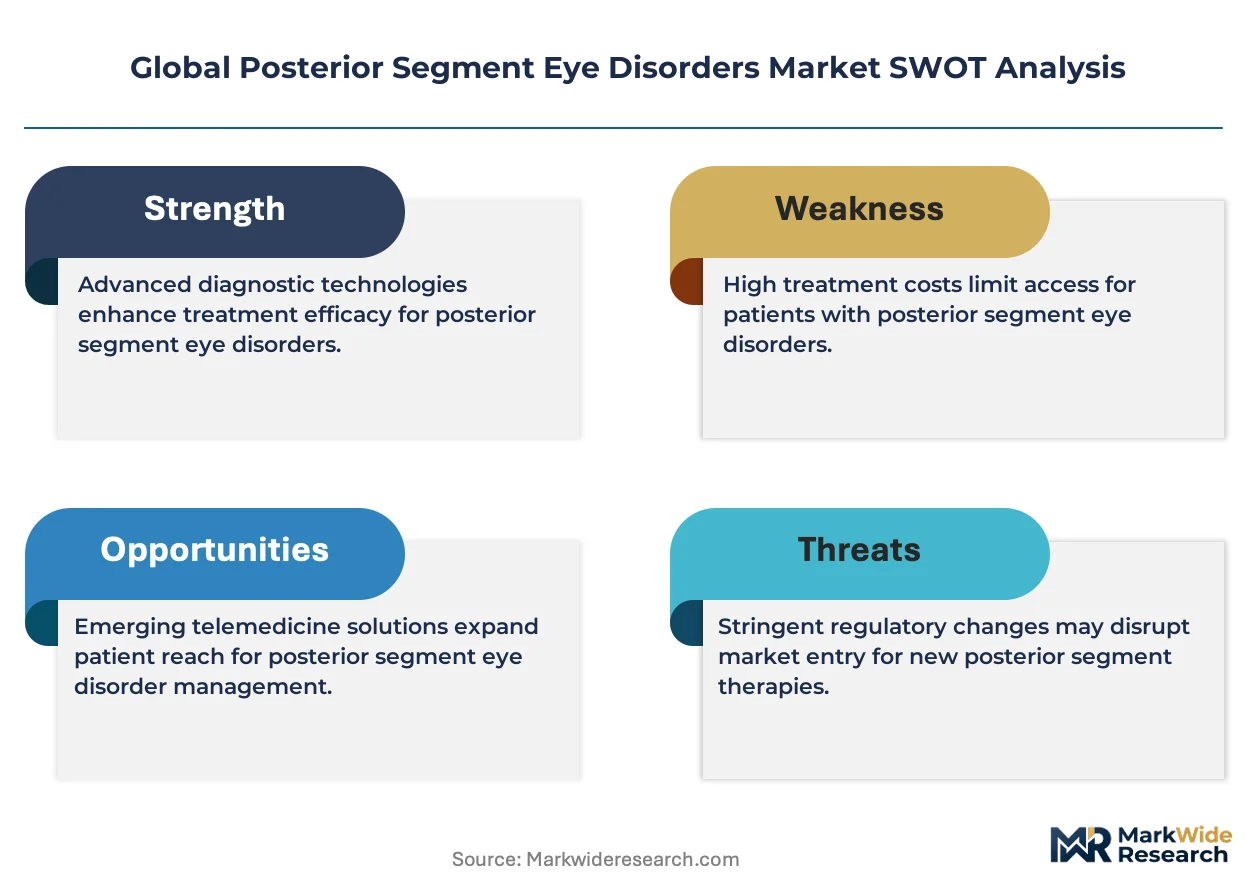
- Intravitreal Injection Burden:Chronic monthly administration requirements strain retinal specialist capacity and patient compliance, limiting real-world effectiveness versus clinical trial outcomes.
- EMA MDR Certification Complexity:Intraocular device reclassification under the EU Medical Device Regulation extends notified body review timelines for sustained-release implants, delaying European commercialization.
Strategic Opportunities
- Geographic Atrophy Unmet Need:The PMDA's priority review designation for complement pathway inhibitors creates first-mover positioning in Japan's rapidly aging patient population.
- Gene Therapy Convergence:Adeno-associated viral vectors combined with CRISPR editing platforms enable one-time interventions for inherited retinal dystrophies, potentially displacing chronic anti-VEGF administration.
- Ambulatory Surgical Center Channel:Standalone ophthalmic ASCs bypass hospital procurement bottlenecks and capture margin through bundled procedure-drug reimbursement models.
Industry Challenges
- Vitreoretinal Surgeon Training Pipeline:Fellowship positions fail to match patient volume growth, creating geographic access disparities and treatment delays in secondary markets.
- Good Manufacturing Practice Facility Validation:Aseptic fill-finish capacity for biologics requires 24-36 month construction and qualification timelines, constraining supply elasticity for demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Posterior Segment Eye Disorders Market |
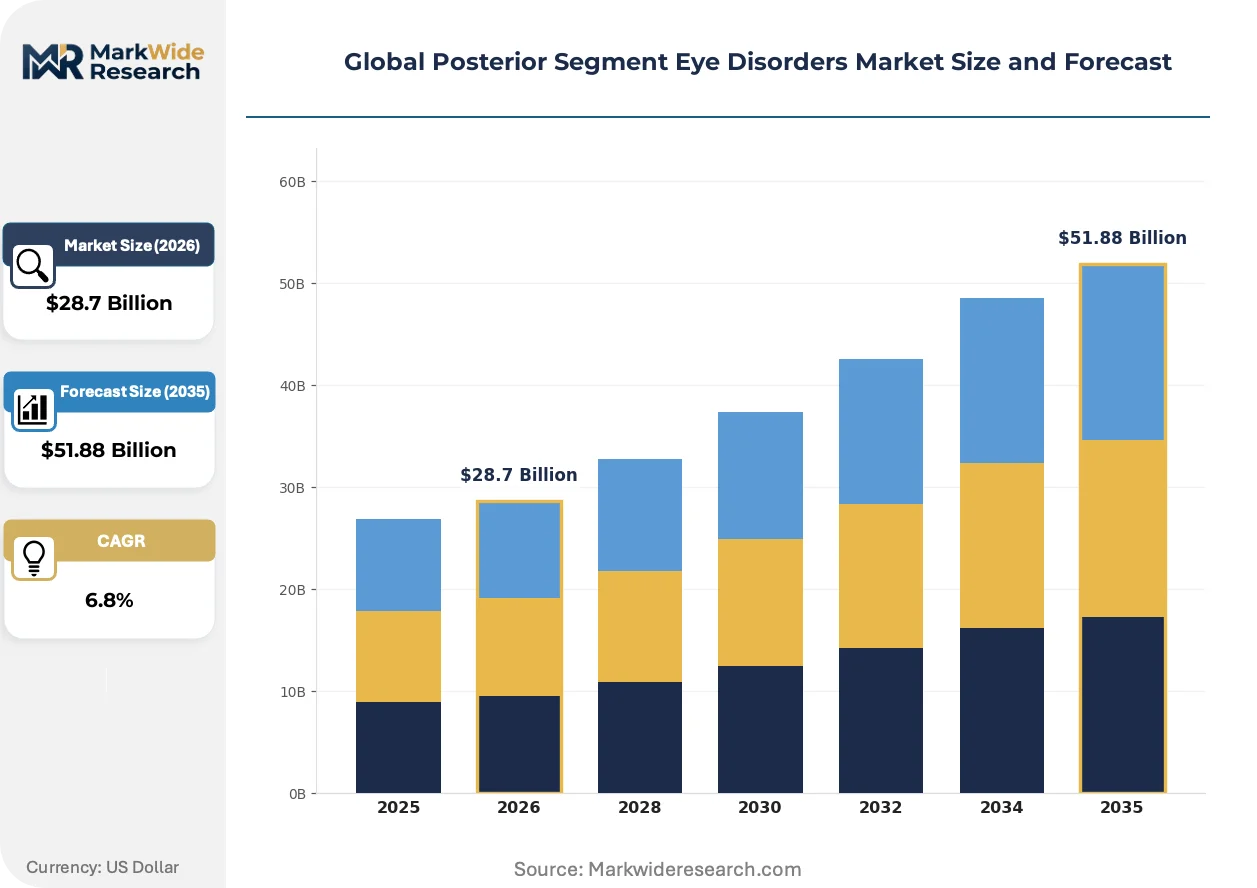
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Disorder Type: Age-Related Macular Degeneration, Diabetic Retinopathy, Retinal Vein Occlusion, Uveitis, Others Treatment Modality: Anti-VEGF Therapy, Corticosteroid Therapy, Laser Photocoagulation, Vitrectomy, Drug Delivery Devices End User: Ophthalmic Clinics, Specialty Eye Hospitals, Ambulatory Surgical Centers, Research Institutes Product Type: Pharmaceuticals, Surgical Instruments, Diagnostic Imaging Systems, Injectable Devices, Biologics |
| Companies Covered | Regeneron Pharmaceuticals Inc, Alcon Inc., Novartis AG, Santen Pharmaceutical Co. Ltd., Bausch Health Companies Inc., F. Hoffmann-La Roche AG, Merck & Co. Inc., Second Sight Medical Products Inc., AbbVie Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Posterior Segment Eye Disorders Market Shifts & Advancements
Biopharmaceutical delivery architectures are converging with microfabrication capabilities, enabling programmable release kinetics that match disease progression patterns rather than forcing patients to clinical schedules.
Sustained-release intravitreal implants are migrating from experimental platforms to standard-of-care alternatives for chronic retinal diseases. Retinal specialists in high-volume United States practices are adopting port delivery systems and hydrogel depots at accelerating rates, compressing the addressable market for conventional intravitreal syringes and shifting clinic workflow toward less frequent, higher-reimbursement procedures.
The FDA's breakthrough therapy designation for ophthalmic gene therapies is compressing regulatory review timelines while maintaining safety surveillance rigor. This acceleration is reshaping portfolio prioritization at biopharmaceutical developers, who are reallocating resources from incremental anti-VEGF formulations toward one-time curative modalities for inherited retinal conditions, with the most pronounced pipeline shifts visible in the United States and European Union.
Retinal practices are consolidating purchasing decisions through specialty group purchasing organizations that negotiate drug-device bundles directly with manufacturers, bypassing traditional wholesale distribution. This channel transformation is most advanced in the United States, where vertically integrated retina practice management platforms now control substantial anti-VEGF volume and extract price concessions through committed volume agreements.
Global Posterior Segment Eye Disorders Market Segmentation
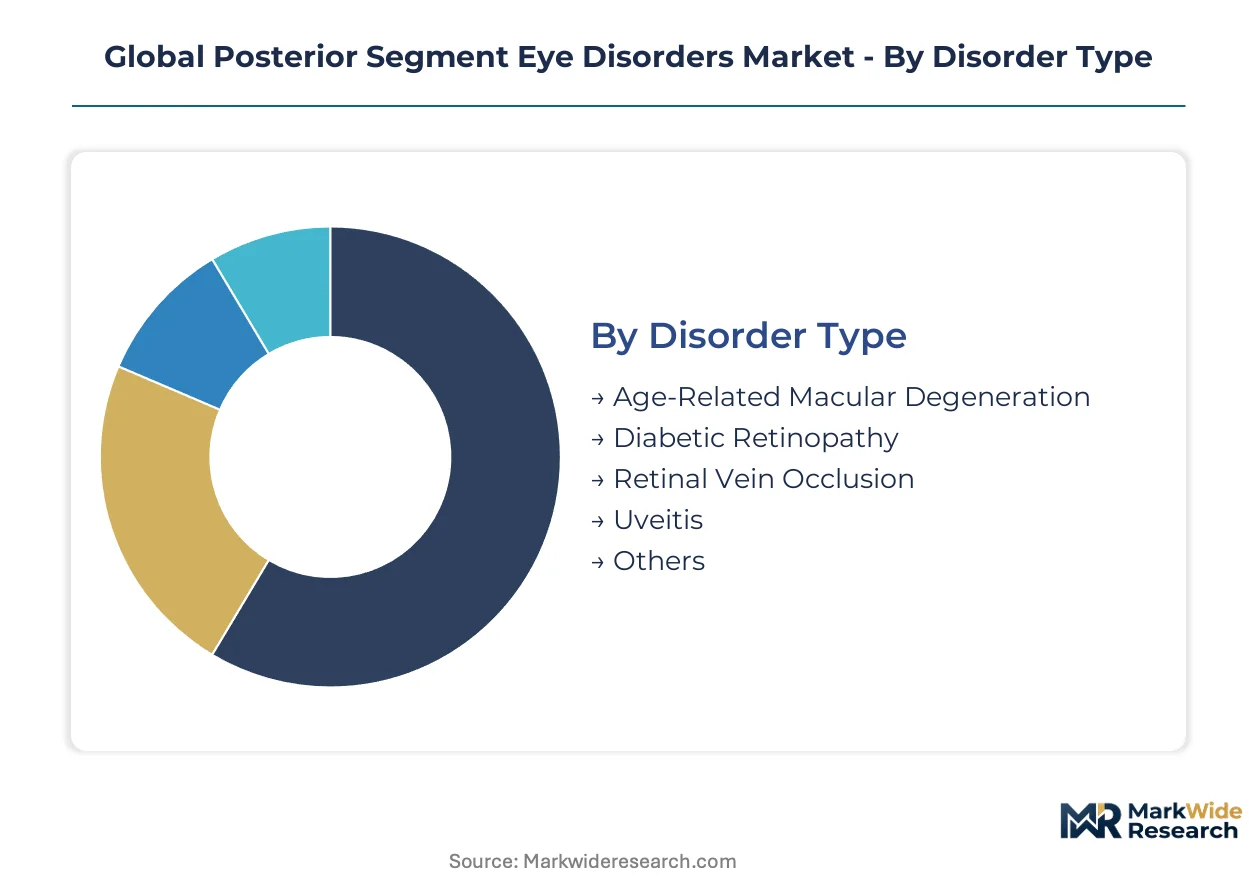
Posterior segment therapeutics fragment across four structural dimensions that determine procurement patterns and margin capture. Disorder type dictates treatment intensity and reimbursement codes. Product type and treatment modality govern manufacturing complexity and regulatory pathway selection.
Disorder Type:
Cycle times vary dramatically across indications, with chronic progressive conditions requiring sustained intervention versus acute episodic disorders demanding episodic care.
- Age-Related Macular Degeneration:Neovascular AMD drives the majority of anti-VEGF injection volume in the United States, Germany, and Japan. Wet AMD patients require monthly to bimonthly intravitreal administration indefinitely, compressing clinic capacity and sustaining pharmaceutical demand.
- Diabetic Retinopathy:Proliferative and diabetic macular edema variants now absorb expanding specialist hours as diabetes prevalence climbs in North American and European populations. Vision-threatening complications trigger earlier intervention thresholds under updated clinical guidelines.
- Retinal Vein Occlusion:Branch and central RVO indications represent concentrated anti-VEGF and corticosteroid demand with defined acute treatment windows.
- Uveitis:Posterior uveitis requires immunomodulatory and sustained-release corticosteroid approaches with smaller addressable populations.
- Others:Inherited retinal dystrophies and geographic atrophy are gaining therapeutic attention as gene therapy platforms mature.
Age-Related Macular Degeneration dominates installed base. Geographic Atrophy within Others is where expansion concentrates.
Treatment Modality:
Cost tiers separate chronic pharmaceutical administration from capital-intensive surgical intervention and emerging device-based delivery platforms.
- Anti-VEGF Therapy:Ranibizumab, aflibercept, and biosimilar formulations constitute the standard pharmacologic approach for neovascular retinal diseases. United States retinal practices allocate the majority of chair time to these intravitreal injections.
- Drug Delivery Devices:Sustained-release implants and port delivery systems are climbing the fastest as manufacturers engineer six-month dosing intervals for ranibizumab and faricimab analogues.
- Corticosteroid Therapy:Intravitreal steroid implants address macular edema from RVO and uveitis with distinct side-effect profiles requiring glaucoma monitoring.
- Laser Photocoagulation:Focal and panretinal photocoagulation retains role in proliferative diabetic retinopathy and selected peripheral retinal pathologies.
- Vitrectomy:Pars plana vitrectomy addresses tractional retinal detachment, epiretinal membrane, and vitreous hemorrhage with instrument systems dominating hospital procurement.
Anti-VEGF Therapy dominates installed base. Drug Delivery Devices is where expansion concentrates.
End User:
Customer type determines reimbursement mechanics and capital deployment requirements, with freestanding facilities capturing margin through procedure-drug bundling.
- Specialty Eye Hospitals:Dedicated ophthalmic institutions in Japan, Germany, and the United States maintain high-volume injection suites and vitreoretinal surgical theaters. These centers negotiate directly with manufacturers for anti-VEGF volume commitments.
- Ambulatory Surgical Centers:Freestanding ASCs in the United States bypass hospital administrative overhead and capture favorable site-of-service differentials for intravitreal procedures.
- Ophthalmic Clinics:Private practice retinal specialists manage chronic injection populations with optical coherence tomography-guided treatment extend protocols.
- Research Institutes:Academic medical centers conduct gene therapy trials and imaging biomarker studies under FDA and EMA investigational frameworks.
Specialty Eye Hospitals dominates installed base. Ambulatory Surgical Centers is where expansion concentrates.
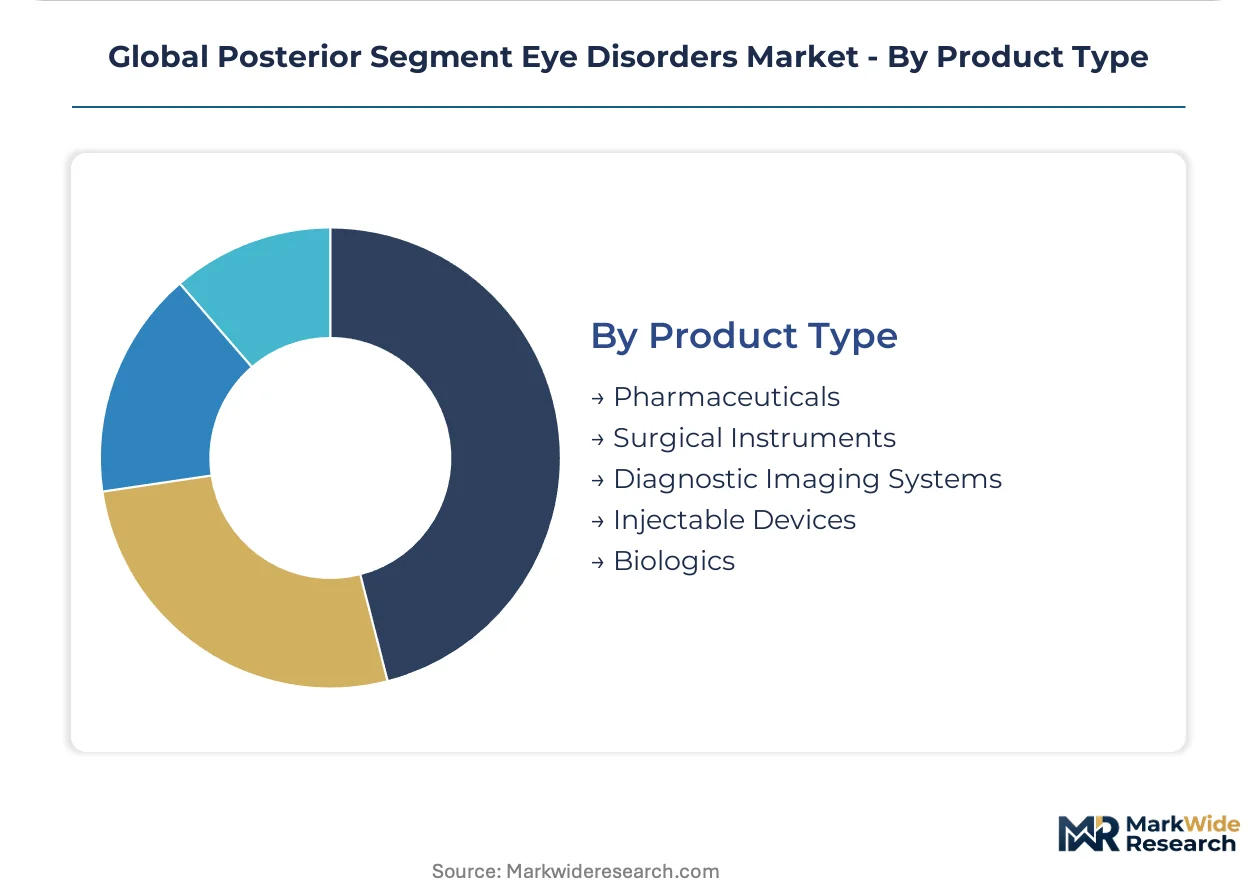
Product Type:
Supply concentration clusters in biologics manufacturing, while diagnostic imaging and surgical instruments consolidate through distinct vendor ecosystems.
- Biologics:Recombinant antibodies and fusion proteins require aseptic fill-finish capacity concentrated among contract manufacturers in Switzerland and Ireland. Patent-protected formulations command premium pricing through ophthalmology-specific sales forces.
- Pharmaceuticals:Small-molecule and biosimilar anti-VEGF alternatives compete on price in European markets with EMA centralized approval pathways.
- Injectable Devices:Prefilled syringes and sustained-release implants demand polymer science and microfabrication capabilities from specialized device manufacturers.
- Surgical Instruments:Vitrectomy systems, laser consoles, and disposable packs flow through hospital procurement and ASC group purchasing organizations.
- Diagnostic Imaging Systems:Spectral-domain and swept-source optical coherence tomography platforms achieve 5-7 micrometer axial resolution for retinal layer visualization.
Biologics dominates installed base. Injectable Devices is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's PMDA priority review pathway for geographic atrophy therapies accelerates commercial timelines, while Germany's EMA MDR implementation reshapes device certification economics. The United States, Switzerland, and India complete the geographic matrix where regulatory differentiation creates distinct competitive entry points.
United States
Retina specialist practices in Florida and California absorb the highest per-capita anti-VEGF injection volumes globally. The FDA's breakthrough therapy designation for ophthalmic gene therapies compresses review timelines for inherited retinal dystrophy candidates. Boston's academic medical centers anchor gene therapy trial recruitment, pulling manufacturing investment toward the Northeast corridor.
Germany
Specialty eye hospitals in Bavaria and North Rhine-Westphalia maintain Europe's densest vitreoretinal surgical theater networks. EMA MDR reclassification of sustained-release implants extends notified body review timelines, delaying product launches versus Swiss competitors. The Heidelberg ophthalmology cluster concentrates optical coherence tomography R&D and diagnostic imaging manufacturing.
Japan
Tokyo and Osaka metropolitan areas concentrate the world's oldest patient populations, driving treatment intensity for neovascular AMD. PMDA's Sakigake designation accelerates reviews for complement pathway inhibitors addressing geographic atrophy. Kansai region manufacturing bases supply aseptic fill-finish capacity for Asia-Pacific biologics distribution.
Switzerland
Basel and Zurich host contract manufacturing organizations producing bulk anti-VEGF active pharmaceutical ingredients for global markets. Swissmedic maintains alignment with EMA standards while offering streamlined timelines for novel biologics. The country's polymer science capabilities support sustained-release implant development for European commercialization.
India
Maharashtra and Karnataka states expand ophthalmic clinic networks to address diabetic retinopathy prevalence among urban populations. CDSCO's accelerated approval pathway for biosimilar anti-VEGF therapies enables faster market entry versus originator products. Hyderabad's pharmaceutical manufacturing cluster develops fill-finish capacity for regional biologics supply.
Global Posterior Segment Eye Disorders Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct value capture vectors. Retina practice management platforms in the United States negotiate volume commitments directly with manufacturers, while European hospital procurement consortia centralize purchasing decisions. The competitive structure fragments across three archetypes: vertically integrated biopharmaceutical developers, specialized surgical instrument manufacturers, and contract manufacturing organizations with aseptic fill-finish capabilities. Dominant competitive moves include strategic partnerships between device developers and drug delivery platforms, plus geographic expansion of ambulatory surgical center networks.
Within the biopharmaceutical developer tier, Regeneron Pharmaceuticals Inc. and AbbVie Inc. exemplify vertically integrated antibody platform strategies. Alcon Inc. occupies a position as the surgical instrument archetype. Among Japan-based developers, Santen Pharmaceutical Co. Ltd. represents the regional specialist model. Novartis AG and F. Hoffmann-La Roche AG sit within the diversified multinational tier with ophthalmology as one therapeutic vertical among broader portfolios.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals Inc |
| Alcon Inc. |
| Novartis AG |
| Santen Pharmaceutical Co. Ltd. |
| Bausch Health Companies Inc. |
| F. Hoffmann-La Roche AG |
| Merck & Co. Inc. |
| Second Sight Medical Products Inc. |
| AbbVie Inc |
| Others |
Supply & Pricing Matrix
Aseptic fill-finish capacity concentrated in Switzerland and Ireland anchors margin capture downstream, with contract manufacturers commanding premium pricing for anti-VEGF active pharmaceutical ingredients while specialty eye hospitals and ambulatory surgical centers compete for procedure-drug bundling economics.
Pricing Analysis
Certification level creates the primary spread across the pricing landscape, with FDA BLA-approved biologics commanding substantial premiums over EMA MDR-certified alternatives and emerging biosimilar formulations. Three-tier pricing structure separates originator anti-VEGF antibodies from licensed biosimilars and unbranded commodity alternatives. Cost compression in the biosimilar tier is intensifying because of CDSCO accelerated approvals in India and emerging market manufacturing scale. Ambulatory surgical centers exhibit the highest price sensitivity due to site-of-service reimbursement differentials, while specialty eye hospitals in Japan and Germany demonstrate lower elasticity tied to volume commitment contracts.
Supply Chain Analysis
Extended payment terms from large hospital procurement consortia are reshaping working capital requirements for device manufacturers and biologics suppliers throughout the value chain. Bulk biologics production clusters in Switzerland, Ireland, and Japan, drawing from recombinant cell culture media, single-use bioreactor systems, and specialized cold-chain logistics infrastructure. Single-source vulnerability for anti-VEGF active pharmaceutical ingredients represents the dominant structural risk, with fill-finish capacity constraints creating supply elasticity limitations. Distribution runs through specialty group purchasing organizations in the United States and hospital procurement consortia in Germany, bypassing traditional wholesale channels for high-volume anti-VEGF transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy platforms pose a credible substitution threat to chronic anti-VEGF administration, requiring incumbents to defend recurring revenue streams against one-time curative modalities while navigating sustained-release device migration.
For Market Incumbents: Build regulatory data exclusivity moats through FDA breakthrough therapy designations and EMA PRIME eligibility for geographic atrophy candidates. Secure backward integration into aseptic fill-finish capacity in Switzerland or Ireland to reduce single-source vulnerability for active pharmaceutical ingredients. Channel control through vertically integrated retina practice management platforms offers defensive positioning against biosimilar price erosion. For New Entrants and Emerging Players: Mid-market ophthalmic clinics in India and Southeast Asia represent the most penetrable entry point for biosimilar anti-VEGF formulations and diagnostic imaging systems. Geographic atrophy therapies under PMDA Sakigake review in Japan offer accelerated regulatory pathways for complement pathway inhibitors. Direct contracting with ambulatory surgical center networks bypasses entrenched hospital procurement relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed ambulatory surgical center rollups in the United States seeking drug-device bundling capabilities. Long-term viability over the analysis window favors platforms with sustained-release implant pipelines and gene therapy manufacturing infrastructure. Watch FDA gene therapy approval velocity as the inflection indicator for portfolio reallocation away from chronic administration models.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough designation compresses timelines for geographic atrophy candidates. |
| Manufacturing Scale-Up | Aseptic fill-finish expansion in Switzerland addresses single-source API vulnerability. |
| Hospital System Partnership | Vertically integrated retina platforms extract price concessions through volume commitments. |
| Pipeline Diversification | Gene therapy candidates offset substitution risk to chronic anti-VEGF administration. |
| Reimbursement Strategy | Site-of-service differentials favor ambulatory surgical center channel migration. |
Research Methodology
A standing panel of retinal specialists, hospital procurement directors, regulatory affairs leads, and payer access specialists provided ongoing calibration for demand assumptions and treatment protocol evolution. Primary interviews with formulary directors at United States specialty eye hospitals and group purchasing organization contract managers were cross-referenced against FDA BLA filings, EMA MDR submission databases, ClinicalTrials.gov protocols, and CMS Medicare reimbursement schedules. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation validated segmentation outputs across disorder type and treatment modality dimensions.
Scenario-bracketing framed the analytical approach, with demand trajectories tested against alternative sustained-release adoption curves and gene therapy penetration assumptions throughout the projection horizon. Segmentation dimensions modeled encompass disorder type, treatment modality, product type, and end-user channel, with regional regulatory clusters capturing FDA, EMA, PMDA, and CDSCO pathway differentiation. CAGRs were derived from treatment intensity projections per capita and clinic capacity expansion rates, incorporating optical coherence tomography screening penetration and intravitreal injection frequency compression as industry-specific inputs.
Practitioners should monitor biosimilar approval velocity, sustained-release implant reimbursement thresholds, and vitreoretinal surgeon fellowship pipeline expansion for early signals of forecast deviation. Assumptions underlying patient volume, pricing, and adoption curve projections reflect stated regulatory and clinical parameters. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Lasers Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Laser Indirect Ophthalmoscope Market
Ophthalmology
Global Artificial Tear Market
Ophthalmology
Vision Care Market
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
Global Ophthalmology Drugs and Devices Market
Ophthalmology
Macular Edema Market
Ophthalmology
Global Optic Nerve Disorders Treatment Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
Europe Dry Eye Syndrome Market