
 Europe Digital Health Market | 2026-2036
Europe Digital Health Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Health Market Intelligence
European software development capacity is pivoting toward clinical-grade digital therapeutics as regulatory clarity improves. MindMaze leverages neuroscience-driven rehabilitation platforms to dominate stroke recovery segments. Liva Healthcare sustains behavioral-change coaching models that anchor diabetes prevention contracts with NHS England and Scandinavian payers. Kaia Health competes in musculoskeletal digital therapy with computer-vision motion tracking that reduces physiotherapy costs for German insurers.
Europe Digital Health encompasses software, connected hardware, and data infrastructure designed to deliver, manage, or augment medical care outside traditional facility settings, typically integrating ISO 27001-certified cloud architectures with CE-marked diagnostic algorithms to ensure patient safety and data interoperability across national health systems. Telemedicine platforms occupy the largest revenue pool as legacy providers digitize appointment workflows, while artificial intelligence segments represent the fastest structural expansion as radiology and pathology workflows automate pattern recognition. Wearable Devices concentrates margin capture among diabetes and cardiac monitoring applications where continuous glucose monitors and ECG-enabled watches generate recurring data subscriptions.
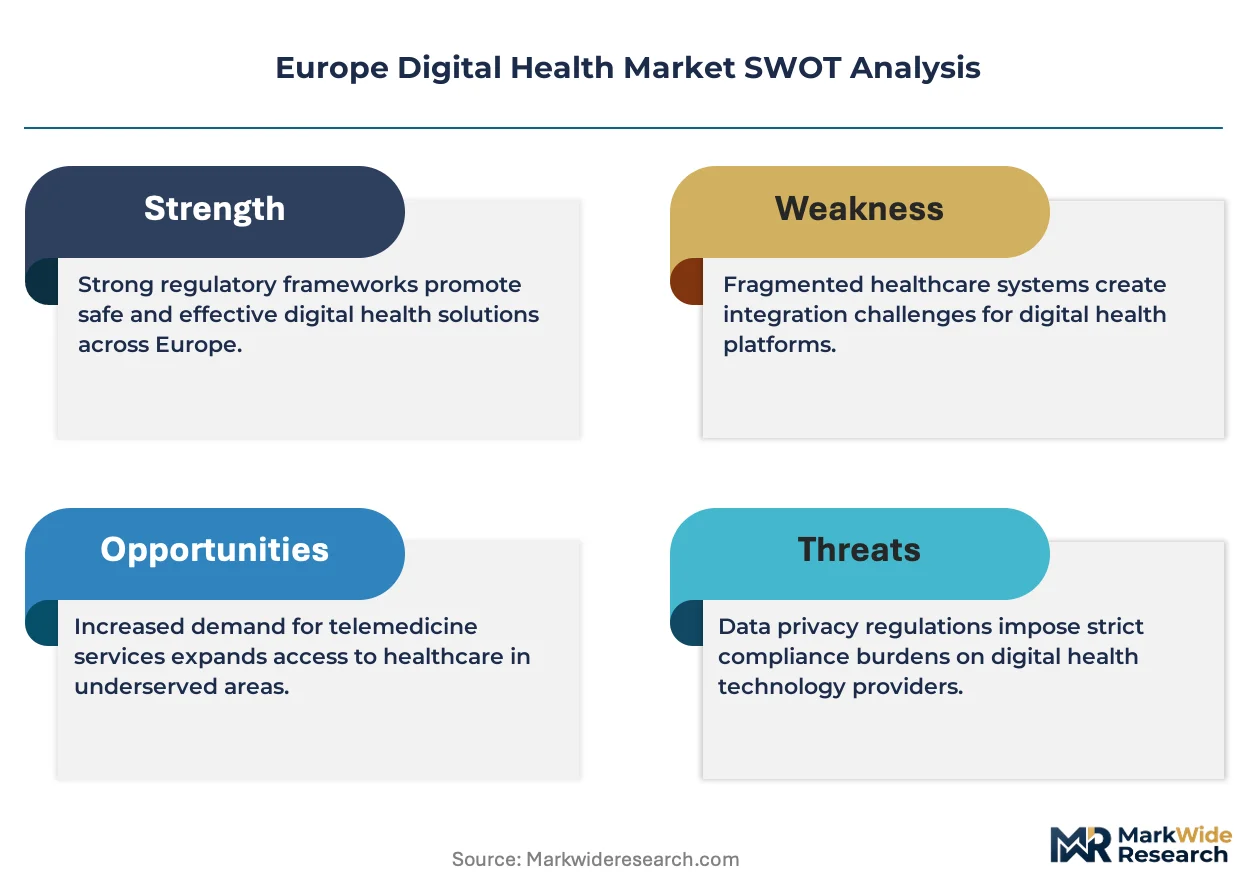
EMA medical device guidance, GDPR health data provisions, and the EU AI Act risk-classification framework collectively determine market access timelines and development costs for algorithm-based diagnostic products sold across member states. The CSRD sustainability reporting mandate further shapes procurement criteria for hospital systems evaluating vendor environmental footprints. Stakeholders must monitor how national reimbursement authorities in France, Germany, and the Netherlands calibrate tariff codes for remote monitoring services versus traditional in-person care.
Market Dynamics
The EU AI Act risk-classification framework is forcing algorithm developers to restructure clinical validation pipelines before CE marking, compressing timelines for diagnostic software deployment across member states.
Growth Catalysts
- Telehealth Reimbursement Expansion:France's chronic disease management sector now covers remote consultations under national tariff codes, accelerating patient enrollment in digital monitoring programs.
- GDPR-Compliant Cloud Infrastructure:ISO 27001-certified health data architectures enable cross-border patient record sharing between German hospital systems and Scandinavian primary care networks.
- Stroke Rehabilitation Demand:Neuroscience-driven motor recovery platforms are displacing traditional physiotherapy in Netherlands rehabilitation centers, reducing facility dependency for post-acute care.
Market Restraints
- EMA Medical Device Guidance Complexity:Algorithm-based diagnostic tools face extended conformity assessment timelines, delaying market entry for software-as-medical-device products.
- Interoperability Fragmentation:National health information exchange standards vary between Germany's gematik framework and France's Health Data Hub specifications, complicating multi-market deployment.
- Workforce Digital Literacy Gaps:Rural primary care physicians in Italy and Spain lack structured training for interpreting AI-augmented diagnostic outputs, limiting adoption velocity.
Strategic Opportunities
- CSRD-Driven Procurement Mandates:Hospital systems in the Netherlands now evaluate vendor environmental footprints alongside clinical efficacy, creating differentiation for sustainability-certified platforms.
- Musculoskeletal Digital Therapy:Computer-vision motion tracking for physiotherapy substitution remains underpenetrated in Poland and Czech Republic occupational health markets.
- Continuous Glucose Monitor Integration:ECG-enabled wearables and diabetes monitoring hardware convergence creates bundled reimbursement opportunities with German statutory health insurers.
Industry Challenges
- CE Marking Documentation Burden:Software lifecycle processes under MDR Annex XI require extensive clinical evidence generation, straining mid-cap developer resources.
- Legacy EHR Integration Complexity:Hospital IT departments face protracted API harmonization efforts when connecting third-party diagnostic algorithms to existing patient record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Health Market |
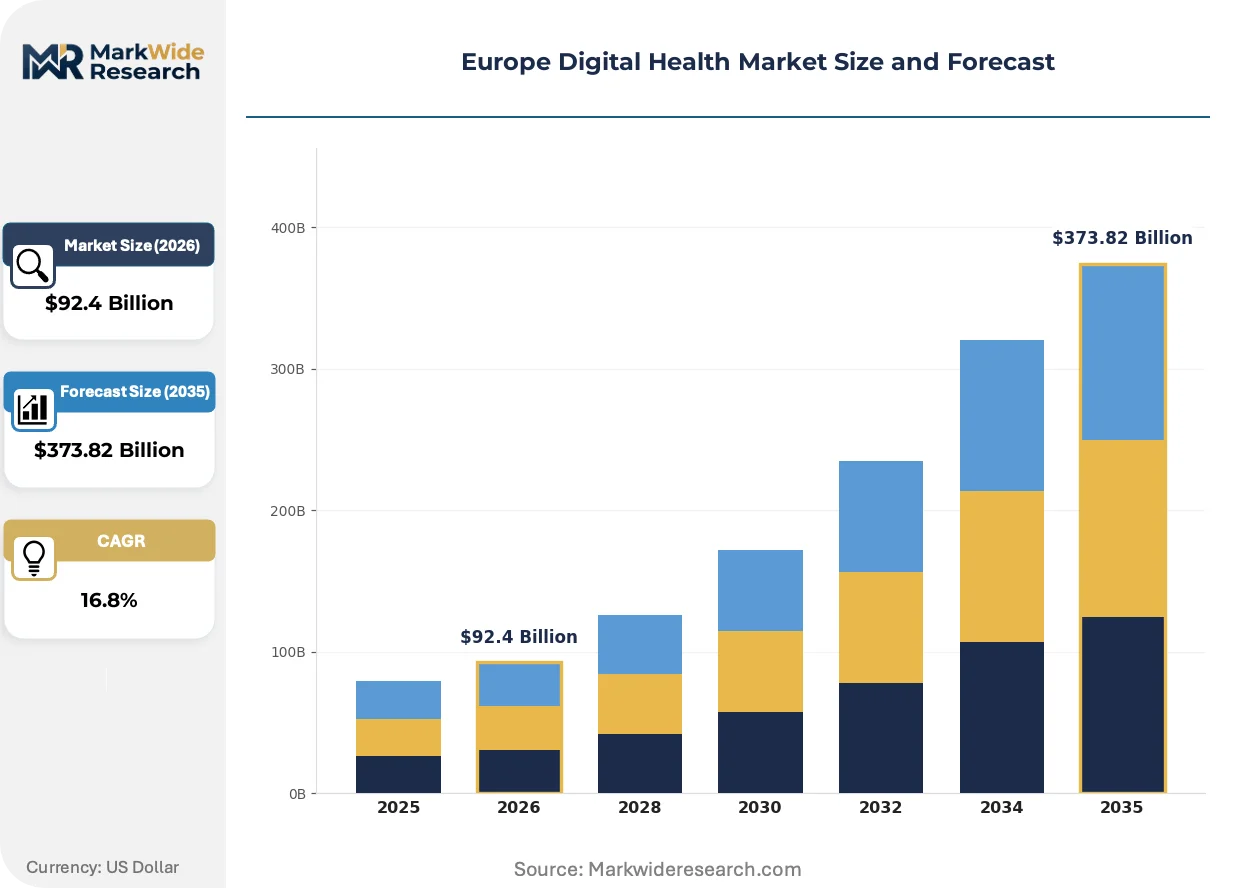
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $373.82 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telemedicine, Wearable Devices, Health Apps, Remote Monitoring End User: Patients, Healthcare Providers, Insurance Companies, Pharmaceuticals Technology: Cloud Computing, Artificial Intelligence, Blockchain, Mobile Health Application: Chronic Disease Management, Telehealth Services, Mental Health Solutions, Wellness Programs |
| Companies Covered | MindMaze, Liva Healthcare, Kaia Health, Natera, Neko Health, Hinge Health, Icometrix, Flatiron Health, Sword Health, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Health Market Strategic Shifts & Innovations
Clinical-grade digital therapeutics are displacing conventional pharmaceutical adjuncts as payers seek measurable outcome guarantees. Regulatory clarity around algorithmic medical devices is accelerating investment in neuroscience and behavioral health platforms.
Edge computing for real-time patient monitoring is modularizing hospital-at-home infrastructure. German insurers are piloting distributed sensor networks that process cardiac and respiratory data locally before cloud transmission. This architecture reduces latency for acute event detection while satisfying GDPR data residency requirements, enabling scaled deployment outside traditional facility settings.
The EU AI Act high-risk system obligations are reshaping clinical validation requirements. Developers must now maintain post-market surveillance systems and algorithmic change control protocols. Radiology and pathology automation segments face the steepest compliance investments, with several platforms restructuring quality management systems to accommodate notified body oversight.
Hospital procurement committees are consolidating vendor relationships around integrated platform providers. French and German acute care networks now favor single-source contracts spanning telemedicine, remote monitoring, and AI-augmented diagnostics over point solutions. This concentration rewards vendors with broad regulatory clearances and punishes narrow specialists lacking cross-functional certification portfolios.
Europe Digital Health Market Segmentation
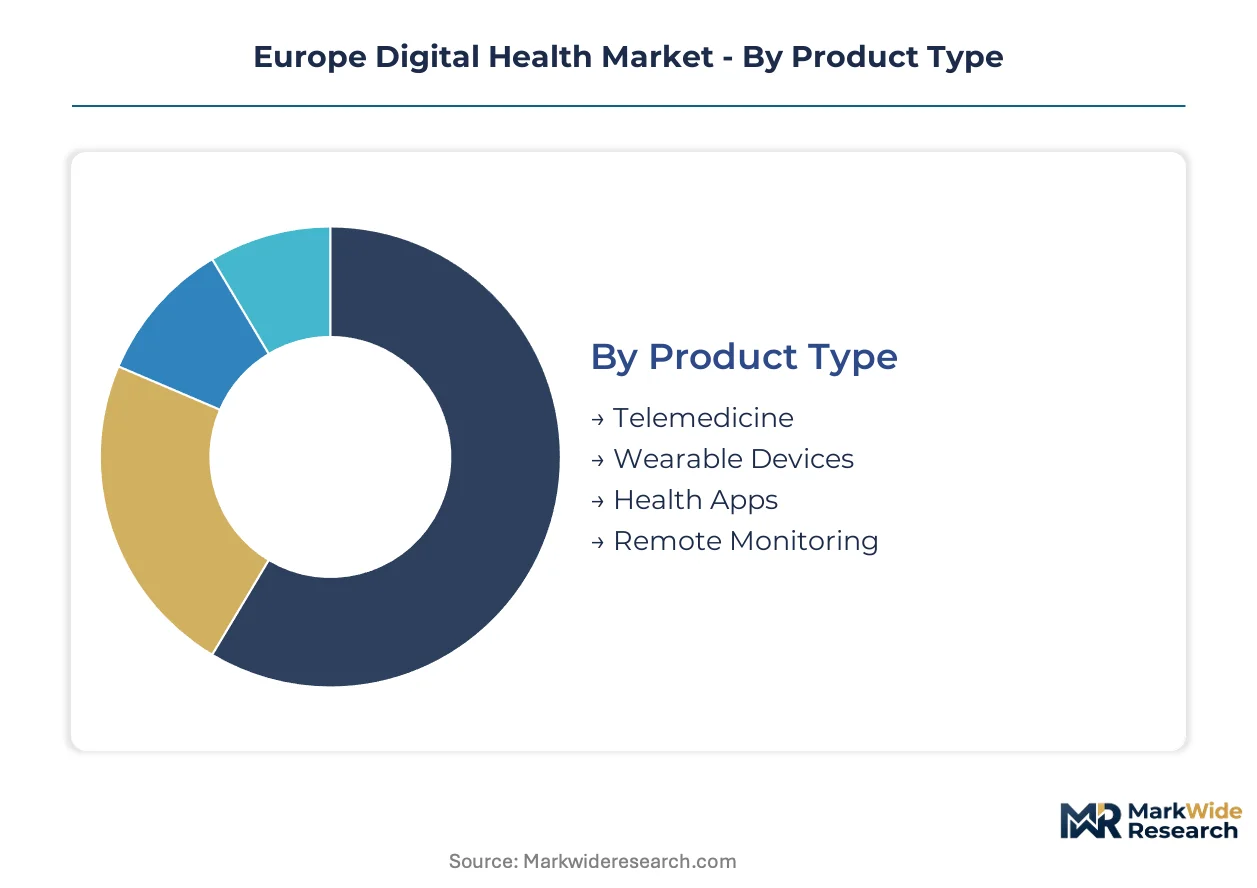
European health systems fragment procurement decisions across national reimbursement authorities, hospital IT departments, and payer consortiums. Segment boundaries reflect these divergent buying logics rather than uniform technical specifications. Vendors must architect go-to-market strategies that align with each stakeholder's distinct compliance and outcome requirements.
Product Type:
Cost tier separates enterprise-grade clinical platforms from consumer wellness tools in European procurement evaluations.
- Telemedicine:Real-time video consultation platforms integrate with national health record systems through HL7 FHIR protocols. French and German hospital networks prioritize solutions that embed directly into existing EHR workflows rather than standalone interfaces.
- Wearable Devices:Continuous glucose monitors and ECG-enabled watches generate recurring data subscriptions through ISO 27001-certified cloud backends. German statutory health insurers now bundle diabetes hardware with remote monitoring tariffs, accelerating patient enrollment.
- Health Apps:Prescription digital therapeutics face CE marking under MDR Class IIa requirements for behavioral health and chronic condition management.
- Remote Monitoring:Hospital-at-home platforms combine biometric sensors with clinical decision support for post-acute care substitution.
Volume sits with Telemedicine; growth tilts toward Wearable Devices.
End User:
Application maturity determines whether buyers prioritize regulatory clearance or user experience metrics.
- Patients:Direct-to-consumer chronic disease apps face GDPR consent complexity and national reimbursement fragmentation across France, Germany, and Netherlands markets.
- Healthcare Providers:Hospital IT departments demand ISO 27001-certified architectures with seamless EHR integration and algorithmic audit trails under EU AI Act obligations.
- Insurance Companies:German and Scandinavian payers contract for outcome-based digital therapeutics, tying reimbursement to measurable HbA1c reduction or stroke recovery velocity.
- Pharmaceuticals:Drug manufacturers acquire digital companion platforms to extend patent protection and differentiate in crowded therapeutic categories.
Revenue concentrates with Healthcare Providers; expansion accelerates fastest among Insurance Companies.
Technology:
Margin capture diverges between infrastructure commoditization and proprietary algorithm development.
- Cloud Computing:GDPR-compliant health data architectures enable cross-border patient record sharing between German hospital systems and Scandinavian primary care networks.
- Artificial Intelligence:Radiology and pathology automation segments face steepest EU AI Act compliance investments, with platforms restructuring quality management systems for notified body oversight.
- Blockchain:Distributed ledger applications for pharmaceutical supply chain traceability remain pilot-phase across EMA-regulated markets.
- Mobile Health:Smartphone-native platforms dominate patient-facing chronic disease management in France's expanded telehealth reimbursement environment.
Deployment volume favors Cloud Computing; value creation shifts toward Artificial Intelligence.
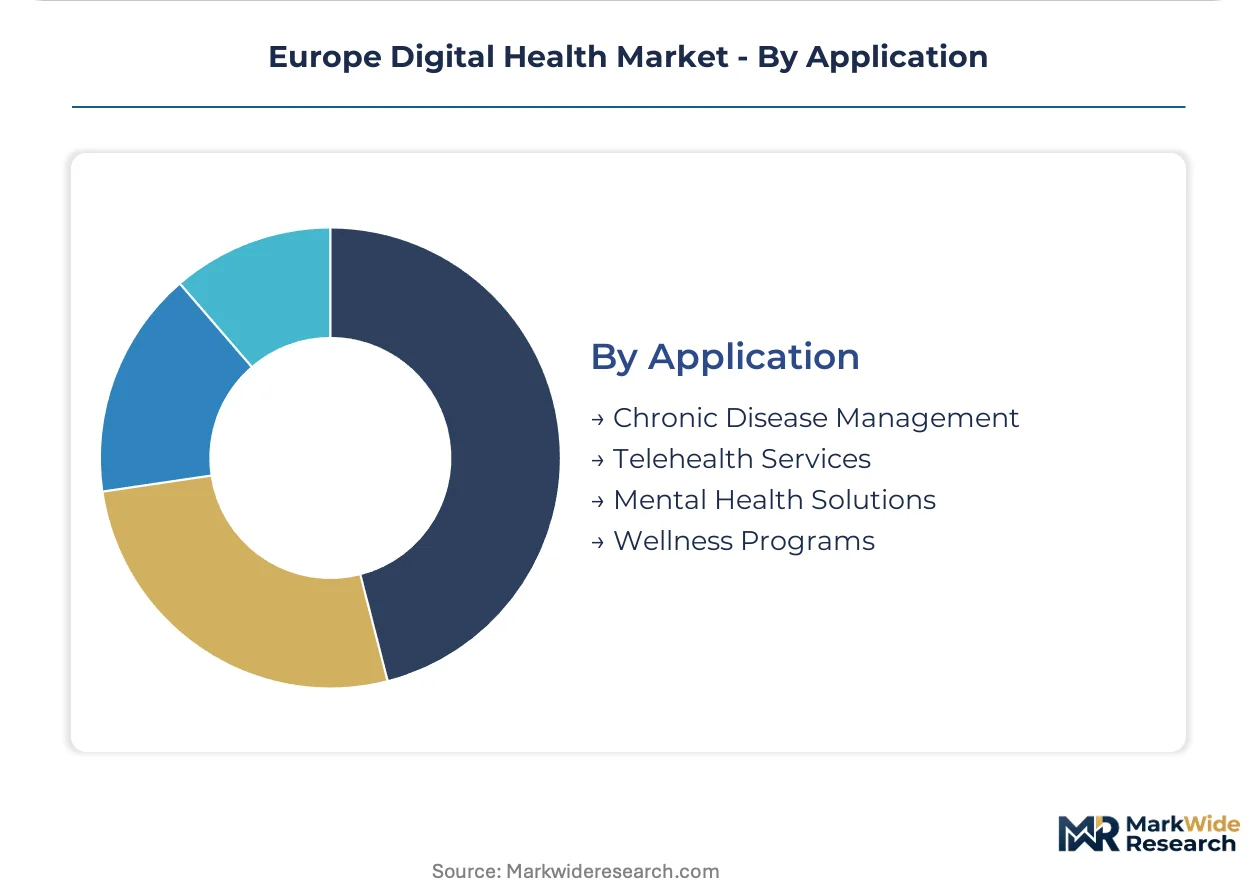
Application:
Customer type splits between acute care substitution and longitudinal prevention models.
- Chronic Disease Management:Diabetes and cardiovascular platforms integrate continuous monitoring with automated insulin dosing and clinical escalation protocols.
- Telehealth Services:Remote consultation platforms occupy the largest revenue pool as legacy providers digitize appointment workflows across French and German primary care networks.
- Mental Health Solutions:Cognitive behavioral therapy apps face ANSM and BfArM scrutiny for clinical evidence standards before national reimbursement inclusion.
- Wellness Programs:Employer-sponsored prevention contracts concentrate in Netherlands and UK occupational health markets with CSRD-aligned sustainability reporting.
Current spend concentrates in Telehealth Services; structural expansion is steepest in Chronic Disease Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investments in Frankfurt and Amsterdam anchor European health data processing capacity. GDPR-compliant data residency requirements concentrate platform development in these metropolitan clusters. National reimbursement frameworks fragment deployment timelines across member states.
Germany
German statutory health insurers bundle diabetes hardware with remote monitoring tariffs, accelerating patient enrollment in continuous glucose programs. The BfArM medical device regulator enforces MDR Annex XI documentation standards for algorithm-based diagnostics. Berlin's hospital networks consolidate vendor relationships around integrated telemedicine and AI-augmented diagnostic platforms.
France
France's chronic disease management sector covers remote consultations under national tariff codes, expanding digital monitoring access. ANSM and CNIL jointly scrutinize clinical evidence standards for prescription digital therapeutics before reimbursement inclusion. Paris acute care networks favor single-source contracts spanning telemedicine and remote patient monitoring over fragmented point solutions.
United Kingdom
NHS England contracts for outcome-based digital therapeutics, tying reimbursement to measurable HbA1c reduction and stroke recovery velocity. The MHRA aligns software-as-medical-device guidance with EU MDR frameworks post-Brexit. London-based behavioral health platforms anchor diabetes prevention contracts with Scandinavian payer consortiums.
Netherlands
Dutch rehabilitation centers displace traditional physiotherapy with neuroscience-driven motor recovery platforms for post-acute stroke care. The national health information exchange framework complicates multi-market deployment against Germany's gematik specifications. Eindhoven hospital systems evaluate vendor environmental footprints under CSRD procurement mandates alongside clinical efficacy metrics.
Sweden
Scandinavian primary care networks share cross-border patient records through ISO 27001-certified cloud architectures connected to German hospital systems. Sweden's national reimbursement authority calibrates remote monitoring tariffs against traditional in-person care benchmarks. Stockholm's occupational health markets concentrate employer-sponsored prevention contracts with sustainability-aligned wellness program providers.
Europe Digital Health Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue CE-marked algorithmic diagnostics and behavioral health platforms. The vendor base stratifies between integrated platform providers with broad regulatory clearances and narrow specialists lacking cross-functional certification portfolios. Neuroscience rehabilitation platforms, behavioral-change coaching models, and computer-vision motion tracking specialists represent three dominant strategic archetypes. Competitive moves concentrate on M&A consolidation for regulatory portfolio expansion and strategic partnerships for EHR integration capabilities.
Within the integrated platform tier, MindMaze and Liva Healthcare exemplify archetype positioning through neuroscience-driven and behavioral health specializations respectively. Kaia Health occupies a position among computer-vision motion tracking specialists targeting musculoskeletal therapy substitution. These three entities represent the competitive anchor points visible in current market configuration.
| Leading Market Players |
|---|
| MindMaze |
| Liva Healthcare |
| Kaia Health |
| Natera |
| Neko Health |
| Hinge Health |
| Icometrix |
| Flatiron Health |
| Sword Health |
| Others |
Cost & Logistics Intelligence
CSRD sustainability reporting mandates gate qualified supply and premium-tier pricing access for European digital health vendors, as hospital procurement committees in the Netherlands and Germany now evaluate environmental footprints alongside clinical efficacy metrics. This dual-filter compresses margins for uncertified developers while rewarding integrated platform providers with cross-functional regulatory clearances.
Pricing Analysis
Service-bundling separates enterprise-grade clinical platforms with embedded ISO 27001-certified cloud architectures and post-market surveillance from unbundled point solutions lacking algorithmic audit trails. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking tier and EHR integration depth, with German statutory health insurers driving cost compression in diabetes hardware bundles. Pricing pressure stems from NHS England outcome-based contracts tying reimbursement to measurable HbA1c reduction. Small-to-mid cap developers exhibit highest price sensitivity due to MDR Annex XI documentation burdens.
Supply Chain Analysis
Workforce availability constraints in Irish and Estonian software development clusters limit algorithm validation pipeline capacity for EU AI Act compliance. Cloud infrastructure concentrates in Frankfurt and Amsterdam data centers, with edge computing hardware sourcing from Taiwan and South Korean semiconductor foundries. Single-source vulnerability sits with notified body capacity for CE marking assessments. Distribution runs through hospital IT procurement committees and national reimbursement authorities rather than direct vendor-to-clinic sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical-grade digital therapeutics are displacing conventional pharmaceutical adjuncts as algorithmic medical devices replace legacy appointment workflows across French and German hospital networks.
For Market Incumbents: Lock in EHR integration capabilities through API harmonization investments that embed telemedicine and remote monitoring directly into existing patient record architectures. Consolidate regulatory portfolios via M&A targeting narrow specialists lacking cross-functional certification, defending against emerging computer-vision motion tracking entrants in musculoskeletal therapy substitution. Prioritize backward integration into ISO 27001-certified cloud infrastructure to control data residency compliance costs. For New Entrants and Emerging Players: Rural primary care physicians in Italy and Spain represent an underserved buyer archetype lacking structured training for AI-augmented diagnostic outputs. Poland and Czech Republic occupational health markets offer white-space penetration for physiotherapy substitution platforms with lower CE marking documentation requirements than core EU markets. Pursue strategic partnerships with Scandinavian payer consortiums for outcome-based contracting credibility. For Investors and Strategic Acquirers: BfArM and ANSM reimbursement tariff expansions for remote monitoring services are the leading indicator that algorithm-based diagnostic platforms will achieve sustainable revenue velocity. Long-term viability centers on vendors with post-market surveillance systems and algorithmic change control protocols under EU AI Act high-risk obligations. Target acquisition profiles emphasize neuroscience rehabilitation platforms with proven stroke recovery metrics and behavioral health coaching models anchored to NHS England contracts.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Annex XI compliance unlocks cross-border market access across German and French hospital networks. |
| Hospital System Partnership | Single-source contracts with Paris acute care networks consolidate vendor relationships against point solution competitors. |
| Software Companion Development | Digital therapeutics integration extends pharmaceutical patent protection in crowded diabetes therapeutic categories. |
| Reimbursement Strategy | Alignment with France's national tariff codes for chronic disease management accelerates patient enrollment velocity. |
| Platform Integration | HL7 FHIR protocol embedding enables seamless workflow integration with gematik and Health Data Hub specifications. |
Research Approach
Multi-period observation of telehealth reimbursement tariff expansions, CE marking approval timelines, and algorithmic diagnostic deployment rates anchored the trend analysis, supplemented by interviews with hospital IT procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from EMA medical device guidance documents, EU AI Act implementation texts, national health information exchange specifications, and hospital procurement databases. Bottom-up vendor revenue estimates triangulated against top-down payer spending analysis.
Input-output matrices modeled deployment volume and value creation across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs derived from regression analysis of historical adoption curves calibrated to reimbursement policy inflection points. Forecast inputs incorporated EU AI Act risk-classification compliance cost trajectories and CSRD procurement mandate diffusion rates across member states.
Revisions become necessary when EMA guidance updates, GDPR enforcement actions, or notified body capacity constraints materialize outside baseline assumptions. Material deviation in reimbursement tariff calibration or algorithmic audit requirement stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
Patient Engagement Technology Market
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
Mobile Tablets in Healthcare Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
North America Digital Health Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Mixed Reality in Healthcare Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
Connected Health and Wellness Solutions Market