
 Connected Health and Wellness Solutions Market | 2026-2036
Connected Health and Wellness Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Health and Wellness Solutions Market Intelligence
South Korea is reshaping connected health manufacturing through government-backed smart hospital clusters in Songdo and Daegu. Apple leverages its watchOS health sensor stack to dominate consumer-grade cardiac monitoring. Abbott anchors the prescription wearable segment with its glucose-sensing platform for diabetes management. Medtronic competes through deep integration with health system electronic records across North American hospital networks.
Connected health and wellness solutions encompass networked hardware, software platforms, and data services that capture, transmit, and analyze physiological and behavioral metrics for clinical or consumer health management. These systems typically operate through FDA-cleared Class II medical devices with Bluetooth Low Energy or cellular connectivity, cloud-based data lakes, and algorithmic triage engines that flag anomalies for clinician review. Wearable Devices and Telehealth Platforms represent the most mature revenue pools, while Artificial Intelligence and Blockchain segments within the technology dimension attract the fastest venture allocation due to diagnostic automation and interoperability security demands. Healthcare Providers remain the dominant end-user category for enterprise contract value, though Patients represent the highest-volume addressable base through direct-to-consumer subscription models.
FDA premarket clearance pathways and CMS reimbursement codes determine viable commercialization timelines for connected diagnostic devices in the United States. The EU Medical Device Regulation and GDPR compliance requirements shape product architecture decisions for vendors targeting European health systems. Stakeholders must monitor evolving FDA software-as-a-medical-device guidance and state-level telehealth licensing reciprocity agreements to anticipate market access shifts.
Market Dynamics
Hospital procurement committees now mandate cloud-native RPM platforms with embedded AI triage, forcing legacy device vendors to re-architect around interoperability standards rather than proprietary data lakes.
Growth Catalysts
- CMS reimbursement expansion:New CPT codes for remote therapeutic monitoring accelerate hospital system deployment of continuous glucose monitors and pulse oximetry arrays.
- Germany's DiGA fast-track:Statutory health insurers now reimburse prescribed digital therapeutics within 90 days of BfArM listing, creating predictable revenue streams for connected care software.
- Bluetooth Low Energy 5.3:Extended range and reduced power consumption enable patch-based cardiac monitors to transmit through residential walls without smartphone tethering.
Market Restraints
- Semiconductor supply concentration:FDA-cleared medical devices depend on TSMC-fabricated ASICs for biometric signal processing, exposing vendors to foundry allocation volatility.
- GDPR data localization:EU patient data residency requirements force redundant cloud infrastructure deployments, raising operational costs for US-based platform vendors.
- Lithium-polymer cell chemistry:Wearable device battery life remains constrained by energy density limits, requiring trade-offs between sensor sampling frequency and form factor.
Strategic Opportunities
- India's Ayushman Bharat Digital Mission:The health stack's open API architecture invites foreign connected health vendors to integrate with the national ABHA identifier system.
- Continuous blood pressure monitoring:Optical sensor fusion with PPG and bioimpedance is displacing cuff-based devices in hypertension management protocols.
- Direct-to-employer channels:Fortune 500 self-insured plans bypass traditional payers to contract directly with chronic disease management platforms.
Industry Challenges
- FDA 510(k) software documentation:Algorithm update cycles for machine learning-enabled diagnostics trigger recurring premarket submissions, compressing R&D velocity.
- Health system EHR integration:HL7 FHIR implementation varies across Epic, Cerner, and Meditech deployments, requiring bespoke middleware development for each hospital network.
- Cybersecurity certification lag:UL 2900-2-1 testing timelines extend commercialization by 4-6 months for wireless medical devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Health and Wellness Solutions Market |
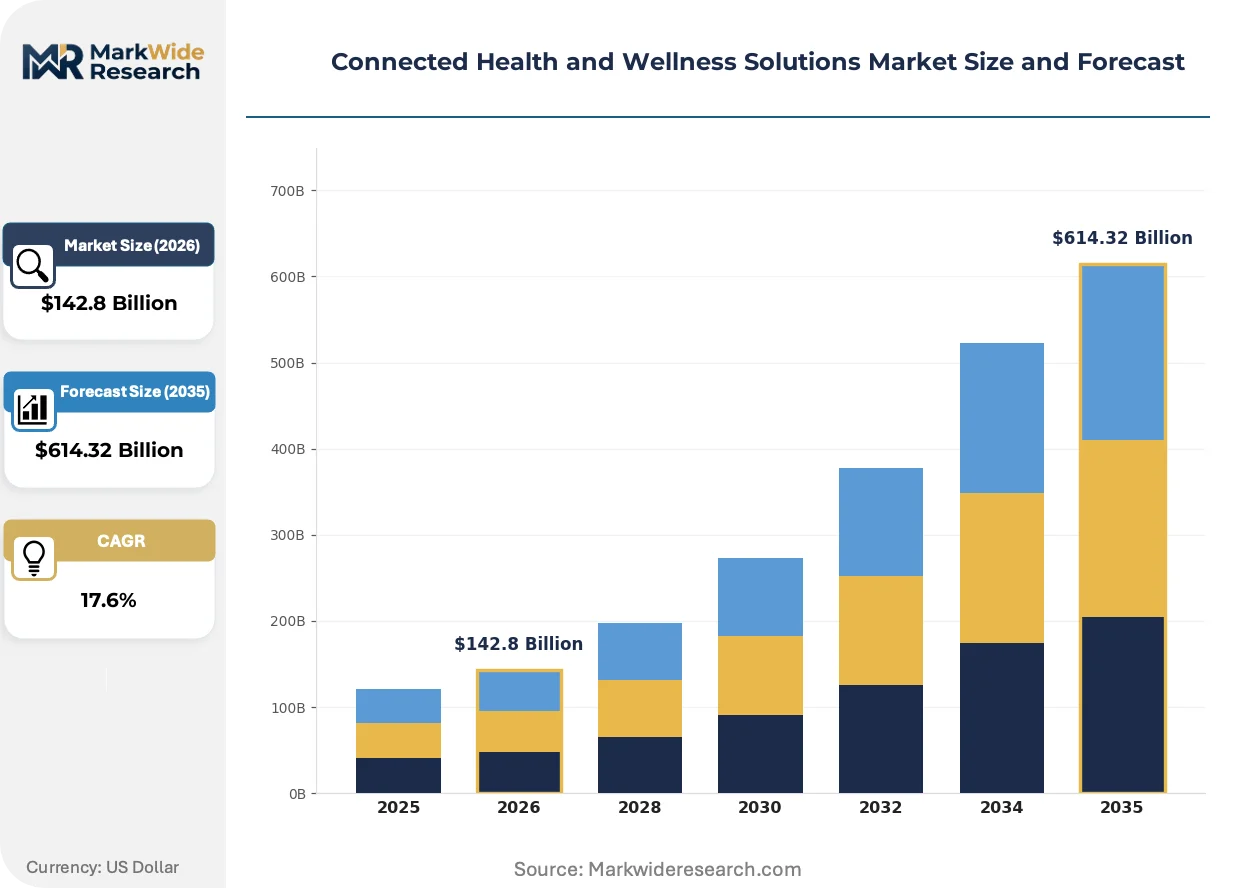
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $614.32 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Telehealth Platforms, Remote Monitoring Systems End User: Healthcare Providers, Patients, Corporates, Insurance Companies Technology: IoT Solutions, Artificial Intelligence, Blockchain, Cloud Computing Service Type: Consultation Services, Data Analytics, Support Services, Integration Services |
| Companies Covered | Apple, Abbott, Fitbit, Medtronic, Koninklijke Philips N.V., GE Healthcare, Omron Healthcare, Dexcom, Garmin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Health and Wellness Solutions Market Strategic Shifts & Innovations
Digital twin architectures and edge computing are compressing the latency between physiological signal capture and clinical intervention, redefining real-time care delivery boundaries.
Edge inference chips from Qualcomm and Ambiq are virtualizing arrhythmia detection directly on wearable devices, eliminating round-trip cloud latency for critical cardiac events. Cardiology departments at Cleveland Clinic and Mayo Clinic pilot these systems for post-discharge monitoring. The shift is virtualizing the traditional Holter monitor rental model into disposable patch economics.
The EU Medical Device Regulation's 2024 guidance on software-as-a-medical-device requires algorithm change control plans for AI-enabled diagnostics. Vendors targeting European health systems must document training data provenance and performance drift monitoring. Germany's notified bodies now prioritize MDR audits for continuous glucose monitoring platforms with predictive hypoglycemia alerts.
Employer-sponsored wellness programs now unbundle hardware subsidies from subscription fees, letting employees retain devices post-employment. This consumption-pattern shift pressures vendors to develop consumer-grade revenue streams independent of B2B contracts. The model is most visible among self-insured technology firms in California and Washington state.
Connected Health and Wellness Solutions Market Segmentation
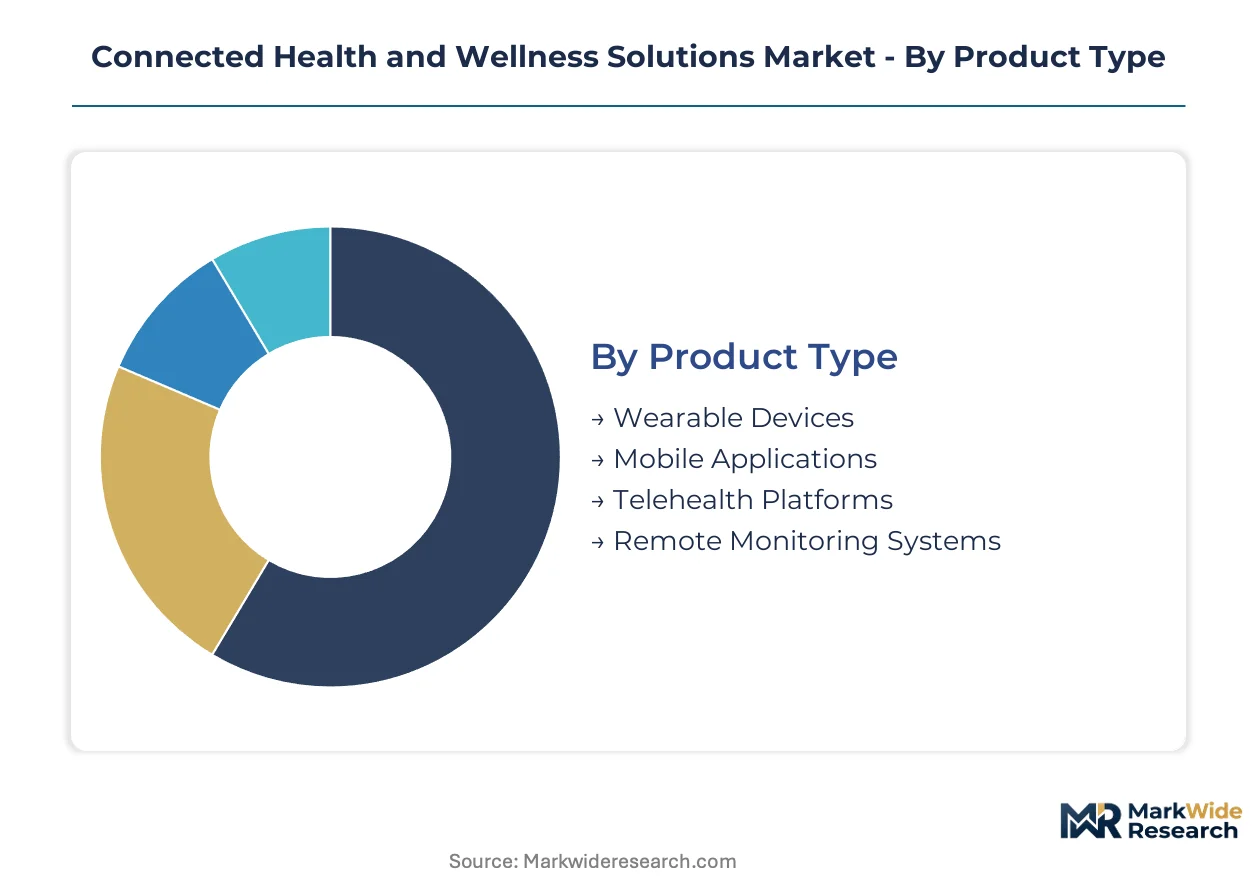
Segmentation in connected health reveals divergent commercial models across hardware, software, and service layers. Procurement patterns differ sharply between hospital system contracts and direct-to-consumer subscriptions. Technology architecture choices determine regulatory pathway complexity and margin structure.
Product Type:
The use-case spectrum spans acute clinical monitoring through preventive wellness tracking, with form factor and connectivity specifications varying by intervention intensity.
- Wearable Devices:FDA-cleared Class II sensors with Bluetooth Low Energy or cellular modems capture continuous cardiac, glucose, or oxygen saturation data. Hospital systems in Germany and the United States concentrate procurement for post-discharge monitoring programs, driven by expanded CMS reimbursement codes for remote physiological monitoring.
- Telehealth Platforms:Cloud-native video consultation infrastructure with embedded EHR integration and AI triage engines. Healthcare providers in South Korea and India accelerate deployment following national digital health stack initiatives, constrained by state-level licensing reciprocity fragmentation in the United States.
- Mobile Applications:Smartphone-based symptom tracking and medication adherence tools with varying clinical validation levels.
- Remote Monitoring Systems:Hub-and-spoke architectures connecting multiple biometric devices to centralized clinician dashboards.
Established volume favors Wearable Devices; emerging adoption favors Telehealth Platforms.
End User:
Customer type determines contract structure, with enterprise sales cycles spanning 12-18 months against consumer acquisition measured in days.
- Healthcare Providers:Hospital networks and physician practices procuring enterprise-grade RPM infrastructure with HL7 FHIR interoperability requirements. Systems in the United States prioritize Epic and Cerner integration, while German providers demand BfArM-compliant digital therapeutic compatibility.
- Patients:Direct-to-consumer purchasers of fitness trackers, continuous glucose monitors, and chronic disease management subscriptions. Subscription retention concentrates in urban populations with employer-sponsored wellness subsidies, limited by device abandonment rates after initial hardware subsidy expiration.
- Corporates:Self-insured employers contracting directly with chronic disease management platforms for workforce health optimization.
- Insurance Companies:Payers integrating connected health data into risk stratification and prior authorization workflows.
Revenue concentration sits with Healthcare Providers; subscriber volume expansion centers on Patients.
Technology:
Architecture maturity ranges from standardized connectivity protocols to experimental trust infrastructure with unproven scale economics.
- IoT Solutions:Sensor networks, edge gateways, and low-power wide-area protocols enabling continuous physiological data transmission. Deployment concentrates in North American hospital-at-home programs and South Korean smart hospital clusters, with Bluetooth 5.3 range extensions reducing smartphone tethering requirements.
- Artificial Intelligence:Machine learning models for arrhythmia detection, predictive hypoglycemia alerting, and clinical decision support. Venture allocation flows fastest to diagnostic automation vendors, constrained by FDA 510(k) resubmission requirements for algorithm updates.
- Cloud Computing:HIPAA and GDPR-compliant data lakes with elastic compute for population health analytics.
- Blockchain:Distributed ledger architectures for patient consent management and interoperability security with limited production deployment.
Commercial traction clusters in IoT Solutions; steepest expansion trajectory appears in Artificial Intelligence.
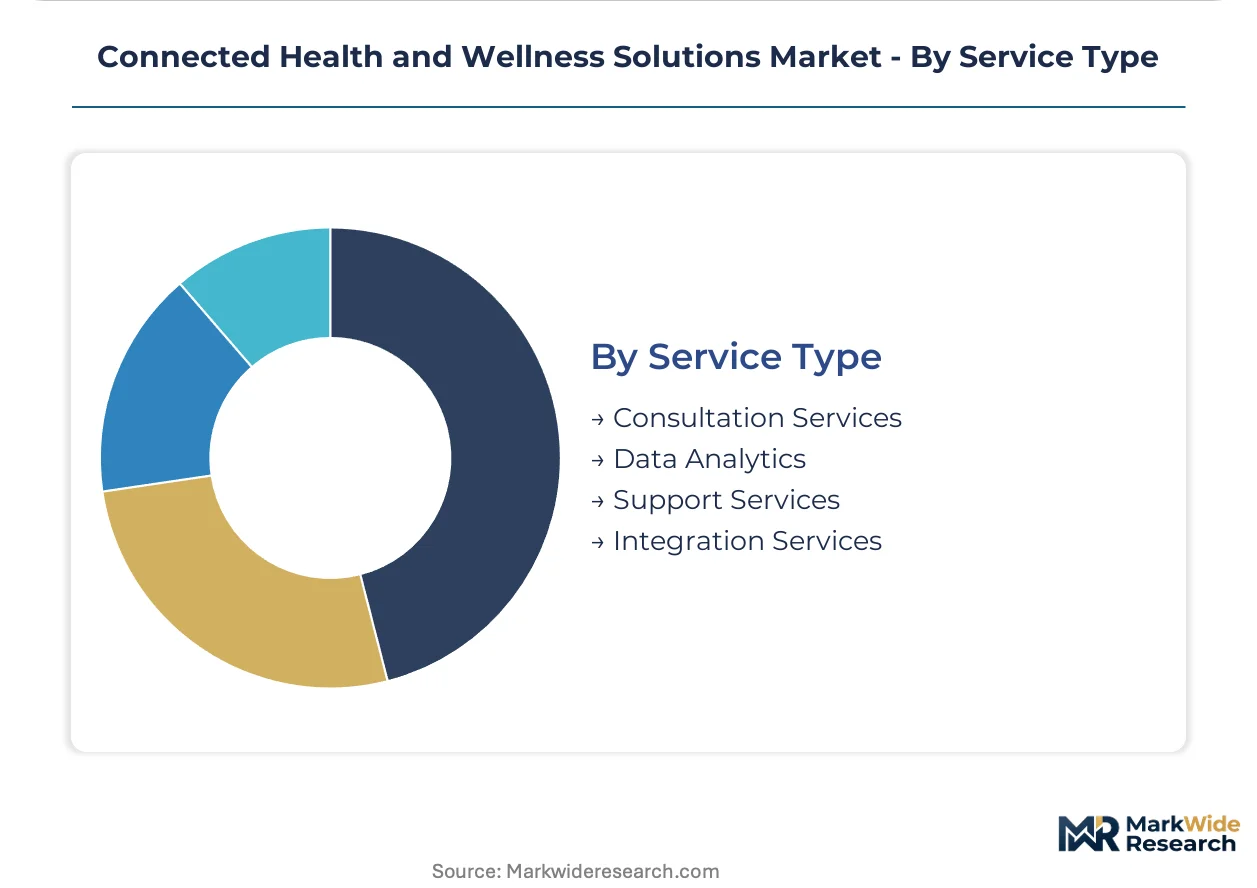
Service Type:
Margin structure differentiates high-touch professional services from scalable software-enabled delivery.
- Data Analytics:Population health insights, predictive risk scoring, and outcomes measurement dashboards delivered through cloud platforms. Demand concentrates among accountable care organizations in the United States and statutory health insurers in Germany, driven by value-based contract reporting requirements.
- Integration Services:Custom middleware development connecting proprietary device data to heterogeneous EHR environments. Health systems with mixed Epic-Cerner-Meditech estates require bespoke implementations, extending deployment timelines and inflating professional services revenue per account.
- Consultation Services:Clinical workflow redesign and remote monitoring protocol development.
- Support Services:Device logistics, patient onboarding, and technical helpdesk operations.
Account profitability favors Integration Services; standardization pressure targets Support Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connected health hardware manufacturing concentrates in South Korea and the United States, while software platform development clusters in Germany and India. Regulatory reimbursement frameworks in these markets determine viable commercialization timelines for vendors.
United States
FDA-cleared remote patient monitoring devices capture CMS reimbursement through expanded CPT codes for continuous physiological monitoring. Hospital systems in the Midwest and Southeast accelerate procurement of cloud-native RPM platforms. The Mayo Clinic in Minnesota pilots edge inference cardiac monitoring for post-discharge patient surveillance.
Germany
Statutory health insurers reimburse prescribed digital therapeutics through the BfArM DiGA fast-track pathway within 90 days of listing. Berlin and Munich host dense clusters of connected care software vendors targeting European health system compliance. The EU MDR's 2024 software-as-a-medical-device guidance shapes algorithm change control documentation for AI-enabled diagnostics.
South Korea
Government-backed smart hospital clusters in Songdo and Daegu reshape connected health device manufacturing through integrated procurement programs. The MFDS accelerates regulatory review for Bluetooth-enabled biometric sensors targeting hospital-at-home deployment. Samsung Medical Center in Seoul operates reference sites for patch-based cardiac monitoring without smartphone tethering.
India
The Ayushman Bharat Digital Mission's open API architecture invites foreign vendors to integrate with the national ABHA identifier system. Bangalore and Hyderabad emerge as telehealth platform development centers serving domestic and export markets. State-level digital health missions in Maharashtra and Karnataka pilot remote monitoring for chronic disease management in rural districts.
United Kingdom
NHS England's remote monitoring reimbursement frameworks accelerate adoption of continuous glucose monitors in primary care networks. London and Cambridge concentrate health technology vendors navigating MHRA post-Brexit regulatory pathways. The NHS Innovation Accelerator program funds pilot deployments of AI triage engines in Greater Manchester and West Midlands hospital trusts.
Connected Health and Wellness Solutions Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying biometric sensors and connectivity modules. The vendor base organizes around three strategic archetypes: consumer electronics giants with health sensor stacks, prescription medical device incumbents with FDA-cleared portfolios, and cloud-native software vendors with EHR integration capabilities. Competitive moves concentrate on strategic partnerships with hospital networks and portfolio diversification into adjacent diagnostic categories.
Within the consumer-grade wearable tier, Apple and Fitbit exemplify platform-centric positioning through integrated hardware-software ecosystems. Abbott and Medtronic occupy the prescription device segment, anchoring clinical validation requirements for reimbursement eligibility. These four entities represent divergent paths to market access: direct-to-consumer subscription velocity versus enterprise health system procurement cycles.
| Leading Market Players |
|---|
| Apple |
| Abbott |
| Fitbit |
| Medtronic |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Omron Healthcare |
| Dexcom |
| Garmin |
| Others |
Cost & Logistics Intelligence
The Incheon-to-Rotterdam maritime corridor carries semiconductor-laden containers whose freight cost volatility directly compresses margins for FDA-cleared wearable manufacturers while amplifying price spreads between premium sensor-integrated devices and economy-grade fitness trackers lacking clinical validation.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across the connected health landscape. Three-tier pricing separates prescription-grade continuous glucose monitors with embedded AI triage from standard consumer wearables and economy-grade fitness bands lacking biometric certification. Price differentiation rests on UL 2900 cybersecurity certification and CMS reimbursement eligibility, with German DiGA-listed digital therapeutics commanding premium positioning. Cost compression in the consumer tier is intensifying because hardware subsidies from employer wellness programs are shortening amortization periods. Direct-to-consumer subscribers exhibit the highest price sensitivity, while hospital procurement committees prioritize interoperability over unit cost.
Supply Chain Analysis
Export controls on advanced biometric ASICs limit component flows from TSMC-fabricated foundries to non-allied medical device vendors. Manufacturing concentrates in South Korea, the United States, and Taiwan for sensor modules and edge inference chips. Raw material dependencies include lithium-polymer cells, Bluetooth 5.3 radio modules, and photoplethysmography optical arrays. Single-source vulnerability in TSMC's 7nm fabrication for cardiac monitoring processors exposes vendors to foundry allocation volatility. Distribution runs through hospital GPO contracts in North America, statutory health insurer procurement frameworks in Germany, and direct-to-consumer e-commerce channels for wellness devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected health hardware is commoditizing while data analytics subscriptions and integration services expand at multiples of device revenue, making service-attach economics the decisive profitability lever for vendors across all tiers.
For Market Incumbents: Harden cloud-native platform architectures against emerging AI-native entrants by embedding proprietary triage algorithms directly into hospital EHR workflows. Deepen backward integration into edge inference chip design to reduce Qualcomm and Ambiq dependency. Prioritize BfArM DiGA fast-track certification for European market access before EU MDR software guidance tightens algorithm documentation requirements. For New Entrants and Emerging Players: India's Ayushman Bharat Digital Mission open API ecosystem represents the most penetrable entry point for foreign connected health vendors lacking established hospital system relationships. Rural chronic disease management programs in Maharashtra and Karnataka offer white-space deployment opportunities with lower competitive density than urban telehealth platforms. Partner with domestic system integrators in Bangalore and Hyderabad to navigate ABHA identifier integration requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underperforming consumer wellness divisions lacking reimbursement strategy focus. Long-term viability hinges on recurring revenue intensity rather than hardware shipment volume. Watch for FDA software-as-a-medical-device guidance finalization as the inflection signal for AI diagnostic valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic and Cerner integration contracts lock in multi-year RPM platform deployments with embedded AI triage. |
| Reimbursement Strategy | CMS CPT code expansion for remote therapeutic monitoring creates predictable revenue streams for glucose-sensing platforms. |
| Software Companion Development | FDA-cleared algorithm updates for predictive hypoglycemia alerts differentiate continuous monitors from commodity hardware. |
| CE Marking Pathway | EU MDR software guidance compliance enables BfArM DiGA listing and statutory insurer reimbursement in Germany. |
| Strategic Partnership | South Korean smart hospital clusters in Songdo offer integrated procurement channels for patch-based cardiac monitors. |
Research Approach
Initial hypotheses were tested against primary input from hospital procurement committee chairs, biomedical engineers, GPO contracts managers, and connected health platform CTOs and refined through secondary validation against FDA 510(k) premarket notification databases, CMS Medicare reimbursement code filings, BfArM DiGA registry listings, and EU MDR guidance documents. Bottom-up device shipment estimates triangulated against top-down health system IT spending allocations across the analysis window.
Demand-supply balance modeling anchored volume projections across the projection horizon. Segmentation dimensions included product type tier, end-user contract structure, technology architecture maturity, and regional regulatory reimbursement framework. CAGRs derived from fitted growth curves incorporating hospital RPM adoption rates, employer wellness subsidy expansion, and semiconductor foundry capacity constraints. Forecast inputs weighted Bluetooth 5.3 penetration curves and AI diagnostic algorithm regulatory clearance timelines.
Practitioners should monitor FDA software-as-a-medical-device guidance finalization, CMS telehealth reimbursement rule stability, and TSMC foundry allocation announcements for early signals of forecast deviation. Material shifts in EU MDR enforcement intensity or German DiGA fast-track processing delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
UAE Mhealth Market
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
US Patient Engagement Solutions Market
Digital Health Solutions
US Digital Therapeutics Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Global Mhealth Solutions Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Heart Failure Software Market
Digital Health Solutions
Mhealth Applications Market