
 Women's Digital Health Market | 2026-2036
Women's Digital Health Market Size, Share, and Industry Trends Forecast 2026-2036
Women's Digital Health Market Intelligence
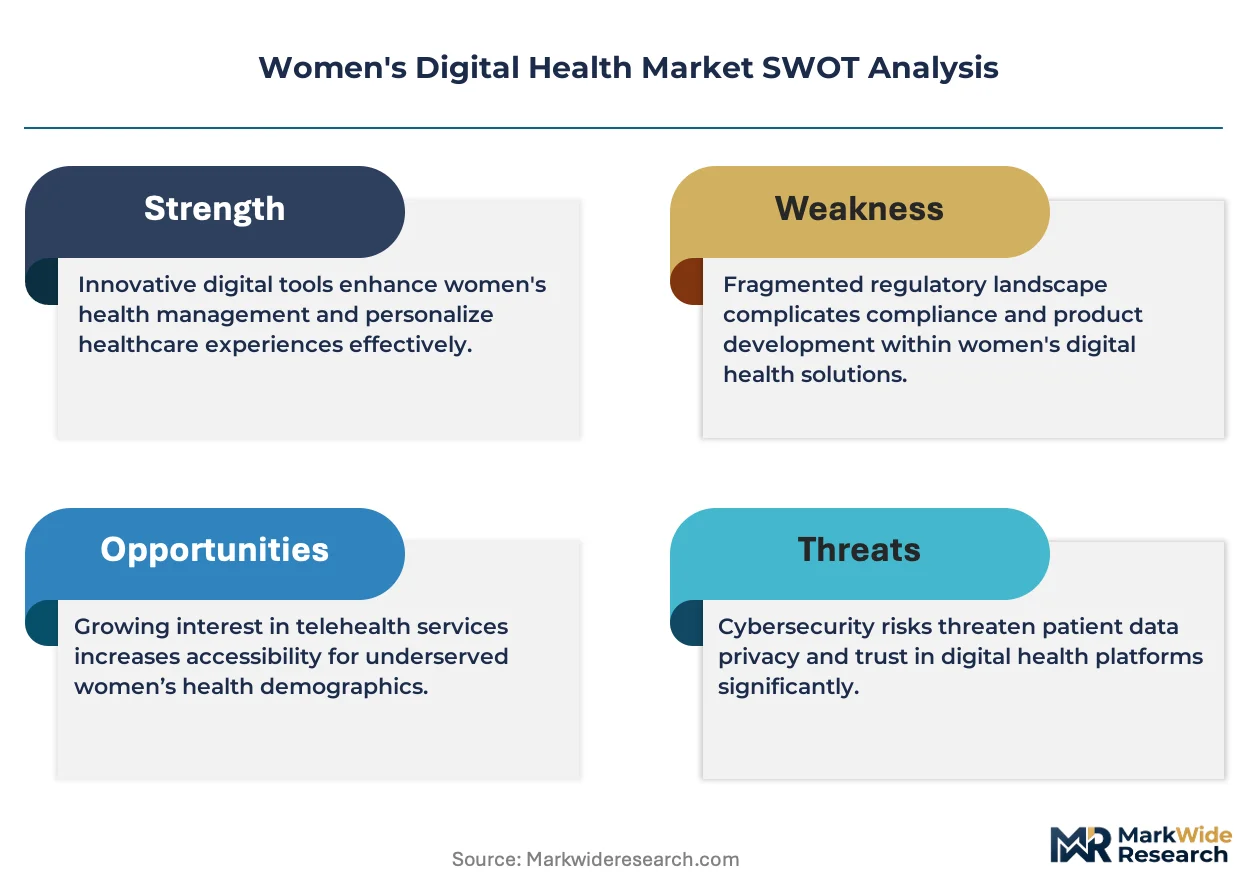
Buyer concentration among large employers is pivoting as self-insured corporations expand fertility and maternal health benefits, pulling demand from individual consumers toward enterprise contracts. Maven Clinic anchors employer channel partnerships with comprehensive virtual care platforms. Elvie leverages hardware-software integration in pelvic floor and breast pump wearables to sustain premium positioning. Kindbody competes through vertically integrated clinic networks that combine diagnostics with digital tracking.
Women's digital health encompasses software, connected devices, and remote services designed to monitor, diagnose, or manage female-specific physiological conditions through biometric sensors, algorithmic analysis, and cloud-based data architecture. Mobile apps and wearables dominate current revenue, with artificial intelligence-enabled diagnostics representing the fastest-expanding margin pool. Telehealth services for reproductive health and maternal care attract the largest subscriber bases, while fitness tracking applications face commoditization from general-purpose consumer electronics.
FDA software-as-medical-device classifications and HIPAA interoperability standards shape product development timelines and data governance requirements for US market participants. The EU AI Act and MDR frameworks impose additional conformity obligations for European market access, particularly on diagnostic algorithms and connected devices. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as payer policies increasingly determine which digital modalities achieve sustainable unit economics.
Market Dynamics
Employer-sponsored benefit expansion is restructuring demand architecture, pulling purchasing decisions from individual consumers toward enterprise procurement departments with specialized fertility and maternal health mandates.
Growth Catalysts
- FDA Software-as-Medical-Device Pathway:Clearance frameworks for algorithmic diagnostics accelerate commercialization timelines for reproductive health applications in the United States.
- Self-Insured Employer Adoption:Large corporations expand fertility benefits as talent retention instruments, creating enterprise contract velocity unavailable to direct-to-consumer channels.
- Biometric Sensor Miniaturization:Advances in photoplethysmography and temperature sensing enable continuous physiological monitoring through consumer-grade wearables.
Market Restraints
- HIPAA Interoperability Compliance Costs:Mandated data exchange standards impose infrastructure investments that disadvantage smaller platform developers.
- Algorithm Training Data Scarcity:Female-specific physiological datasets remain underrepresented in medical AI corpora, constraining diagnostic accuracy for conditions like endometriosis.
- Reimbursement Code Fragmentation:Inconsistent remote patient monitoring coverage across state Medicaid programs creates revenue unpredictability for service providers.
Strategic Opportunities
- Menopause Management White Space:Hormonal transition support attracts minimal dedicated platform investment relative to fertility and maternal segments.
- EU AI Act Conformity Advantage:Early alignment with risk-classification frameworks for diagnostic algorithms secures preferential market access across member states.
- Pharmaceutical Channel Partnerships:Drug manufacturers seek digital companion tools for contraceptive and fertility medication adherence, opening B2B2C distribution paths.
Industry Challenges
- Clinical Validation Timeline Compression:Platform developers face pressure to generate real-world evidence concurrent with product launch, straining study design resources.
- Legacy EHR Integration Friction:Hospital system procurement committees demand bidirectional data flows with entrenched electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women's Digital Health Market |
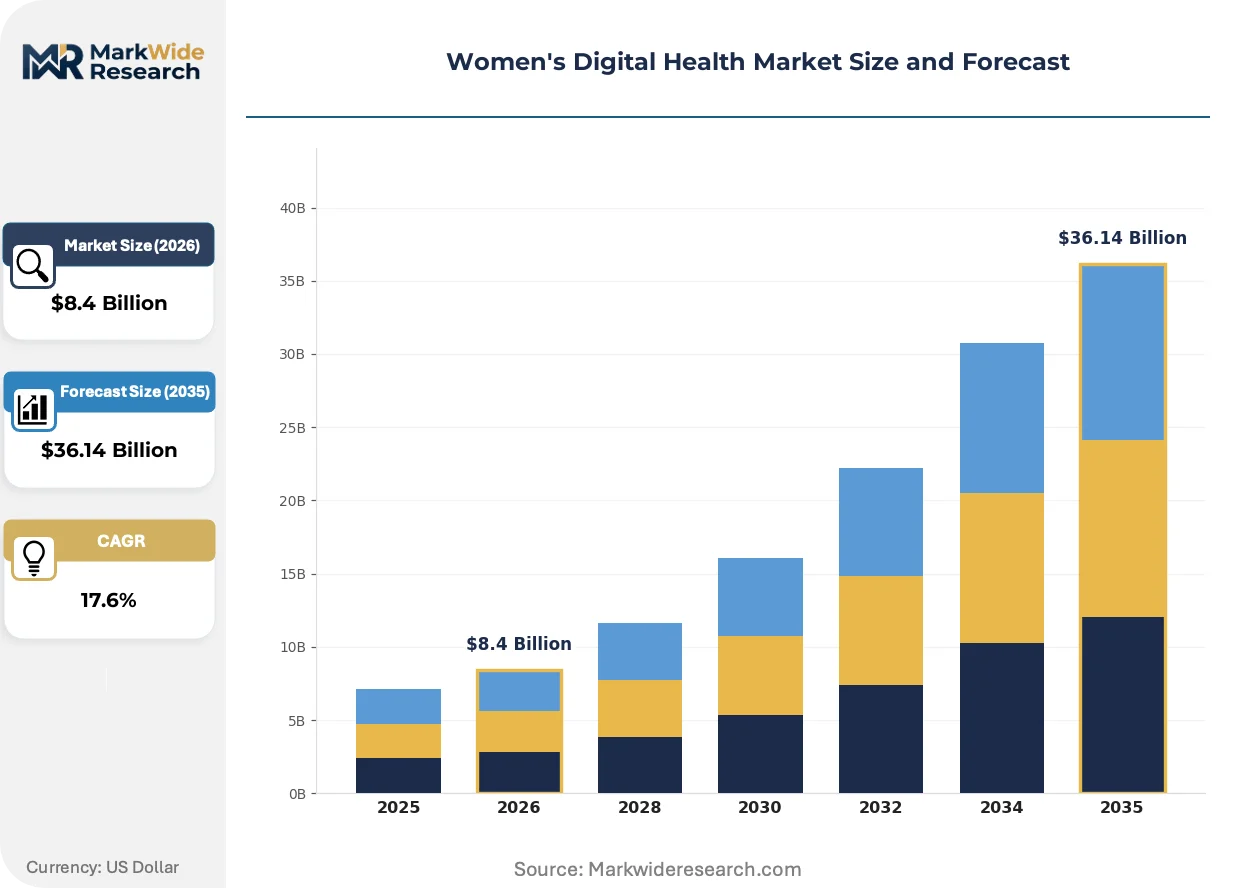
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearables, Mobile Apps, Telehealth Services, Online Communities Technology: Cloud Computing, Artificial Intelligence, Blockchain, Big Data End User: Clinics, Hospitals, Individuals, Employers Application: Reproductive Health, Maternal Care, Mental Wellness, Fitness Tracking |
| Companies Covered | Evvy, FamilyWell Health, Maven Clinic, Celmatix Therapeutics, Gameto, Kindbody, Axena Health, Endelia, Elvie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women's Digital Health Market Strategic Shifts & Innovations
Artificial intelligence is penetrating diagnostic workflows, regulatory frameworks are hardening around algorithmic accountability, and purchasing authority is migrating from patients to benefits administrators.
Continuous glucose monitoring adapted for hormonal cycle tracking is decentralizing fertility awareness from clinic-based laboratory testing to consumer-controlled physiological surveillance. Women with polycystic ovary syndrome and irregular menstrual patterns are adopting these biosensors at accelerating rates. This shift is decentralizing diagnostic authority from obstetrician-gynecologists to algorithm-mediated self-assessment.
EU AI Act risk-tier classifications for medical device software are mandating conformity assessments for reproductive health algorithms before European market entry. Manufacturers must document training data provenance and performance metrics across demographic subgroups. Diagnostic platforms targeting pregnancy risk stratification face the most intensive documentation burdens and are restructuring development pipelines accordingly.
Benefits administrators at self-insured employers are consolidating vendor selection authority previously dispersed across individual employees. Enterprise fertility benefit managers now evaluate platforms on total cost of care and outcomes guarantees rather than user experience metrics. This concentration is most visible among technology sector employers in California and New York with above-average maternity-age workforces.
Women's Digital Health Market Segmentation
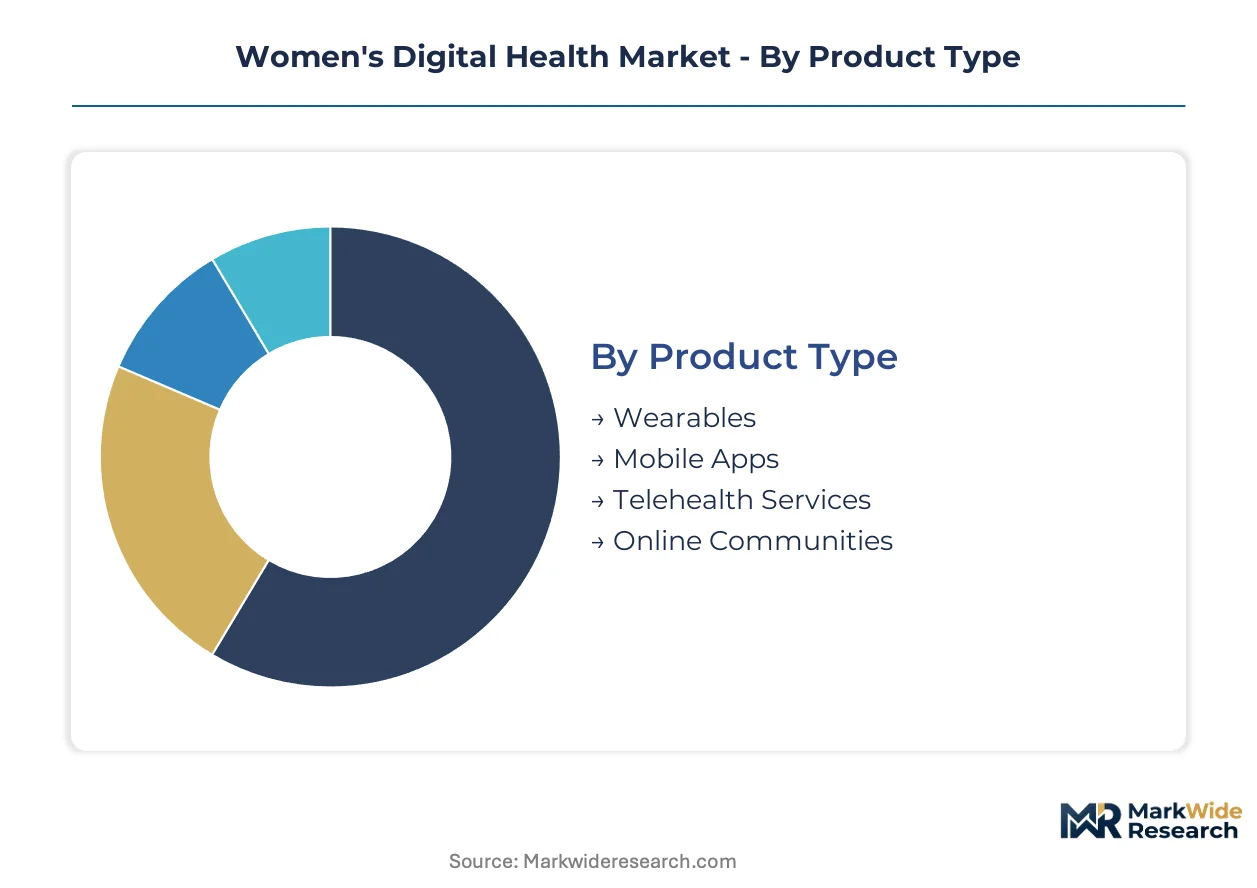
Segmentation in women's digital health reveals how purchasing authority concentrates across enterprise buyers versus individual consumers, with technology choices determining regulatory pathways and reimbursement eligibility. Product architecture and end-user economics diverge sharply between hardware-enabled continuous monitoring and software-only diagnostic platforms.
Product Type:
Enterprise procurement departments evaluate hardware-software bundles on total cost of care guarantees, while individual consumers prioritize subscription pricing transparency and data portability.
- Wearables:Photoplethysmography and temperature sensors embedded in wrist-worn or patch-form devices enable continuous cycle tracking and fertility awareness. Demand concentrates among self-insured employers in California and New York seeking maternity-age workforce retention instruments, constrained by FDA software-as-medical-device clearance timelines for algorithmic diagnostics.
- Telehealth Services:Synchronous virtual consultations and asynchronous messaging platforms connect patients with obstetrician-gynecologists, reproductive endocrinologists, and mental health specialists. Large corporations expand fertility benefit mandates through enterprise contracts with outcomes-based pricing, displacing direct-to-consumer subscription models.
- Mobile Apps:Software-only platforms deliver symptom tracking, medication adherence prompts, and educational content through smartphone interfaces.
- Online Communities:Peer support forums and moderated discussion groups address condition-specific experiences including endometriosis, polycystic ovary syndrome, and perimenopause.
Volume sits with mobile apps; growth tilts toward wearables.
Technology:
Regulatory risk classification determines development investment allocation, with high-risk diagnostic algorithms requiring conformity assessments under EU AI Act frameworks.
- Artificial Intelligence:Machine learning models trained on female-specific physiological datasets perform pregnancy risk stratification, endometriosis pattern recognition, and menstrual cycle prediction. Diagnostic platforms face intensive documentation burdens for training data provenance and demographic subgroup performance metrics under EU AI Act high-risk classifications.
- Cloud Computing:Scalable infrastructure supports real-time biometric data ingestion, algorithmic processing, and patient-facing dashboard delivery. HIPAA interoperability mandates impose infrastructure investments that disadvantage smaller platform developers competing for hospital system procurement contracts.
- Big Data:Aggregated longitudinal health records enable population-level insights and predictive modeling across reproductive health outcomes.
- Blockchain:Distributed ledger architectures address patient consent management and data audit trails for multi-party health information exchange.
Cloud computing anchors current deployment; artificial intelligence commands the steepest expansion trajectory.
End User:
Reimbursement code availability shapes addressable market size, with employer-sponsored benefits bypassing fragmented state Medicaid remote patient monitoring coverage.
- Employers:Self-insured corporations contract comprehensive fertility and maternal health platforms as talent retention instruments, consolidating vendor selection authority previously dispersed across individual employees. Benefits administrators evaluate total cost of care and outcomes guarantees rather than user experience metrics.
- Individuals:Direct-to-consumer purchasers select subscription-based apps and wearables through app stores and e-commerce channels, sensitive to monthly pricing and data privacy controls.
- Hospitals:Health system procurement committees demand bidirectional data flows with entrenched electronic health record architectures.
- Clinics:Specialty reproductive health practices integrate digital tools for patient monitoring between in-person visits.
Individual subscriptions generate volume; employer contracts capture margin expansion.
Application:
White space availability and competitive saturation determine platform investment returns, with menopause management attracting minimal dedicated venture funding relative to fertility segments.
- Reproductive Health:Fertility awareness, contraception management, and assisted reproductive technology support dominate current revenue concentration. FDA software-as-medical-device pathways accelerate commercialization for algorithmic diagnostics in the United States.
- Maternal Care:Pregnancy monitoring, postpartum recovery tracking, and lactation support attract the largest subscriber bases through employer benefit expansion. Telehealth services for high-risk pregnancy management secure reimbursement codes more readily than wellness-oriented applications.
- Mental Wellness:Cognitive behavioral therapy apps and peer support platforms address perinatal depression, anxiety, and trauma.
- Fitness Tracking:General-purpose consumer electronics commoditize menstrual-aware activity monitoring, pressuring standalone app developers.
Maternal care holds installed base; reproductive health gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-sponsored fertility benefits concentrate purchasing power among large corporations in the United States, with European and Asian markets following distinct regulatory and reimbursement pathways.
United States
Self-insured employers in California and New York drive enterprise contract velocity for comprehensive virtual care platforms. FDA software-as-medical-device clearance frameworks accelerate commercialization timelines for algorithmic diagnostics. Silicon Valley and Manhattan host the densest concentrations of technology sector employers expanding maternity-age workforce retention benefits.
United Kingdom
Enterprise procurement departments at financial services and professional services firms expand reproductive health benefits as talent competition instruments. NHS digital transformation mandates create procurement pathways for remote patient monitoring platforms. London anchors the national market with employer benefit managers evaluating total cost of care guarantees.
Germany
Statutory health insurance funds pilot reimbursement for digital health applications through the DiGA fast-track approval pathway. EU AI Act risk-classification frameworks impose conformity documentation burdens on diagnostic algorithm developers. Berlin and Munich concentrate health technology startups navigating MDR and AI Act dual compliance obligations.
China
Domestic technology platforms capture demand for menstrual tracking and maternal health applications through super-app integration. NMPA medical device regulations for software-based diagnostics tighten product registration requirements. Shenzhen and Beijing host hardware-software developers miniaturizing biometric sensors for consumer-grade wearables.
India
Direct-to-consumer subscription models dominate as employer-sponsored benefit infrastructure remains underdeveloped outside multinational corporations. CDSCO medical device rules for software-based diagnostics create registration complexity for foreign platform entrants. Bengaluru and Mumbai concentrate venture-funded health technology startups targeting fertility awareness and maternal care applications.
Women's Digital Health Market Key Industry Players
United States platforms anchor the employer-sponsored tier; European and Asian specialists hold positions in hardware-software integration and direct-to-consumer channels. Market structure fragments across virtual care platforms, connected device manufacturers, and vertically integrated clinic networks. Three archetypes dominate: comprehensive virtual care providers, hardware-enabled monitoring specialists, and clinic-digital hybrid operators. Competitive moves concentrate on employer channel partnerships and regulatory pre-clearance positioning.
Within the comprehensive virtual care archetype, Maven Clinic occupies a position representing employer channel concentration. Among hardware-software integration specialists, Elvie exemplifies premium positioning through wearable form factors. In the vertically integrated tier, Kindbody anchors clinic-digital hybrid operations. These three entities represent distinct strategic pathways: enterprise contract velocity, hardware-enabled biometric monitoring, and physical-digital service integration.
| Leading Market Players |
|---|
| Evvy |
| FamilyWell Health |
| Maven Clinic |
| Celmatix Therapeutics |
| Gameto |
| Kindbody |
| Axena Health |
| Endelia |
| Elvie |
| Others |
Cost & Logistics Intelligence
Biometric sensor miniaturization is simultaneously compressing hardware production costs and concentrating component sourcing among specialized photoplethysmography foundries in Taiwan and South Korea. This technology shift enables premium wearable pricing while squeezing margins for software-only platforms lacking hardware differentiation.
Pricing Analysis
Volume concentrates in subscription-based mobile apps at economy price points, while margin expansion accrues to hardware-software bundles with FDA software-as-medical-device clearance. Price differentiation rests on clinical validation depth and HIPAA interoperability certification tier. Pricing pressure stems from employer procurement committees demanding outcomes-based guarantees rather than per-user fees. Individual consumers exhibit highest price sensitivity to monthly subscription costs; self-insured employers prioritize total cost of care over unit pricing.
Supply Chain Analysis
Domestic-content mandates under the EU AI Act and FDA software-as-medical-device frameworks are reshaping algorithm development sourcing toward US and European data science clusters. Component supply concentrates in Taiwan, South Korea, and China for biometric sensors and cloud infrastructure. Raw material dependencies include photoplethysmography chips, temperature sensors, and lithium-ion batteries. Single-source vulnerability in foundry capacity for specialized medical-grade sensors threatens hardware delivery timelines. Distribution runs through enterprise benefits administrators for employer contracts and direct-to-consumer e-commerce for individual purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration is accelerating as platforms seek captive control over clinic networks, diagnostic laboratories, and pharmaceutical companion tools to secure employer contract renewals.
For Market Incumbents: To counter commoditization of cycle-tracking algorithms, anchor enterprise positioning through backward integration into in-house diagnostic laboratory capacity and outcomes guarantee underwriting. Secure preferential reimbursement codes through FDA software-as-medical-device pre-clearance investment. Deepen clinic network ownership to capture margin from telehealth referrals. For New Entrants and Emerging Players: The premium-to-economy price gap in menopause management platforms creates entry opportunity for mid-market positioning with hormonal biomarker integration. Target direct-to-consumer channels in India and employer pilot programs in the United Kingdom. Pursue pharmaceutical channel partnerships for contraceptive adherence companion tools as distribution wedge. For Investors and Strategic Acquirers: Exit pathways concentrate in clinic-digital hybrid operators with proprietary patient data assets and employer contract backlogs. Long-term viability favors platforms with FDA clearance moats and HIPAA interoperability infrastructure. Watch employer benefit manager consolidation as inflection signal for enterprise contract pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Clearance accelerates commercialization timelines for algorithmic fertility diagnostics in employer procurement. |
| Hospital System Partnership | Bidirectional EHR integration satisfies procurement committee requirements for enterprise contract eligibility. |
| Clinic Network Acquisition | Vertical control over diagnostics captures margin from telehealth referrals and outcomes guarantee underwriting. |
| Pharmaceutical Companion Development | Drug manufacturer partnerships open B2B2C distribution for contraceptive and fertility medication adherence tools. |
| EU AI Act Conformity Pathway | Early alignment with high-risk classification documentation secures preferential market access across member states. |
Research Approach
Multi-period observation of employer benefit expansion, FDA clearance timelines, and reimbursement code adoption anchored the trend analysis, supplemented by interviews with digital health platform executives, benefits administrators at self-insured corporations, hospital procurement committee members, and reproductive endocrinologists. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital GPO contracts, and employer benefit plan disclosures. Bottom-up unit economics modeling and top-down market sizing triangulated volume estimates.
Segment-weighting across product type, technology, end user, and application dimensions structured the analytical framework. CAGRs were derived from fitted growth curves against historical adoption patterns and regulatory milestone schedules. Forecast inputs included employer fertility benefit penetration rates, FDA software-as-medical-device clearance velocity, and EU AI Act conformity assessment timelines.
Inputs from regulatory filings and employer benefit plan disclosures were available through the study window; gaps in real-world evidence generation timelines for algorithmic diagnostics introduce uncertainty bands around commercialization assumptions. Forecasts reflect documented assumptions regarding reimbursement code expansion and employer adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Women Health Devices Market
Women's Health
Maternal Health Market
Women's Health
Menstrual Health Apps Market
Women's Health
Women Health Care Market
Women's Health
Women Health Software Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Women's Health Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Dysfunctional Uterine Bleeding Market
Women's Health
Menopause Market
Women's Health
Women's Health App Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Menstrual Cup Foam Wash Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
Global Menopausal Hot Flashes Market