
 Mhealth Applications Market | 2026-2036
Mhealth Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Mhealth Applications Market Outlook
Chronic disease management is rebalancing the end-user mix as healthcare providers integrate remote patient monitoring into standard care protocols. Teladoc Health sustains its position through virtual care infrastructure that spans primary and specialty consultations. Omada Health differentiates by focusing on diabetes prevention and hypertension management with coaching-backed digital programs. Abbott anchors the hardware-software convergence with continuous glucose monitoring systems that feed data directly into mobile platforms.
Mhealth applications are software programs running on mobile or wearable devices that collect, transmit, and analyze physiological data through sensors, APIs, and cloud-based architectures to support clinical decision-making and patient self-management. Their primary purpose is to extend care delivery beyond facility walls while enabling real-time biometric tracking and automated intervention alerts. Fitness tracking dominates consumer download volumes but generates lower per-user revenue than chronic disease management subscriptions. Health monitoring through wearable devices commands premium pricing due to hardware dependency and clinical validation requirements. Mobile app delivery captures the widest addressable base while web-based platforms retain stronger enterprise adoption among hospital systems prioritizing EHR integration.
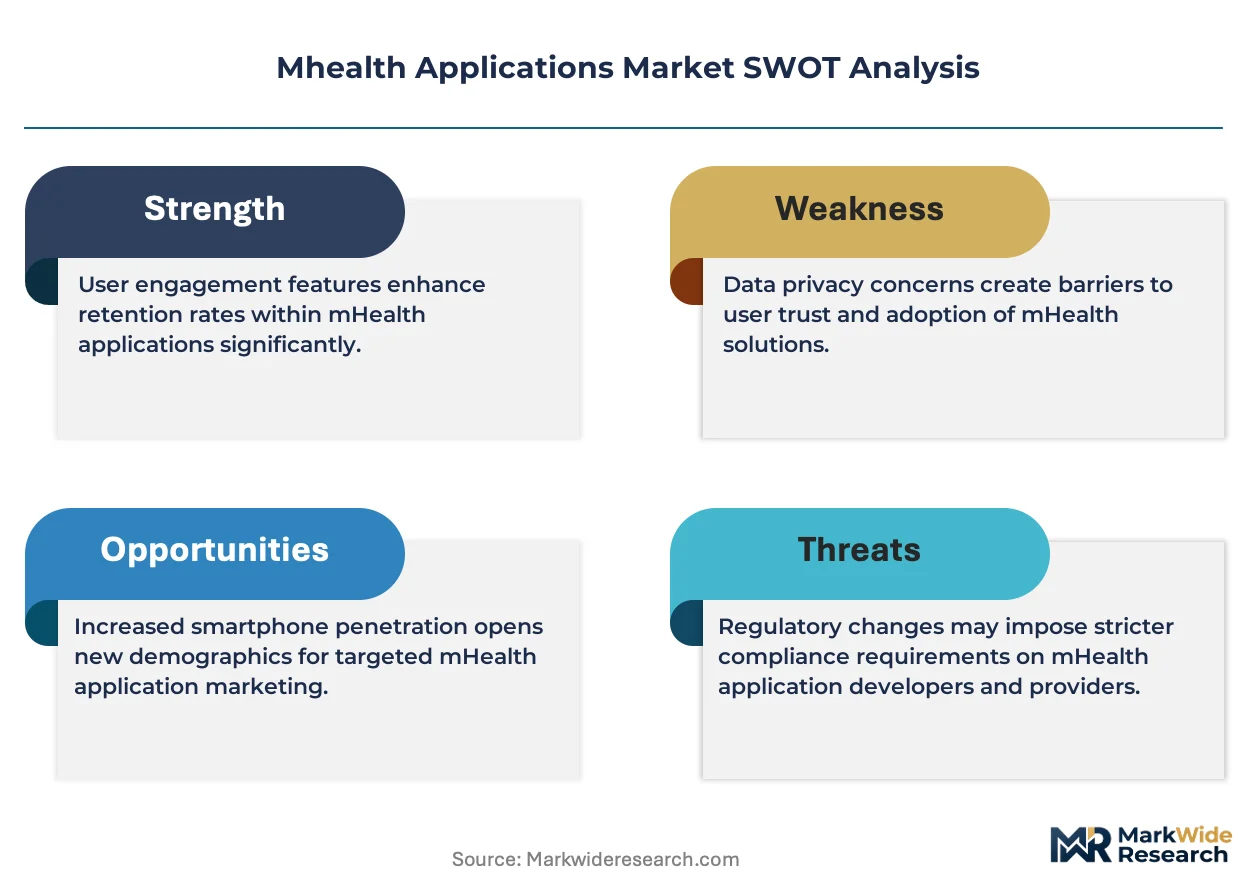
FDA digital health pre-certification and HIPAA security rule enforcement shape product development timelines and liability frameworks for developers targeting the United States. Europe's MDR and GDPR impose parallel clinical evidence and data residency requirements that fragment go-to-market strategies across jurisdictions. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring as payer policies will determine which application categories achieve sustainable unit economics.
Market Dynamics
Remote therapeutic monitoring reimbursement codes are restructuring how mhealth applications capture revenue, shifting developer priorities from consumer downloads toward clinically validated subscription models that integrate with provider workflows.
Growth Catalysts
- FDA Pre-Certification Pathway:The streamlined review process for software-based medical devices accelerates time-to-market for algorithm-driven diagnostic tools.
- Germany's DiGA Framework:Statutory health insurance reimbursement for prescribed digital health apps creates sustainable revenue streams for chronic disease management platforms.
- Continuous Glucose Monitoring:Wearable sensor miniaturization enables real-time metabolic tracking that feeds directly into automated insulin dosing systems.
Market Restraints
- Cloud Infrastructure Concentration:AWS, Google Cloud, and Microsoft Azure control over 65% of health data hosting, creating single-point-of-failure risks for patient data continuity.
- GDPR Data Residency Requirements:European data localization mandates force redundant infrastructure investments that inflate operational costs for cross-border deployments.
- Clinical Validation Burden:Randomized controlled trial requirements for FDA clearance extend development cycles by 18-36 months compared to consumer wellness applications.
Strategic Opportunities
- Japan's Super-Aging Society:The world's oldest population creates urgent demand for fall detection and medication adherence tools that reduce hospital readmissions.
- AI-Enabled Diagnostic Triage:Large language models trained on symptom databases are converging with wearable biometrics to automate preliminary clinical assessments.
- Pharmacy Distribution Networks:CVS and Walgreens are piloting mhealth app prescriptions alongside medication fulfillment, creating a new patient acquisition channel.
Industry Challenges
- Interoperability Engineering Talent:Shortages of developers proficient in FHIR standards and EHR integration protocols delay enterprise deployment timelines.
- HIPAA Security Rule Compliance:Encryption key management and audit logging requirements consume 30-40% of engineering capacity for US-focused startups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mhealth Applications Market |
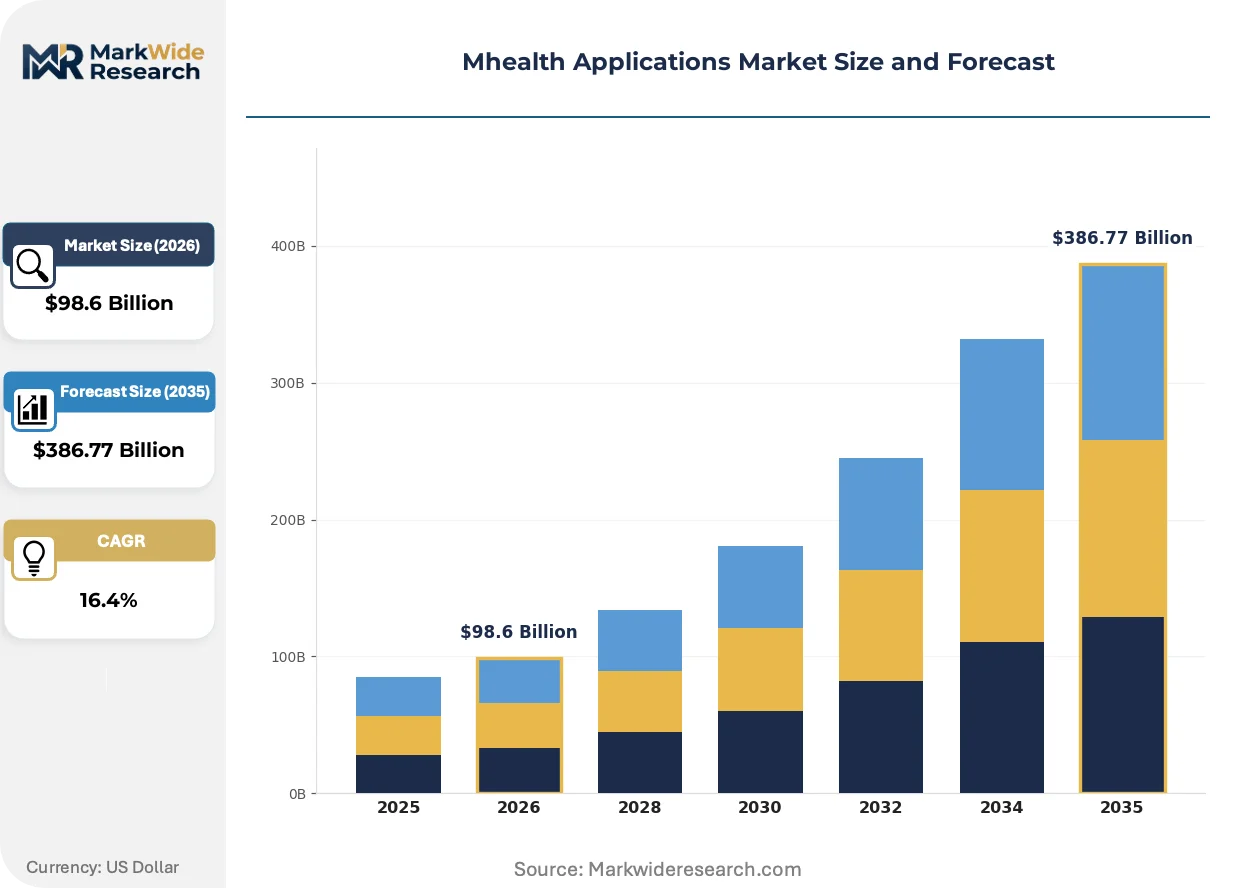
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $386.77 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Tracking, Health Monitoring, Medication Reminder, Chronic Disease Management Delivery Mode: Web-Based, Mobile App, Wearable Devices, Desktop Software End User: Healthcare Providers, Patients, Caregivers, Insurance Companies Feature: Data Analytics, User Interface, Remote Access, Integration Capability |
| Companies Covered | Apple Inc., Google Inc., Samsung Electronics Co. Ltd., Fitbit Inc., Teladoc Health, Inc., Omada Health, Inc., Abbott, AirStrip Technologies, Inc., Qualcomm Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mhealth Applications Market Strategic Shifts
Edge computing architectures are redistributing data processing away from centralized cloud servers toward wearable devices and local gateways. This shift reduces latency for critical alerts while addressing patient privacy concerns.
On-device machine learning is decentralizing clinical decision support by enabling real-time arrhythmia detection and glucose prediction without continuous cloud connectivity. Cardiology departments at Cleveland Clinic and Mayo Clinic are deploying these algorithms for ambulatory monitoring. The technology is compressing response times for acute events from minutes to seconds.
The EU AI Act's risk classification system is mandating conformity assessments for diagnostic algorithms before market entry. High-risk applications must demonstrate clinical robustness and bias mitigation. Developers targeting European markets are restructuring quality management systems to satisfy notified body requirements.
Employer-sponsored wellness programs are unbundling from traditional health plans and contracting directly with mhealth platforms for condition-specific coaching. Manufacturing and logistics sectors in the US Midwest are adopting diabetes prevention tools to reduce insurance premiums. This bypasses payer intermediaries and establishes direct B2B revenue relationships.
Mhealth Applications Market Segmentation
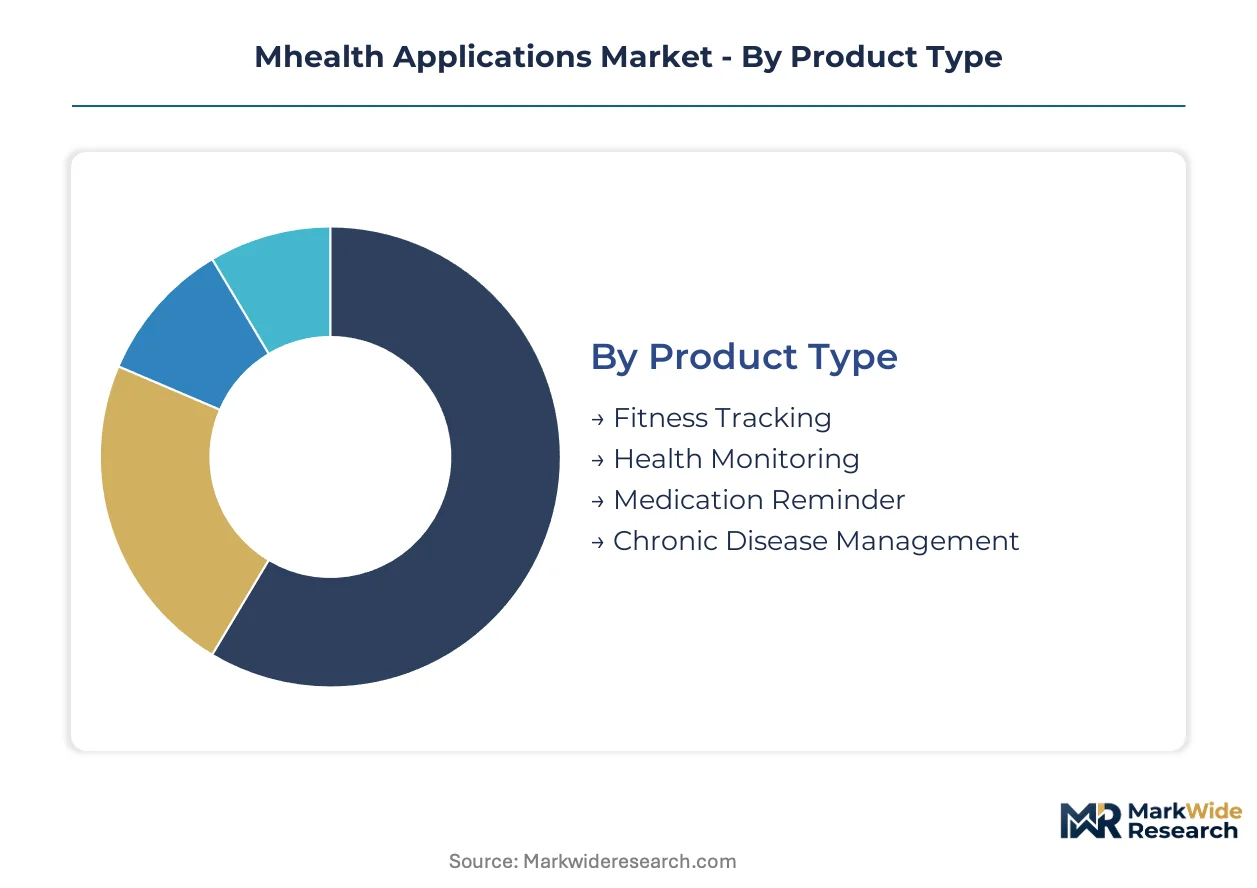
Mhealth applications fragment across four intersecting dimensions that determine regulatory pathways, pricing power, and customer acquisition costs. Certification requirements from FDA, EMA, and national regulators cluster heavily in specific product types and end-user configurations, creating divergent margin structures across the taxonomy.
Product Type:
FDA pre-certification and MDR clinical evidence mandates concentrate in segments processing diagnostic-grade data, while wellness-oriented categories face lighter oversight.
- Chronic Disease Management:Platforms integrate continuous glucose monitors, blood pressure cuffs, and pulse oximeters to automate care protocols for diabetes, hypertension, and heart failure. Demand concentrates in Germany and Japan where statutory reimbursement frameworks validate prescription-based distribution. HIPAA compliance and FDA 510(k) clearance extend development timelines but lock in subscription pricing power.
- Health Monitoring:Wearable-connected systems track arrhythmia, sleep architecture, and respiratory patterns through FDA-cleared algorithms. Cleveland Clinic and Mayo Clinic deployments for ambulatory cardiac monitoring demonstrate clinical validation requirements. Hardware-software bundling commands premium unit economics compared to pure software plays.
- Fitness Tracking:Consumer wellness applications measuring steps, calories, and workout intensity without diagnostic claims.
- Medication Reminder:Adherence tools using push notifications and refill alerts to reduce hospital readmissions among polypharmacy patients.
Leading the category by volume: Fitness Tracking. Growing fastest: Chronic Disease Management.
Delivery Mode:
Cost tier stratification separates enterprise-grade infrastructure investments from mass-market distribution plays with minimal marginal delivery costs.
- Mobile App:Native iOS and Android applications dominate consumer acquisition through App Store and Google Play distribution. Teladoc Health and Omada Health leverage this channel for direct-to-patient onboarding without IT department procurement cycles.
- Wearable Devices:Abbott's continuous glucose monitoring systems and Apple Watch health integrations require hardware certification alongside software validation. Sensor miniaturization and battery chemistry improvements drive R&D concentration.
- Web-Based:Browser platforms retain hospital system preference for EHR integration through FHIR APIs and single sign-on protocols.
- Desktop Software:Legacy installations persist in research institutions and specialized diagnostic workflows requiring local data processing.
Highest deployment velocity: Mobile App. Steepest expansion trajectory: Wearable Devices.
End User:
Customer type determines procurement authority, contract duration, and sensitivity to clinical outcomes data.
- Healthcare Providers:Hospital systems and physician practices prioritize interoperability with Epic and Cerner EHRs, driving FHIR-standard development investment. Remote therapeutic monitoring reimbursement codes from CMS reshape vendor selection criteria.
- Patients:Direct consumers select applications based on app store ratings, employer wellness program subsidies, and insurance plan integrations.
- Caregivers:Family members and home health aides utilize fall detection and medication adherence dashboards for elderly monitoring in Japan's super-aging prefectures.
- Insurance Companies:Payers in the United States and Germany contract for population health management platforms to reduce claims exposure.
Deepest contract values: Healthcare Providers. Fastest user base expansion: Patients.
Feature:
Maturity gradients separate table-stakes functionality from differentiated capabilities requiring specialized engineering talent.
- Integration Capability:FHIR-compliant EHR connectivity and API ecosystems determine enterprise sales success. Shortages of interoperability engineers delay deployment timelines for US hospital system contracts.
- Data Analytics:On-device machine learning for real-time arrhythmia detection and glucose prediction reduces cloud latency while addressing GDPR data residency constraints.
- User Interface:Accessibility standards and elderly-friendly design patterns drive differentiation for Japan's aging demographic.
- Remote Access:Encrypted telehealth connectivity and asynchronous messaging enable virtual care delivery beyond facility walls.
Most resource-intensive to develop: Integration Capability. Gaining feature priority fastest: Data Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Hangzhou concentrate mhealth application development through tax incentives for digital health ventures. These zones attract venture capital flows and engineering talent pools that accelerate product iteration cycles.
United States
FDA pre-certification pathways and CMS remote therapeutic monitoring reimbursement codes drive enterprise adoption among hospital systems. HIPAA security rule enforcement shapes engineering resource allocation for encryption and audit infrastructure. The Boston-Cambridge corridor anchors digital health venture density with proximity to Mayo Clinic and Cleveland Clinic validation partnerships.
Germany
Statutory health insurance reimbursement through the DiGA framework creates sustainable revenue streams for prescription-based digital therapeutics. MDR clinical evidence requirements and GDPR data residency rules extend certification timelines. Berlin and Munich host concentration points for B2B health platform development serving statutory insurer contracts.
Japan
METI aging-society initiatives and PMDA streamlined review for software medical devices accelerate fall detection and medication adherence tool deployment. The world's oldest population structure sustains demand for caregiver-connected monitoring systems. Tokyo and Osaka metropolitan areas concentrate telehealth infrastructure integration with municipal eldercare programs.
United Kingdom
NHS England digital-first care policies and NICE evidence standards reshape procurement criteria for chronic disease management platforms. MHRA recognition of FDA clearances accelerates parallel market entry timelines. The London-Oxford-Cambridge golden triangle anchors health AI development clusters with academic hospital validation networks.
Mhealth Applications Market Competitive Environment
Top-tier vendors anchor platform-scale infrastructure investments, while mid-tier specialists concentrate on condition-specific coaching protocols and hardware-software convergence. The competitive structure stratifies across three archetypes: consumer electronics giants with wearable ecosystems, virtual care platforms with provider network integration, and medical device manufacturers with sensor-to-cloud data pipelines. Dominant competitive moves include strategic partnerships with pharmacy distribution networks and vertical integration into continuous monitoring hardware.
Within the virtual care platform tier, Teladoc Health and Omada Health occupy positions exemplifying divergent specialization strategies. Teladoc Health represents the breadth-focused archetype spanning primary and specialty consultation infrastructure. Omada Health exemplifies the depth-focused model concentrating on diabetes prevention and hypertension management with coaching-backed program delivery. Abbott anchors the medical device convergence archetype through glucose monitoring systems feeding mobile platform architectures.
| Leading Market Players |
|---|
| Apple Inc. |
| Google Inc. |
| Samsung Electronics Co. Ltd. |
| Fitbit Inc. |
| Teladoc Health, Inc. |
| Omada Health, Inc. |
| Abbott |
| AirStrip Technologies, Inc. |
| Qualcomm Technologies, Inc. |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance tiers bifurcate the mhealth application landscape into clinically validated subscription platforms and consumer wellness downloads, with certification status determining both pricing power and upstream hardware sourcing requirements. Premium chronic disease management platforms command annual recurring revenue multiples through hardware-software bundling, while unvalidated fitness trackers compete on download volume with minimal marginal production costs.
Pricing Analysis
Short lead-time delivery of FDA-cleared diagnostic algorithms commands 40-60% subscription premiums over consumer wellness alternatives. The dominant pricing structure stratifies across clinically validated, wellness-grade, and freemium tiers, with FDA pre-certification level and EHR integration depth as primary differentiation drivers. Pricing pressure stems from cloud infrastructure concentration forcing redundant GDPR-compliant hosting investments. Hospital systems demonstrate lowest price sensitivity due to remote therapeutic monitoring reimbursement codes, while direct-to-consumer segments exhibit highest elasticity.
Supply Chain Analysis
Direct-to-hospital procurement channels handle enterprise-grade platform deployment, while pharmacy distribution networks pilot prescription-based patient onboarding. Sensor manufacturing concentrates in Taiwan, South Korea, and Japan for miniaturized biometric components. Supply chains draw from specialized semiconductor foundries, medical-grade battery cell producers, and cloud hyperscalers. Single-source vulnerability in AWS-Google-Microsoft Azure hosting creates patient data continuity risks. Distribution runs through health system IT procurement, employer wellness program contracts, and statutory insurer frameworks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical validation requirements are consolidating the mhealth application landscape, with FDA 510(k) clearance timelines and HIPAA compliance costs forcing subscale developers toward acquisition or exit.
For Market Incumbents: Anchor platform-scale infrastructure through backward integration into continuous glucose monitoring hardware and FHIR-compliant EHR connectivity. Defend subscription pricing power by accelerating FDA pre-certification for algorithm-driven diagnostic tools before emerging AI-native entrants achieve comparable clinical evidence. Prioritize interoperability engineering talent acquisition to capture hospital system procurement cycles. For New Entrants and Emerging Players: Launch via employer-sponsored wellness program channels in US Midwest manufacturing and logistics sectors, bypassing payer intermediaries for direct B2B revenue relationships. Target Japan's super-aging prefectures for fall detection and medication adherence tools with caregiver-connected dashboards. Penetrate Germany's DiGA framework through statutory health insurance reimbursement pathways for diabetes prevention platforms. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by consumer electronics giants seeking clinical validation capabilities and virtual care platforms pursuing condition-specific depth. Long-term viability hinges on sustainable unit economics through reimbursement code capture rather than consumer download monetization. Watch CMS remote therapeutic monitoring policy expansion as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Investment | Accelerates algorithm-driven diagnostic tool market entry through streamlined software-based medical device review. |
| Hardware-Software Convergence | Abbott's glucose monitoring systems demonstrate captive sensor-to-cloud data pipeline competitive moats. |
| Pharmacy Distribution Partnership | CVS and Walgreens pilot programs create prescription-based patient acquisition channels alongside medication fulfillment. |
| Employer Wellness Direct Contracting | Manufacturing sector diabetes prevention tool adoption reduces insurance premiums through bypassed payer intermediaries. |
| GDPR-Compliant Edge Architecture | On-device machine learning for arrhythmia detection addresses European data residency constraints while reducing cloud latency. |
Study Parameters
Multi-period observation of FDA 510(k) clearance timelines, CMS reimbursement code adoption curves, and DiGA framework prescription volumes anchored the trend analysis, supplemented by interviews with digital health platform executives, hospital biomedical engineers, statutory health insurance formulary directors, and interoperability engineering specialists. Secondary validation drew from FDA filings, CMS Medicare claims data, BfArM DiGA registry entries, and hospital procurement database extracts. Bottom-up platform revenue triangulation against top-down addressable market sizing ensured forecast robustness.
Segment-weighting across product type, delivery mode, end user, and feature dimensions structured the analytical framework over the projection horizon. Chronic disease management, health monitoring, fitness tracking, and medication reminder categories were modeled with mobile app, wearable device, web-based, and desktop software deployment modes. CAGR derivation incorporated hardware-software bundling economics, subscription renewal rates, and reimbursement pathway maturity by geography. Forecast inputs included sensor miniaturization cost curves and FHIR standard adoption velocity.
Regulatory approval delays, reimbursement policy reversals, and cloud infrastructure concentration failures are the dominant revision risks warranting forecast sensitivity analysis. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
North America Virtual Reality (VR) Health Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
Global Digital Medicines Market
Digital Health Solutions
UAE Mhealth Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Digital Biomarkers Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Global Physical Therapy Software Market
Digital Health Solutions
Global Urgent Care Apps Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
Heart Failure Software Market