
 Digital Radiology Market | 2026-2036
Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Radiology Market Intelligence
Software-defined subscription layers for remote diagnostics and predictive maintenance is repositioning capital equipment vendors as recurring-revenue service providers. Siemens Healthineers leverages its in-house AI development pipeline to bundle algorithm updates with hardware leases. GE Healthcare anchors its competitive stance through extensive field service networks that lock in multi-year maintenance contracts. Philips differentiates by integrating enterprise imaging software with cardiology and oncology workflows across integrated delivery networks.
Digital radiology encompasses the acquisition, processing, storage, and transmission of medical images using electronic detectors and computerized reconstruction algorithms, with spatial resolutions typically ranging from 0.1 to 0.2 millimeters for flat-panel detectors and dose efficiency measured by detective quantum efficiency coefficients exceeding 70 percent in premium systems. CT scanners command the largest installed base revenue pool due to replacement cycles tied to gantry speed upgrades and spectral imaging capabilities. Cloud-based solutions represent the fastest-expanding technology segment as hospital IT departments shift capital expenditure to operational expenditure models. Diagnostic centers concentrate margin capture in ultrasound devices, where portable point-of-care units expand service reach without facility construction costs.
FDA premarket notification pathways for radiological devices, combined with HIPAA security rule mandates for electronic protected health information, establish compliance thresholds that shape vendor product development priorities and customer procurement checklists. The European Medical Device Regulation imposes clinical evidence requirements on software-as-a-medical-device classifications, affecting how PACS and AI modules enter EU markets. Stakeholders must monitor how national reimbursement frameworks for AI-augmented reads reshape purchasing authority between radiology departments and hospital procurement offices.
Market Dynamics
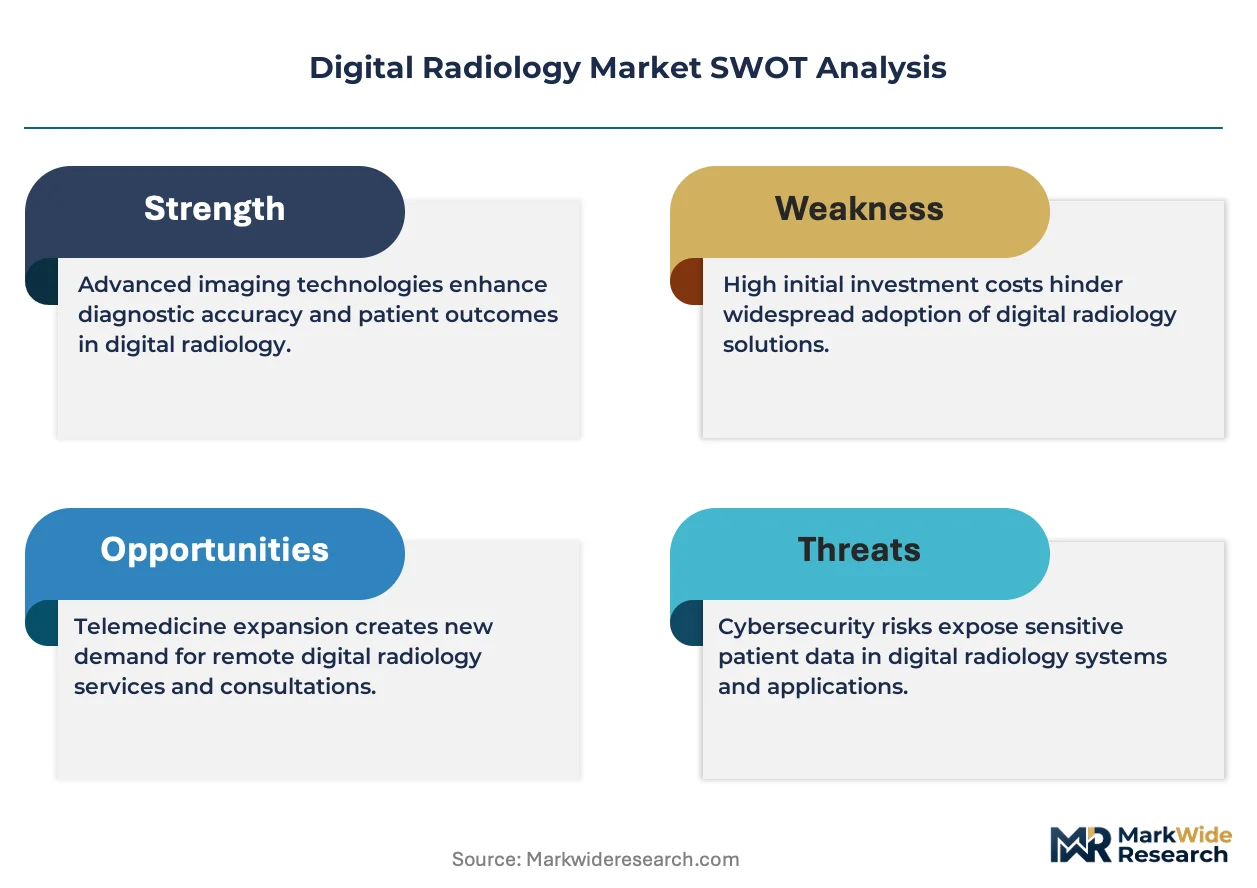
Cloud-connected imaging suites are compressing replacement cycles for capital equipment as hospital networks prioritize operational expenditure models over upfront hardware acquisition. This shift forces vendors to restructure revenue recognition from single-sale transactions to recurring service architectures.
Growth Catalysts
- AI-assisted diagnostic software:FDA clearance pathways are accelerating time-to-market for algorithm developers, reducing regulatory friction for new entrants seeking 510(k) premarket notification.
- University hospital consortia in Germany:Standardization on vendor-neutral PACS architectures creates procurement pull for interoperable imaging platforms.
- Spectral imaging capabilities:CT scanner upgrades incorporating dual-energy reconstruction algorithms drive replacement demand among academic medical centers.
Market Restraints
- Detective quantum efficiency thresholds:Premium flat-panel detectors exceeding 70 percent DQE coefficients require rare-earth scintillator materials concentrated in Chinese processing facilities.
- HIPAA security rule mandates:Technical safeguards for electronic protected health information impose infrastructure costs that disadvantage smaller diagnostic center operators.
- Ultrasound point-of-care substitution:Portable diagnostic units capture margin in low-acuity settings, constraining revenue per procedure for fixed radiography installations.
Strategic Opportunities
- Remote diagnostics platforms:Software-defined subscription layers enable teleradiology services penetrating rural hospital networks in the United States.
- EU AI Act compliance frameworks:Conformity assessment pathways for software-as-a-medical-device create first-mover advantage for vendors with established clinical evidence packages.
- Predictive maintenance algorithms:Integration of machine learning with field service networks transforms multi-year maintenance contracts into data-monitored uptime guarantees.
Industry Challenges
- Radiologist workflow integration:AI-augmented read interfaces require retraining of diagnostic staff, creating adoption friction in high-volume emergency departments.
- PACS migration complexity:Legacy DICOM archive systems resist seamless transfer to cloud-native architectures, extending implementation timelines for hospital IT departments.
- Reimbursement authority fragmentation:National frameworks for AI-augmented reads shift purchasing decisions between radiology departments and centralized procurement offices unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Radiology Market |
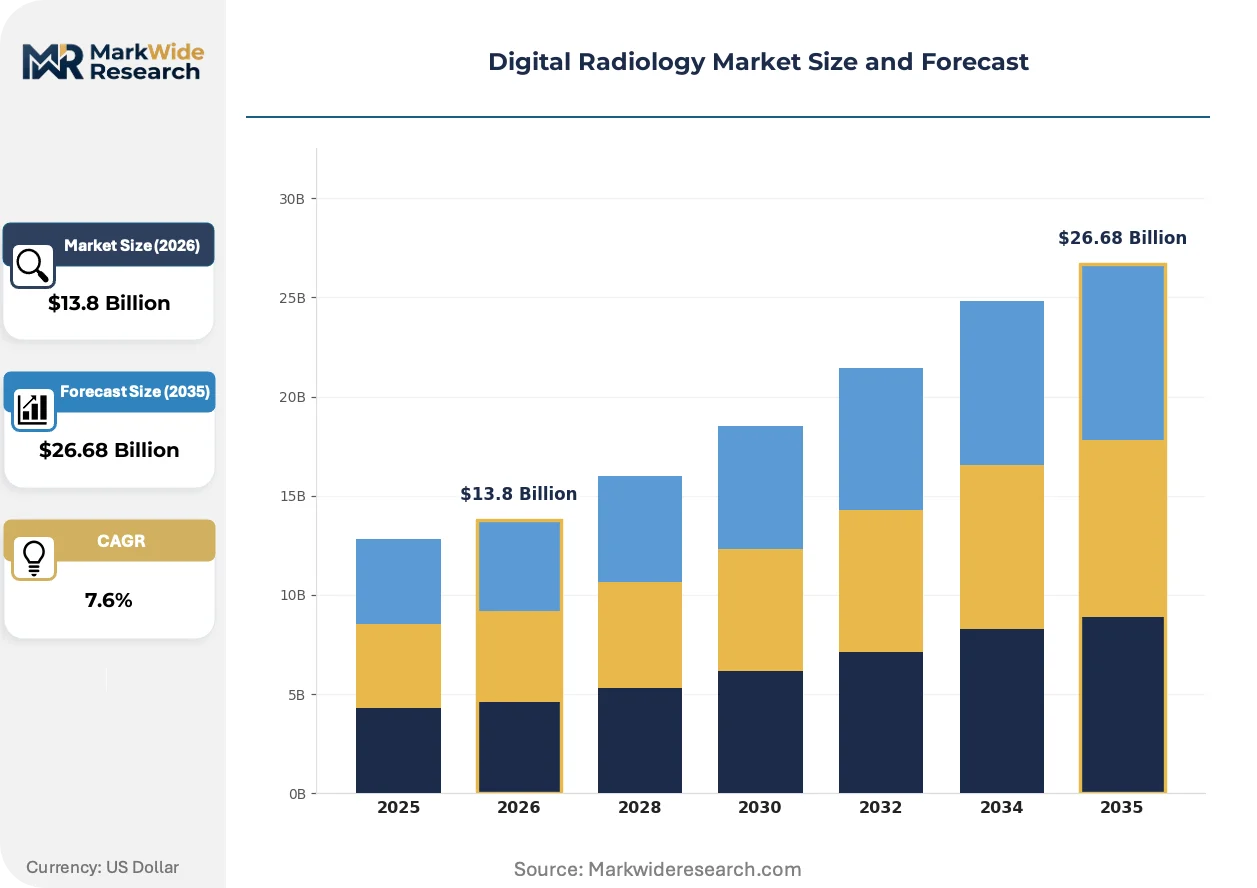
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Systems, MRI Machines, CT Scanners, Ultrasound Devices End User: Hospitals, Diagnostic Centers, Clinics, Research Institutions Technology: Computed Radiography, Digital Radiography, PACS, Cloud-Based Solutions Application: Oncology, Orthopedics, Cardiology, Neurology |
| Companies Covered | Siemens Healthineers, GE Healthcare, FUJIFILM Holdings, Canon Medical Systems, Koninklijke Philips, Agfa-Gevaert Group, Shimadzu Corporation, Varex Imaging Corporation, Carestream Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Radiology Market Strategic Shifts & Innovations
Photon-counting detector technology is redefining dose-efficiency benchmarks across CT modalities, compressing the performance gap between premium and mid-tier system configurations. This hardware evolution intersects with regulatory pressure on radiation exposure limits and operational demands for higher patient throughput.
Photon-counting CT detectors are consolidating market segmentation by enabling spectral imaging at standard-dose protocols previously requiring dual-source architectures. Academic medical centers in Switzerland and the Netherlands are replacing conventional energy-integrating detectors at accelerated replacement cycles. The technology is consolidating vendor R&D priorities toward single-source spectral platforms, marginalizing dual-source hardware investments.
EU Medical Device Regulation clinical evidence requirements for software-as-a-medical-device classifications are extending PACS and AI module approval timelines in European markets. Manufacturers must now submit prospective validation studies for algorithm performance claims previously accepted through retrospective analyses. Radiology departments in France and Italy are delaying procurement decisions pending MDR certificate issuance, compressing near-term revenue recognition for vendors.
Hospital procurement offices are unbundling after-sales service contracts from hardware leases, forcing vendors to compete for maintenance revenue on standalone terms. Integrated delivery networks in the United States are centralizing imaging equipment decisions under chief financial officer oversight rather than radiology department chairs. This concentration of purchasing authority favors vendors with transparent remote monitoring capabilities and predictable spare parts logistics.
Digital Radiology Market Segmentation
Vendor revenue recognition and procurement authority distribute unevenly across segmentation axes. Equipment replacement cycles, software subscription models, and reimbursement frameworks each favor distinct category configurations.
Product Type:
Standardization dominates high-volume modalities while premium configurations retain customization for academic medical centers.
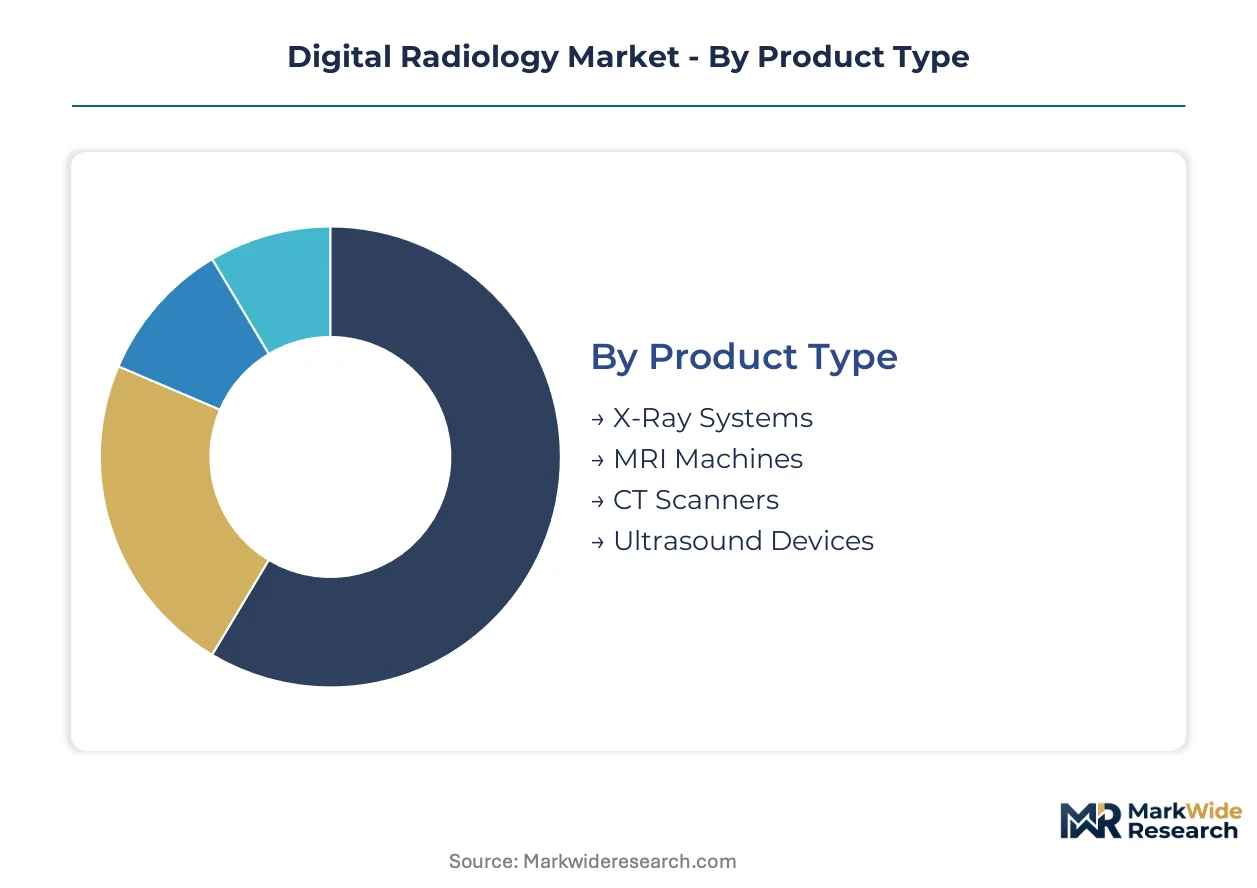
- CT Scanners:Gantry speed upgrades and spectral imaging capabilities drive replacement demand among academic medical centers. Revenue concentrates in dual-energy and photon-counting configurations as Switzerland and the Netherlands accelerate detector refresh cycles. Most installed capacity flows through CT Scanners. Expansion is steepest in Ultrasound Devices.
- Ultrasound Devices:Portable point-of-care units expand service reach without facility construction costs. Diagnostic centers in Germany capture margin through handheld systems deployed in outpatient settings.
- X-Ray Systems:Flat-panel detectors with detective quantum efficiency coefficients exceeding 70 percent command premium positioning in hospital networks.
- MRI Machines:Superconducting magnet maintenance contracts and helium supply constraints shape total cost of ownership calculations for procurement offices.
Most installed capacity flows through CT Scanners. Expansion is gaining share fastest in Ultrasound Devices.
End User:
Purchasing authority concentrates differently by facility scale, with centralized procurement offices displacing department-level decision rights in consolidated networks.
- Hospitals:Integrated delivery networks in the United States centralize imaging equipment decisions under chief financial officer oversight. Cloud-connected imaging suites compress replacement cycles as operational expenditure models displace upfront capital acquisition.
- Diagnostic Centers:Margin capture concentrates in ultrasound services where portable units enable point-of-care deployment without infrastructure investment.
- Clinics:Smaller operators face HIPAA technical safeguard costs that disadvantage procurement of premium flat-panel detector systems.
- Research Institutions:University hospital consortia in Germany standardize on vendor-neutral PACS architectures that prioritize interoperability over single-vendor integration.
Revenue volume concentrates in Hospitals. Adoption friction is lowest in Diagnostic Centers.
Technology:
Capital-to-operational expenditure shifts reshape competitive positioning across hardware and software layers.
- Cloud-Based Solutions:Hospital IT departments shift capital expenditure to operational expenditure models through subscription architectures. FDA clearance pathways for AI-assisted diagnostic software accelerate algorithm deployment across rural hospital networks.
- PACS:Legacy DICOM archive systems resist seamless transfer to cloud-native architectures, extending implementation timelines for hospital IT departments in France and Italy pending EU Medical Device Regulation certificate issuance.
- Digital Radiography:Electronic detectors and computerized reconstruction algorithms deliver spatial resolutions ranging from 0.1 to 0.2 millimeters in premium flat-panel configurations.
- Computed Radiography:Cassette-based systems persist in cost-constrained settings where replacement cycles lag detector technology advancement.
Procurement momentum favors Cloud-Based Solutions. Legacy infrastructure delays are most pronounced in PACS.
Application:
Workflow integration requirements and AI algorithm training data availability segment demand by clinical specialty.
- Oncology:Spectral imaging capabilities and dual-energy reconstruction algorithms enable tissue characterization for treatment planning. Philips integrates enterprise imaging software with oncology workflows across integrated delivery networks.
- Cardiology:Siemens Healthineers bundles algorithm updates with hardware leases targeting cardiac CT and MRI protocols.
- Orthopedics:Weight-bearing radiography and musculoskeletal MRI protocols drive detector specification requirements in sports medicine centers.
- Neurology:AI-augmented read interfaces for stroke protocols require retraining of diagnostic staff, creating adoption friction in high-volume emergency departments.
Software integration investment is deepest in Oncology. Regulatory validation timelines extend furthest in Neurology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting imaging equipment procurement toward jurisdictions with streamlined medical device approval pathways and harmonized data protection standards. Vendors optimize manufacturing footprints across compliance-cost gradients while hospital networks prioritize interoperability certifications in procurement decisions.
United States
Integrated delivery networks centralize imaging procurement under chief financial officer oversight, compressing vendor sales cycles. FDA 510(k) premarket notification pathways for AI-assisted diagnostic software accelerate algorithm deployment timelines. Mayo Clinic and Cleveland Clinic anchor demand for photon-counting CT configurations in the Upper Midwest.
Germany
University hospital consortia standardize on vendor-neutral PACS architectures, creating procurement pull for interoperable platforms. EU Medical Device Regulation clinical evidence requirements extend software-as-a-medical-device approval timelines. Berlin-Brandenburg and Bavaria concentrate replacement demand for spectral imaging capabilities in academic medical centers.
China
Hospital networks expand procurement of cloud-connected imaging suites under operational expenditure models. NMPA medical device registration pathways compress time-to-market for domestic algorithm developers. Yangtze River Delta medical device clusters in Shanghai and Jiangsu Province drive flat-panel detector manufacturing scale.
Japan
Superconducting magnet maintenance contracts and helium supply constraints shape total cost of ownership calculations for procurement offices. PMDA pharmaceutical and medical device agency harmonization with FDA standards accelerates dual-approval strategies. Kanto region Tokyo-based hospital networks prioritize predictive maintenance algorithm integration.
Switzerland
Academic medical centers accelerate photon-counting detector replacement cycles ahead of EU radiation exposure limit tightening. Swissmedic conformity assessment pathways for software-as-a-medical-device create first-mover positioning for vendors with established clinical evidence packages. Basel and Zurich university hospitals anchor spectral imaging demand in the Alpine corridor.
Digital Radiology Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with full-system vendors capturing hardware lease revenue while component suppliers feed modular upgrade pathways. Market structure concentrates around three strategic archetypes: diversified conglomerates with in-house AI pipelines, pure-play imaging equipment specialists, and detector component fabricators serving multiple OEMs. Dominant competitive moves include restructuring revenue recognition toward recurring service architectures and unbundling maintenance contracts from hardware leases.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify the integrated-platform archetype, bundling algorithm development with field service network scale. Koninklijke Philips occupies a position emphasizing enterprise software integration across cardiology and oncology workflows. These three anchors represent divergent strategic postures within the premium-tier vendor landscape, each leveraging distinct capability foundations to capture procurement authority shifts in consolidated hospital networks.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| FUJIFILM Holdings |
| Canon Medical Systems |
| Koninklijke Philips |
| Agfa-Gevaert Group |
| Shimadzu Corporation |
| Varex Imaging Corporation |
| Carestream Health |
| Others |
Cost & Logistics Intelligence
Detector-grade scintillator bifurcation separates premium flat-panel systems from cost-constrained cassette-based configurations, with this performance gap manifesting in both subscription-tier pricing for cloud-connected suites and concentrated rare-earth sourcing through Chinese processing nodes. Hospital procurement offices exploit this divergence by unbundling maintenance contracts from hardware leases, forcing vendors to compete for service revenue on standalone terms while diagnostic centers absorb HIPAA technical safeguard premiums that disadvantage smaller operators.
Pricing Analysis
Distributor markups on replacement detector arrays compress margins for independent service organizations while direct-to-hospital leasing arrangements by Siemens Healthineers and GE Healthcare preserve pricing power through bundled algorithm updates. Three-tier pricing structure across premium photon-counting, standard dual-energy, and economy flat-panel configurations tracks detective quantum efficiency certification thresholds rather than brand positioning alone. Cost compression in mid-tier CT configurations intensifies as academic medical centers accelerate photon-counting refresh cycles, dumping energy-integrating detectors into secondary markets. Rural hospital networks exhibit highest price sensitivity due to constrained capital expenditure authority, whereas integrated delivery networks under CFO oversight prioritize total cost-of-ownership metrics over acquisition price.
Supply Chain Analysis
China's rare-earth processing mandates under MIIT guidelines reshape scintillator sourcing for premium flat-panel detectors, compelling Japanese and German OEMs to establish qualified supplier relationships with Yangtze River Delta refiners. Gadolinium oxide and cesium iodide crystals draw from concentrated Chinese separation facilities, while helium for MRI superconducting magnets rests on Qatari and Algerian liquefaction infrastructure. Single-source vulnerability in terbium-doped phosphor supply creates exposure to export license delays. Distribution runs through authorized service depots in regional hospital clusters rather than traditional medical device distributors, with predictive maintenance algorithms enabling remote spare parts logistics that bypass intermediate inventory positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photon-counting detector penetration signals late-cycle quality migration, with academic medical centers in Switzerland and the Netherlands demanding spectral imaging capabilities that obsolete conventional energy-integrating architectures within standard replacement horizons.
For Market Incumbents: Deepen predictive maintenance algorithm integration with field service networks to transform multi-year contracts into uptime-guaranteed subscriptions, insulating against hospital procurement office unbundling pressure. Acquire detector component fabricators in the Yangtze River Delta to secure rare-earth scintillator supply continuity amid Chinese processing concentration. Prioritize FDA 510(k) pathway expertise as AI-assisted diagnostic software compresses regulatory timelines for algorithm entrants. For New Entrants and Emerging Players: Rural hospital networks in the United States represent the most penetrable buyer archetype, with teleradiology subscription models bypassing capital expenditure constraints that exclude these operators from hardware procurement. Target diagnostic centers in Germany seeking vendor-neutral PACS architectures that incumbent conglomerates resist supporting. Deploy software-as-a-medical-device offerings through cloud-native platforms to circumvent legacy DICOM migration complexity that delays hospital IT implementations. For Investors and Strategic Acquirers: Consolidation pressure builds where AI development pipelines require clinical evidence packages exceeding standalone capital thresholds. Five-to-ten year viability favors diversified conglomerates with in-house algorithm capabilities over pure-play equipment vendors exposed to hardware lease margin compression. Acquisition target archetype: detector component specialists with established Chinese rare-earth supplier relationships and EU MDR conformity assessment documentation. Signal to watch: NMPA registration pathway harmonization accelerating domestic Chinese algorithm developer market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Platform Migration | Spectral imaging at standard-dose protocols consolidates vendor R&D priorities toward single-source architectures. |
| EU MDR Clinical Evidence Package Development | Prospective validation studies for software-as-a-medical-device create first-mover positioning in French and Italian procurement delays. |
| Cloud-Native PACS Architecture Deployment | Subscription revenue recognition displaces single-sale transactions as hospital IT shifts capital expenditure to operational models. |
| Predictive Maintenance Algorithm Integration | Machine learning with field service networks transforms maintenance contracts into data-monitored uptime guarantees. |
| Vendor-Neutral Archive Interoperability Certification | German university hospital consortia standardization creates procurement pull for platforms decoupled from single-vendor lock-in. |
Research Approach
Direct dialogue with hospital procurement officers, radiology department chairs, biomedical engineers, and GPO contracts managers grounded qualitative assessment, cross-referenced against FDA 510(k) premarket notification databases, EU MDR certificate registries, hospital procurement databases, and CMS Medicare reimbursement filings. Secondary validation incorporated customs records on rare-earth scintillator trade flows and SEC filings from listed imaging equipment vendors. Bottom-up equipment installation tracking and top-down revenue triangulation converged on segment-level estimates.
Bottom-up modeling aggregated replacement cycle timing by modality across academic medical centers, community hospitals, and diagnostic centers, while top-down analysis calibrated aggregate vendor revenue recognition patterns. Segmentation dimensions spanned product type, end-user facility scale, technology deployment model, and clinical application workflow. CAGRs derived from fitted growth curves anchored to disclosed procurement volumes and spectral imaging capability penetration rates. Forecast inputs incorporated NMPA registration pathway velocity and EU AI Act conformity assessment timeline assumptions.
Underlying measurement precision varies by segment; photon-counting CT and cloud-based solutions carry tighter precision than cassette-based computed radiography due to disclosed vendor shipment data availability. Forecasts reflect documented assumptions on replacement cycle compression and reimbursement framework evolution. Reimbursement authority fragmentation between radiology departments and centralized procurement offices poses revision risk to hardware demand timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Global Dental Panoramic Radiography Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
Radiographic Film Processor Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
Industrial Radiography Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
Healthcare Cloud Picture Archiving and Communications System Market
Medical Imaging
Global Veterinary CT Scanner Market