
 Healthcare Chatbots Market | 2026-2036
Healthcare Chatbots Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Chatbots Market Intelligence
Demand for healthcare chatbots is rotating from large-scale hospital systems towards direct-to-consumer telemedicine providers and mental health platforms. This shift favors vendors with agile, API-first deployment models. Babylon Holdings Limited leverages its established telehealth infrastructure to integrate chatbot-led triage. Ada Health GmbH specializes in AI-driven symptom assessment, while Woebot Labs focuses specifically on the mental wellness segment.
Healthcare chatbots are AI-powered software applications that use natural language processing (NLP) to interact with patients. These systems are designed to conduct initial patient triage, schedule appointments, or provide medical information, often integrating with Electronic Health Record (EHR) systems. Symptom checker functionalities represent a foundational and mature product type. However, the fastest-growing applications are now in the Mental Health Assistant and Chronic Disease Management therapy areas, where continuous patient engagement is critical.
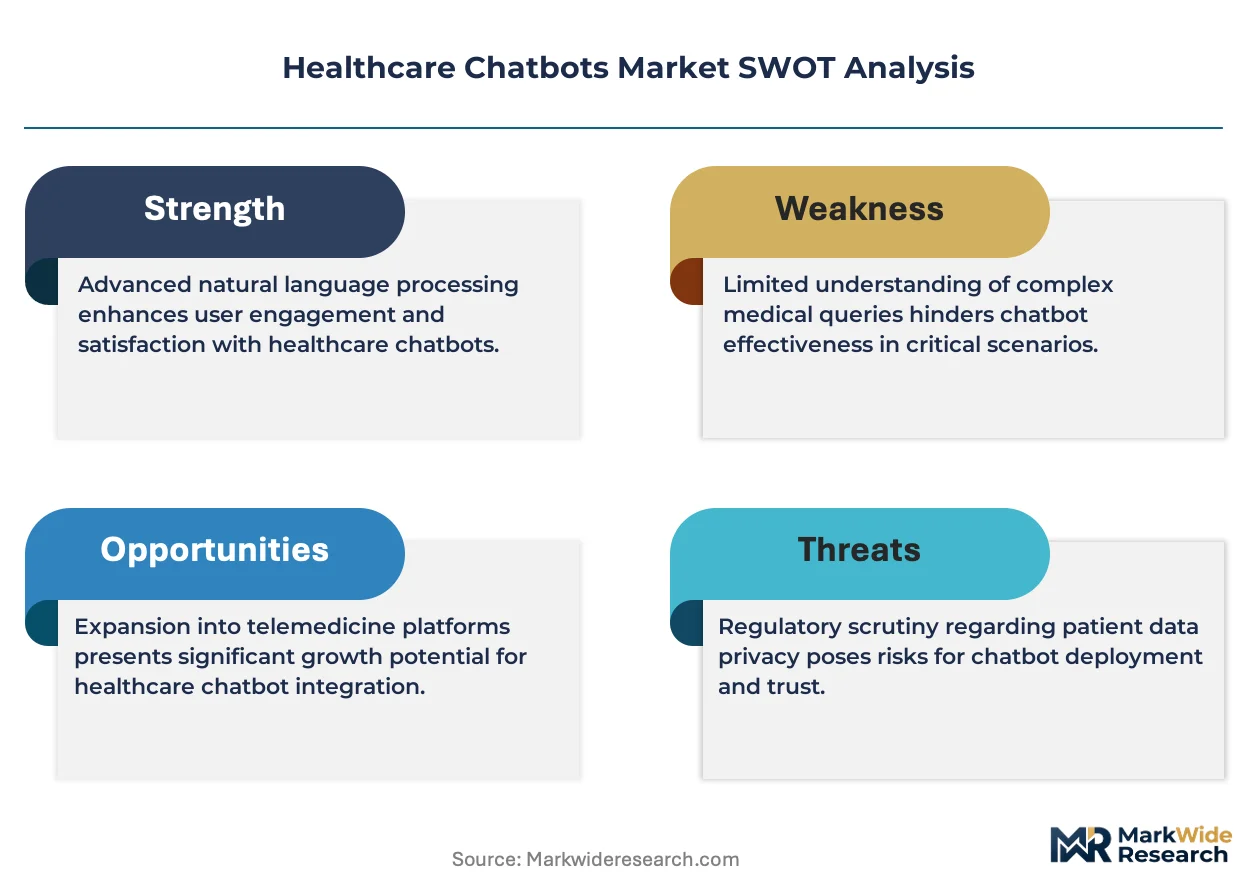
Regulatory frameworks like HIPAA in the United States and GDPR in Europe impose strict data privacy and security requirements on chatbot developers. Furthermore, classification under regulations such as the EU's Medical Device Regulation (MDR) can determine the pathway to market for diagnostic-intent bots. The key strategic decision for vendors is whether to pursue clinical-grade, regulated applications or focus on lower-risk wellness and administrative functions.
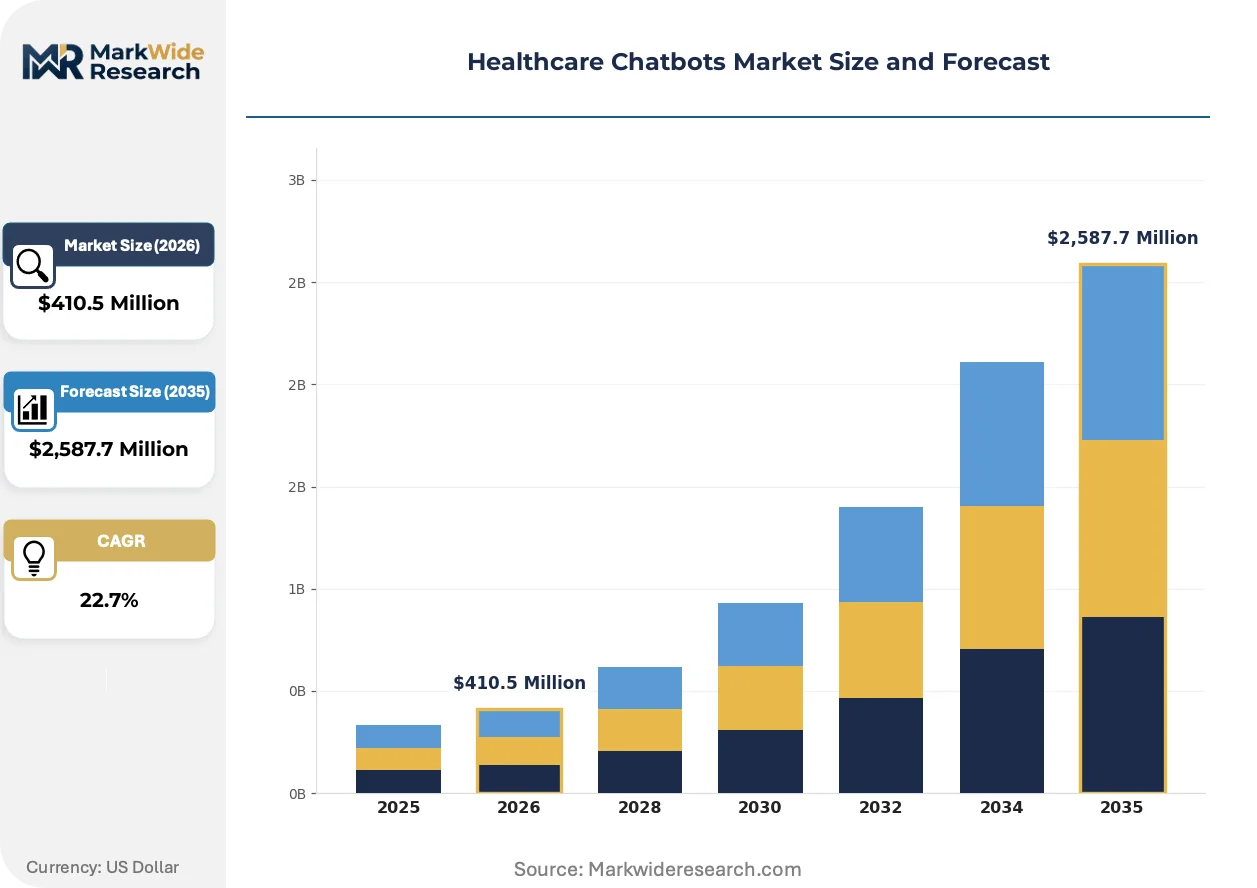
Market Dynamics
The market's central dynamic is the tension between rapid advancements in natural language processing and the stringent regulatory requirements governing patient data and medical advice. This creates a bifurcation between high-risk clinical applications and lower-risk administrative or wellness tools.
Growth Catalysts
- National Digital Health Initiatives:China's policy to integrate digital platforms into the national healthcare system accelerates the deployment of chatbots for patient management and public health communication.
- Telemedicine Provider Adoption:Direct-to-consumer telemedicine companies are scaling their use of chatbots for patient intake, triage, and follow-up, driving demand for API-first solutions.
- Chronic Disease Management Focus:The need for continuous patient engagement in managing conditions like diabetes and hypertension is a primary catalyst for chatbots that support adherence and monitoring.
Market Restraints
- EU MDR Classification:The stringent requirements of the EU's Medical Device Regulation (MDR) for diagnostic-intent chatbots create high compliance costs and long development timelines, limiting market entry.
- EHR System Interoperability:The lack of standardized APIs across legacy Electronic Health Record (EHR) systems presents a significant technical barrier to seamless data exchange and workflow integration.
- HIPAA and GDPR Compliance:The high cost and complexity of ensuring continuous compliance with data privacy regulations like HIPAA in the US and GDPR in Europe restrain development, especially for smaller vendors.
Strategic Opportunities
- Southeast Asian Markets:Growing mobile connectivity and healthcare investment in countries like Indonesia and Vietnam present significant opportunities for deploying lightweight, mobile-first chatbot solutions.
- Post-Operative Care:A clear opportunity exists for chatbots to automate post-surgical follow-up, monitor for complications, and ensure patient adherence to recovery protocols, reducing hospital readmissions.
- Generative AI Integration:Incorporating large language models to enhance the empathetic capabilities of mental wellness chatbots represents a major area for product differentiation and user engagement.
Industry Challenges
- Lack of Clinical Validation Skills:A talent shortage exists for professionals with expertise in both AI development and the design of clinical trials needed to validate the efficacy and safety of diagnostic chatbots.
- Integrating with Hospital IT Infrastructure:The operational challenge of integrating chatbot platforms with diverse and often outdated hospital IT systems, including security protocols, delays implementation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Chatbots Market |
| Market Size in 2026 | $410.5 Million |
| Market Size in 2035 | $2,587.7 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Symptom Checker, Appointment Scheduler, Medication Reminder, Mental Health Assistant, Wellness Coach, Insurance Support Therapy Area: Chronic Disease Management, Mental Wellness, Preventive Care, Postoperative Care, Geriatric Support, Pediatric Assistance End User: Hospitals, Clinics, Telemedicine Providers, Diagnostic Centers, Home Healthcare, Research Institutions Deployment Mode: Cloud-Based, On-Premises, Hybrid, Mobile App, Web-Based, API Integration |
| Companies Covered | Ada Health GmbH, Babylon Holdings Limited, Buoy Health, Inc., Sensely, Inc., Infermedica Sp. z o.o., Woebot Labs, Creative Virtual Ltd., GYANT, Inc., HealthJoy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Chatbots Market Strategic Shifts & Innovations
The evolution from scripted, single-purpose chatbots to sophisticated conversational AI platforms defines the current market trajectory. This transition is driven by advancements in natural language understanding and the demand for more personalized and empathetic patient interactions.
Generative AI, specifically large language models, enables chatbots to create dynamic, context-aware, and empathetic responses beyond pre-programmed scripts. Mental health and wellness platforms are rapidly adopting this technology to provide more human-like supportive conversations. The use of generative AI for nuanced dialogue is displacing the reliance on rigid, decision-tree-based logic that characterized earlier generations of symptom checkers and administrative bots.
The European Union's AI Act introduces a risk-based framework for artificial intelligence systems, classifying many healthcare chatbots as high-risk. This regulation mandates stringent requirements for data quality, transparency, and human oversight for developers targeting the EU market. Chatbot vendors specializing in diagnostic or triage functions are most affected, needing to build robust risk management systems into their product lifecycle.
Healthcare providers are moving away from monolithic, all-in-one chatbot platforms toward procuring specialized, best-of-breed solutions for specific functions. This unbundling disrupts vendors offering a single suite, favoring API-first companies that specialize in appointment scheduling, symptom triage, or mental health support. This trend is most visible in the competitive United States telemedicine market, where providers integrate multiple specialized bots into a cohesive patient journey.
Healthcare Chatbots Market Segmentation
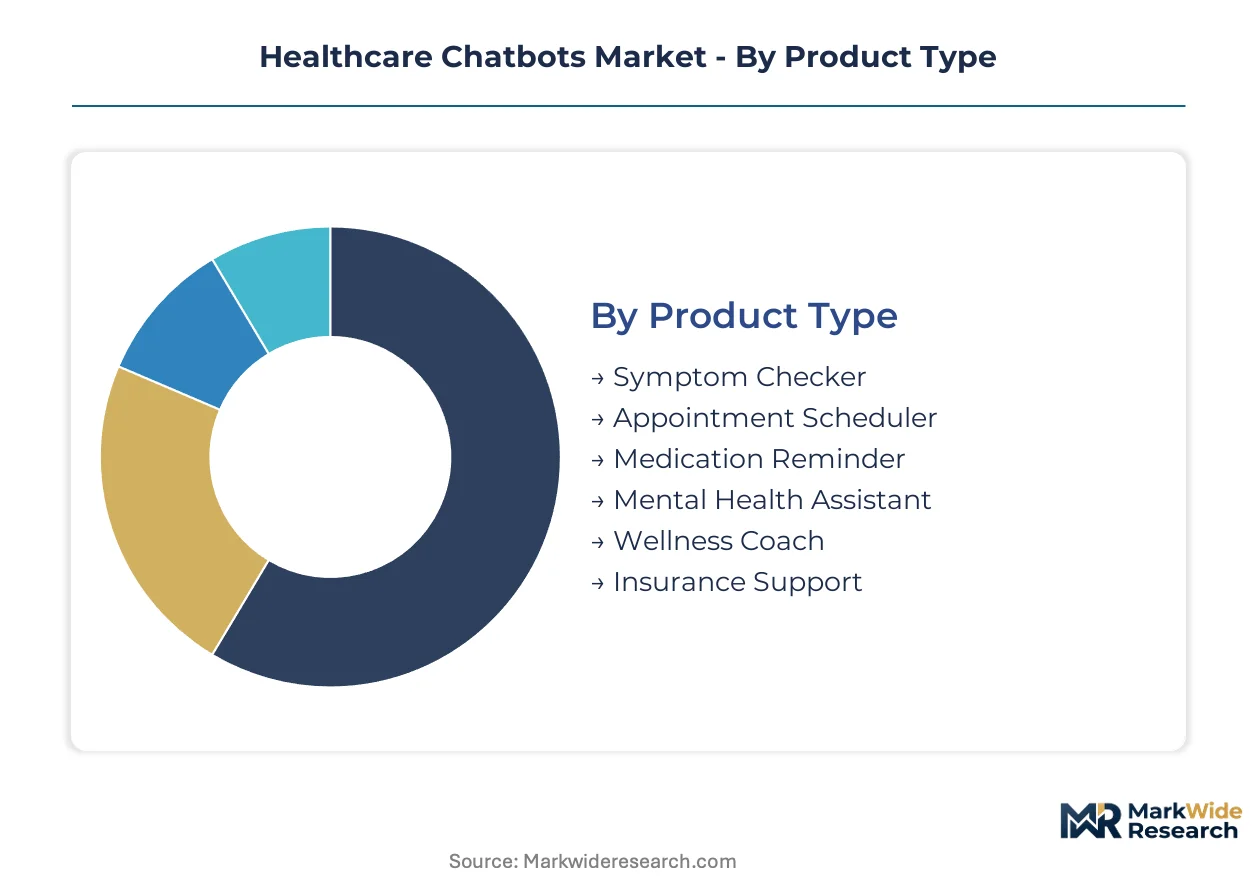
The healthcare chatbots market exhibits diverse applications and deployment models, reflecting varied patient needs and provider operational structures. Understanding these distinct segments is crucial for vendors to tailor product development and market entry strategies effectively. Market participants must align their offerings with specific user requirements and regulatory pathways.
Product Type:
Regulatory frameworks such as the EU AI Act and MDR significantly differentiate product types, with diagnostic-intent chatbots facing the most stringent compliance requirements. This classification dictates development costs and market access pathways for various chatbot functionalities.
- Symptom Checker:These AI-powered tools leverage natural language processing to assess patient-reported symptoms, offering preliminary diagnoses or recommending appropriate care pathways. Demand remains foundational in initial patient triage, particularly within primary care settings and urgent care platforms across Europe and North America.
- Mental Health Assistant:These applications provide empathetic, conversational support for mental wellness, often integrating generative AI for nuanced interactions. Rapid adoption is occurring on direct-to-consumer platforms and specialized mental health apps, driven by the need for continuous patient engagement in the US and UK.
- Appointment Scheduler:Chatbots automate the booking and management of patient appointments, reducing administrative burden for healthcare providers.
- Medication Reminder:These bots send automated alerts to patients, promoting adherence to prescribed medication regimens and improving health outcomes.
- Wellness Coach:Chatbots offer personalized guidance and motivation for lifestyle changes, focusing on preventative care and chronic disease self-management.
- Insurance Support:These systems assist patients with queries regarding insurance coverage, claims processing, and policy details, streamlining administrative tasks.
Established volume favors Symptom Checker; emerging adoption favors Mental Health Assistant.
Therapy Area:
The specific therapy area dictates the level of continuous patient engagement required and the potential for long-term health outcome improvements. Different therapeutic needs drive distinct chatbot functionalities and integration requirements.
- Chronic Disease Management:Chatbots provide ongoing support for patients with conditions like diabetes or hypertension, facilitating medication adherence, symptom monitoring, and lifestyle coaching. This segment sees significant demand from integrated health systems in Germany and digital health platforms in China, aiming to reduce hospital readmissions.
- Mental Wellness:These chatbots offer accessible, scalable support for psychological well-being, ranging from stress management to cognitive behavioral therapy exercises. The fastest growth is observed in the United States and the UK, where there is a strong focus on early intervention and destigmatization of mental health support.
- Preventive Care:Chatbots promote healthy behaviors and provide educational content to prevent the onset of diseases.
- Postoperative Care:These systems automate follow-up instructions, monitor recovery progress, and identify potential complications after surgical procedures.
- Geriatric Support:Chatbots assist elderly patients with daily routines, medication reminders, and social engagement, improving independent living.
- Pediatric Assistance:These applications offer guidance and information to parents regarding children's health, development, and common ailments.
The market is observing Mental Wellness expanding most quickly, while Chronic Disease Management maintains a stable base.
End User:
The operational models and IT infrastructure of end-user segments significantly influence chatbot deployment strategies and integration complexities. Each end-user type presents unique challenges and opportunities for vendors.
- Telemedicine Providers:These direct-to-consumer platforms integrate chatbots for efficient patient intake, initial triage, and follow-up communication, leveraging API-first solutions. Demand is concentrated in the US and Canada, where virtual care models are rapidly scaling to meet patient access needs.
- Hospitals:Large-scale hospital systems deploy chatbots for administrative tasks, appointment scheduling, and patient information dissemination. Integration with legacy Electronic Health Record (EHR) systems presents a significant technical barrier for these institutions, particularly in established markets like Germany and Japan.
- Clinics:Smaller healthcare facilities use chatbots to streamline patient flow, manage appointments, and provide basic information, enhancing operational efficiency.
- Diagnostic Centers:Chatbots assist with appointment booking for imaging and lab tests, provide pre-procedure instructions, and communicate results.
- Home Healthcare:These services utilize chatbots for remote patient monitoring, medication reminders, and routine check-ins, supporting care in residential settings.
- Research Institutions:Chatbots aid in patient recruitment for clinical trials, data collection, and providing information about ongoing studies.
Operational efficiency gains are most pronounced in Telemedicine Providers, with Hospitals focusing on patient access.
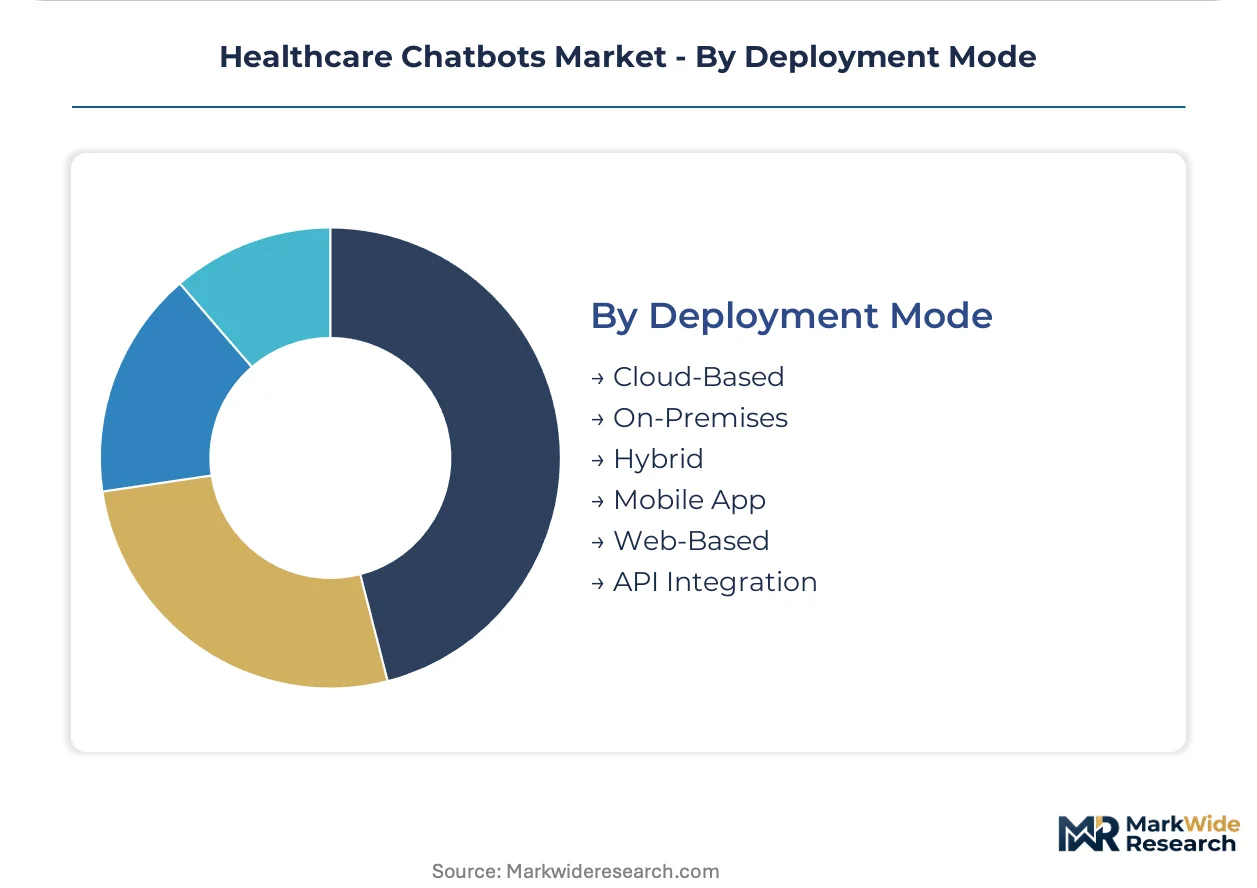
Deployment Mode:
The choice of deployment mode reflects an organization's IT infrastructure, data security requirements, and desired scalability. Each mode offers distinct advantages for integration and data management within healthcare environments.
- API Integration:This mode allows seamless embedding of chatbot functionalities into existing digital health platforms and Electronic Health Record systems. Agile telemedicine providers and specialized solution vendors in the US and UK prioritize API-first models for flexible and scalable service delivery.
- Mobile App:Chatbots deployed as standalone or integrated mobile applications offer direct patient access and convenience, particularly for wellness and mental health support. Markets in Southeast Asia, with high mobile penetration, are driving demand for these accessible solutions.
- Cloud-Based:These deployments leverage external servers for hosting, offering scalability and reduced infrastructure costs, favored by many startups and smaller clinics.
- On-Premises:Enterprises with stringent data privacy requirements, such as large hospital systems, prefer on-premises solutions for maximum control over sensitive patient data.
- Hybrid:This approach combines elements of cloud and on-premises deployment, balancing scalability with data security and compliance needs.
- Web-Based:Chatbots accessible directly through web browsers provide broad reach and ease of access for patients without requiring app downloads.
The shift towards agile, scalable solutions favors API Integration, contrasting with the established presence of Cloud-Based deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The robust global digital health infrastructure, particularly mobile connectivity, underwrites the expanding adoption of healthcare chatbots. This facilitates patient engagement and administrative efficiencies across diverse markets. Demand concentration is notable in key economies with evolving digital health landscapes.
United States
Telemedicine providers in the United States prioritize chatbots for efficient patient intake and follow-up, driving demand for API-first solutions. HIPAA regulations impose stringent data privacy requirements on all chatbot developers operating within the country. The competitive US telemedicine market, particularly in California, integrates multiple specialized bots into patient journeys.
China
National digital health initiatives in China accelerate chatbot deployment for patient management and public health communication. The government's policy actively integrates digital platforms into the national healthcare system. Major digital health platforms in cities like Beijing are central to this widespread integration.
Germany
Integrated health systems in Germany show demand for chronic disease management chatbots, aiming to reduce hospital readmissions. The EU MDR classification significantly impacts diagnostic-intent bots, requiring high compliance costs and long development timelines. Digital health startups in Berlin are exploring these regulated clinical applications.
United Kingdom
Mental wellness platforms in the United Kingdom rapidly adopt generative AI-enhanced chatbots for empathetic and continuous support. GDPR compliance is a critical factor for all patient-facing applications handling sensitive data. London's vibrant health tech ecosystem fosters innovation in direct-to-consumer mental health apps.
Indonesia
Growing mobile connectivity and healthcare investment in Indonesia drive demand for lightweight, mobile-first chatbot solutions. The country's digital health policies support accessible services for its large, dispersed population. Jakarta's tech hubs see active development of patient engagement platforms tailored for mobile users.
Healthcare Chatbots Market Key Industry Players
Concentration sits with agile, API-first vendors serving direct-to-consumer telemedicine providers. The market exhibits a tiered structure, from highly regulated clinical-grade applications to lower-risk administrative tools. Strategic archetypes include specialized mental wellness platforms and AI-driven symptom assessment providers. Companies pursue strategic partnerships and portfolio diversification to capture niche segments.
Specialists in AI-driven symptom assessment like Ada Health GmbH exemplify the focus on preliminary diagnoses and care pathway recommendations. Babylon Holdings Limited occupies a position leveraging established telehealth infrastructure for chatbot-led triage and patient management. Woebot Labs, Inc. represents the dedicated mental wellness segment, emphasizing continuous patient engagement through conversational AI. These companies anchor distinct solution approaches within the evolving market.
| Leading Market Players |
|---|
| Ada Health GmbH |
| Babylon Holdings Limited |
| Buoy Health, Inc. |
| Sensely, Inc. |
| Infermedica Sp. z o.o. |
| Woebot Labs |
| Creative Virtual Ltd. |
| GYANT, Inc. |
| HealthJoy |
| Others |
Cost & Logistics Intelligence
Generative AI's displacement of fixed decision-tree logic simultaneously reshapes vendor talent pools and allows for more flexible pricing models based on conversational complexity. This shift encourages a re-evaluation of development costs versus user engagement value.
Pricing Analysis
Volume-based subscription tiers dominate the healthcare chatbot market, reflecting usage scale and feature sets. Price differentiation stems from the complexity of natural language processing models and the level of integration with Electronic Health Record systems. Pricing pressure stems from the commoditization of basic administrative functions, particularly for smaller clinics. Telemedicine providers exhibit lower price sensitivity for solutions offering high patient engagement.
Supply Chain Analysis
Stringent data privacy regulations like HIPAA and GDPR represent a critical supply chain chokepoint for chatbot developers. Cloud infrastructure providers in the United States and Ireland host much of the core AI processing, creating regional concentration. Core dependencies include large language models and specialized medical ontologies. Single-source vulnerability for specific AI models poses a structural risk. Distribution runs through API integrations into digital health platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a high-growth disruption, driven by the rapid evolution of generative AI capabilities. This technology fundamentally alters patient interaction and service delivery models.
For Market Incumbents: Secure specialized talent in clinical AI validation to maintain a competitive edge against emerging AI-first startups. Incumbents must acquire smaller, agile firms with proven mental wellness or chronic disease management solutions. This strategy mitigates the threat of being outmaneuvered by rapid innovation in niche segments. Investment in API-first deployment models is a crucial lever.
For New Entrants and Emerging Players: Unaddressed post-operative care needs present a significant service-layer gap for new entrants. Focus on lightweight, mobile-first solutions for specific therapy areas like geriatric support in Southeast Asian markets. A value-based pricing model tied to reduced readmission rates offers a compelling go-to-market angle. Emphasize regulatory compliance as a core product feature.
For Investors and Strategic Acquirers: The market sits at an early-growth phase that favors specialized AI-driven platforms with strong clinical validation. Long-term viability depends on solutions that integrate seamlessly with existing EHR systems and demonstrate clear patient outcomes. Monitor the EU AI Act's high-risk classification as a signal for future regulatory compliance costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire Mental Wellness AI Specialist | Integrates advanced generative AI for empathetic patient support, enhancing product differentiation. |
| Develop API-First Integration Modules | Facilitates seamless embedding of chatbot functions into diverse telemedicine platforms across the US. |
| Invest in Clinical Validation Trials | Establishes efficacy and safety for diagnostic-intent chatbots, enabling market access in Germany. |
| Expand to Southeast Asian Mobile Markets | Captures new user bases with lightweight solutions, leveraging high mobile connectivity in Indonesia. |
| Implement Robust Data Privacy Frameworks | Ensures compliance with HIPAA and GDPR, mitigating regulatory risks for global operations. |
Research Approach
Operator-level perspectives from telemedicine executives, hospital IT managers, AI developers, and regulatory affairs specialists anchored the qualitative base for this analysis. Primary interviews were combined with secondary validation from health authority reports, academic studies, and digital health platform disclosures. This approach ensured a robust bottom-up and top-down triangulation of market insights.
Sensitivity analysis informed the quantitative modeling, assessing various adoption scenarios for healthcare chatbots. The analytical framework projected market growth across the analysis window, segmenting by product type, therapy area, end-user, and deployment mode. Compound Annual Growth Rates were derived from historical data trends and projected technological advancements. Key forecast inputs included digital health investment trends and regulatory evolution.
Forecasts assume regulatory continuity in HIPAA and GDPR regimes; material policy shifts would require re-modeling. The analysis reflects current technological trajectories and market dynamics. Practitioners should keep alternative scenarios live as AI development and healthcare policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
US Real World Evidence Solutions Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Global Physical Therapy Software Market
Digital Health Solutions
Asia-Pacific Heart Failure Software Market
Digital Health Solutions
Global Behavioral/Mental Health Software Market
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Digital Therapeutics Market
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Global Health Kiosk Market
Digital Health Solutions
Virtual Reality (VR) in Healthcare Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Global Patient Centric Healthcare App Market