
 AI-Powered Clinical Decision Support Market | 2026-2036
AI-Powered Clinical Decision Support Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Powered Clinical Decision Support Market Insights
The capital-intensity divergence between cloud-native specialists and legacy platform incumbents is reorganizing competitive dynamics in clinical AI. Epic Systems Corp. dominates inpatient workflow integration through its embedded AI modules within the EHR stack. IBM sustains significant R&D commitments to natural language processing for unstructured clinical notes. Signal 1 leverages lean operational architecture to compete on deployment speed for mid-sized hospital networks.
AI-powered clinical decision support encompasses software systems that analyze patient data, medical literature, and institutional protocols to generate evidence-based recommendations at the point of care, typically processing structured and unstructured inputs through machine learning pipelines with sub-second inference latency for real-time workflow integration. Diagnostic tools command the largest installed base across hospitals, while predictive analytics applications in cardiology represent the fastest-expanding margin pool as health systems prioritize readmission reduction. Natural language processing capabilities are maturing rapidly in oncology documentation, though treatment planning modules remain concentrated among research institutions with specialized informatics teams.
The FDA software-as-a-medical-device framework and HIPAA security rule collectively shape product architecture requirements, mandating algorithmic transparency documentation and encrypted patient data handling that extends development timelines by months. The EU AI Act's high-risk system classification for clinical decision tools creates parallel compliance obligations for vendors seeking European market access. Stakeholders must monitor evolving premarket review pathways as regulators distinguish between assistive recommendation engines and autonomous diagnostic systems.
Market Dynamics
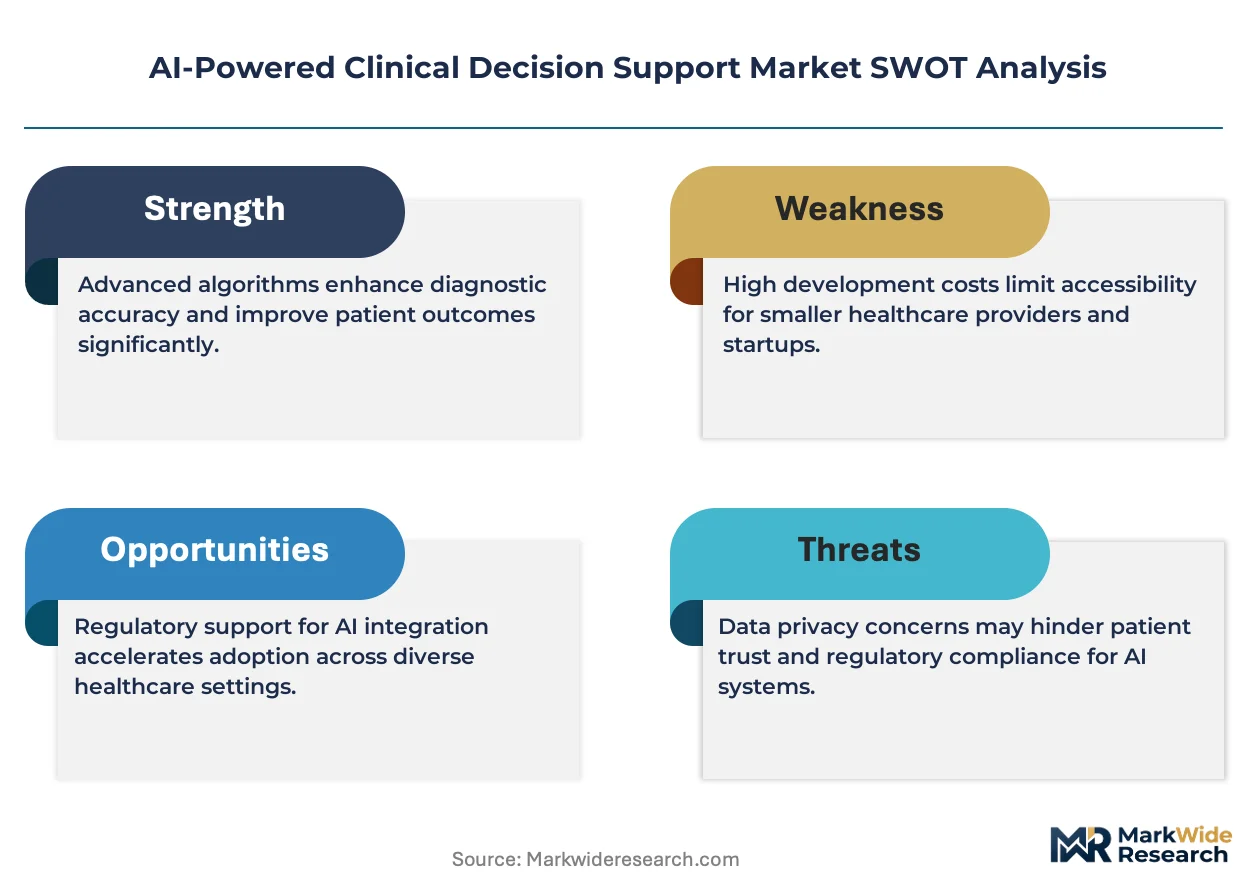
The FDA's software-as-a-medical-device framework is compressing product development timelines while fragmenting vendor compliance capabilities across algorithmic transparency and validation documentation requirements.
Growth Catalysts
- FDA SaMD pathway maturation:The FDA's pre-certification pilot for AI/ML-based software is accelerating market entry for validated diagnostic algorithms in radiology and cardiology workflows.
- Epic Systems embedded AI modules:Enterprise EHR deployments with native decision support integration are reducing implementation friction for health systems seeking workflow-native intelligence.
- Natural language processing pipelines:Unstructured clinical note analysis capabilities are expanding addressable data volumes beyond structured EHR fields into pathology reports and discharge summaries.
Market Restraints
- Algorithmic validation costs:Multi-site clinical trials required for FDA SaMD clearance impose seven-figure development expenditures that concentrate capability among well-capitalized vendors.
- Specialized talent scarcity:Dual expertise in clinical medicine and machine learning engineering commands compensation premiums exceeding 40% above pure technology roles.
- Interoperability fragmentation:Proprietary data formats across EHR platforms create integration bottlenecks that extend deployment timelines and inflate professional services requirements.
Strategic Opportunities
- Mid-sized hospital networks:Community health systems with 200-500 beds remain underserved by enterprise-focused vendors, creating whitespace for modular, cloud-native deployment models.
- EU AI Act high-risk system classification:Early compliance with European algorithmic transparency mandates positions vendors for first-mover advantage as the regulation activates enforcement mechanisms.
- Edge computing convergence:On-premise inference hardware is enabling sub-50 millisecond latency for time-critical applications in emergency department triage and surgical decision support.
Industry Challenges
- Clinical workflow integration complexity:Alert fatigue from poorly calibrated recommendation engines is driving physician resistance that undermines adoption metrics and contract renewals.
- HIPAA technical safeguard compliance:Encrypted data handling requirements for machine learning training pipelines demand specialized infrastructure investments that strain operational budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Powered Clinical Decision Support Market |
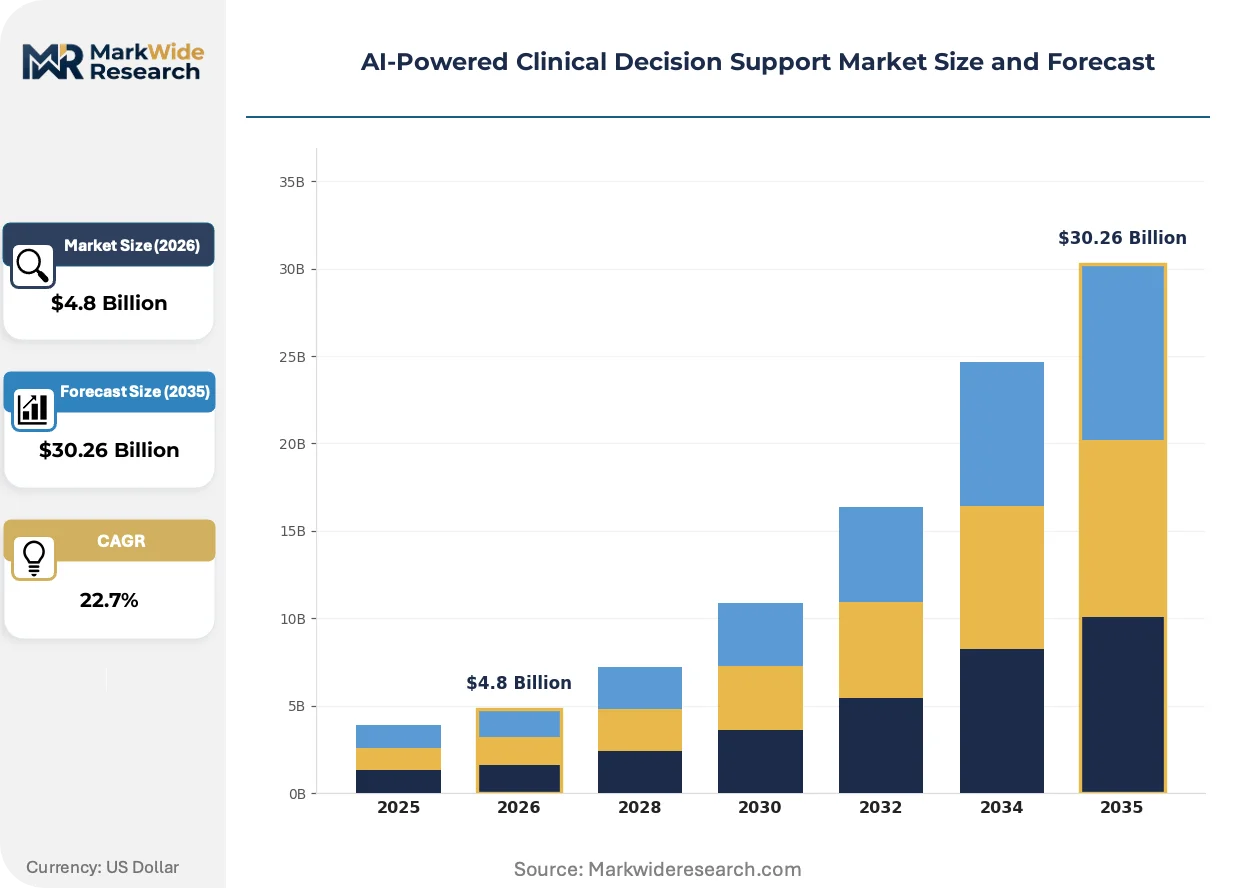
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tools, Treatment Planning, Risk Assessment, Workflow Optimization End User: Hospitals, Clinics, Telehealth Providers, Research Institutions Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Data Mining Application: Oncology, Cardiology, Neurology, Primary Care |
| Companies Covered | Change Healthcare, Elsevier Health, IQVIA, Signal 1, WELL Health Technologies Corp., VisualDx, IBM, Epic Systems Corp., Oracle Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Powered Clinical Decision Support Market Trends and Innovations
Foundation models trained on multimodal clinical data are compressing development cycles for specialized diagnostic applications while raising new questions about attribution and clinical liability frameworks.
Multimodal diagnostic AI is fragmenting competitive positioning across radiology, pathology, and genomics as vendors race to integrate imaging, laboratory, and molecular data streams into unified inference architectures. Academic medical centers with proprietary biobanks are licensing data assets to commercial developers, accelerating model training while creating exclusive distribution arrangements that lock out second-tier competitors. The resulting capability concentration is compressing margins for single-modality point solutions and forcing consolidation among specialized diagnostic AI vendors.
The EU AI Act's high-risk system classification for clinical decision support tools is mandating conformity assessments and post-market monitoring obligations that extend beyond FDA SaMD requirements. Vendors seeking European market access must document algorithmic performance across demographic subgroups and maintain human oversight protocols that increase operational overhead. Cardiology and oncology applications face the most stringent scrutiny, prompting several developers to sequence regulatory submissions with EU clearance preceding US commercialization.
Hospital procurement committees are unbundling decision support modules from enterprise EHR contracts and evaluating standalone vendors on specialty-specific performance benchmarks. Radiology departments increasingly source computer-aided detection directly from imaging equipment manufacturers, bypassing EHR-integrated alternatives. This channel fragmentation is most visible in the United States, where health system consolidation has concentrated purchasing authority within centralized value analysis committees that prioritize interoperability over single-vendor convenience.
AI-Powered Clinical Decision Support Market Segmentation
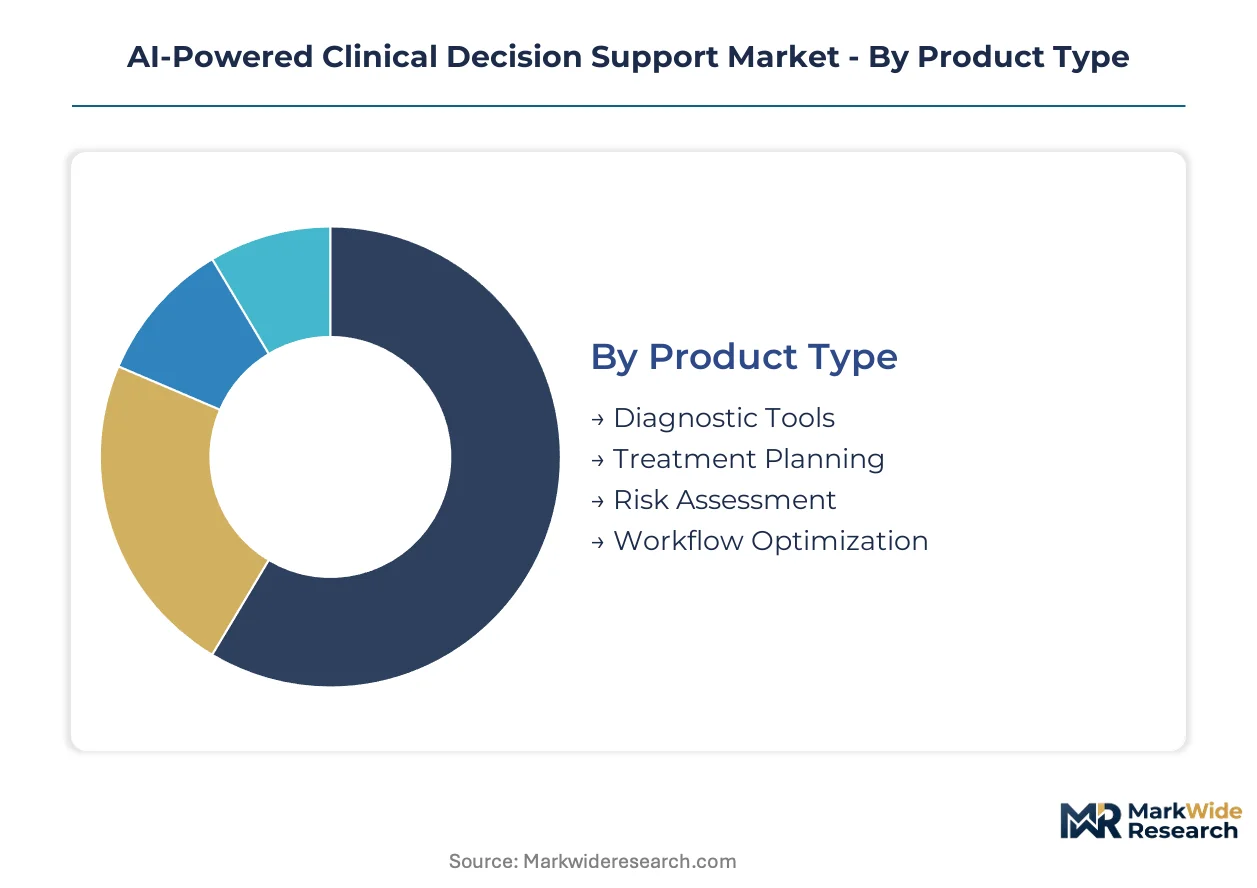
Segmentation in clinical AI reveals how substitution pressures and workflow integration requirements reshape procurement patterns across health systems. Product architecture choices determine whether vendors compete on embedded EHR compatibility or standalone specialty performance.
Product Type:
Diagnostic Tools face intensifying substitute pressure from imaging equipment manufacturers bundling computer-aided detection directly into hardware platforms.
- Diagnostic Tools:Algorithms analyzing medical images, laboratory results, and physiological signals to flag abnormalities for physician review. Demand concentrates in radiology departments within United States health systems seeking FDA-cleared computer-aided detection for mammography and chest CT workflows. Equipment manufacturers embedding these capabilities threaten standalone software vendors.
- Treatment Planning:Systems synthesizing patient history, genomic profiles, and clinical guidelines to recommend therapeutic protocols. Research institutions with specialized informatics teams in Germany and the Netherlands represent the concentrated demand pool, constrained by liability frameworks for autonomous recommendations.
- Risk Assessment:Predictive models stratifying patient populations by readmission probability or disease progression likelihood.
- Workflow Optimization:Tools automating documentation, scheduling, and resource allocation within clinical operations.
Diagnostic Tools retains volume leadership; Treatment Planning holds the steepest expansion curve as precision medicine protocols mature.
End User:
Cost tier stratification separates enterprise health systems with capital budgets for integrated deployments from resource-constrained community providers seeking modular solutions.
- Hospitals:Acute care facilities with 500+ beds deploying enterprise-wide decision support across multiple service lines. Epic Systems embedded AI modules dominate procurement in United States health systems prioritizing EHR-native integration over best-of-breed specialty tools.
- Clinics:Outpatient facilities with limited IT infrastructure requiring cloud-native deployment models and subscription pricing. Mid-sized networks in France and Italy represent underserved whitespace where Signal 1 competes on implementation speed.
- Telehealth Providers:Virtual care platforms integrating asynchronous diagnostic support and automated triage protocols.
- Research Institutions:Academic medical centers licensing proprietary biobank assets to commercial developers for model training.
Hospitals command the largest installed base; Telehealth Providers are climbing the fastest as virtual care platforms expand diagnostic capabilities.
Technology:
Application maturity varies sharply across technology foundations, with production deployment lagging research capability by several years in natural language processing.
- Machine Learning:Supervised and unsupervised algorithms trained on structured clinical data for pattern recognition tasks. Cardiology applications in the United States show the fastest clinical validation progress, driven by health system priorities around readmission reduction and CMS quality metrics.
- Natural Language Processing:Pipelines extracting structured insights from unstructured clinical notes, pathology reports, and discharge summaries. Oncology documentation in Germany demonstrates rapid capability maturation, though treatment planning modules remain concentrated among research institutions.
- Predictive Analytics:Time-series models forecasting patient deterioration, resource utilization, or disease trajectory.
- Data Mining:Pattern discovery across heterogeneous clinical databases to identify population-level insights and protocol variations.
Machine Learning retains deployment scale leadership; Natural Language Processing is gaining share fastest as unstructured data volumes expand beyond EHR structured fields.
Application:
Customer type differentiation separates research-intensive specialties requiring multimodal data integration from high-volume primary care workflows demanding sub-second inference latency.
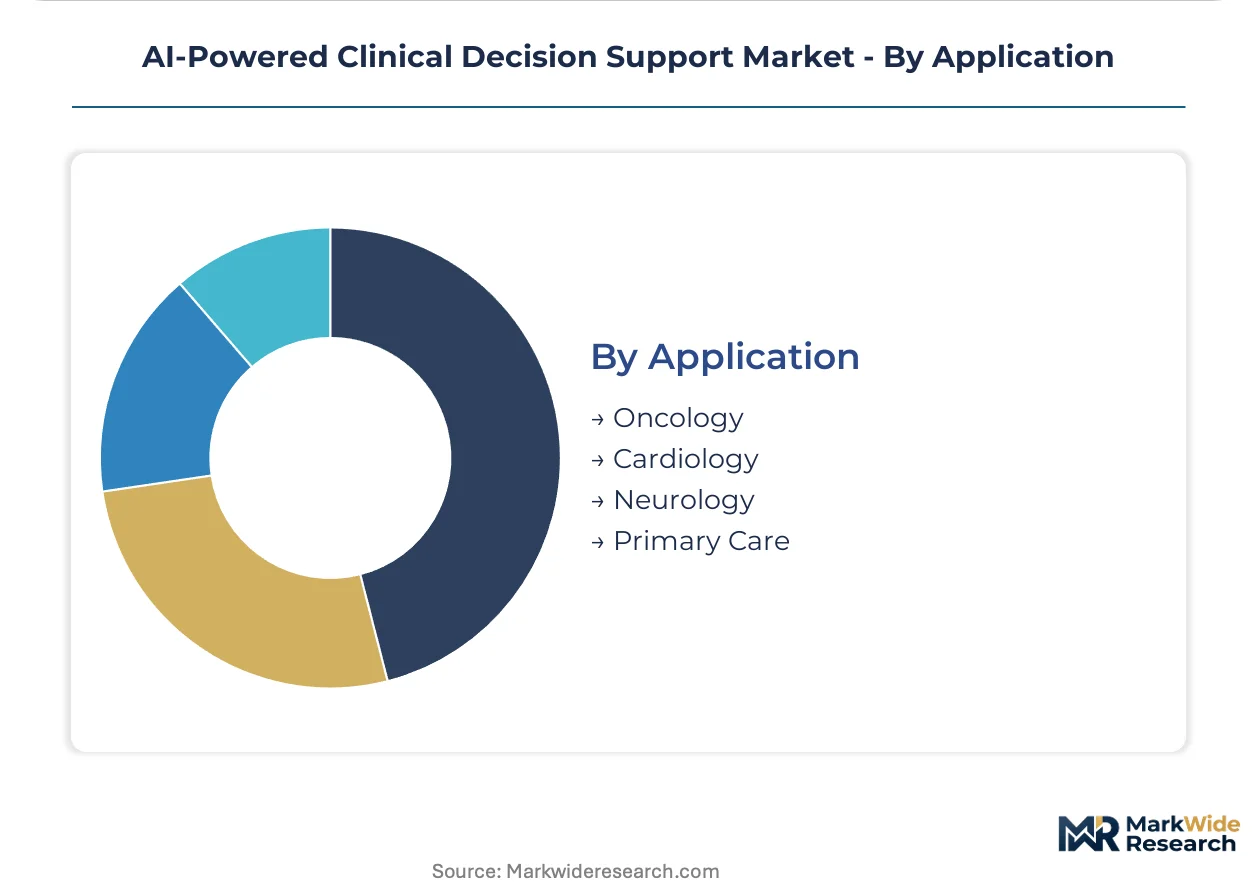
- Oncology:Multimodal AI integrating imaging, genomics, and clinical history for tumor characterization and therapy selection. Academic medical centers in Switzerland and the Netherlands license proprietary biobank assets, creating exclusive distribution arrangements that accelerate model training while locking out second-tier competitors.
- Cardiology:Predictive analytics for arrhythmia detection, heart failure risk stratification, and interventional planning. United States health systems prioritize these applications for readmission reduction, with the fastest margin pool expansion across diagnostic AI segments.
- Neurology:Algorithms for stroke detection, seizure prediction, and neurodegenerative disease monitoring.
- Primary Care:Broad-spectrum decision support for common conditions, medication interactions, and preventive care protocols.
Cardiology retains revenue concentration leadership; Oncology holds the steepest expansion trajectory as precision medicine protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes AI-powered clinical decision support through embedded EHR modules, while European health systems favor standalone specialty tools with explicit algorithmic transparency documentation.
United States
Epic Systems and Oracle anchor enterprise deployments across major health systems prioritizing workflow-native integration. FDA software-as-a-medical-device framework mandates algorithmic transparency documentation that extends development timelines. The Greater Boston cluster concentrates academic medical centers licensing proprietary biobank assets to commercial developers.
Germany
Research institutions in Heidelberg and Munich drive demand for treatment planning modules with specialized informatics teams. EU AI Act high-risk system classification imposes conformity assessments beyond FDA requirements. The Baden-Württemberg region hosts precision medicine protocols integrating multimodal diagnostic data streams.
United Kingdom
NHS trusts evaluate standalone vendors on specialty-specific performance benchmarks rather than EHR-integrated convenience. MHRA alignment with FDA SaMD pathways accelerates parallel regulatory submissions for cardiology applications. London's academic hospitals concentrate oncology documentation capabilities with rapid NLP maturation.
Switzerland
Academic medical centers in Zurich and Basel license proprietary biobank assets creating exclusive distribution arrangements. Swissmedic maintains stringent post-market surveillance that shapes product architecture for European market access. The Basel cluster concentrates pharmaceutical informatics expertise accelerating precision medicine model training.
Netherlands
Community health systems with 200-500 beds represent underserved whitespace for modular cloud-native deployment models. EMA guidance on AI-based medical devices influences national procurement criteria for algorithmic validation. The Amsterdam-Rotterdam corridor concentrates telehealth platform development integrating asynchronous diagnostic support.
AI-Powered Clinical Decision Support Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier competing on deployment velocity and specialty depth. Epic Systems Corp. and Oracle dominate inpatient workflow integration through embedded EHR modules, while leaner cloud-native vendors target mid-sized hospital networks. Strategic archetypes separate enterprise platform incumbents, vertical AI specialists, and modular workflow optimizers. Competitive moves concentrate on M&A for data asset access and strategic partnerships with academic medical centers for validation cohorts.
Within the enterprise platform tier, Epic Systems Corp. and Oracle Corp. exemplify integrated leaders leveraging captive EHR relationships. Signal 1 occupies a position among cloud-native specialists competing on implementation speed for resource-constrained networks. IBM represents the legacy technology conglomerate archetype sustaining R&D commitments to natural language processing capabilities.
| Leading Market Players |
|---|
| Change Healthcare |
| Elsevier Health |
| IQVIA |
| Signal 1 |
| WELL Health Technologies Corp. |
| VisualDx |
| IBM |
| Epic Systems Corp. |
| Oracle Corp. |
| Others |
Pricing and Supply Chain Analysis
Cloud-native deployment models replacing on-premise infrastructure are redistributing supply geography toward hyperscaler data centers while compressing pricing premiums for traditional enterprise software licensing. This substitution simultaneously erodes margin pools for legacy platform incumbents and creates volume opportunities for modular SaaS vendors serving mid-sized hospital networks.
Pricing Analysis
After-sales revenue from multi-year implementation contracts and professional services integration drives lifetime value for enterprise EHR-embedded solutions. The dominant pricing structure stratifies across enterprise, mid-market, and community-hospital tiers based on deployment complexity and customization depth. Price differentiation rests on FDA SaMD clearance status and Epic Systems integration certification. Cost compression in the mid-market tier is intensifying because Signal 1 and cloud-native competitors compete on implementation speed. Community hospital networks with 200-500 beds exhibit highest price sensitivity, while academic medical centers with specialized informatics teams demonstrate lowest sensitivity due to research funding offsets.
Supply Chain Analysis
The United States and Germany anchor algorithmic development and clinical validation cohorts for FDA and EU AI Act compliance pathways. Taiwan and South Korea supply GPU clusters and edge inference hardware enabling sub-50 millisecond latency for emergency department applications. The supply chain draws from specialized machine learning engineering talent pools concentrated in Greater Boston and Zurich, plus cloud infrastructure provisioning from hyperscaler regions. Single-source vulnerability exists around NVIDIA GPU supply for training foundation models. Distribution runs through direct enterprise sales teams for health systems, GPO contracts for mid-sized networks, and OEM partnerships with imaging equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-powered clinical decision support is exiting a regulatory consolidation phase and entering cyclical expansion as FDA SaMD pathway maturation accelerates validated algorithm market entry.
For Market Incumbents: Fortify embedded EHR relationships through exclusive AI module development with Epic Systems and Oracle, while acquiring cloud-native specialists to neutralize Signal 1's deployment speed advantage in mid-sized networks. Vertical integration into proprietary biobank licensing with academic medical centers creates data moats against foundation model commoditization. FDA SaMD validation documentation requirements favor incumbents with seven-figure clinical trial budgets. For New Entrants and Emerging Players: Differentiate on EU AI Act early compliance positioning to capture European market access ahead of US-sanctioned competitors sequencing regulatory submissions. Community health systems in the Netherlands and Italy represent the most penetrable whitespace, underserved by enterprise-focused vendors. A direct-to-clinic SaaS model with subscription pricing and rapid cloud-native deployment addresses procurement committee unbundling trends. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical AI specialists holding FDA-cleared cardiology algorithms but lacking EHR integration depth. Long-term viability over a five-to-ten year window favors vendors with multimodal diagnostic capabilities spanning imaging, genomics, and clinical history. Watch for EU AI Act enforcement activation as inflection indicator for competitive repositioning toward algorithmic transparency documentation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA SaMD Submission Acceleration | Epic Systems-integrated modules gain priority review through pre-certification pilot pathways. |
| EU AI Act Conformity Assessment | Early compliance positions vendors for Swissmedic and EMA-aligned market access advantages. |
| Academic Medical Center Partnership | Heidelberg and Basel biobank licensing creates exclusive training data arrangements. |
| Cloud-Native Platform Integration | Mid-sized Netherlands hospital networks adopt modular deployment models bypassing enterprise EHR contracts. |
| Edge Computing Hardware Partnership | Taiwan-sourced inference chips enable sub-50 millisecond latency for emergency department triage workflows. |
Research Methodology
Desk research of FDA 510(k) clearance databases, CMS Medicare reimbursement filings, and hospital procurement contract disclosures preceded structured interviews with chief medical informatics officers, health system value analysis committee chairs, biomedical engineering directors, and GPO contracts managers. Primary fieldwork across United States, Germany, and Netherlands health systems validated secondary estimates of embedded AI module adoption rates and standalone vendor penetration. Bottom-up installation counts triangulated against top-down health IT expenditure allocations.
Variance decomposition across technology maturity curves, regulatory pathway timelines, and health system consolidation patterns shaped the analytical framework over the projection horizon. Modeled dimensions span product type, end-user scale tier, technology foundation, and clinical application specialty. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated FDA SaMD pre-certification enrollment trajectories and EU AI Act implementation phase transitions.
Material uncertainties — FDA algorithmic transparency rulemaking evolution, hyperscaler GPU supply allocation shifts, and health system bankruptcy restructuring — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and clinical workflow integration friction. Recalibration cycles align with material shifts in FDA pre-certification pilot expansion or EU AI Act enforcement mechanism activation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Asia-Pacific Heart Failure Software Market
Digital Health Solutions
US Digital Therapeutics Market
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Digiceuticals Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Heart Failure Software Market
Digital Health Solutions
Medical Virtual Reality Operating Systems Market
Digital Health Solutions
Mobile Tablets in Healthcare Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
GCC E-Health Market