
 Patient Engagement Platforms Market | 2026-2036
Patient Engagement Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Engagement Platforms Market Analytics
Cloud infrastructure spending by health IT vendors is decoupling from traditional on-premises deployment cycles, reshaping how platforms reach end users. Epic Systems leverages its integrated EHR architecture to anchor enterprise hospital deployments across North America. Cerner Corporation competes through R&D intensity in interoperability standards, while athenahealth specializes in cloud-native workflows for ambulatory clinics.
Patient engagement platforms constitute software systems that enable bidirectional communication between healthcare providers and patients through secure messaging, appointment scheduling, remote monitoring dashboards, and personalized health education content, typically architected on HL7 FHIR APIs for data exchange. These systems serve the industrial purpose of reducing readmission rates and closing care gaps through automated outreach and self-service access to clinical records. Web portals currently dominate enterprise procurement budgets due to legacy system integration requirements, though mobile apps represent the fastest-growing delivery vector as younger patient cohorts expect smartphone-native experiences. Cloud-based deployment captures the deepest margin pools by eliminating client-side infrastructure overhead and enabling subscription pricing models.
FDA guidance on software-as-medical-device classification shapes how vendors architect clinical decision support features, while HIPAA mandates govern data exchange protocols and patient consent workflows. The ONC Cures Act Final Rule enforces information blocking prohibitions that directly expand platform interoperability requirements. Stakeholders must monitor evolving state-level telehealth reimbursement policies to calibrate investment in synchronous versus asynchronous engagement modules.
Market Dynamics
Cloud-native architectures are displacing legacy on-premises deployments across hospital systems, forcing vendors to restructure R&D budgets toward subscription pricing models and API-first development cycles.
Growth Catalysts
- FHIR API Mandates:The ONC Cures Act Final Rule in the United States compels vendors to build interoperable data exchange layers, accelerating platform consolidation.
- Chronic Care Burden:Health systems in Germany deploy patient portals to manage diabetes and cardiovascular disease cohorts through automated outreach workflows.
- Smartphone-First Expectations:Younger patient demographics demand mobile-native appointment scheduling and secure messaging interfaces.
Market Restraints
- Data Localization Requirements:China's Personal Information Protection Law restricts cross-border health data flows, fragmenting vendor cloud infrastructure strategies.
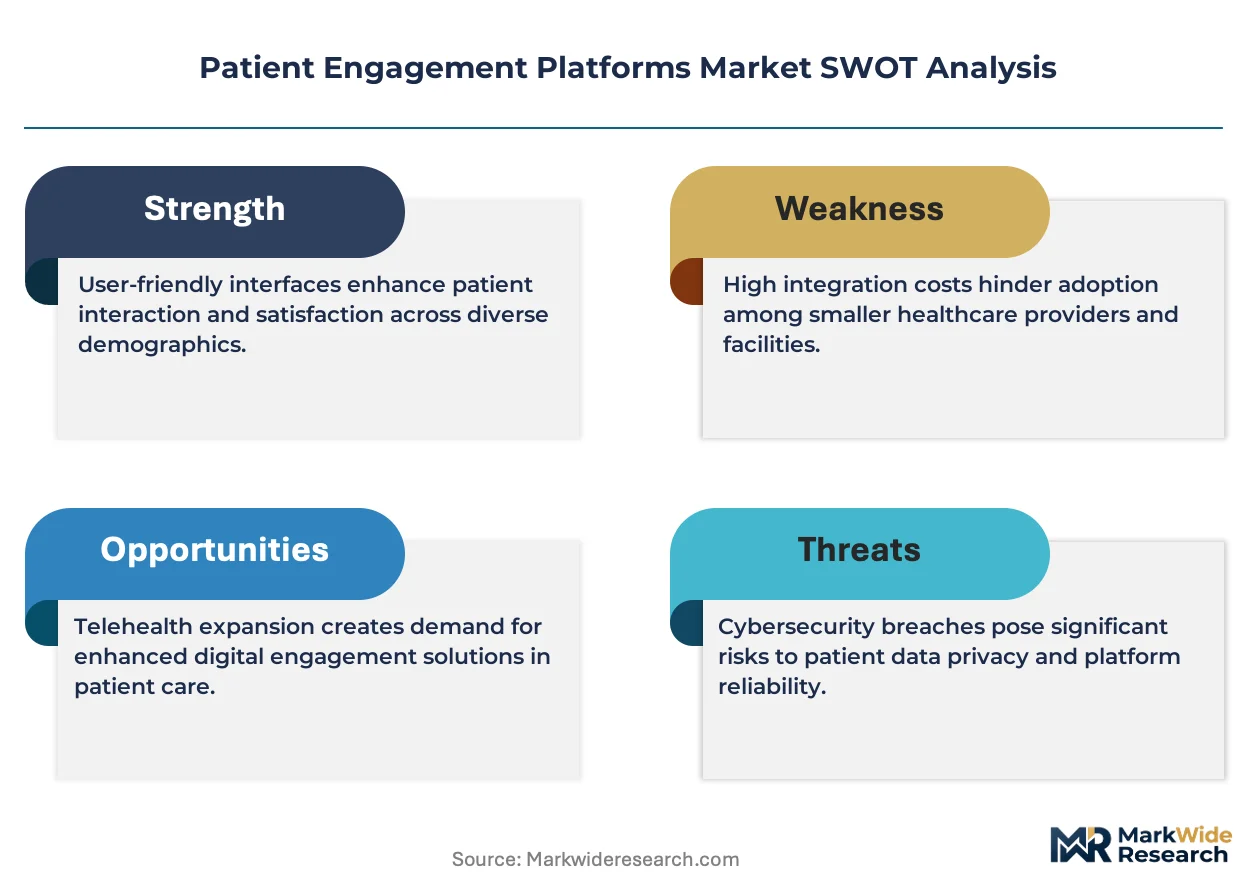
- EHR Vendor Concentration:Dominant electronic health record platforms in North America create integration bottlenecks for third-party engagement modules.
- Cybersecurity Insurance Costs:Ransomware targeting healthcare IT systems drives up operational overhead for cloud-hosted patient data repositories.
Strategic Opportunities
- Rural Hospital Digitization:India's Ayushman Bharat Digital Mission funds patient portal deployment in tier-2 and tier-3 cities with limited IT infrastructure.
- Remote Therapeutic Monitoring:Medicare reimbursement codes in the United States enable billable integration between engagement platforms and connected medical devices.
- AI-Powered Triage:Natural language processing engines are converging with symptom checker modules to reduce nursing call center volume.
Industry Challenges
- Interoperability Talent Scarcity:Health systems struggle to hire engineers proficient in HL7 FHIR R4 implementation and SMART on FHIR authentication protocols.
- Legacy System Integration:Mainframe-based billing systems in established hospitals resist API connectivity, requiring costly middleware development.
- State-Level Telehealth Licensing:Patchwork regulations across United States jurisdictions complicate multi-state provider credentialing for virtual care modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Engagement Platforms Market |
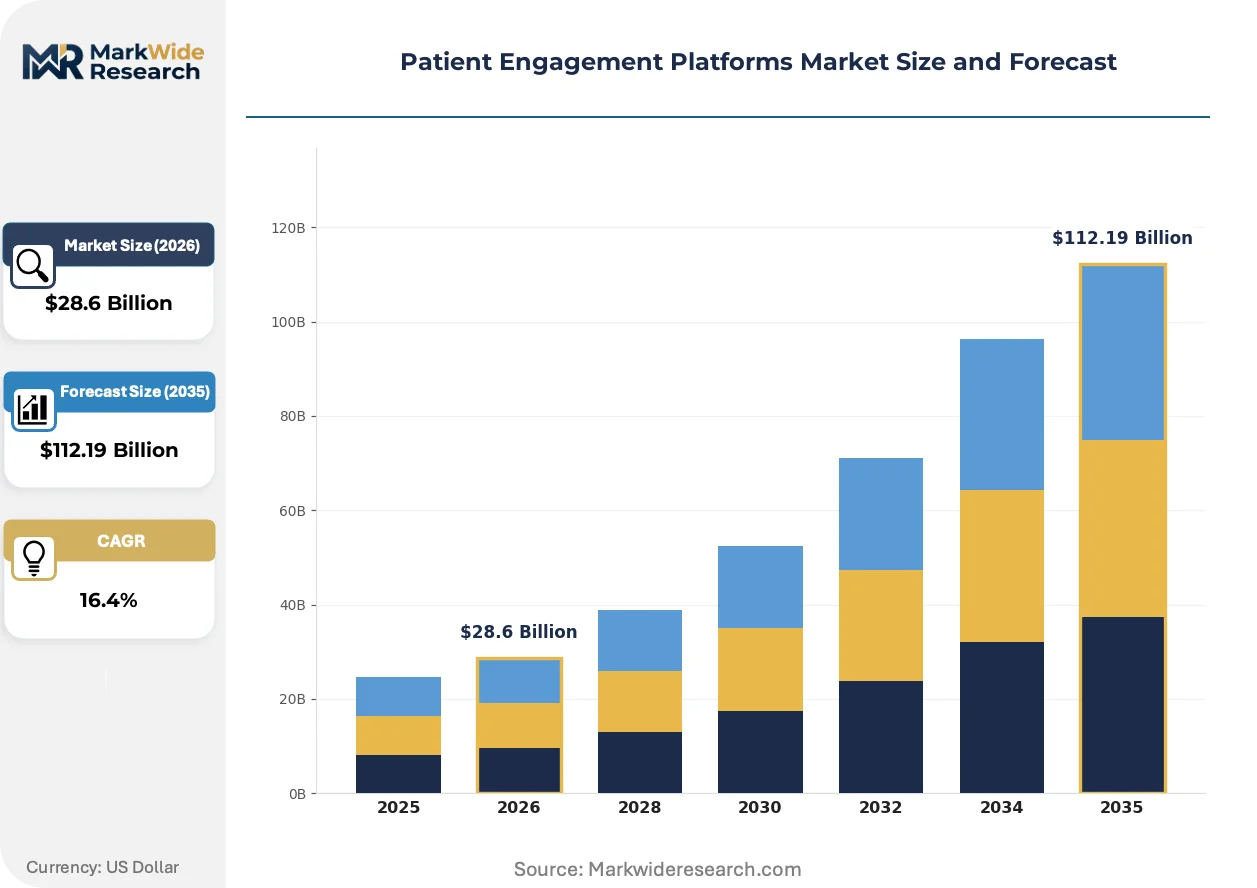
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Web Portals, Communication Tools, Patient Monitoring Systems Delivery Mode: Cloud-Based, On-Premises, Hybrid, SaaS End User: Hospitals, Clinics, Pharmacies, Telehealth Providers Technology: AI-Driven Solutions, Data Analytics, IoT Integration, Blockchain |
| Companies Covered | Epic Systems, McKesson Corporation, Wolters Kluwer, athenahealth, Cerner Corporation, GetWellNetwork, Orion Health, IBM Corporation, Allscripts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Engagement Platforms Market Evolving Landscape
Artificial intelligence capabilities are embedding into patient-facing interfaces, transforming static portals into adaptive systems that anticipate care needs before clinical deterioration occurs.
Conversational AI agents are integrating with electronic health record backends to automate appointment scheduling, medication adherence prompts, and post-discharge follow-up workflows. Ambulatory clinic networks in the United States are deploying these tools at scale to reduce front-desk staffing costs. The technology is integrating previously siloed communication channels into unified patient experience layers that compress response times from hours to minutes.
The European Union's AI Act establishes risk classification frameworks for clinical decision support features embedded in patient engagement software. Vendors must now document conformity assessment procedures for algorithms influencing diagnosis or treatment recommendations. Medical device manufacturers targeting EU markets are restructuring product roadmaps to segregate high-risk AI modules from administrative automation tools.
Hospital procurement committees are unbundling patient engagement capabilities from comprehensive EHR contracts, creating standalone vendor evaluation criteria. Specialty clinics and Federally Qualified Health Centers now issue separate RFPs for portal functionality, remote monitoring, and patient education content. This pattern is most visible in United States markets where CMS quality metrics tie reimbursement to specific patient-reported outcome measures.
Patient Engagement Platforms Market Segmentation
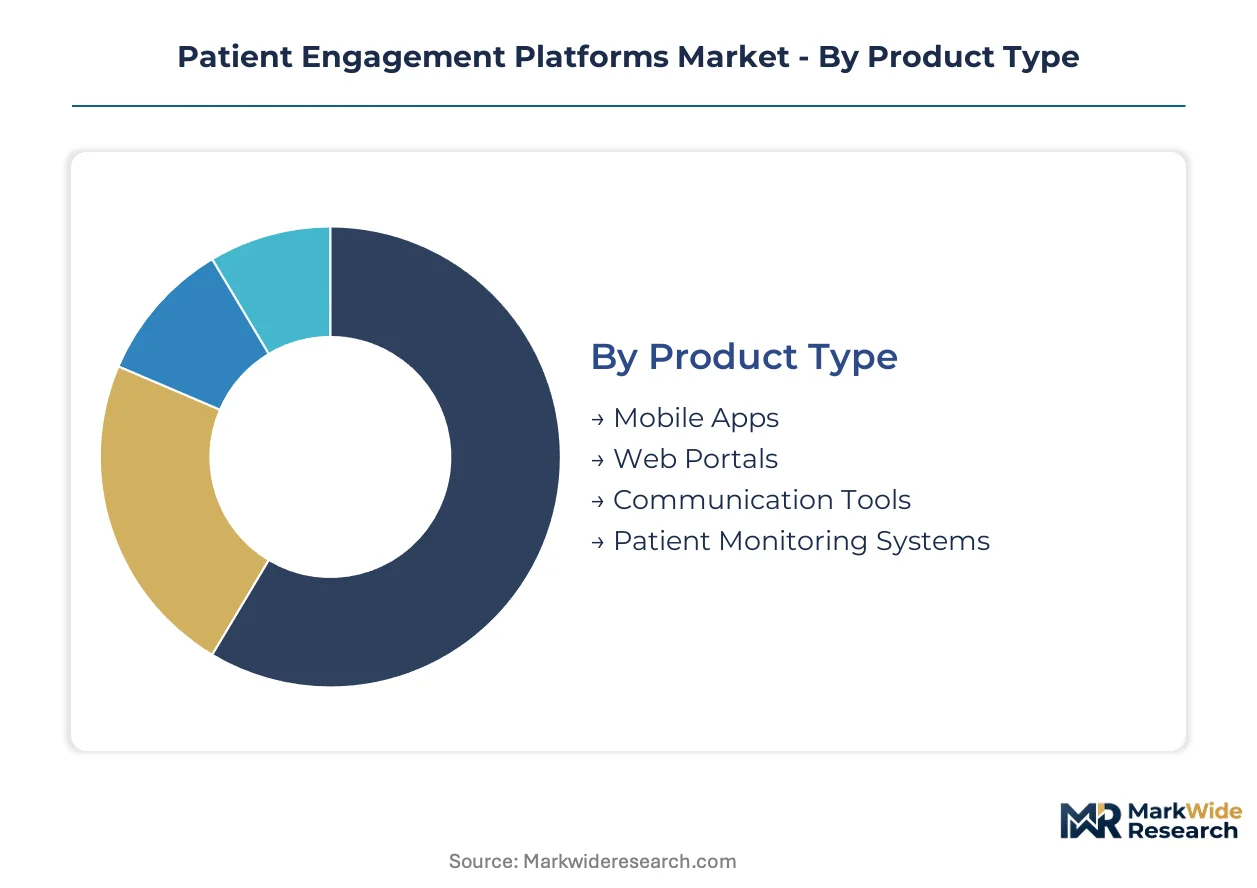
Segmentation in patient engagement platforms reveals divergent technical requirements across care settings. Procurement patterns vary sharply between enterprise hospital systems and ambulatory networks. Vendor product strategies must align with specific deployment constraints and regulatory exposure.
Product Type:
Standardization dominates mobile and web interfaces, while monitoring systems demand heavy customization for clinical workflows.
- Mobile Apps:Native smartphone applications deliver appointment scheduling, secure messaging, and medication reminders through iOS and Android SDKs. Younger patient cohorts in Germany and the United States expect smartphone-native experiences, driving rapid deployment in urban hospital networks. Growing fastest: Mobile Apps.
- Web Portals:Browser-based platforms integrate with legacy EHR systems through HL7 FHIR APIs, serving as the default procurement choice for health systems with substantial technical debt. Leading the category by volume: Web Portals.
- Communication Tools:Bidirectional messaging infrastructure enables automated outreach for care gap closure and chronic disease management.
- Patient Monitoring Systems:Remote physiological data collection platforms interface with connected medical devices for post-acute surveillance.
Web Portals anchor current procurement budgets. Mobile Apps expand most quickly as digital-native demographics age into chronic care needs.
Delivery Mode:
Cost tier separation distinguishes capital-intensive on-premises deployments from operating-expense cloud models.
- Cloud-Based:Multi-tenant SaaS architectures eliminate client-side infrastructure overhead and enable subscription pricing. Health systems in India leverage cloud deployments to bypass limited on-site IT capacity in tier-2 and tier-3 cities.
- SaaS:Pure subscription models dominate ambulatory clinic procurement in the United States, aligning vendor incentives with ongoing platform utilization. Steepest expansion trajectory: SaaS.
- On-Premises:Self-hosted installations persist in defense and government healthcare facilities with stringent data sovereignty requirements.
- Hybrid:Split architectures segregate PHI storage on-premises while pushing patient-facing interfaces to cloud edge nodes.
Cloud-Based and SaaS collectively capture procurement momentum. On-Premises contracts concentrate in regulated government health systems.
End User:
Application intensity varies from high-acuity inpatient coordination to retail pharmacy medication adherence.
- Hospitals:Enterprise deployments span inpatient, emergency, and outpatient coordination with deep EHR integration requirements. German hospital digitization programs fund portal expansion for diabetes and cardiovascular cohort management.
- Telehealth Providers:Virtual-first care models demand asynchronous messaging and remote monitoring at core platform functionality. Fastest volume gain: Telehealth Providers.
- Clinics:Ambulatory settings prioritize scheduling efficiency and automated recall workflows over complex clinical data visualization.
- Pharmacies:Retail health settings emphasize medication synchronization, adherence packaging coordination, and immunization scheduling.
Hospitals dominate absolute platform spend. Telehealth Providers climb fastest as reimbursement codes stabilize.
Technology:
Maturity gradient separates production-grade analytics from emerging architectural bets.
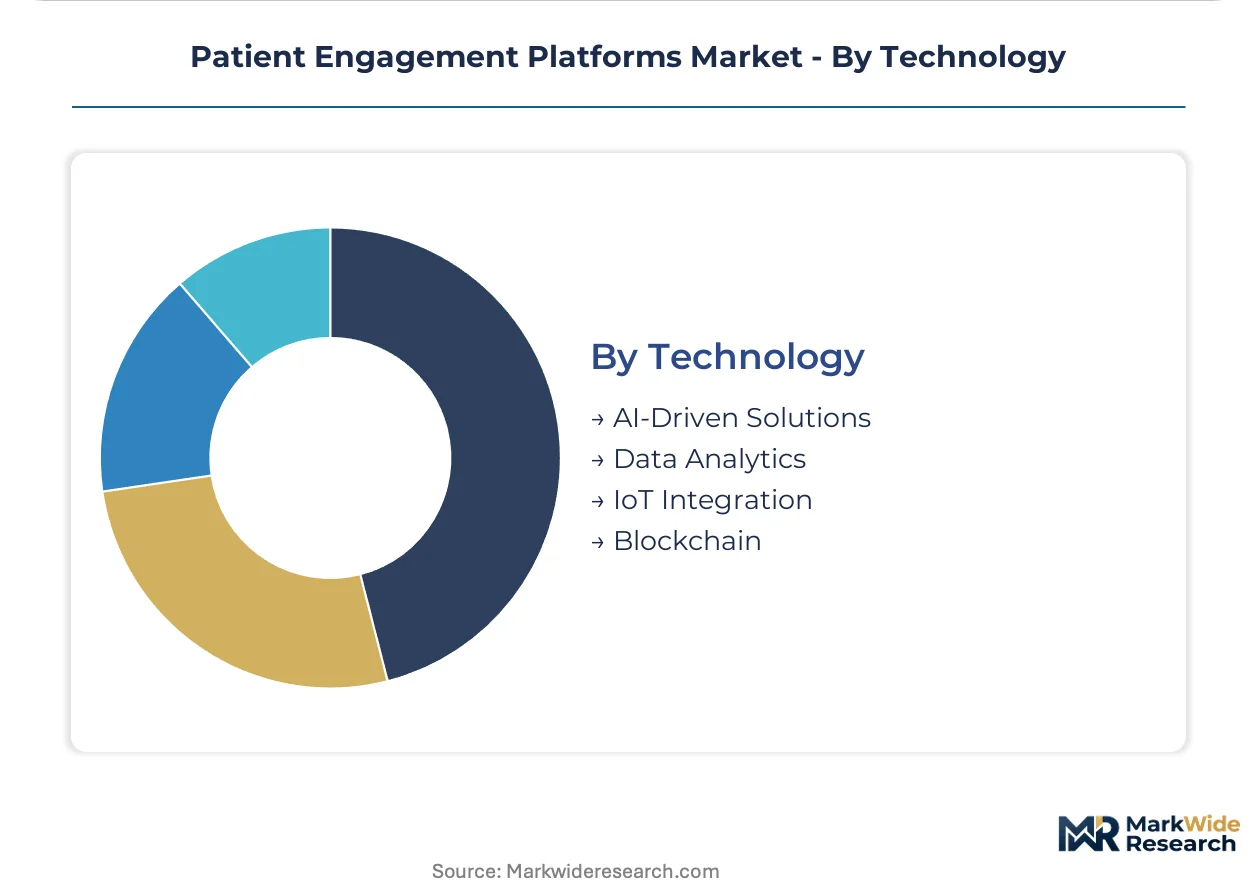
- Data Analytics:Descriptive and predictive dashboards process utilization patterns, no-show risk, and readmission probability. United States health systems deploy analytics to meet CMS quality metrics tying reimbursement to patient-reported outcomes.
- AI-Driven Solutions:Natural language processing engines automate symptom triage, appointment routing, and post-discharge follow-up. Highest growth slope: AI-Driven Solutions.
- IoT Integration:Connected device middleware enables remote therapeutic monitoring reimbursement pathways.
- Blockchain:Distributed ledger pilots address consent management and audit trail immutability in multi-party data exchange.
Data Analytics underpins current platform value. AI-Driven Solutions attract disproportionate R&D allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investment flows from Silicon Valley and Bangalore anchor platform development, while regulatory mandates in Washington, Brussels, and Beijing reshape deployment architectures.
United States
Hospital systems in Texas and Florida expand patient portal deployments to manage Medicare Advantage populations. The ONC Cures Act Final Rule enforces information blocking prohibitions that accelerate FHIR API adoption. Epic Systems anchors enterprise deployments across the Midwest and Northeast corridor.
Germany
Hospital digitization programs in Bavaria and North Rhine-Westphalia drive patient portal procurement for diabetes cohort management. The country's national hospital digitization law mandates interoperable data exchange standards. Berlin-based health IT clusters specialize in FHIR-compliant middleware development.
India
Tier-2 and tier-3 cities in Maharashtra and Karnataka leverage cloud deployments to bypass limited on-site IT capacity. The Ayushman Bharat Digital Mission funds patient portal infrastructure in underserved regions. Hyderabad and Bengaluru health tech clusters concentrate SaaS development talent.
China
Hospital networks in Shanghai and Guangdong deploy engagement platforms for chronic disease surveillance. The Personal Information Protection Law restricts cross-border health data flows, fragmenting cloud strategies. Shenzhen hardware manufacturers integrate patient monitoring with domestic cloud stacks.
United Kingdom
NHS trusts in London and Greater Manchester unbundle engagement capabilities from monolithic EHR contracts. The country's national health service mandates patient access to electronic records through standardized APIs. Cambridge health informatics clusters develop AI-powered triage modules.
Patient Engagement Platforms Market Competitive Landscape
Global majors compete with regional champions across interoperability standards and cloud deployment models, creating a tiered structure where integrated EHR vendors anchor enterprise hospital segments while cloud-native specialists capture ambulatory growth. Three archetypes dominate: comprehensive EHR-integrated platforms, API-first interoperability specialists, and vertical SaaS providers for specific care settings. Consolidation pressures intensify through strategic partnerships between legacy vendors and cloud infrastructure providers, while portfolio diversification into remote monitoring capabilities accelerates.
Within the integrated platform tier, Epic Systems and Cerner Corporation occupy positions as anchor vendors for North American hospital systems, exemplifying the EHR-centric deployment model. athenahealth represents the cloud-native specialist archetype, sitting within the ambulatory-focused segment where subscription pricing aligns vendor incentives with utilization metrics. These three companies illustrate the competitive divergence between enterprise hospital consolidation and distributed clinic network expansion.
| Leading Market Players |
|---|
| Epic Systems |
| McKesson Corporation |
| Wolters Kluwer |
| athenahealth |
| Cerner Corporation |
| GetWellNetwork |
| Orion Health |
| IBM Corporation |
| Allscripts |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up cloud infrastructure specialists anchor vendor consolidation patterns, concentrating pricing power among scaled SaaS platforms while forcing mid-tier developers toward aggressive subscription discounts to secure hospital system contracts.
Pricing Analysis
Warranty and implementation service bundling separates enterprise procurement tiers, with comprehensive onboarding packages commanding premium positioning against unbundled software licenses. Three-tier pricing structure across premium, standard, and economy levels reflects integration complexity, FHIR certification grade, and dedicated support availability. Cost compression in the mid-market tier is intensifying because ambulatory clinic networks demand per-provider pricing below traditional per-bed hospital models. Federally Qualified Health Centers exhibit highest price sensitivity, while integrated delivery systems with bundled EHR contracts demonstrate lowest sensitivity to standalone module costs.
Supply Chain Analysis
Direct-to-health-system channels handle enterprise hospital demand, while value-added resellers and GPO contracts serve ambulatory networks and specialty clinics. Cloud infrastructure concentrates in the United States, India, and Germany, with hyperscale data centers anchoring multi-tenant SaaS delivery. Platform development draws from specialized engineering talent pools, HL7 FHIR middleware libraries, and cybersecurity certification frameworks. Single-source vulnerability in FHIR implementation expertise creates bottleneck risk for rapid deployment timelines. Distribution runs through healthcare IT consultants and EHR vendor partnership programs for enterprise penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architectures are displacing legacy on-premises deployments, with FHIR-compliant API infrastructure replacing siloed portal systems as the dominant integration standard across health system procurement.
For Market Incumbents: Cement interoperability leadership by acquiring FHIR specialist firms in Berlin and Bengaluru health tech clusters to counter cloud-native ambulatory entrants. Deepen API-first development capacity to defend against athenahealth-style subscription models eroding traditional licensing revenue.
For New Entrants and Emerging Players: Enter via India's Ayushman Bharat-funded tier-2 hospital digitization wave, where cloud deployments bypass limited on-site IT infrastructure. Target remote therapeutic monitoring integration as the most penetrable segment, leveraging Medicare reimbursement codes to establish billable service footholds.
For Investors and Strategic Acquirers: Distressed-cycle entries favor ambulatory-focused SaaS specialists with established Epic Systems integration pathways in the United States. Long-term viability hinges on AI-powered triage differentiation and state-level telehealth licensing compliance breadth. Watch ONC Cures Act enforcement intensity as inflection indicator for platform consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Certification Investment | ONC Cures Act mandates accelerate vendor consolidation around interoperability-compliant platforms. |
| Remote Monitoring Partnership | Medicare reimbursement codes enable billable integration with connected medical device ecosystems. |
| AI Triage Module Development | NLP engines reduce nursing call center volume for United States ambulatory clinic networks. |
| Cloud Infrastructure Expansion | Hyderabad and Bengaluru data centers serve India's Ayushman Bharat hospital digitization mission. |
| Cybersecurity Insurance Structuring | Ransomware targeting healthcare IT elevates operational overhead for patient data repositories. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with health system CIOs, EHR integration specialists, hospital procurement committee members, and GPO contracts managers. Hospital procurement databases, CMS Medicare reimbursement filings, HIPAA compliance audit records, and ONC Cures Act implementation guidance provided quantitative scaffolding. Bottom-up deployment counts triangulated against top-down health IT spending estimates across the analysis window.
Reconciliation of vendor revenue disclosures, health system capex budgets, and cloud infrastructure investment flows shaped the analytical framework. Segmentation dimensions modeled include delivery mode, end-user facility type, technology maturity tier, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated baseline estimates. FHIR adoption velocity and state-level telehealth reimbursement stability served as industry-specific forecast inputs throughout the projection horizon.
Revisions become necessary when ONC enforcement patterns shift, major EHR vendors alter partnership terms, or cybersecurity incident frequency disrupts cloud hosting economics. Forecasts reflect assumptions regarding HIPAA compliance cost trajectories and smartphone-first patient demographic expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
Global Plastic Surgery Software Market
Digital Health Solutions
Artificial Intelligence in Precision Medicine Market
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
Global Surgical Preoperative Planning Software Market
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Digital Healthcare Solutions Market