
 Mobile Tablets in Healthcare Market | 2026-2036
Mobile Tablets in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Tablets in Healthcare Market Outlook
Enterprise-grade security certification is bifurcating the competitive landscape into premium clinical-grade suppliers and cost-optimized generalist vendors. Apple Inc leverages its integrated ecosystem and proprietary encryption architecture to sustain premium positioning across large hospital networks. Samsung Healthcare Solutions anchors its competitive stance through MIL-STD-810G ruggedization standards and dedicated healthcare service contracts. Koninklijke Philips N.V. differentiates via native interoperability with its patient monitoring and diagnostic imaging platforms.
Mobile tablets in healthcare denote portable touchscreen computing devices engineered with antimicrobial housings, IEC 60601-1 electrical safety compliance, and minimum IP54 ingress protection for clinical sanitation protocols; these units enable real-time data capture, diagnostic image viewing, and remote consultation at the point of care. Rugged tablets dominate procurement volumes in emergency and surgical environments where drop resistance and fluid exposure tolerance justify unit premiums, while telemedicine applications represent the fastest-expanding demand segment as remote patient monitoring protocols extend beyond traditional facility boundaries. Standard tablets retain volume leadership in administrative and electronic health records workflows where environmental hardening offers limited incremental value.
FDA 510(k) clearance pathways for tablet-based diagnostic software and HIPAA Security Rule enforcement shape product development priorities and channel access requirements for vendors serving United States healthcare providers. The European Medical Device Regulation and CE marking obligations under MDR Article 20 impose additional clinical evidence burdens on tablet-integrated diagnostic applications entering EU markets. Stakeholders must monitor evolving cybersecurity guidance from national health regulators as network-connected tablet deployments expand attack surfaces across clinical environments.
Market Dynamics
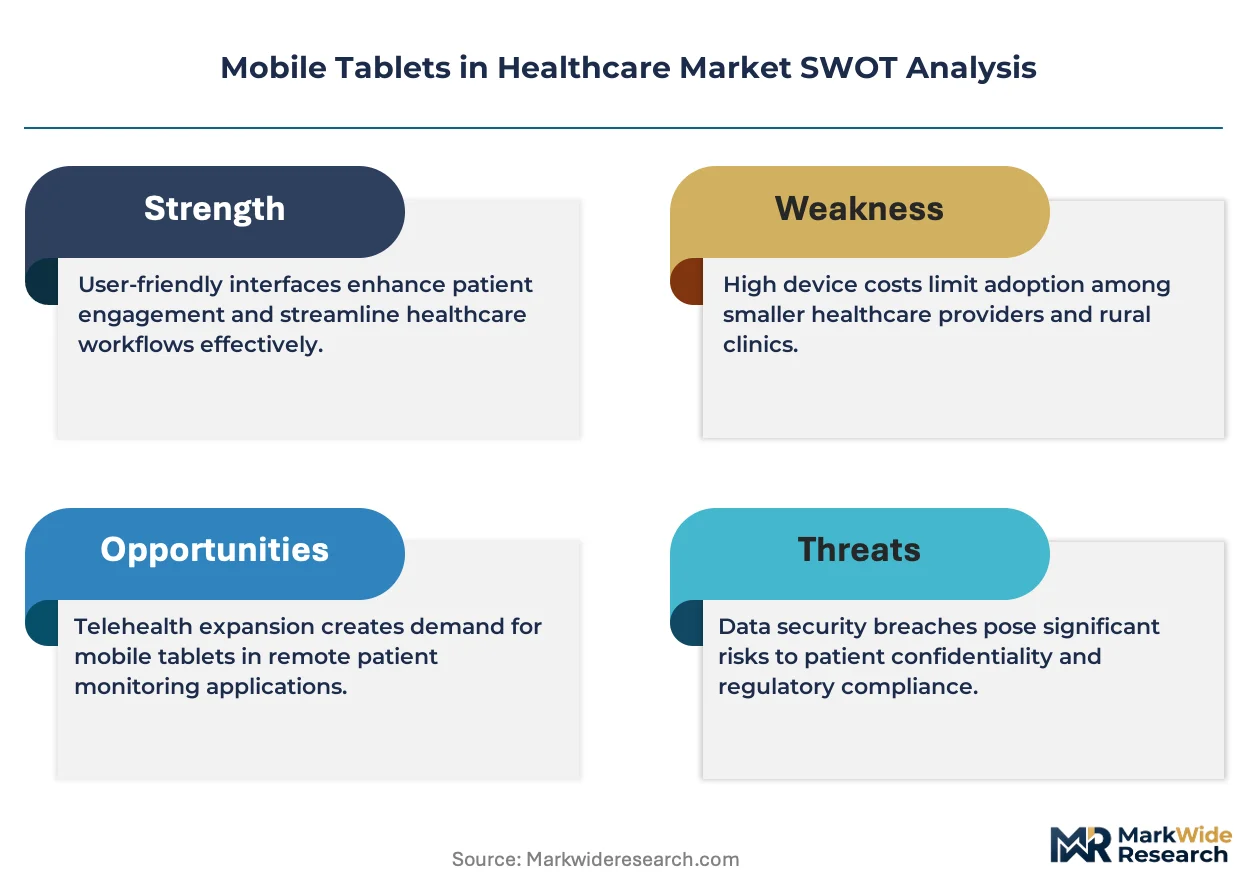
Hospital digitization mandates and cybersecurity hardening requirements are compressing vendor qualification timelines while elevating procurement barriers for non-certified suppliers across acute care networks.
Growth Catalysts
- Hospital Future Act (Germany):Federal reimbursement incentives for bedside tablet infrastructure are accelerating capital deployment schedules in German hospital systems.
- Telemedicine protocol expansion:Remote patient monitoring reimbursement codes in US Medicare frameworks are extending tablet demand beyond traditional facility boundaries.
- Antimicrobial surface engineering:Advances in copper-alloy and silver-ion embedded housings are reducing nosocomial transmission risks and supporting clinical adoption.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea fab capacity constraints are extending lead times for medical-grade tablet processors.
- IEC 60601-1 certification costs:Third-party electrical safety testing and documentation burdens add substantial fixed costs for new market entrants.
- Smartphone substitution pressure:Large-format clinical smartphones with stylus compatibility are capturing low-acuity documentation workflows.
Strategic Opportunities
- Home health integration:Post-acute care networks in the United States are deploying patient-owned tablets for transitional care management.
- EU MDR Article 20 alignment:Streamlined CE marking pathways for tablet-integrated diagnostic software are reducing time-to-market for compliant vendors.
- AI-enabled edge computing:On-device clinical decision support algorithms are creating premium positioning for high-memory tablet configurations.
Industry Challenges
- Biomedical engineering talent scarcity:Qualified technicians for tablet fleet management and cybersecurity patching are concentrated in metropolitan hospital clusters.
- EHR interoperability certification:Health Level Seven International (HL7) Fast Healthcare Interoperability Resources (FHIR) compliance testing extends product launch timelines.
- Legacy infrastructure integration:Proprietary hospital network architectures require custom middleware development for seamless tablet deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Tablets in Healthcare Market |
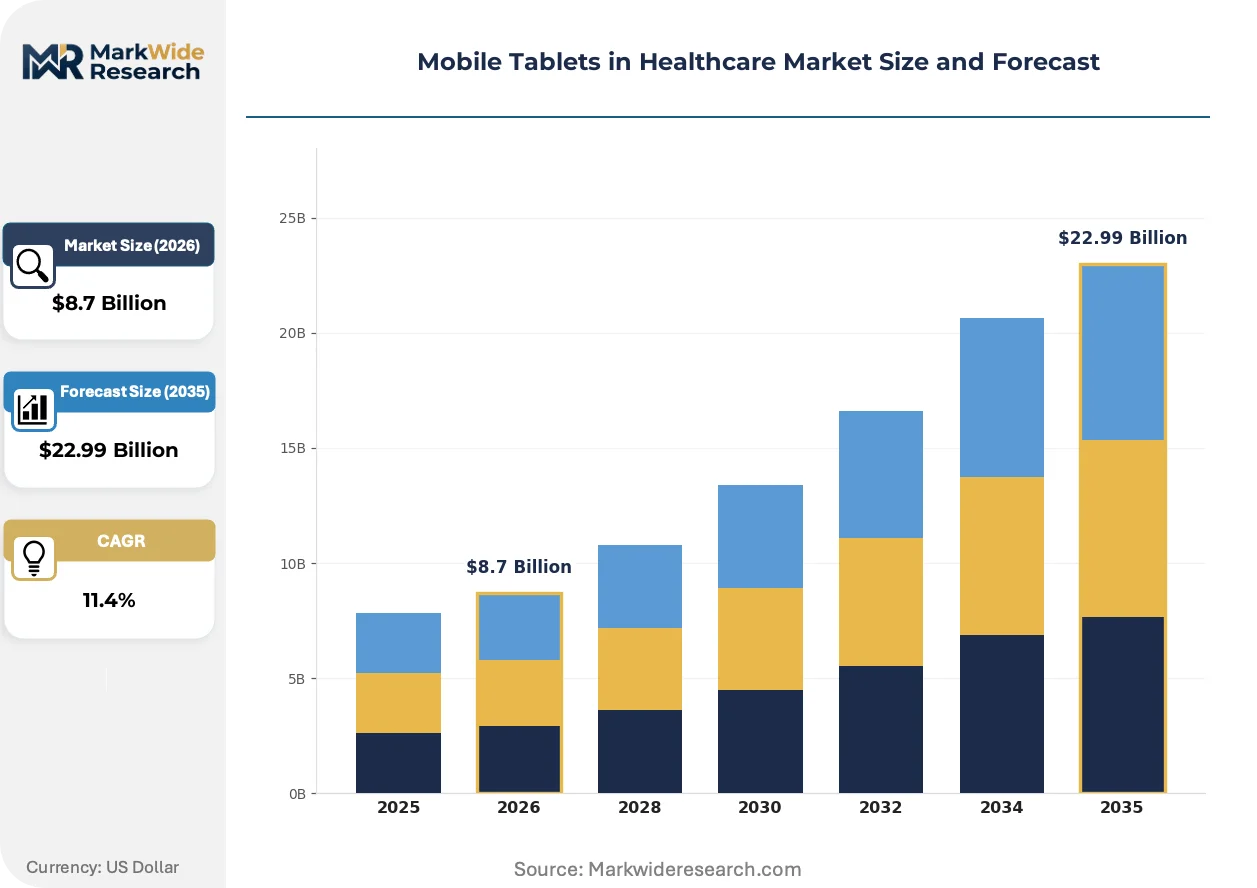
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tablets, Rugged Tablets, All-in-One Tablets, Lightweight Tablets End User: Hospitals, Clinics, Laboratories, Homecare Providers Application: Patient Monitoring, Electronic Health Records, Telemedicine, Medical Imaging Technology: Wi-Fi Enabled, 4G LTE, Bluetooth, NFC |
| Companies Covered | Apple Inc, Samsung Healthcare Solutions, Medtronic, Abbott, Koninklijke Philips N.V., ASUSTek Computer, Susmed Inc., Adjuvare Inc, HCL Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Tablets in Healthcare Market Strategic Shifts
Clinical workflow digitization and point-of-care computing requirements are accelerating hardware specialization and software ecosystem consolidation across healthcare delivery organizations.
Modular thermal management architectures are miniaturizing within rugged tablet form factors to support sustained diagnostic imaging workloads without active cooling fans. Surgical suites and emergency departments are adopting these passively cooled configurations to maintain sterile field integrity. The elimination of moving parts is miniaturizing failure rates and extending mean time between repairs in high-utilization clinical environments.
EU Medical Device Regulation (MDR) clinical evidence requirements are intensifying documentation burdens for tablet-integrated patient monitoring applications entering European markets. Manufacturers must now submit post-market surveillance data and risk management files beyond previous Medical Device Directive thresholds. Diagnostic imaging tablet vendors are responding by establishing dedicated regulatory affairs functions in Brussels and Berlin.
Subscription-based hardware-as-a-service models are displacing capital purchase cycles in US health systems seeking operational expenditure alignment with value-based reimbursement structures. Device lifecycle management and cybersecurity patch administration are bundling into per-bed monthly fees. Kaiser Permanente and Intermountain Healthcare are visible early adopters of this procurement restructuring.
Mobile Tablets in Healthcare Market Segmentation
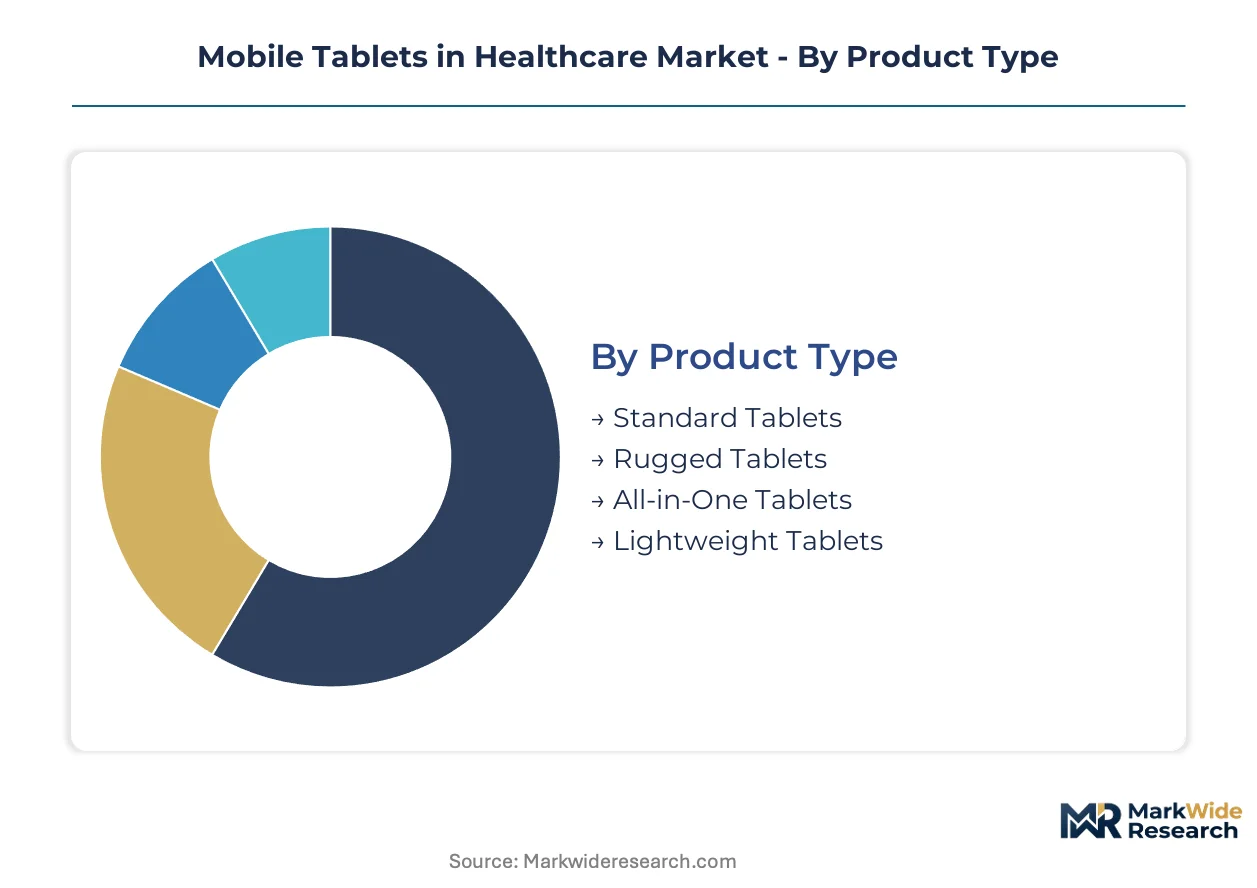
Segmentation in healthcare tablets reveals distinct procurement patterns across clinical environments. Product durability requirements, connectivity protocols, and end-user workflows channel demand through specialized vendor ecosystems with divergent certification standards.
Product Type:
Channel mix varies sharply: rugged units flow through biomedical equipment distributors with service contracts, while standard tablets reach hospitals via IT resellers and group purchasing organizations.
- Standard Tablets:Consumer-grade hardware with antimicrobial coatings and basic IP54 sealing dominates administrative workflows and EHR documentation. Demand clusters in US hospital systems prioritizing cost containment over environmental hardening, though HIPAA Security Rule compliance requirements are elevating procurement thresholds.
- Rugged Tablets:MIL-STD-810G certified housings with shock-mounted displays and sealed thermal management survive drop tests from 1.2 meters onto concrete. German emergency departments under Hospital Future Act digitization mandates are accelerating procurement of these units for pre-hospital and surgical applications.
- All-in-One Tablets:Integrated barcode scanners, RFID readers, and smart card modules reduce peripheral clutter at nursing stations.
- Lightweight Tablets:Sub-500g form factors prioritize clinician mobility during ward rounds and home visits.
By volume, Standard Tablets leads. By growth pace, Rugged Tablets is ahead.
End User:
Cost tier stratification separates capital-rich hospital networks from budget-constrained outpatient settings, with reimbursement models dictating hardware refresh cycles.
- Hospitals:Acute care networks with 500+ beds deploy enterprise tablet fleets exceeding 10,000 units, integrating with Epic and Cerner EHR architectures. FDA 510(k) clearance for diagnostic software drives premium positioning in US health systems.
- Clinics:Federally qualified health centers and specialty practices favor mid-tier configurations with cloud-based EHR compatibility.
- Laboratories:LIMS integration requirements and chemical resistance specifications dominate procurement specifications.
- Homecare Providers:Post-acute networks leverage patient-owned devices for transitional care, with Medicare remote monitoring reimbursement codes expanding addressable demand.
Hospitals capture the largest revenue share. Homecare Providers is climbing the fastest.
Application:
Application maturity determines margin structure: established EHR workflows compete on price, while emerging telemedicine deployments support premium pricing.
- Patient Monitoring:Continuous telemetry integration with Philips IntelliVue and GE Healthcare systems requires IEC 60601-1 electrical isolation and real-time alarm routing. German ICU digitization programs are driving large-scale deployments.
- Electronic Health Records:HL7 FHIR compliance and single sign-on integration are baseline requirements, with procurement decisions driven by EHR vendor certification lists.
- Telemedicine:Video consultation platforms with peripheral integration for digital stethoscopes and dermatoscopes.
- Medical Imaging:DICOM viewer certification and high-brightness displays for radiology workflows.
Electronic Health Records dominates installed base. Telemedicine shows steepest expansion trajectory.
Technology:
Connectivity specifications map directly to deployment environment: wired infrastructure dependency versus untethered clinical mobility.
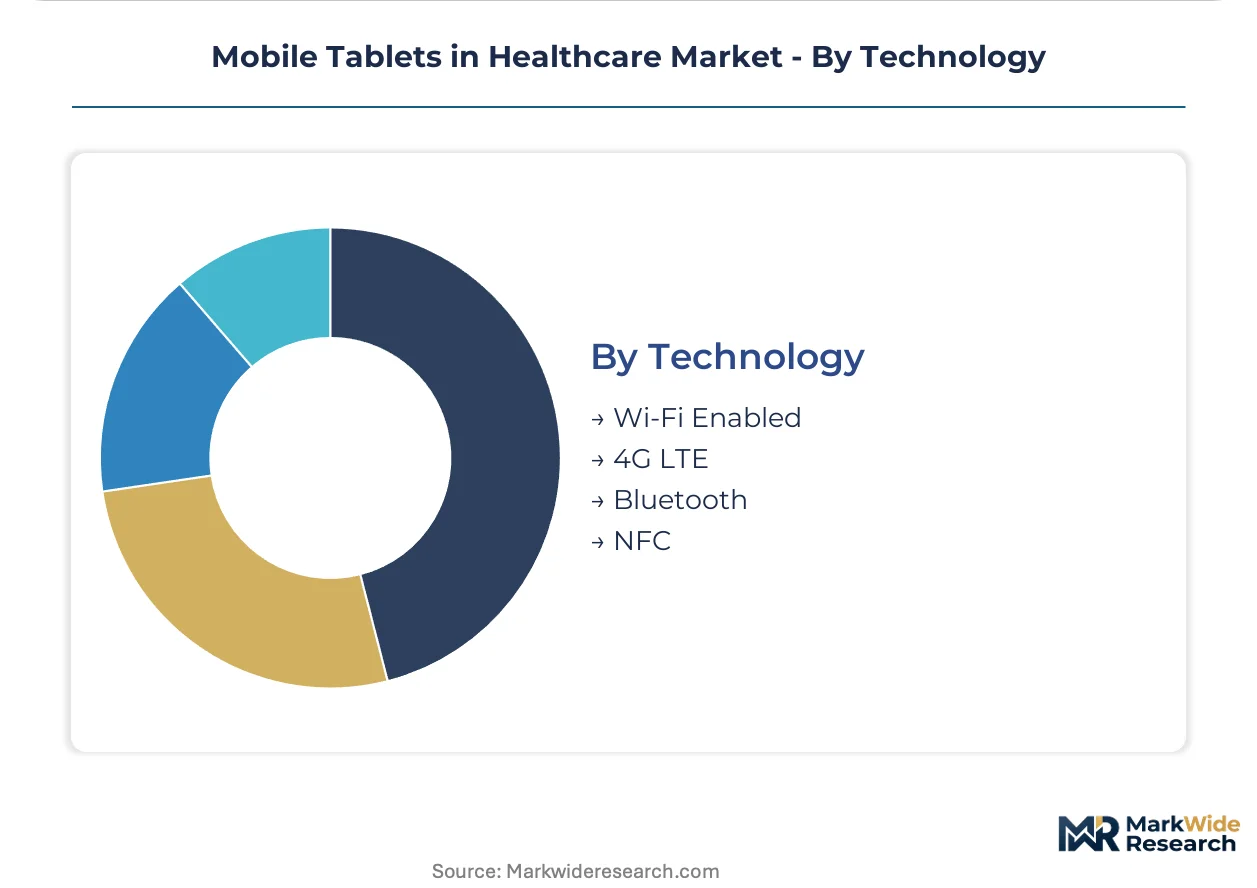
- Wi-Fi Enabled:802.11ax support with WPA3-Enterprise authentication anchors indoor deployments, with Cisco and Aruba network certification requirements limiting vendor qualification.
- 4G LTE:Cellular connectivity enables home health and ambulance-based workflows where hospital network access is unavailable.
- Bluetooth:Low-energy pairing with pulse oximeters, glucometers, and wearable sensors.
- NFC:Contactless patient identification and medication administration verification.
Wi-Fi Enabled leads by deployment volume. 4G LTE is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export clinical-grade tablet systems to hospital networks across the United States, establishing a dominant transatlantic trade corridor in medical computing hardware.
United States
Hospital networks exceeding 500 beds drive enterprise tablet fleet deployments exceeding 10,000 units per system. FDA 510(k) clearance pathways for tablet-based diagnostic software elevate procurement barriers and compress vendor qualification timelines. The Cleveland Clinic and Mayo Clinic anchor demand concentration in the Midwest, where Epic Systems integration requirements shape hardware specifications.
Germany
Federal reimbursement incentives under the Hospital Future Act accelerate capital deployment schedules for bedside tablet infrastructure. EU Medical Device Regulation Article 20 imposes clinical evidence burdens on tablet-integrated diagnostic applications entering European markets. Berlin and Munich hospital clusters lead procurement volumes for ruggedized units in surgical and emergency environments.
China
Domestic hospital digitization programs expand procurement of antimicrobial-housed tablets for point-of-care workflows. NMPA medical device registration requirements and GB standards for electrical safety compliance shape product development priorities. Shanghai and Beijing medical centers concentrate demand for high-brightness diagnostic imaging tablets integrated with PACS architectures.
Japan
Aging population demographics extend tablet demand into home health and remote patient monitoring applications. PMDA consultation pathways for software-as-a-medical-device accelerate regulatory clarity for AI-enabled clinical decision support. The Kanto region around Tokyo anchors hospital system procurement, with Osaka-based distributors serving western Japan acute care networks.
United Kingdom
NHS Long Term Plan digitization targets drive tablet deployments for electronic health records and telemedicine workflows. MHRA guidance on medical device software and UKCA marking requirements post-Brexit reshape channel access for international vendors. London hospital trusts and the Greater Manchester health system concentrate procurement volume for integrated clinical communication platforms.
Mobile Tablets in Healthcare Market Competitive Environment
Listed leaders compete with private specialists across certification depth and ecosystem integration. The vendor base stratifies into three tiers: premium clinical-grade suppliers with proprietary encryption architectures, mid-tier ruggedization specialists with dedicated healthcare service contracts, and cost-optimized generalist vendors targeting administrative workflows. Dominant competitive moves include strategic partnerships with EHR platform vendors and geographic expansion through biomedical equipment distributors with embedded service capabilities.
Within the integrated ecosystem tier, Apple Inc and Samsung Healthcare Solutions exemplify divergent positioning strategies. Apple Inc anchors premium positioning through proprietary encryption and native interoperability with large hospital network IT architectures. Samsung Healthcare Solutions occupies a position defined by MIL-STD-810G ruggedization standards and dedicated healthcare service contracts. Koninklijke Philips N.V. represents the medical device incumbent archetype, leveraging native interoperability with patient monitoring and diagnostic imaging platforms to defend installed base relationships.
| Leading Market Players |
|---|
| Apple Inc |
| Samsung Healthcare Solutions |
| Medtronic |
| Abbott |
| Koninklijke Philips N.V. |
| ASUSTek Computer |
| Susmed Inc. |
| Adjuvare Inc |
| HCL Technologies |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance pathways and IEC 60601-1 certification regimes gate both supplier qualification and price differentiation across clinical tablet procurement, compressing vendor margins for non-certified entrants while sustaining premiums for compliant incumbents serving acute care networks.
Pricing Analysis
Hospital systems with 500+ bed counts anchor a subscription-based hardware-as-a-service pricing structure displacing capital purchase cycles, with three-tier pricing stratification across clinical-grade, ruggedized, and administrative configurations. Price differentiation rests on MIL-STD-810G certification tier and embedded encryption architecture rather than raw component specifications. Cost compression in standard tablet tiers intensifies as large-format clinical smartphones capture low-acuity documentation workflows. Federally qualified health centers exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for medical-grade tablet processors, with China concentrating antimicrobial housing manufacturing and final assembly capacity. The supply chain draws from copper-alloy substrate suppliers, medical-grade display panel fabricators, and IEC-certified battery cell producers. Single-source vulnerability in advanced semiconductor lithography equipment exposes procurement timelines to geopolitical export controls. Distribution runs through biomedical equipment distributors with embedded service capabilities for ruggedized units, while IT resellers and group purchasing organizations channel standard tablet volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital digitization mandates across German and US acute care networks signal early-cycle expansion, with telemedicine protocol extensions creating new addressable demand beyond traditional facility boundaries.
For Market Incumbents: Fortify ecosystem integration through native interoperability investments with Epic and Cerner EHR architectures, while expanding dedicated healthcare service contracts to defend against MIL-STD-810G ruggedization specialists. Certification depth in FDA 510(k) pathways and EU MDR Article 20 compliance represents the critical defensive moat against cost-optimized generalist vendors. For New Entrants and Emerging Players: Anchor in post-acute home health segments where Medicare remote monitoring reimbursement codes reduce procurement friction and incumbent presence remains limited. Patient-owned tablet deployments for transitional care management offer the most penetrable white space, with direct-to-provider SaaS pricing models bypassing capital committee approval cycles. For Investors and Strategic Acquirers: EU MDR Article 20 implementation reshapes the acquisition landscape toward regulatory affairs capabilities and post-market surveillance infrastructure. Five-to-ten year viability favors targets with established Brussels regulatory presence and CE marking pathway expertise. The signal to monitor is MHRA guidance evolution on UKCA marking reciprocity post-Brexit.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic and Cerner EHR certification lists determine hardware qualification across US acute care networks. |
| CE Marking Pathway | EU MDR Article 20 compliance reduces time-to-market for tablet-integrated diagnostic software entrants. |
| Software Companion Development | AI-enabled edge computing algorithms create premium positioning for high-memory tablet configurations. |
| Reimbursement Strategy | Medicare remote monitoring codes expand addressable demand beyond traditional facility boundaries. |
| Backward Integration | In-house production of antimicrobial housing components reduces nosocomial transmission liability exposure. |
Study Parameters
A standing panel of hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists provided ongoing calibration against primary interview transcripts and secondary validation sources. The synthesis combined FDA 510(k) filing databases, EU MDR clinical evidence submissions, hospital procurement contract repositories, and CMS Medicare reimbursement code updates. Bottom-up unit deployment estimates triangulated against top-down health system IT budget allocations across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including health system capital expenditure disclosures and medical device distributor revenue segmentation. The analytical framework modeled product type, end user, application, and technology dimensions over the projection horizon. CAGRs derived from logistic adoption curves calibrated to hospital digitization mandate timelines and telemedicine protocol expansion trajectories.
Material uncertainties — semiconductor fab capacity constraints, cybersecurity guidance evolution, and reimbursement code modifications — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and health system IT refresh cycles. Recalibration cycles align with material shifts in FDA enforcement priorities and EU MDR implementation guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
US Digital Therapeutics Market
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
Medical Animation Market
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
UAE Mhealth Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Asia-Pacific Digital Therapeutic (Dtx) Market
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
Global Metaverse in Healthcare Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
US Digital Health Market