
 Patient Engagement Technology Market | 2026-2036
Patient Engagement Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Engagement Technology Market Outlook
HIPAA interoperability mandates are decoupling data portability from vendor lock-in, forcing incumbents to open APIs or lose hospital contracts. Epic Systems Corporation leverages its dominant EHR install base to extend into patient-facing portals, while Cerner Corporation anchors its cloud migration strategy around federal certification requirements. Oracle competes through vertical integration of clinical and consumer data layers after its health IT acquisitions.
Patient engagement technology encompasses software platforms, connected devices, and communication infrastructure that capture, transmit, and activate health data between patients and care teams, typically operating through FHIR-compliant APIs and cloud-native architectures with sub-second latency for real-time alerts. Its primary purpose is to close feedback loops in care delivery, converting passive recipients into active participants who adhere to treatment protocols and report symptoms between visits. Mobile apps and patient portals capture the largest share of current deployments, though AI-driven solutions represent the fastest-expanding margin pool as predictive risk stratification becomes reimbursable. Wearable devices remain a hardware-dependent segment where unit economics favor platform-agnostic device makers over vertically integrated health systems.
FDA digital health guidance, ONC certification requirements, and CMS value-based payment rules collectively determine which platforms qualify for federal reimbursement and hospital procurement budgets. The FDA regulates software-as-medical-device claims, while ONC enforces information-blocking penalties that mandate patient data access. Stakeholders must monitor how CMS redefines remote patient monitoring billing codes, as reimbursement eligibility directly dictates provider adoption velocity and vendor R&D allocation.
Market Dynamics
Value-based reimbursement mandates from CMS are forcing hospital procurement committees to prioritize platforms that demonstrate measurable readmission reduction, creating a structural preference for integrated patient engagement stacks over point solutions.
Growth Catalysts
- Medicare Hospital Readmissions Reduction Program:Financial penalties for excessive 30-day readmissions push health systems toward automated post-discharge monitoring and patient outreach tools.
- FHIR API mandates:ONC information-blocking rules require standardized data exchange, enabling third-party developers to build interoperable patient-facing applications without EHR vendor permission.
- Remote patient monitoring:Expanded CMS billing codes for physiologic data collection outside clinical settings reimburse providers for continuous patient touchpoints.
Market Restraints
- Cloud infrastructure concentration:AWS, Microsoft Azure, and Google Cloud control the majority of healthcare data hosting, creating single-point-of-failure risks for multi-tenant patient engagement platforms.
- Cybersecurity insurance costs:Ransomware attacks against hospital networks have driven premiums for cyber liability coverage up substantially, consuming IT budgets that would otherwise fund engagement technology.
- Legacy EHR data silos:Proprietary data models in dominant systems require expensive middleware to extract patient records for third-party engagement tools.
Strategic Opportunities
- Behavioral health integration:Depression screening and substance use monitoring represent underpenetrated clinical domains where patient-reported outcome tools lack established vendors.
- Medicaid expansion states:Newly eligible populations in holdout states that recently expanded coverage require culturally tailored engagement platforms with multilingual interfaces.
- AI-driven risk stratification:Machine learning models that predict no-show probability or medication non-adherence enable targeted outreach before clinical deterioration.
Industry Challenges
- Clinical informatics talent scarcity:Health systems compete with technology firms for data scientists who understand both FHIR standards and care workflow design.
- State-level privacy fragmentation:California Consumer Privacy Act and emerging state laws create compliance mosaics that complicate multi-state platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Engagement Technology Market |
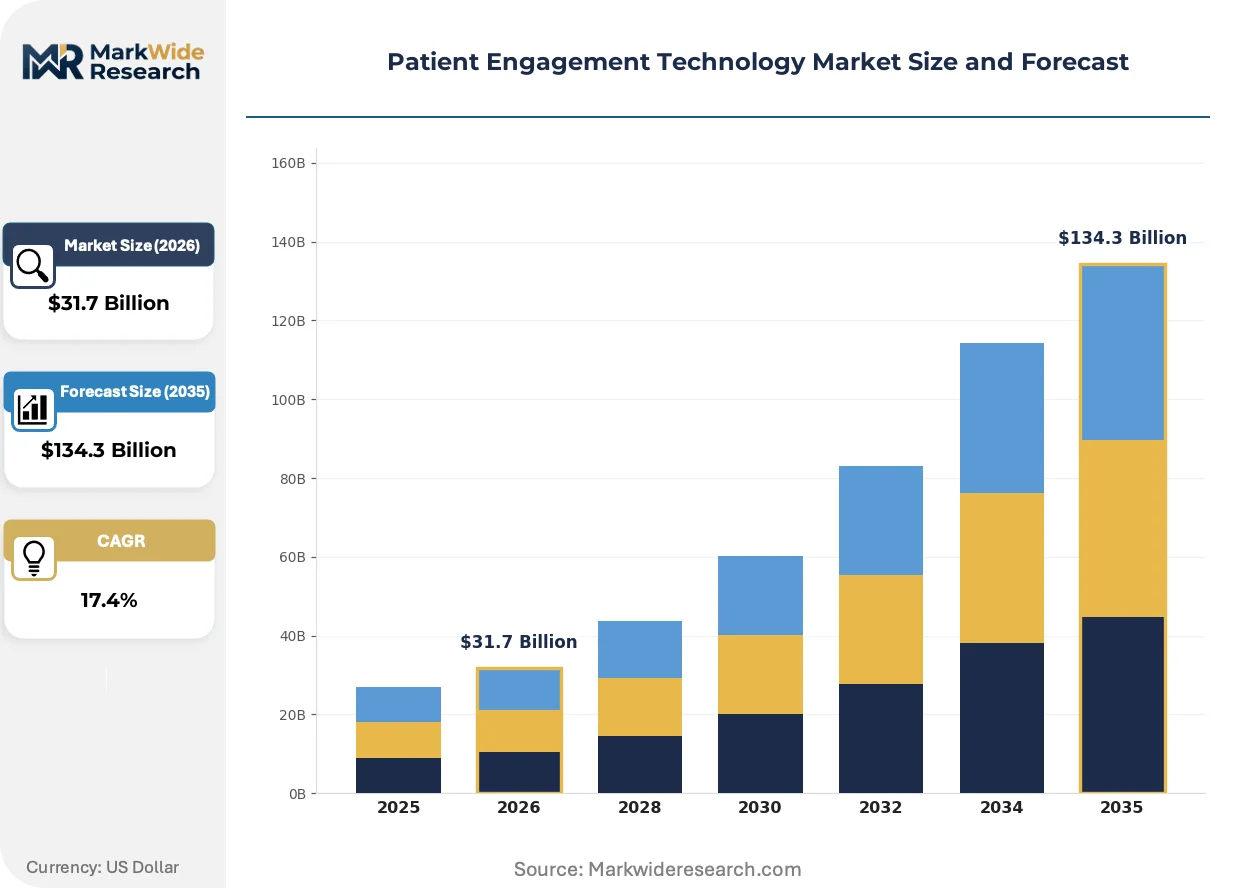
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $134.3 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Patient Portals, Wearable Devices, Communication Tools End User: Healthcare Providers, Patients, Payers, Caregivers Technology: Cloud-Based, On-Premise, Hybrid, AI-Driven Solutions Delivery Mode: Subscription-Based, One-Time Purchase, Freemium, Pay-Per-Use |
| Companies Covered | Oracle, McKesson Corporation, athenahealth, Veradigm LLC, Health Catalyst, Epic Systems Corporation, NextGen Healthcare, Cerner Corporation, Allscripts Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Engagement Technology Market Strategic Shifts
Generative AI interfaces and ambient documentation tools are compressing the time between patient symptom reporting and clinical response, altering how care teams prioritize asynchronous communication workflows.
Large language models trained on clinical corpora are rewriting the patient intake experience. Health systems in Texas and Florida deploy conversational agents that triage symptoms before scheduled visits. These tools compress nursing staff workload while capturing structured data that feeds directly into risk-adjustment calculations.
EU AI Act risk classification rules are reshaping how algorithmic patient engagement tools enter European markets. High-risk applications—including diagnostic support and treatment recommendation engines—now require conformity assessments and post-market monitoring. German hospital procurement committees increasingly demand documentation of training data provenance and bias mitigation protocols.
Direct-to-employer contracting is fragmenting traditional health system patient acquisition channels. Self-insured employers in manufacturing-heavy Midwestern states negotiate standalone virtual primary care contracts that bypass established referral networks. These arrangements favor engagement platforms with white-label capabilities and occupational health-specific content modules.
Patient Engagement Technology Market Segmentation
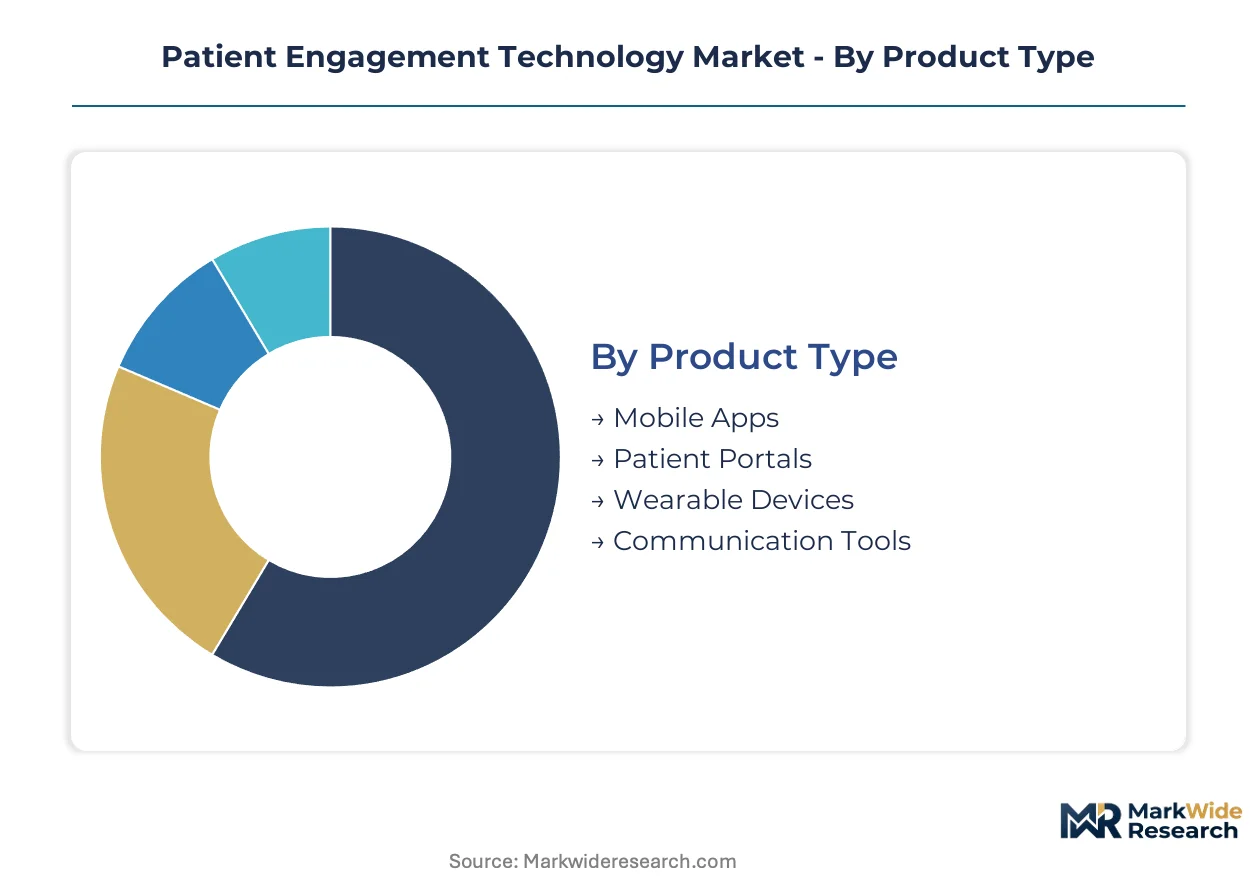
Segmentation in patient engagement technology reveals how procurement priorities diverge across stakeholder workflows. Hospital IT committees evaluate platforms against EHR integration depth, while payers prioritize outcome measurement capabilities for risk-adjusted contracts.
Product Type:
Cloud-native architectures and API interoperability standards define functional boundaries across product categories.
- Mobile Apps:Native and progressive web applications deliver medication reminders, symptom tracking, and secure messaging through FHIR-connected backends. Demand concentrates in United States health systems seeking to reduce 30-day readmission penalties under CMS Hospital Readmissions Reduction Program rules. Epic Systems and Cerner extend their EHR dominance into this segment through integrated patient-facing modules.
- Patient Portals:Web-based gateways provide appointment scheduling, lab result access, and clinical note review, typically tethered to specific EHR installations. United States hospital networks deploy these most intensively where ONC information-blocking mandates require patient data accessibility. Legacy portal fragmentation creates middleware opportunities for third-party developers.
- Wearable Devices:Physiologic sensors capture continuous glucose, heart rate, and activity data for remote monitoring programs. Platform-agnostic device makers capture margin from hardware-agnostic software layers.
- Communication Tools:Secure messaging, automated outreach, and telehealth interfaces bridge synchronous and asynchronous care interactions. SMS-based platforms dominate Medicaid expansion states with lower smartphone penetration.
Mature deployment sits with Patient Portals. Newer deployment is concentrated in Mobile Apps.
End User:
Procurement authority and reimbursement eligibility reshape feature requirements across stakeholder types.
- Healthcare Providers:Hospitals, physician practices, and integrated delivery networks purchase enterprise licenses for population health management. United States academic medical centers lead adoption where value-based contracts tie payments to patient-reported outcomes.
- Patients:Direct-to-consumer subscriptions for chronic disease management and wellness tracking represent a nascent revenue stream. Out-of-pocket payment limits scale in this segment.
- Payers:Insurance carriers deploy engagement platforms to steer members toward preferred providers and close care gaps for HEDIS quality metrics. Medicare Advantage plans in Florida and Texas invest most aggressively.
- Caregivers:Family member access to patient data and care coordination tools addresses aging population needs. Demand clusters where state Medicaid programs cover home-based care coordination.
Revenue concentration favors Healthcare Providers. Fastest expansion trajectory belongs to Payers integrating engagement with risk adjustment workflows.
Technology:
Infrastructure decisions determine scalability, security posture, and integration complexity for deployment teams.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital expenditure for server infrastructure while enabling elastic scaling during enrollment surges. AWS, Microsoft Azure, and Google Cloud control hosting capacity, creating concentration risk for platform vendors.
- On-Premise:Self-managed installations persist in Department of Defense facilities and critical access hospitals with limited internet reliability. Maintenance burden and upgrade friction constrain growth.
- Hybrid:Split architectures keep protected health information on local servers while pushing analytics workloads to public cloud. German hospital procurement committees favor this model under EU data residency requirements.
- AI-Driven Solutions:Machine learning models predict no-show probability, medication non-adherence, and clinical deterioration risk. FDA digital health guidance governs software-as-medical-device claims in this segment.
Installed base remains concentrated in On-Premise legacy systems. Steepest expansion trajectory characterizes AI-Driven Solutions as predictive risk stratification gains reimbursement eligibility.
Delivery Mode:
Pricing architecture shapes customer acquisition costs and lifetime value calculations for platform vendors.
- Subscription-Based:Recurring per-user or per-provider fees align vendor incentives with customer retention. Annual contracts dominate United States hospital procurement.
- One-Time Purchase:Perpetual licenses with maintenance add-ons persist in government and rural hospital segments with constrained operating budgets.
- Freemium:Basic functionality at no cost converts to paid tiers for advanced analytics or EHR integration. Direct-to-patient chronic disease platforms favor this model.
- Pay-Per-Use:Transactional billing for specific encounters or messages aligns costs with utilization. Remote patient monitoring programs under CMS billing codes experiment with this structure.
Contract value concentrates in Subscription-Based arrangements. Emerging deployment favors Pay-Per-Use where reimbursement volatility makes fixed commitments untenable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and HUBZone designations in the United States concentrate patient engagement technology deployment where Medicare reimbursement incentives intersect with federal tax advantages for health IT infrastructure investment.
United States
CMS Hospital Readmissions Reduction Program penalties drive health system procurement of automated post-discharge monitoring platforms in Texas and Florida. HIPAA interoperability mandates from ONC force EHR vendors to open FHIR-compliant APIs for third-party developers. Epic Systems Corporation anchors its dominance through integrated patient-facing modules in Wisconsin and Illinois hospital networks.
Germany
EU AI Act risk classification rules reshape procurement criteria for algorithmic triage tools in Bavarian academic medical centers. BfArM digital health application fast-track approvals accelerate reimbursement eligibility for prescription-grade patient engagement apps. Berlin-Brandenburg health technology clusters concentrate startup activity around FHIR-native communication platforms.
United Kingdom
NHS England Long Term Plan targets for digital-first primary care expand tender opportunities for remote monitoring vendors in Greater London and Manchester. MHRA software-as-medical-device guidance governs AI-driven symptom checkers seeking market authorization. Cambridge-Oxford health data research clusters feed machine learning training pipelines for predictive risk stratification tools.
Japan
PMDA regulatory science initiatives streamline approval pathways for software-based therapeutic engagement in Tokyo and Osaka metropolitan hospitals. METI Society 5.0 healthcare digitization subsidies accelerate cloud migration for aging rural clinic networks. Nagoya medical device manufacturing corridors supply wearable sensors for continuous glucose monitoring programs.
India
CDSCO medical device rules classify certain patient engagement software as regulated products, creating compliance barriers for unvalidated platforms in Maharashtra and Karnataka. Ayushman Bharat Digital Mission infrastructure investments expand addressable market for vernacular-language patient portals. Hyderabad health technology parks host development centers for telemedicine-integrated engagement stacks.
Patient Engagement Technology Market Competitive Environment
United States vendors anchor the enterprise tier; European specialists hold regulatory-compliant positions in privacy-sensitive markets. Market structure tilts toward consolidation around EHR-integrated suites rather than point solutions. Three archetypes dominate: legacy health IT incumbents extending platform dominance, cloud-native challengers exploiting API interoperability, and vertical integrators combining clinical and consumer data layers. Competitive moves concentrate on strategic acquisitions of AI analytics capabilities and federal certification pursuit for reimbursement eligibility.
Within the incumbent platform tier, Epic Systems Corporation and Cerner Corporation exemplify EHR-anchored expansion into patient-facing modules. Oracle occupies a position as a vertical integrator following its health IT acquisitions, combining clinical infrastructure with consumer data assets. These three entities represent distinct strategic postures: organic platform extension, cloud migration around certification requirements, and backward integration across data layers.
| Leading Market Players |
|---|
| Oracle |
| McKesson Corporation |
| athenahealth |
| Veradigm LLC |
| Health Catalyst |
| Epic Systems Corporation |
| NextGen Healthcare |
| Cerner Corporation |
| Allscripts Healthcare |
| Others |
Value Chain & Pricing Dynamics
CMS value-based reimbursement mandates are compressing hospital IT procurement timelines, forcing vendors to pre-certify cloud-native platforms for rapid deployment or sacrifice margin to expedited implementation fees. This demand-side urgency stratifies pricing around deployment velocity rather than feature depth alone.
Pricing Analysis
Short lead-time premiums dominate vendor pricing structures, with health systems paying 15-25% surcharges for sub-90-day FHIR-compliant platform activation. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled predictive modules from basic patient portal functionality, with ONC certification status serving as the primary quality-grade differentiator. Pricing pressure stems from hyperscaler infrastructure cost pass-throughs as AWS and Azure adjust healthcare data hosting rates. Medicaid expansion states exhibit highest price sensitivity due to constrained operating budgets, while academic medical centers under risk-based contracts show lowest sensitivity to upfront licensing costs.
Supply Chain Analysis
ONC certification and FDA software-as-medical-device qualification requirements gate supplier eligibility, creating a qualified vendor pool concentrated in the United States, Germany, and India. Cloud infrastructure draws from AWS, Microsoft Azure, and Google Cloud data centers, while wearable sensor hardware sources from Nagoya manufacturing corridors and Shenzhen component markets. Single-source vulnerability sits with hyperscaler concentration for multi-tenant SaaS hosting. Distribution runs through health system GPO contracts and direct-to-hospital enterprise sales teams, with federal certification status determining procurement committee shortlist inclusion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient engagement technology sits in a cloud-transition phase, with FHIR-native architectures displacing legacy on-premise EHR-tethered installations. AI-driven risk stratification capabilities are becoming table stakes for reimbursement eligibility.
For Market Incumbents: Cement platform dominance by acquiring FHIR-native interoperability specialists before API mandates erode EHR lock-in advantages. Defensive consolidation must address cloud-native challengers exploiting ONC information-blocking rules; backward integration into AI analytics capabilities preserves margin in predictive risk stratification segments.
For New Entrants and Emerging Players: Conversational AI interfaces for behavioral health triage represent the most penetrable white-space target, with depression screening and substance use monitoring lacking established vendors. Medicaid expansion states in the Midwest offer geography-specific entry points where culturally tailored multilingual platforms face limited incumbent presence. Go-to-market execution should anchor around white-label direct-to-employer contracts bypassing traditional health system procurement.
For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native challengers possessing FDA software-as-medical-device clearances given CMS reimbursement code expansion for algorithmic patient outreach. Long-term viability over the next decade favors platforms with proven readmission reduction metrics under value-based contracts. The signal to watch is BfArM fast-track approval velocity in Germany as a leading indicator for EU-wide reimbursement adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Integration | ONC certification mandates force EHR vendors to open patient data access for third-party developers. |
| AI Risk Stratification Development | FDA software-as-medical-device clearances unlock CMS billing codes for predictive patient outreach. |
| Cloud Infrastructure Migration | Multi-tenant SaaS architectures eliminate capital expenditure while enabling elastic scaling during enrollment surges. |
| Behavioral Health Module Launch | Depression screening and substance use monitoring represent underpenetrated domains with limited incumbent presence. |
| Direct-to-Employer Partnership | Self-insured manufacturing employers in Midwestern states negotiate standalone virtual primary care contracts. |
Study Parameters
SEC 10-K filings, CMS Medicare reimbursement databases, and FDA digital health guidance documents formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with hospital IT procurement directors, EHR integration specialists, and GPO contracts managers validated deployment timelines and pricing structures. Bottom-up triangulation across vendor revenue disclosures and top-down validation against health system IT expenditure surveys anchored the forecast framework.
Historical trendline analysis of patient portal adoption curves and remote patient monitoring billing code expansion informed the projection methodology across the analysis window. Segmentation modeling incorporated product type, end-user archetype, technology infrastructure, and delivery mode dimensions. CAGRs derived from fitted growth curves adjusted for regulatory inflection points, with AI-driven solutions and payer risk-adjustment workflows serving as primary demand-side forecast inputs.
Several conditions sit outside the modeled scope, including state-level privacy law fragmentation effects and cybersecurity insurance cost volatility. Forecasts reflect assumptions about CMS reimbursement rule stability and ONC enforcement continuity. Stakeholders should weight assumptions against their own operating context, particularly regarding EHR vendor consolidation timelines and hyperscaler pricing trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Long Term Post-Acute Care Software Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market
Digital Health Solutions
Digital Brain Health Market
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Asia-Pacific Heart Failure Software Market
Digital Health Solutions
Medical Virtual Reality Operating Systems Market
Digital Health Solutions
Mobile Tablets in Healthcare Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
North America Virtual Reality (VR) Health Market