
 Women Health Applications Market | 2026-2036
Women Health Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Women Health Applications Market Analytics
Subscription-based revenue models and asset-light platform delivery are reshaping competitive dynamics in women's health technology. Flo Health leverages extensive user data networks to sustain engagement across menstrual and fertility tracking. Clue specializes in hormone health analytics, differentiating through science-backed cycle insights. Apple anchors the wearable segment through tight integration of health sensors with native software ecosystems.
Women health applications encompass software and connected hardware systems that capture, analyze, and communicate biometric and self-reported data related to reproductive, hormonal, and general wellness parameters. These systems employ machine learning algorithms, Bluetooth-enabled peripherals, and encrypted cloud architectures to deliver personalized insights and clinical decision support. Mobile apps occupy the largest installed base, though wearable trackers command premium pricing through continuous physiological monitoring. AI-powered analytics represents the fastest-expanding technology layer, enabling predictive cycle forecasting and anomaly detection. Telehealth solutions are maturing as reimbursement codes stabilize, concentrating margin pools in hybrid care models that blend asynchronous data collection with synchronous clinician consultation.
FDA digital health guidance, HIPAA privacy mandates, and EU MDR requirements for software-as-medical-device collectively determine product classification, clinical validation obligations, and cross-border market access. The EU AI Act introduces additional risk-tiering for reproductive health algorithms, compelling developers to demonstrate bias mitigation and performance transparency. Stakeholders must monitor evolving regulatory divergence between jurisdictions to calibrate compliance investment against commercial expansion priorities.
Market Dynamics
AI-powered predictive analytics is compressing development cycles and forcing incumbents to rebuild core algorithms around federated learning architectures. Reimbursement code expansion for remote patient monitoring creates direct revenue pathways previously blocked by cash-pay constraints.
Growth Catalysts
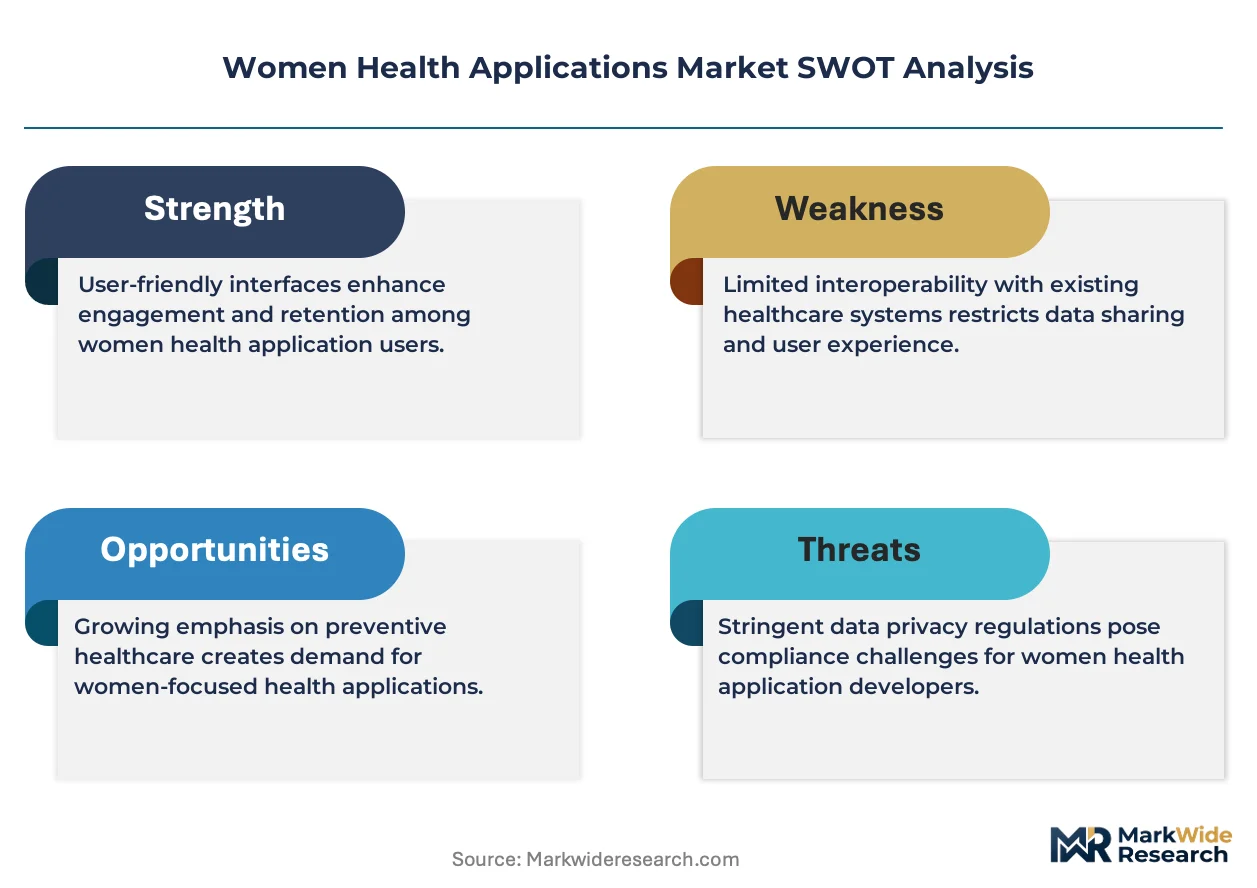
- FDA 510(k) digital health pathway:Streamlined premarket review for software-as-medical-device accelerates commercialization timelines for fertility prediction algorithms.
- Bluetooth Low Energy peripherals:Continuous temperature and hormone sensors enable passive data capture that reduces user friction and improves adherence metrics.
- Germany's DiGA fast-track:Statutory health insurance reimbursement for prescribed digital therapeutics opens institutional procurement channels for menstrual disorder management tools.
Market Restraints
- EU AI Act risk-tiering:Reproductive health algorithms face heightened transparency obligations and conformity assessment costs that deter mid-stage developers.
- Cloud infrastructure concentration:AWS, Google Cloud, and Microsoft Azure control over 80% of health data hosting, creating single-point vulnerabilities and egress cost volatility.
- Biometric sensor accuracy variance:Skin tone and body composition differences produce measurement drift that undermines clinical trust in wearable-derived insights.
Strategic Opportunities
- India's PLI scheme for medical devices:Manufacturing incentives reduce hardware production costs for locally assembled fertility monitoring kits targeting price-sensitive consumers.
- Telehealth-integrated hybrid care:Asynchronous symptom logging combined with synchronous specialist consultation captures margin pools abandoned by pure-software competitors.
- Perimenopause tracking whitespace:Hormonal transition monitoring remains underserved relative to menstrual and fertility segments, with payer interest rising as workforce demographics shift.
Industry Challenges
- Clinical validation timelines:Prospective cohort studies for cycle prediction accuracy require 12-24 month follow-up periods that delay regulatory submissions and revenue recognition.
- Interoperability with EHR systems:Epic and Cerner integration protocols demand specialized engineering resources that strain development budgets at sub-scale vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women Health Applications Market |
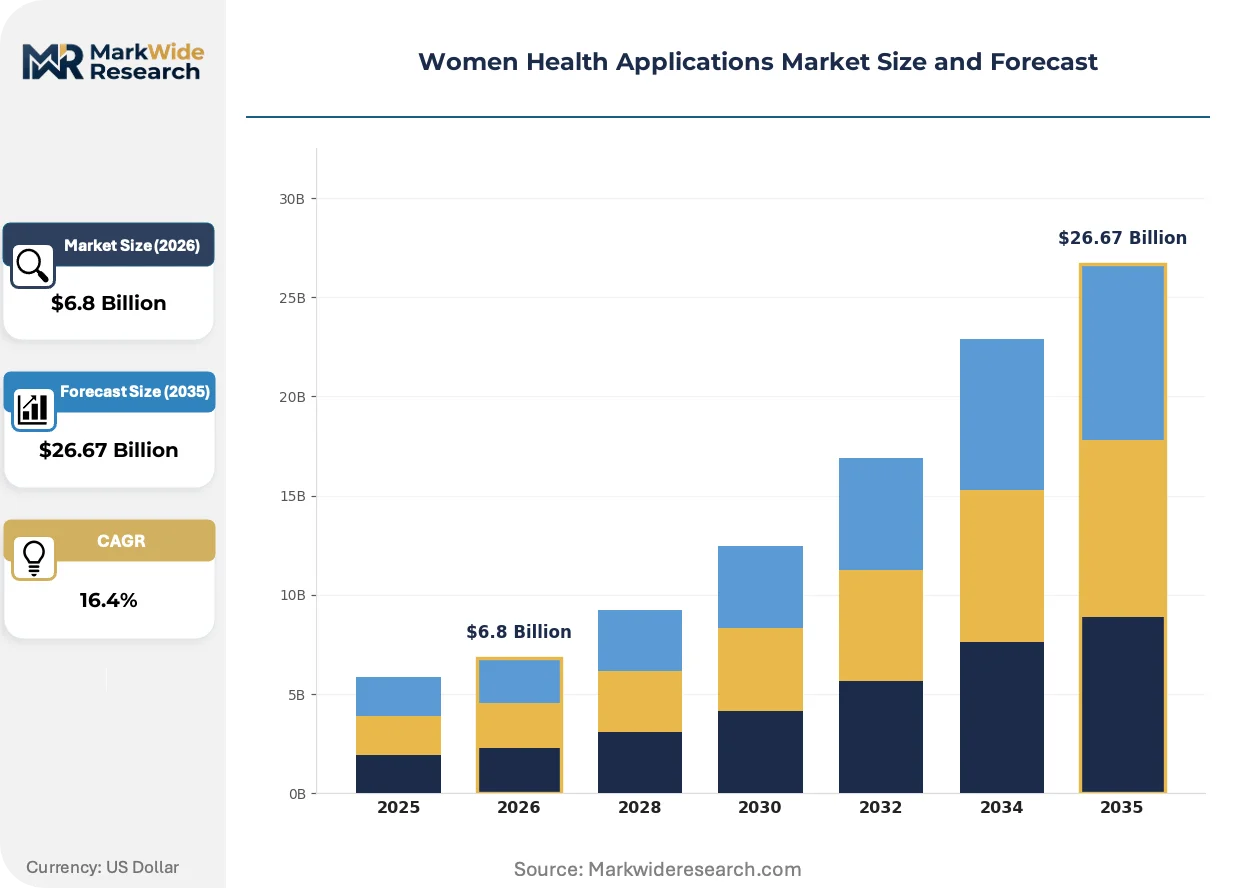
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Trackers, Mobile Apps, Telehealth Solutions, Software Platforms End User: Individuals, Healthcare Providers, Wellness Coaches, Gynecologists Technology: AI-Powered Analytics, Cloud-Based Systems, IoT Devices, Mobile Interfaces Application: Menstrual Tracking, Fertility Monitoring, General Health Management, Prenatal Support |
| Companies Covered | Flo Health, Clue, Apple, Glow, Natural Cycles, Ovia Health, Wildflower Health, Ava, Maven Clinic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women Health Applications Market Evolving Landscape
Machine learning inference is migrating from cloud servers to edge devices, reshaping data governance architectures and competitive moats. This shift enables real-time personalization while reducing transmission latency and compliance surface area.
Edge AI chipsets embedded in wearable form factors now execute menstrual phase classification without cloud round-trips. Consumer adoption concentrates among privacy-sensitive users in Germany and Switzerland who resist cross-border data transfer. Federated learning is virtualizing model training across distributed device populations, compressing the need for centralized health data repositories.
The EU AI Act's high-risk system classification for reproductive health algorithms triggers mandatory bias testing and post-market surveillance. Developers must maintain algorithmic change logs and performance metrics accessible to notified bodies. France's CNIL and Germany's BfDI are already enforcing stricter consent mechanisms than baseline GDPR requirements.
Employer-sponsored wellness programs are displacing direct-to-consumer channels as the primary acquisition path for enterprise contracts. Human resources departments negotiate volume licenses that bundle menstrual health tools with broader benefits platforms. This pattern is most visible in the United States, where self-insured employers seek medical cost reduction through preventive reproductive health interventions.
Women Health Applications Market Segmentation
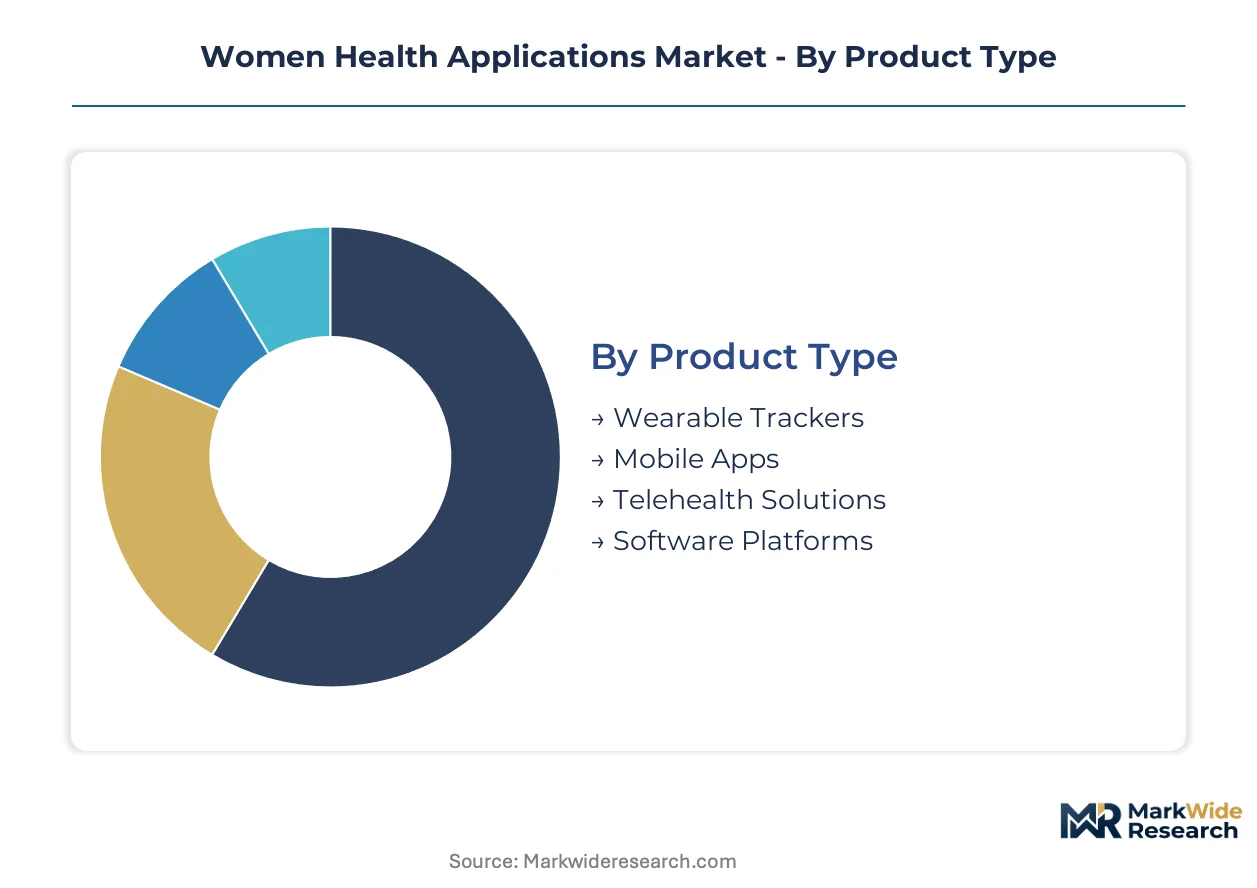
Product architecture and user interface choices in women's health applications determine data capture fidelity, clinical utility, and reimbursement eligibility. Segment boundaries blur as wearable hardware converges with software platforms and telehealth services bundle predictive analytics.
Product Type:
Mobile apps refresh fastest with quarterly feature releases, while wearable hardware cycles extend 18-24 months due to sensor validation requirements and manufacturing lead times.
- Mobile Apps:Software-only delivery through iOS and Android ecosystems minimizes distribution friction. Demand clusters among privacy-conscious users in Germany and Switzerland who resist cloud data residency risks, driving edge-computing feature prioritization.
- Wearable Trackers:Bluetooth-enabled peripherals with continuous temperature, heart rate variability, and accelerometer sensors. Premium pricing in the United States reflects employer-sponsored wellness program procurement, though skin tone measurement variance remains a clinical trust barrier.
- Telehealth Solutions:Hybrid platforms combining asynchronous symptom logging with synchronous clinician consultation. Germany's DiGA fast-track reimbursement accelerates institutional adoption for menstrual disorder management.
- Software Platforms:Enterprise-facing systems with EHR integration protocols for Epic and Cerner environments. Long sales cycles concentrate margin pools in healthcare provider networks seeking population health analytics.
Mobile apps dominate installed base. Telehealth solutions are where expansion concentrates.
End User:
Direct-to-consumer acquisition costs exceed enterprise contract economics by 3-4x, shifting vendor prioritization toward institutional channels with volume licensing potential.
- Individuals:Self-directed consumers purchasing through app stores or direct subscription. Privacy sensitivity varies sharply by geography, with EU users demanding local data processing assurances under GDPR and EU AI Act frameworks.
- Healthcare Providers:Hospitals and clinics prescribing reimbursed digital therapeutics. FDA 510(k) clearance for fertility prediction algorithms unlocks institutional procurement in the United States.
- Wellness Coaches:Independent practitioners bundling menstrual health tools with broader lifestyle intervention programs. Price sensitivity limits penetration to subscription tiers below clinical-grade platforms.
- Gynecologists:Specialist practices integrating cycle data into diagnostic workflows. Interoperability requirements with legacy EHR systems strain development resources at sub-scale vendors.
Individuals represent the largest addressable population. Healthcare providers command the steepest expansion trajectory as reimbursement codes stabilize.
Technology:
Infrastructure concentration in AWS, Google Cloud, and Microsoft Azure creates single-point vulnerabilities that edge AI architectures increasingly circumvent.
- AI-Powered Analytics:Machine learning algorithms for predictive cycle forecasting and anomaly detection. EU AI Act high-risk classification mandates bias testing and algorithmic change logs accessible to notified bodies in France and Germany.
- Cloud-Based Systems:Centralized data repositories enabling cross-device synchronization. Egress cost volatility and cross-border transfer restrictions under GDPR drive hybrid architectures with regional data residency.
- IoT Devices:Networked peripherals with Bluetooth Low Energy connectivity. Continuous passive capture reduces user friction but introduces firmware update complexity across fragmented device fleets.
- Mobile Interfaces:Native and cross-platform application frameworks. Rapid OS release cycles from Apple and Google force perpetual compatibility engineering.
Cloud-based systems anchor current deployment. AI-powered analytics is gaining share fastest as federated learning architectures mature.
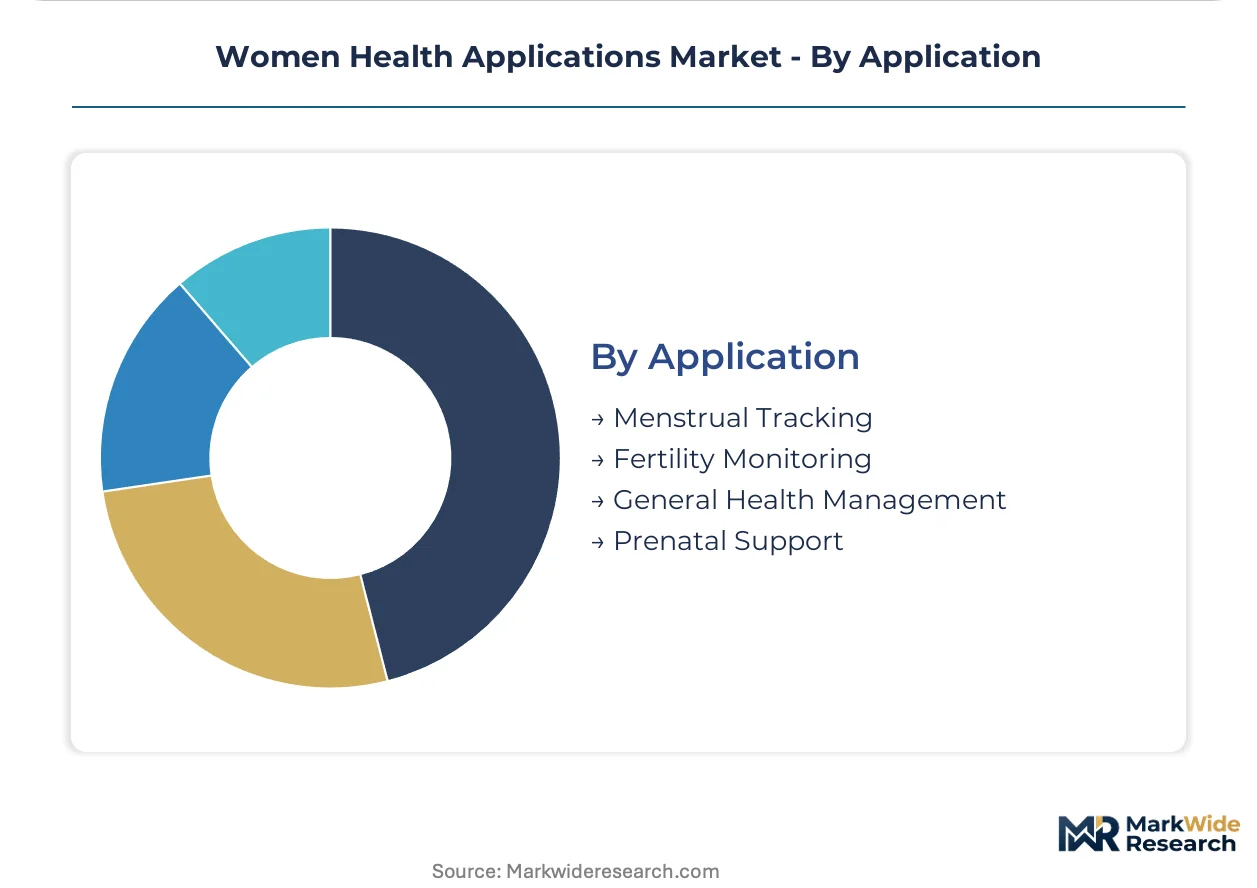
Application:
Menstrual tracking saturation contrasts with perimenopause whitespace, where hormonal transition monitoring remains underserved relative to established fertility and pregnancy segments.
- Menstrual Tracking:Cycle logging with symptom correlation and phase-based insights. Flo Health and Clue data networks establish engagement moats through historical accumulation effects.
- Fertility Monitoring:Ovulation prediction with basal body temperature and luteinizing hormone integration. FDA 510(k) pathway streamlines premarket review for algorithmic prediction claims in the United States.
- General Health Management:Broad wellness parameters extending beyond reproductive markers. Competes with generalist wearables from Apple and Samsung, diluting differentiation.
- Prenatal Support:Gestational monitoring with kick counting, contraction timing, and provider communication. Reimbursement code gaps limit institutional penetration compared to postpartum remote patient monitoring.
Menstrual tracking saturates consumer adoption. Perimenopause and fertility monitoring represent the fastest-climbing application layers as workforce demographics shift and payer interest rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented software licensing from US and European developers exceeds import demand from hardware-dependent Asian markets, creating a structural surplus in digital health trade flows. Cross-border data residency restrictions increasingly fragment cloud infrastructure deployment, forcing regional replication of core platform architectures. Reimbursement code harmonization lags behind product innovation, concentrating margin capture in jurisdictions with established digital therapeutic pathways.
United States
Employer-sponsored wellness programs drive procurement volume through self-insured health plans seeking preventive reproductive care cost reduction. FDA 510(k) digital health pathway streamlines premarket review for fertility prediction algorithms, accelerating commercialization timelines. Silicon Valley and Boston clusters concentrate venture-backed development of AI-powered cycle forecasting tools with EHR integration capabilities.
Germany
Statutory health insurance reimbursement through DiGA fast-track opens institutional procurement channels for menstrual disorder management platforms. BfDI enforces stricter consent mechanisms than baseline GDPR requirements, compelling local data processing architectures. Berlin and Munich health tech clusters specialize in edge-computing features for privacy-sensitive users resisting cross-border data transfer.
China
Domestic demand for fertility monitoring solutions expands alongside delayed childbearing demographics and two-child policy adjustments. NMPA digital health guidance determines software-as-medical-device classification and clinical validation obligations for algorithmic health claims. Shenzhen hardware manufacturers integrate Bluetooth Low Energy sensors with mobile platform ecosystems for regional distribution.
India
PLI scheme for medical devices reduces production costs for locally assembled fertility monitoring kits targeting price-sensitive consumer segments. CDSCO regulatory frameworks for software-based medical devices evolve to accommodate AI-powered diagnostic features. Bangalore and Hyderabad software clusters develop telehealth-integrated hybrid care platforms combining asynchronous data collection with synchronous specialist consultation.
United Kingdom
NHS Digital therapeutic assessment programs create procurement pathways for clinically validated menstrual health applications. MHRA post-Brexit regulatory divergence from EU MDR requirements necessitates separate conformity assessment procedures for reproductive health algorithms. London fintech-healthtech convergence clusters experiment with subscription-based revenue models for employer-sponsored wellness contracts.
Women Health Applications Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with sensor hardware and algorithmic modules. Market structure consolidates around three to five vertically integrated developers with established data network effects, while dozens of sub-scale app publishers compete on feature differentiation. Strategic archetypes include wearable ecosystem anchors, fertility-focused clinical validators, and employer-facing enterprise platforms. Competitive dynamics center on M&A activity targeting data network assets and strategic partnerships with EHR system vendors.
Within the clinical validation tier, Flo Health and Clue exemplify science-backed cycle analytics platforms with extensive longitudinal user data accumulation. Natural Cycles occupies a position among European regulatory-first developers leveraging notified body relationships for medical device certification. These three entities represent distinct geographic and regulatory strategy archetypes: UK-based scale, German precision health positioning, and Swedish medical device compliance leadership respectively.
| Leading Market Players |
|---|
| Flo Health |
| Clue |
| Apple |
| Glow |
| Natural Cycles |
| Ovia Health |
| Wildflower Health |
| Ava |
| Maven Clinic |
| Others |
Value Network & Pricing Analysis
AWS, Google Cloud, and Microsoft Azure control over 80% of health data hosting infrastructure, concentrating upstream cloud compute costs and pushing margin pools toward edge-AI chipsets and federated learning architectures that circumvent egress fees.
Pricing Analysis
Employer-sponsored wellness programs anchor subscription-based pricing structures in the United States, with self-insured health plans negotiating volume licenses that bundle menstrual health tools with broader benefits platforms. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by clinical validation grade, EHR integration depth, and after-sales clinician support. Cost compression in the direct-to-consumer tier intensifies as Flo Health and Clue data networks create engagement moats that force sub-scale app publishers toward price erosion. Healthcare providers exhibit lowest price sensitivity due to DiGA reimbursement pathways in Germany and FDA 510(k) institutional procurement channels, while individual consumers in price-sensitive markets like India drive demand for locally assembled fertility monitoring kits.
Supply Chain Analysis
Bluetooth Low Energy sensors and edge-AI chipsets feed from Taiwan semiconductor foundries, Shenzhen hardware assembly clusters, and Indian PLI-subsidized medical device manufacturing zones. Firmware development draws from Bangalore and Hyderabad software clusters, while cloud infrastructure rests on hyperscaler data centers concentrated in the United States, Ireland, and Singapore. Single-source vulnerability in AWS-Google-Microsoft cloud concentration creates regulatory risk as EU AI Act and GDPR data residency mandates force regional replication. Distribution runs through employer benefits platforms in the United States, statutory health insurance procurement in Germany, and direct-to-consumer app stores for privacy-sensitive users resisting cross-border data transfer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Women's health applications sit in early-cycle expansion as reimbursement code stabilization unlocks institutional procurement channels previously blocked by cash-pay constraints.
For Market Incumbents: Entrench data network effects by deepening longitudinal user accumulation at Flo Health and Clue scale, while accelerating FDA 510(k) submissions for fertility prediction algorithms to defend against emerging clinical-grade entrants. Prioritize backward integration into edge-AI chipset design to reduce cloud egress dependency and satisfy Germany's BfDI consent requirements. Certification investment in EU MDR and EU AI Act high-risk system classification creates regulatory moats that mid-stage developers cannot replicate. For New Entrants and Emerging Players: Perimenopause tracking whitespace in employer-sponsored wellness programs represents the most penetrable entry point, with hormonal transition monitoring underserved relative to saturated menstrual and fertility segments. India's PLI scheme for locally assembled fertility monitoring kits offers manufacturing cost advantages for price-sensitive consumer penetration. Telehealth-integrated hybrid care combining asynchronous symptom logging with synchronous specialist consultation captures margin pools abandoned by pure-software competitors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed developers holding FDA 510(k) clearances but lacking EHR integration scale, presenting consolidation targets for platform integrators seeking Epic and Cerner interoperability. Long-term viability hinges on reimbursement code expansion for remote patient monitoring and AI-powered predictive analytics. Watch DiGA fast-track adoption velocity in Germany as the inflection signal for institutional procurement scalability across European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Chipset Integration | Reduces cloud egress costs and satisfies GDPR data residency requirements in Germany and Switzerland. |
| FDA 510(k) Digital Health Pathway | Streamlines premarket review for fertility prediction algorithms unlocking institutional procurement. |
| DiGA Fast-Track Certification | Opens statutory health insurance reimbursement channels for menstrual disorder management platforms. |
| Federated Learning Architecture | Virtualizes model training across distributed devices compressing centralized health data repository needs. |
| EHR Integration Partnership | Epic and Cerner protocol compliance concentrates margin pools in healthcare provider networks. |
Research Methodology
The analysis maps mobile apps, wearable trackers, telehealth solutions, and software platforms, each validated through product managers at Flo Health and Clue, biomedical engineers at Apple, hospital purchasing committees evaluating DiGA reimbursement, and GPO contracts managers at self-insured employers. Primary interviews with CTOs designing edge-AI architectures, regulatory affairs leads navigating EU AI Act risk-tiering, and formulary directors assessing fertility prediction algorithm coverage combined with secondary validation from FDA 510(k) filings, NMPA digital health guidance, hospital procurement databases, and CMS Medicare remote patient monitoring data. Bottom-up installed base estimates triangulate against top-down reimbursement code expansion projections.
Assumptions held fixed include current FDA digital health guidance interpretation, EU AI Act enforcement patterns by France's CNIL and Germany's BfDI, and employer-sponsored wellness program procurement growth trajectories. Variables tested across the projection horizon encompass cloud infrastructure egress cost volatility, Bluetooth Low Energy sensor accuracy variance by skin tone, and perimenopause tracking payer interest acceleration. Segmentation dimensions modeled include product architecture, end-user channel, AI-powered versus cloud-based technology layer, and application from menstrual tracking through fertility monitoring to hormonal transition management. CAGRs derive from cohort retention curves, reimbursement code adoption S-curves, and hardware replacement cycle analysis.
Macroeconomic conditions sit as an overlay; deviation in employer health benefit budgets, statutory health insurance reimbursement rates, or cross-border data transfer enforcement would shift the trajectory. Forecasts reflect assumptions about regulatory pathway stability and clinical validation timeline norms. Material shifts in EU AI Act high-risk system classification interpretation or FDA 510(k) software-as-medical-device predicate device policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
Global Plastic Surgery Software Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
North America Eclinical Solutions Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Digital Biomarkers Market
Digital Health Solutions
UAE Mhealth Market
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Long Term Post-Acute Care Software Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
Mhealth Services Market