
 North America Patient Support Technology Market | 2026-2036
North America Patient Support Technology Market Size, Share, and Industry Trends Forecast 2026-2036
North America Patient Support Technology Market Analytics
Subscription-based financing for patient support platforms is reshaping competitive entry barriers across North America. McKesson Corporation leverages its pharmaceutical distribution infrastructure to anchor cloud-based adherence programs. Cardinal Health competes through specialty pharmacy integration with remote monitoring workflows. Oracle extends its health cloud architecture to capture enterprise hospital contracts in the United States and Canada.
Patient support technology encompasses digital systems, connected devices, and software platforms engineered to monitor, educate, and coordinate care for individuals managing acute or chronic conditions, typically integrating Bluetooth-enabled biometric sensors with HIPAA-compliant data architectures. Telehealth solutions and wearable technology segments lead current deployment, with artificial intelligence and data analytics representing the fastest-expanding technology layers as health systems seek predictive risk stratification. Remote monitoring devices maintain mature adoption curves in cardiac and diabetes management, while mobile apps concentrate margin pools through medication adherence licensing to pharmaceutical manufacturers.
FDA digital health guidance, CMS remote therapeutic monitoring reimbursement codes, and HIPAA security rule enforcement collectively determine product certification requirements and provider purchasing incentives across the United States. Health Canada medical device regulations and provincial privacy statutes in Ontario, Quebec, and British Columbia govern market access for Canadian deployments. Stakeholders must track evolving FDA software-as-a-medical-device classification decisions and CMS fee schedule updates to align platform development with reimbursable clinical workflows.
Market Dynamics
CMS reimbursement rule evolution for remote therapeutic monitoring is compressing provider technology procurement cycles while expanding addressable patient populations for connected care platforms.
Growth Catalysts
- RTM Reimbursement Expansion:CMS fee schedule updates for remote therapeutic monitoring create direct revenue streams for physician practices deploying biometric sensors. Clinical networks in Texas and California accelerate platform procurement.
- Bluetooth Low Energy:Wearable device manufacturers embed BLE 5.3 modules to enable continuous glucose and cardiac monitoring with extended battery life. End-use adoption concentrates in diabetes management workflows.
- Chronic Care Management:Medicare CCM billing codes incentivize health systems to invest in cloud-based patient engagement portals. Ontario provincial health authorities mirror this payment structure for primary care networks.
Market Restraints
- Semiconductor Supply Concentration:Biometric sensor chip fabrication depends on Taiwan-based foundry capacity, creating input cost volatility for device manufacturers.
- HIPAA Compliance Friction:Security rule enforcement penalties deter smaller physician practices from deploying cloud-based platforms despite clinical benefits.
- Interoperability Limitations:Proprietary data formats between EHR systems and third-party monitoring platforms force redundant integration costs.
Strategic Opportunities
- Mental Health Integration:Underpenetrated behavioral health clinics in British Columbia seek combined physical and psychological monitoring platforms.
- AI-Enhanced Risk Stratification:Machine learning algorithms converging with continuous monitoring data enable predictive intervention protocols.
- Direct-to-Employer Channels:Self-insured corporations in Quebec bypass traditional provider networks to contract platform services directly.
Industry Challenges
- Clinical Informatics Talent Scarcity:Health systems compete for data scientists capable of configuring predictive analytics on patient support platforms.
- Legacy EHR Integration Complexity:Cerner and Epic system architectures require custom API development, extending deployment timelines.
- FDA SaMD Classification Uncertainty:Evolving software-as-a-medical-device guidance delays product roadmaps for algorithm-driven diagnostic features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Patient Support Technology Market |
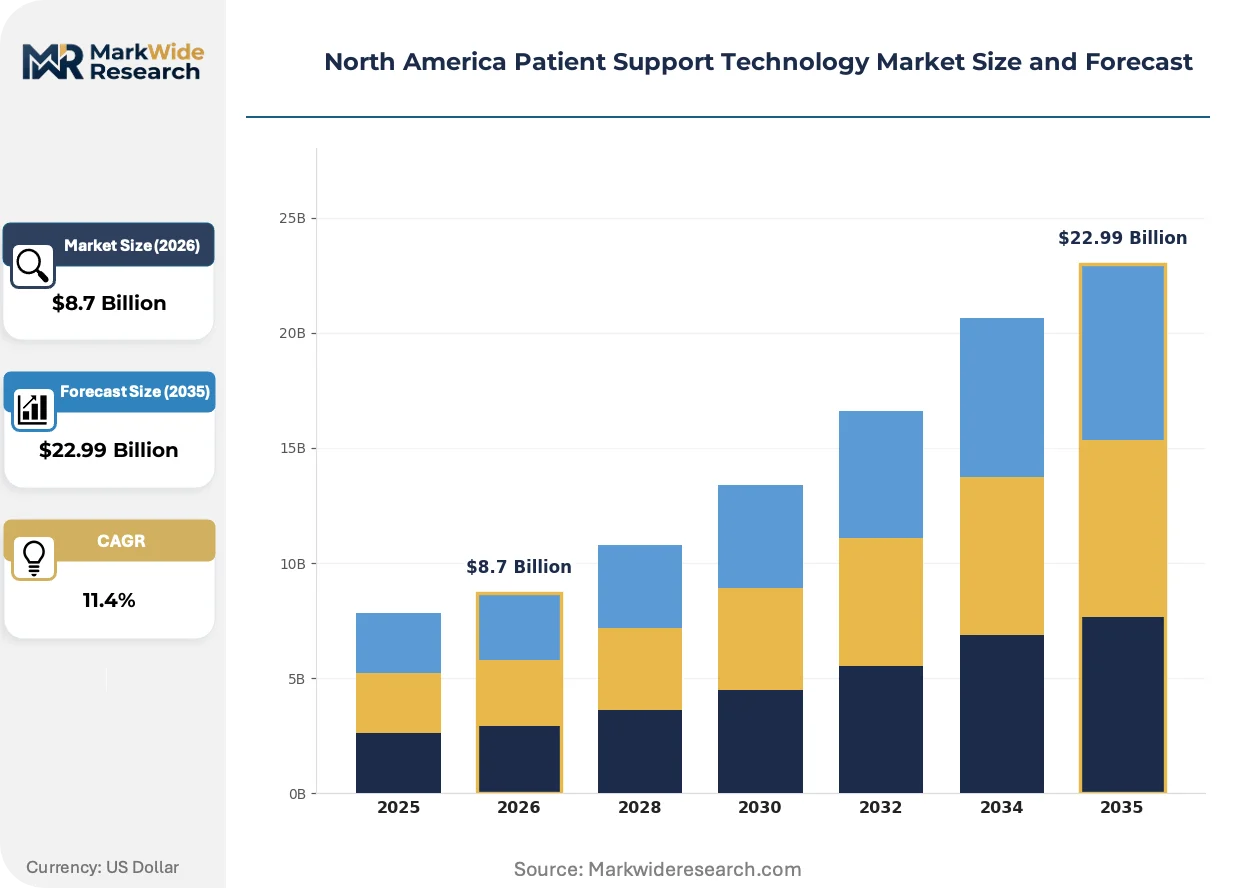
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Remote Monitoring Devices, Wearable Technology, Telehealth Solutions End User: Clinics, Home Care Providers, Hospitals, Rehabilitation Centers Delivery Model: Subscription-Based, Pay-Per-Use, Freemium, On-Premises Technology: Artificial Intelligence, Cloud Computing, Internet of Things, Data Analytics |
| Companies Covered | Deloitte, Accenture, McKesson Corporation, Cardinal Health, Inizio Engage, DataRiver S.r.l., AssistRx, Medisafe, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Patient Support Technology Market Evolving Landscape
Platform architectures are pivoting from episodic data collection toward continuous predictive models, with artificial intelligence layers becoming the primary competitive differentiator.
Continuous glucose monitoring technology is migrating from periodic fingerstick replacement toward closed-loop insulin delivery integration. Pediatric endocrinology practices in Ontario and Texas adopt these systems at accelerating pace. The technology shift is compressing margins for traditional blood glucose meter manufacturers while expanding recurring revenue pools for sensor-integrated pump manufacturers.
FDA digital health guidance for software-as-a-medical-device classification clarifies predicate pathways for algorithm-driven diagnostic tools. Device manufacturers restructure quality management systems to accommodate premarket submission requirements. Cardiac monitoring segments face the steepest compliance curve as arrhythmia detection algorithms trigger higher-risk regulatory categories.
Hospital procurement committees now require outcome guarantees from patient support technology vendors, displacing traditional perpetual license sales with performance-linked subscription structures. Medical device distributors in California and Quebec build clinical outcome measurement capabilities to support this transition. The purchasing pattern shift concentrates contract awards among vendors with established risk-sharing frameworks.
North America Patient Support Technology Market Segmentation
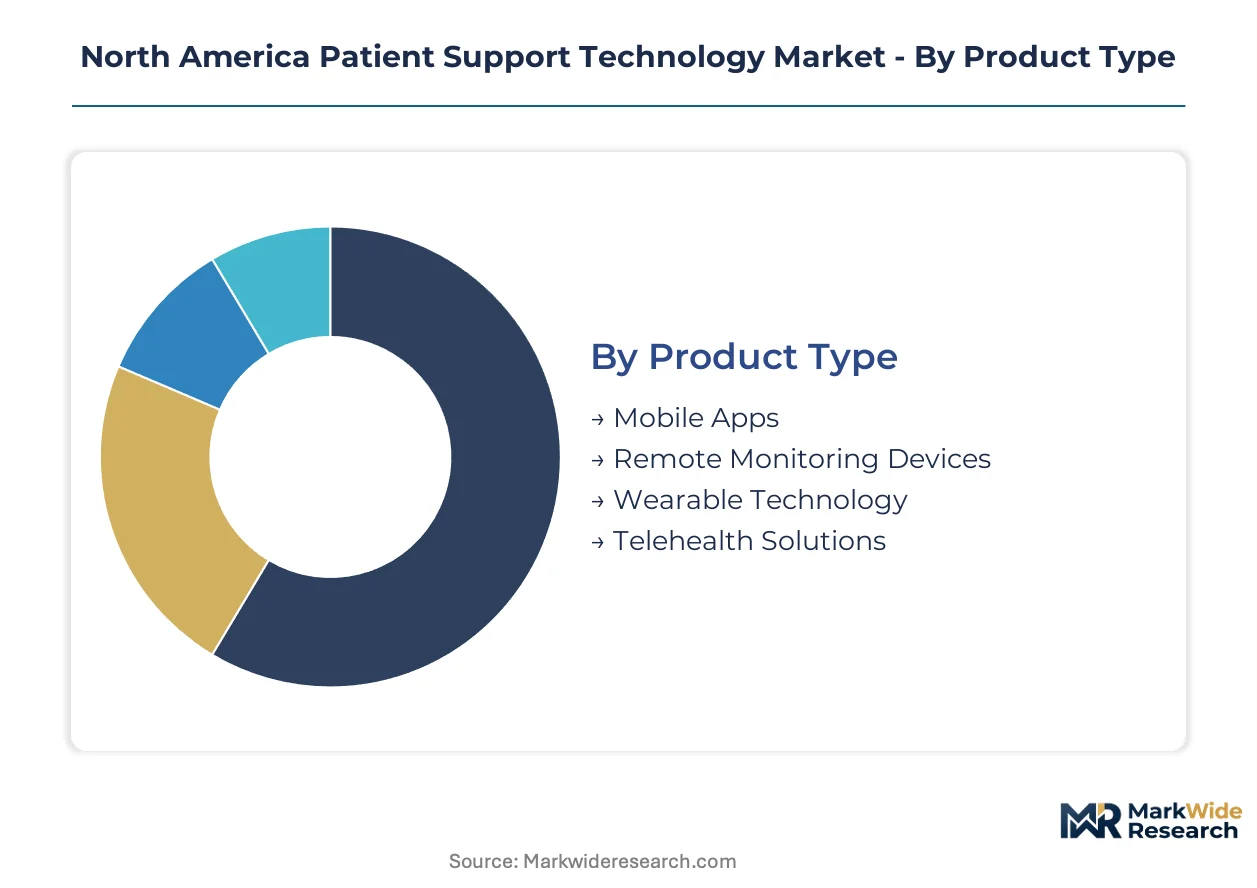
Patient support technology vendors configure platform architectures around distinct procurement patterns across North American health systems. Segmentation reveals where reimbursement rules, clinical workflows, and technology maturity intersect to determine commercial viability.
Product Type:
Cost tier differentiation separates episodic monitoring tools from continuous biometric systems with embedded predictive layers.
- Telehealth Solutions:Video-based clinical consultation platforms integrate with EHR workflows through HL7 FHIR APIs. Texas and California health systems deploy these for rural specialist access where reimbursement codes now cover synchronous virtual visits.
- Wearable Technology:Continuous glucose monitors and cardiac patches transmit BLE-encrypted biometric streams to cloud analytics engines. Ontario pediatric endocrinology practices drive demand as closed-loop insulin integration matures.
- Remote Monitoring Devices:Hub-and-spoke architectures for home-based vital sign collection.
- Mobile Apps:Medication adherence interfaces licensed to pharmaceutical manufacturers for patient engagement programs.
Telehealth solutions hold installed capacity. Wearable technology is rotating up the share rankings.
End User:
Application context determines platform complexity — acute settings demand real-time alerting while ambulatory environments prioritize patient self-management tools.
- Hospitals:Enterprise deployments require FDA-validated algorithms for inpatient deterioration detection and sepsis risk scoring. Epic and Cerner integration mandates consume implementation timelines.
- Home Care Providers:Post-acute monitoring for COPD and heart failure patients leverages cellular-connected pulse oximeters and weight scales. Medicare Advantage plans in Florida and Arizona expand coverage for these services.
- Clinics:Federally qualified health centers in Texas deploy lightweight CCM platforms for chronic disease panel management.
- Rehabilitation Centers:Musculoskeletal recovery tracking through motion sensors and patient-reported outcome tools.
Hospitals anchor current procurement volume. Home care providers are expanding most quickly as risk-based contracting proliferates.
Delivery Model:
Customer type and capital availability determine whether health systems prefer operational expenditure structures or owned infrastructure.
- Subscription-Based:Multi-year SaaS contracts with outcome guarantees displace perpetual licenses. California hospital procurement committees now mandate risk-sharing provisions for patient support platforms.
- Pay-Per-Use:Transactional pricing for episodic remote monitoring aligns with value-based care pilot programs in Ontario primary care networks.
- Freemium:Basic patient portals with premium analytics upsells target independent physician practices.
- On-Premises:Air-gapped deployments for military and correctional health facilities with stringent data sovereignty requirements.
Subscription-based models hold installed capacity. Pay-per-use is climbing the fastest as CMS reimbursement uncertainty persists.
Technology:
Technology maturity curves separate proven infrastructure layers from emerging capabilities requiring clinical validation.
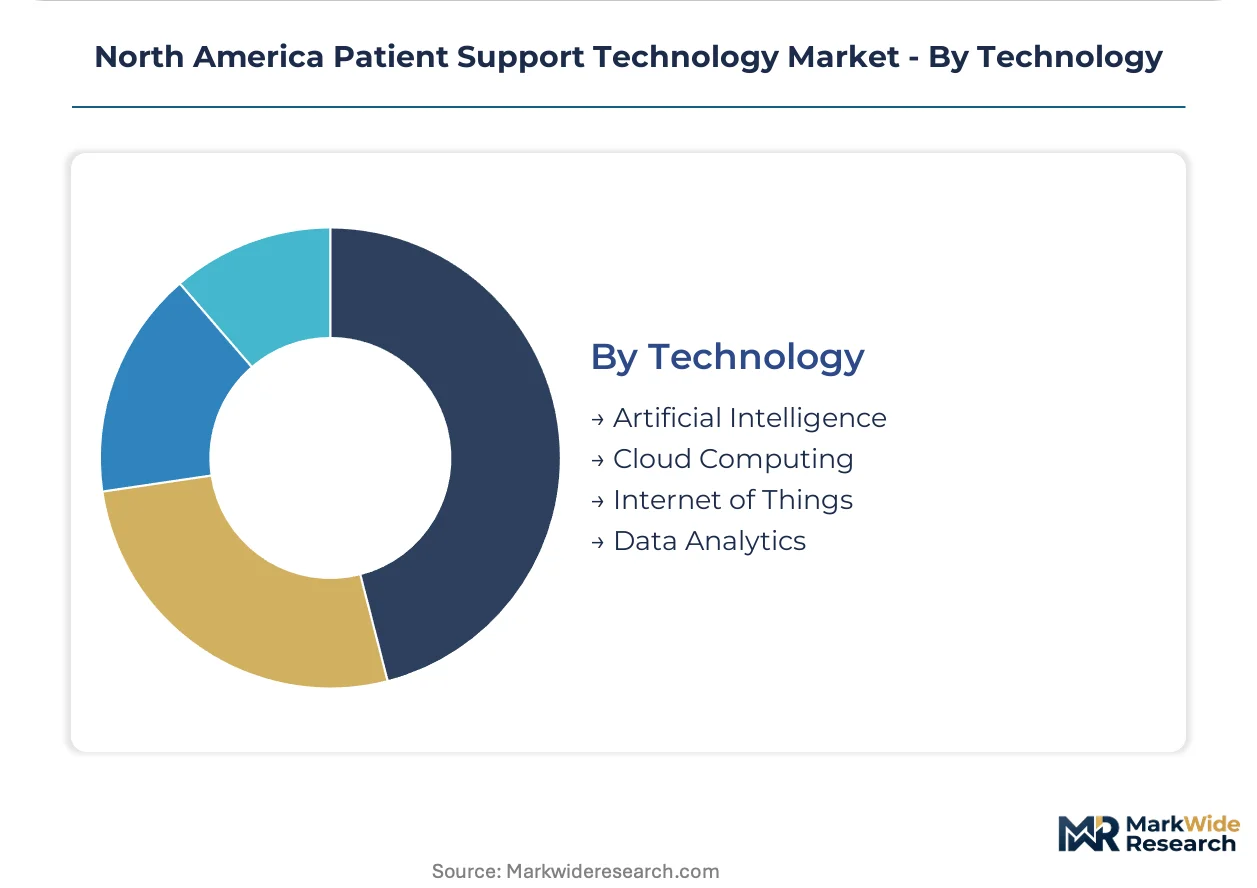
- Cloud Computing:HIPAA-compliant multi-tenant architectures enable rapid scaling across health system networks. Microsoft Azure and AWS health data lakes dominate enterprise procurement in the United States and Canada.
- Artificial Intelligence:Machine learning models for predictive risk stratification require FDA software-as-a-medical-device clearance. Cardiac arrhythmia detection algorithms face the steepest regulatory validation burden.
- Internet of Things:BLE 5.3 and LoRaWAN protocols for low-power biometric sensor connectivity.
- Data Analytics:Population health dashboards aggregating claims and clinical data for accountable care organization reporting.
Cloud computing holds installed capacity. Artificial intelligence is gaining share fastest as health systems compete for clinical informatics talent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border technology licensing and service delivery patterns define regional trade flows. Canadian health technology firms export cloud-based patient engagement platforms to United States hospital networks. Mexican medical device distributors import remote monitoring hardware from California-based manufacturers for border-state health systems.
United States
Texas and California health systems drive procurement volume for remote therapeutic monitoring platforms. CMS fee schedule updates for chronic care management create direct reimbursement pathways for physician practices. The Boston-Cambridge cluster anchors health informatics talent pipelines for predictive analytics development.
Canada
Ontario provincial health authorities mirror Medicare billing structures for primary care network investments. Health Canada medical device regulations govern software-as-a-medical-device classification for algorithm-driven diagnostic tools. Toronto-Waterloo corridor health technology startups concentrate on HIPAA-compliant cloud architectures for cross-border contracts.
Mexico
Border-state hospitals in Tijuana and Ciudad Juárez adopt telehealth platforms for specialist consultation access. Mexican national health system digitization programs expand procurement budgets for patient engagement infrastructure. Monterrey medical device distributors serve as logistics hubs for United States manufacturer supply chains.
North America Patient Support Technology Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability clusters. Pharmaceutical distributors leverage existing provider relationships to anchor adherence program platforms. Health technology specialists compete through artificial intelligence layers and predictive analytics differentiation. Enterprise software vendors capture hospital system contracts through EHR integration depth. M&A activity concentrates on data analytics capabilities, while strategic partnerships dominate cloud infrastructure deployment.
Among pharmaceutical distribution-based platform providers, McKesson Corporation and Cardinal Health exemplify the infrastructure-anchored archetype. Oracle occupies a position within the enterprise software tier, extending health cloud architectures for hospital network contracts. Deloitte and Accenture represent the consulting-integrated delivery model, combining implementation services with technology deployment for health system transformation programs.
| Leading Market Players |
|---|
| Deloitte |
| Accenture |
| McKesson Corporation |
| Cardinal Health |
| Inizio Engage |
| DataRiver S.r.l. |
| AssistRx |
| Medisafe |
| Oracle |
| Others |
Value Network & Pricing Analysis
Taiwanese foundry concentration for biometric sensor chips exposes device manufacturers to input cost volatility that widens pricing spreads between premium FDA-cleared platforms and economy-tier unregulated alternatives while compressing margins across intermediate tiers. Health systems in California and Texas respond by consolidating procurement volumes to extract subscription discounts from vendors bearing semiconductor inventory risk.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels in patient support technology markets. Premium tiers command spreads through FDA software-as-a-medical-device clearance and Epic integration certification, while economy tiers compete on per-device transactional pricing for unregulated wellness applications. Cost compression in standard-tier remote monitoring stems from Medicare Advantage plan rate pressure on post-acute providers. Federally qualified health centers exhibit highest price sensitivity; integrated delivery networks demonstrate lowest sensitivity due to risk-based contracting insulation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for Bluetooth-enabled biometric sensor manufacturers. Component sourcing draws from Taiwan for semiconductor fabrication, Mexico for final device assembly, and Malaysia for printed circuit board production. Raw material dependencies center on rare earth elements for sensor magnetics, lithium for wearable battery cells, and specialized polymers for skin-contact adhesives. Distribution runs through pharmaceutical distributors McKesson and Cardinal Health for hospital channel access, with direct-to-provider e-commerce emerging for independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through health system consolidation in Texas and California, where integrated delivery networks now command outcome-guaranteed subscription terms that extract 15-20% pricing concessions from vendors lacking risk-sharing frameworks.
For Market Incumbents: Insulate platform margins by deepening Epic and Cerner API integration to raise switching costs for hospital customers facing legacy EHR lock-in. Pursue backward integration into Bluetooth Low Energy sensor manufacturing to reduce Taiwan foundry dependency exposure. Prioritize Health Canada software-as-a-medical-device pre-certification to accelerate Ontario provincial contract awards before mid-tier competitors achieve regulatory parity. For New Entrants and Emerging Players: Establish a beachhead in British Columbia behavioral health clinics where combined physical and psychological monitoring platforms remain underpenetrated relative to cardiac and diabetes segments. Target direct-to-employer channels in Quebec self-insured corporations bypassing traditional provider network procurement. Lead with pay-per-use pricing aligned with Ontario primary care value-based care pilots rather than competing against entrenched subscription vendors in California hospital systems. For Investors and Strategic Acquirers: The market sits at a reimbursement-clarification phase that favors data analytics specialists with FDA software-as-a-medical-device clearances already in hand. Long-term viability hinges on platforms demonstrating measurable hospital readmission reduction in Medicare CCM programs. Acquisition target archetype: clinical informatics teams with deployed predictive risk stratification algorithms at Texas health systems. Signal to watch: CMS remote therapeutic monitoring fee schedule expansion beyond current respiratory and musculoskeletal codes to neurological and behavioral health indications.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Unlocks Medicare reimbursement pathways for algorithm-driven diagnostic features in cardiac monitoring segments. |
| Hospital System Risk-Sharing Partnership | Secures multi-year subscription contracts with outcome guarantees required by California procurement committees. |
| Epic Integration Certification | Eliminates redundant API development costs that extend deployment timelines for enterprise hospital contracts. |
| Bluetooth Low Energy Manufacturing Scale-Up | Reduces Taiwan foundry dependency and stabilizes input costs for continuous glucose monitor production. |
| Health Canada Pre-Certification Pathway | Accelerates Ontario provincial health authority procurement decisions for cross-border platform deployment. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee directors, biomedical engineers configuring predictive analytics, GPO contracts managers, and CMS policy specialists and refined through secondary validation. Primary research combined structured interviews with health system technology procurement leaders and remote monitoring platform product managers. Secondary sources encompassed FDA 510(k) and De Novo clearance databases, CMS Medicare fee schedule and CCM billing code documentation, Health Canada medical device active license listings, and hospital procurement database records from Texas and California integrated delivery networks. Bottom-up demand modeling triangulated against top-down health system IT spending benchmarks.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included product type tier, end-user setting, delivery model structure, and technology maturity curve position. CAGRs were derived from regression analysis against historical reimbursement code expansion patterns and health system technology procurement cycle data. Industry-specific forecast inputs incorporated CMS remote therapeutic monitoring fee schedule adoption curves and Bluetooth Low Energy protocol penetration rates in diabetes management workflows.
Sensitivities concentrate around FDA software-as-a-medical-device classification delays, Taiwan semiconductor foundry capacity constraints, and CMS reimbursement code expansion timing. Forecasts reflect assumptions regarding regulatory clarity and supply chain stability that could require revision if trade policy or pandemic disruptions resurface. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Virtual Reality (VR) in Healthcare Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
Distance Health Technologies Market
Digital Health Solutions
Global Preventive Healthcare Technologies and Services Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Medical Virtual Reality Operating Systems Market