
 Digital Health Tracking Apps Market | 2026-2036
Digital Health Tracking Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Health Tracking Apps Market Outlook
Developer talent scarcity in clinical-grade algorithm design is bifurcating the competitive landscape between medically validated platforms and consumer-grade utilities. Fitbit anchors its position through backward integration into wearable hardware and Google's cloud infrastructure. Apple Health leverages native OS distribution to sustain engagement rates that third-party alternatives struggle to match. Garmin Connect specializes in GPS-integrated performance metrics for outdoor athletes, occupying a defensible niche against generalist competitors.
Digital health tracking apps comprise software applications that capture, process, and visualize user-generated health metrics through smartphone sensors, connected peripherals, or manual input, typically operating with sampling frequencies from 1 Hz for step counting to 256 Hz for electrocardiography-grade heart rate variability. Their primary commercial purpose lies in converting raw biometric signals into actionable behavioral feedback for consumers, clinicians, or payers. Fitness monitoring dominates current revenue due to low regulatory friction and broad consumer familiarity, while chronic disease management represents the fastest-expanding margin pool as reimbursement codes mature in major markets. Wearable device compatibility increasingly determines platform selection, with smartphone-only offerings facing churn pressure as users upgrade to continuous-monitoring hardware.
FDA software-as-a-medical-device oversight and HIPAA privacy obligations govern US market entry, while the EU AI Act and GDPR impose additional algorithmic transparency and data residency requirements on European deployments. CE marking under the EU Medical Device Regulation creates a dual-track compliance burden for apps making diagnostic or therapeutic claims versus those limited to general wellness. Stakeholders must monitor evolving reimbursement eligibility criteria from CMS and national health technology assessment bodies, as coverage decisions will determine which application categories transition from direct-to-consumer to institutional procurement models.
Market Dynamics
Algorithmic clinical validation requirements under FDA software-as-a-medical-device guidance and the EU AI Act are forcing platform developers to restructure engineering teams and data governance frameworks.
Growth Catalysts
- Medicare Advantage reimbursement expansion:CMS coverage codes for remote patient monitoring are pulling chronic disease management platforms into institutional procurement channels.
- Bluetooth Low Energy 5.3:The protocol standard is enabling continuous glucose monitors and cardiac patches to stream data at sub-10mW power budgets.
- Employer-sponsored wellness mandates:Large US corporations are integrating step-counting and sleep-tracking metrics into annual premium discount programs.
Market Restraints
- Silicon photonics fabrication:PPG sensor die supply concentrates in Taiwan-based foundries, creating single-source vulnerability for heart-rate monitoring hardware.
- EU AI Act algorithmic transparency:Explainability requirements for diagnostic-grade features impose documentation burdens that extend development cycles.
- Smartphone-native utilities:Free step-counters and sleep timers embedded in iOS and Android limit willingness-to-pay for standalone fitness applications.
Strategic Opportunities
- India's Ayushman Bharat digitization:The national health stack creates distribution pathways for diabetes and hypertension management tools at population scale.
- Continuous blood pressure estimation:Optical plethysmography plus machine learning convergence promises cuffless monitoring without pneumatic hardware.
- Pharmacy benefit manager channels:CVS Caremark and Express Scripts are piloting app-based medication adherence programs with direct-to-patient deployment.
Industry Challenges
- FDA 510(k) predicate pathway:Novel algorithmic diagnostic features lack established comparators, forcing de novo review timelines.
- Clinical data scientist scarcity:Platforms struggle to hire personnel credentialed in both biomedical signal processing and regulatory submission writing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Health Tracking Apps Market |
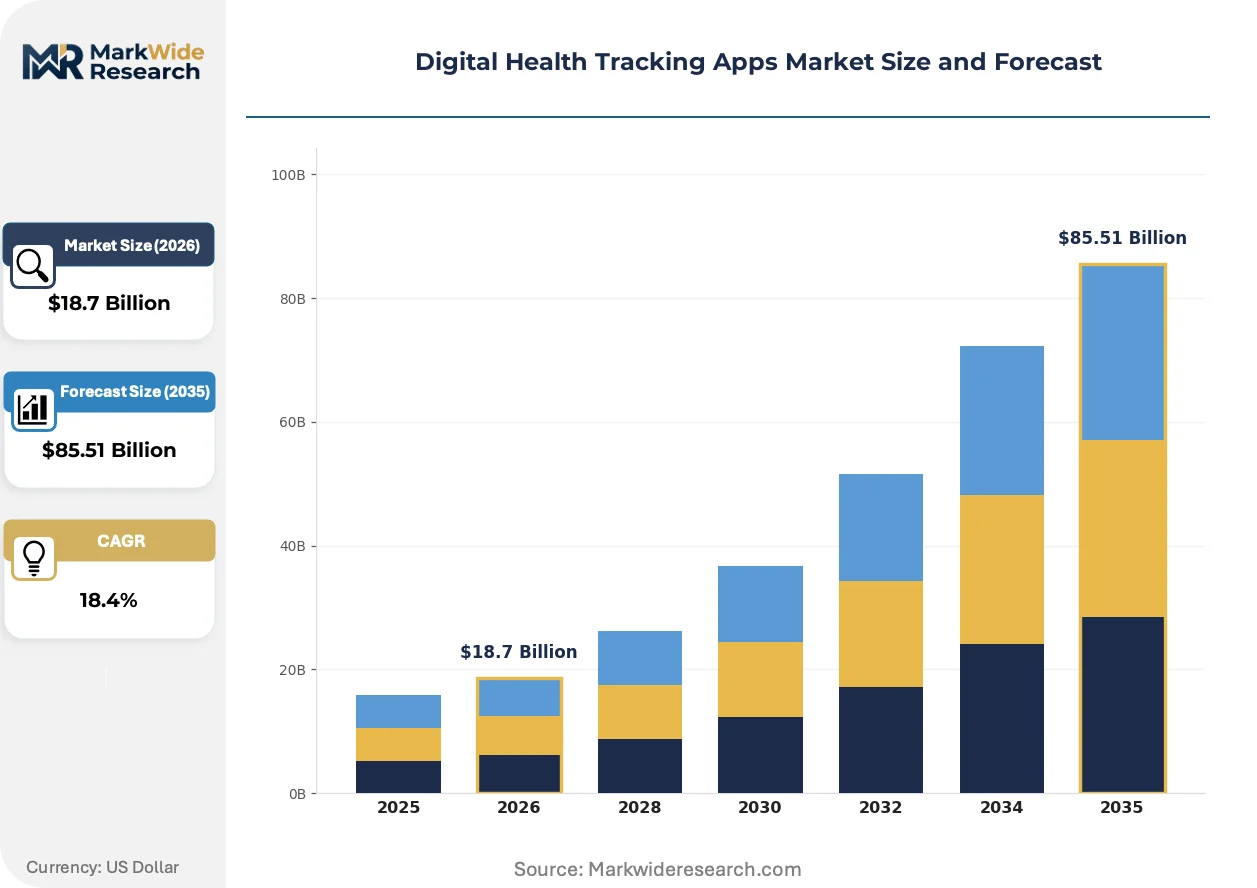
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fitness Monitoring, Chronic Disease Management, Mental Health Support, Nutrition Tracking Device Compatibility: Smartphones, Wearable Devices, Tablets, Desktop Computers Target User: Individuals, Healthcare Providers, Corporates, Fitness Enthusiasts Data Type: Physiological Data, Activity Data, Nutritional Data, Biometric Data |
| Companies Covered | Garmin Connect, MyFitnessPal (Under Armour), Fitbit (Google), Noom, Strava, Apple Health, Huawei Health, Calm, Samsung Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Health Tracking Apps Market Strategic Shifts
Hardware-software integration depth and algorithmic regulatory classification are compressing competitive differentiation windows across the developer ecosystem.
Photoplethysmography chipsets are miniaturizing to sub-2mm² die footprints while maintaining clinical-grade signal fidelity. Wearable OEMs are embedding these sensors into ring and earbud form factors previously incompatible with optical heart-rate capture. This silicon shrinkage is miniaturizing the physical barrier between consumer accessories and medical monitors.
EU Medical Device Regulation recast obligations now capture software with therapeutic claims under notified body oversight. Developers must maintain technical documentation and post-market surveillance systems comparable to implantable device manufacturers. Chronic disease management platforms targeting European deployment face CE marking timelines stretching eighteen to thirty-six months.
Hospital procurement committees are consolidating vendor relationships around enterprise-wide platform licenses rather than point-solution subscriptions. Health systems in Germany and the Netherlands are negotiating multi-year contracts bundling patient-facing apps with clinician dashboards and EHR integration layers. This committee-based purchasing concentrates contract value among vendors with full-stack clinical workflow capabilities.
Digital Health Tracking Apps Market Segmentation
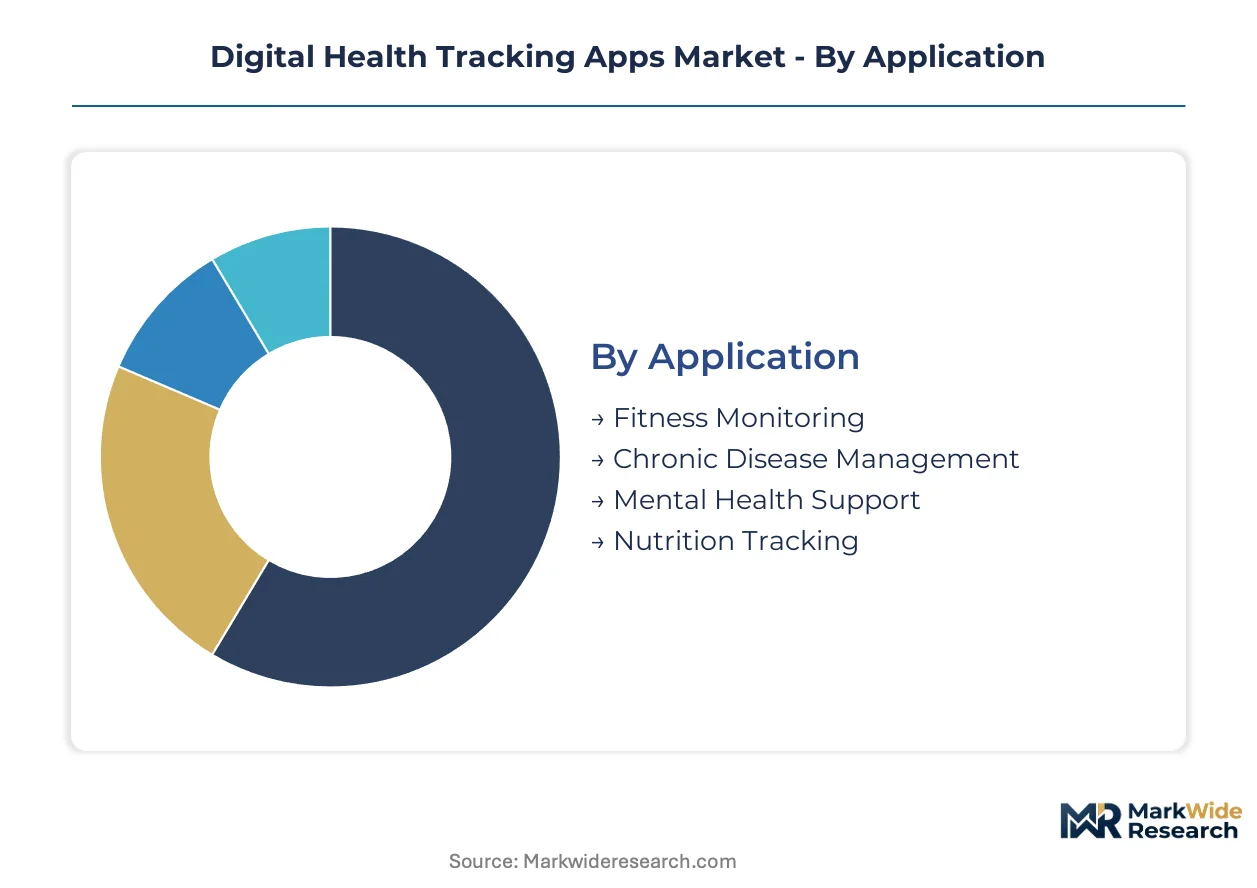
Segmentation in digital health tracking apps reveals how regulatory pathways, hardware ecosystems, and reimbursement eligibility split commercial opportunity across distinct customer profiles. Understanding these fault lines helps vendors allocate engineering resources and prioritize certification investments.
Application:
Fitness Monitoring draws primarily domestic consumer spend in the United States and Western Europe, while Chronic Disease Management platforms increasingly target export-led institutional procurement through Medicare Advantage and EU hospital networks.
- Fitness Monitoring:Step counting, workout logging, and sleep scoring dominate direct-to-consumer revenue. United States employer wellness programs and private gym chains in Germany absorb the majority of enterprise licensing volume. Bluetooth Low Energy 5.3 integration with wearable hardware sustains engagement rates.
- Chronic Disease Management:Glucose tracking, hypertension monitoring, and cardiac rehabilitation tools require FDA software-as-a-medical-device clearance or CE marking under EU Medical Device Regulation. United States Medicare Advantage reimbursement codes and Netherlands hospital procurement committees drive the fastest adoption curves.
- Mental Health Support:Mood journaling and cognitive behavioral therapy apps face FDA enforcement discretion boundaries and GDPR special category data restrictions.
- Nutrition Tracking:Calorie logging and macronutrient analysis serve weight management clinics and direct-to-consumer subscription models.
Fitness Monitoring commands the established base. The steepest expansion runs through Chronic Disease Management.
Device Compatibility:
Cost tiering separates premium continuous-monitoring hardware from free smartphone-native utilities, with subscription pricing scaling directly to sensor integration depth.
- Smartphones:Accelerometer and gyroscope-based step counters plus camera-derived heart rate estimation. Free iOS and Android utilities limit willingness-to-pay for standalone downloads.
- Wearable Devices:Photoplethysmography-enabled rings, watches, and cardiac patches stream data at clinical-grade sampling frequencies. United States and Japanese consumers upgrade fastest to continuous-monitoring form factors.
- Tablets:Larger screens suit clinician dashboard interfaces and patient education content in hospital settings.
- Desktop Computers:Web portals aggregate longitudinal data for research cohorts and enterprise wellness administrators.
Wearable Devices concentrate the premium subscriber base. Volume expansion flows through Smartphone distribution.
Target User:
Customer type determines procurement channel complexity, with Individuals purchasing through app stores, Healthcare Providers requiring EHR integration, and Corporates negotiating enterprise licenses.
- Individuals:Direct-to-consumer subscriptions and one-time purchases through Apple App Store and Google Play. Churn pressure intensifies as native OS utilities improve.
- Healthcare Providers:Hospital networks and primary care clinics demand HIPAA-compliant data flows and Epic or Cerner EHR integration. United States health systems consolidate vendor relationships around full-stack platforms.
- Corporates:Fortune 500 employers in the United States integrate step-counting metrics into annual premium discount programs.
- Fitness Enthusiasts:Amateur athletes and outdoor recreationists prioritize GPS-integrated performance metrics and training load algorithms.
Individuals anchor the installed base. Healthcare Providers are climbing the fastest as reimbursement codes mature.
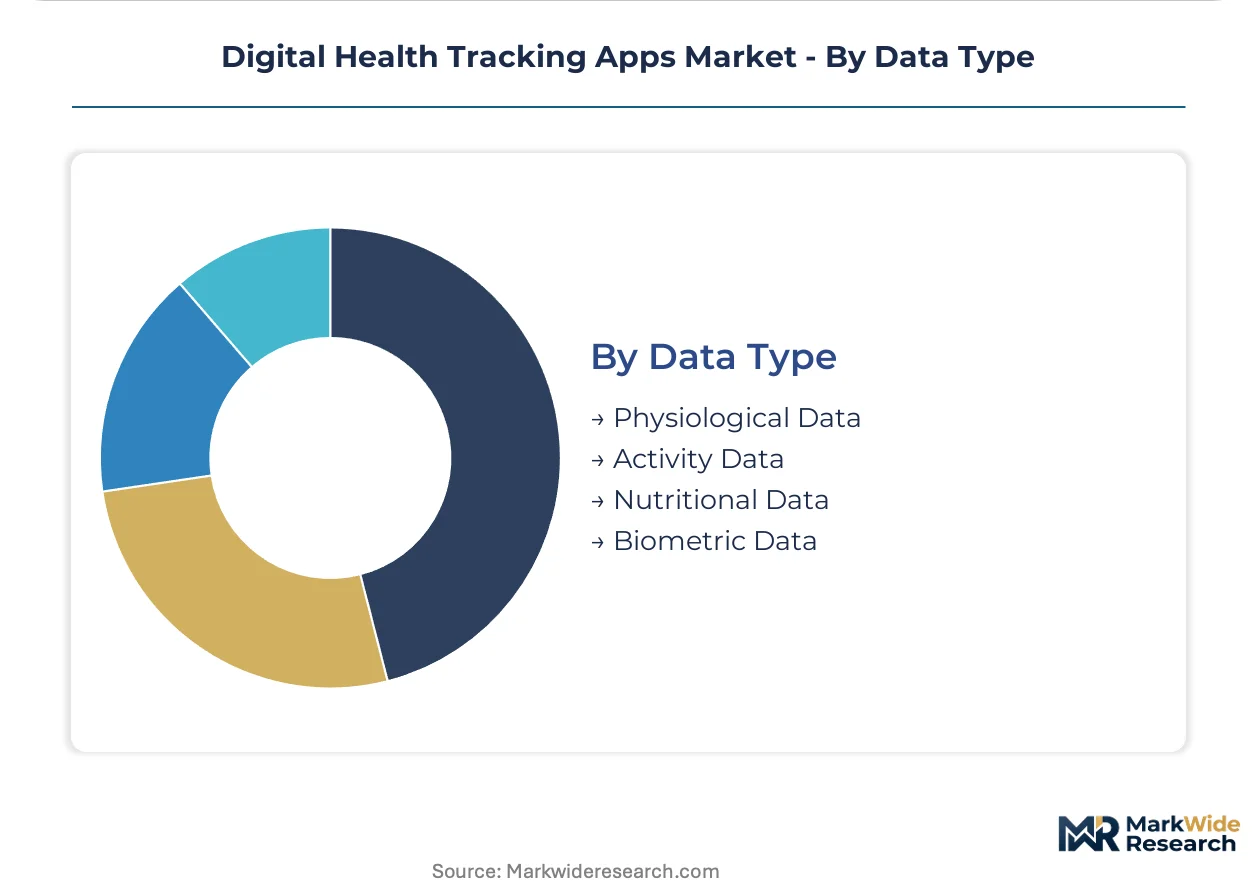
Data Type:
Margin tiering separates commodity activity logging from regulated biometric diagnostics, with FDA and EU AI Act oversight concentrating on algorithmic outputs that inform clinical decisions.
- Physiological Data:Heart rate variability, blood oxygen saturation, and electrodermal activity require clinical validation for diagnostic claims. FDA 510(k) predicates and EU notified body reviews extend development timelines.
- Activity Data:Step counts, distance traveled, and elevation gain rely on standard smartphone sensors with minimal regulatory friction.
- Nutritional Data:Barcode scanning and meal logging support dietitian consultations and diabetes management protocols.
- Biometric Data:Continuous glucose readings and cuffless blood pressure estimates demand hardware-software co-certification under FDA software-as-a-medical-device guidance.
Activity Data holds the broadest adoption. Biometric Data is gaining share fastest through continuous monitoring hardware penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where Medicare Advantage reimbursement codes and employer wellness mandates sustain premium subscription rates, while India and Southeast Asian markets operate on compressed unit economics driven by smartphone-first distribution and government-subsidized health stack access.
United States
Employer-sponsored wellness programs and Medicare Advantage remote patient monitoring reimbursement pull chronic disease management platforms into institutional procurement channels. FDA software-as-a-medical-device guidance and HIPAA privacy obligations govern market entry for diagnostic-grade features. Hospital networks in Boston and the Bay Area consolidate vendor relationships around full-stack platforms bundling patient apps with clinician dashboards.
Germany
Hospital procurement committees in North Rhine-Westphalia and Bavaria negotiate multi-year enterprise licenses bundling patient-facing apps with EHR integration layers. EU Medical Device Regulation recast obligations and the EU AI Act impose CE marking timelines of eighteen to thirty-six months for therapeutic claims. The Netherlands and German health technology assessment bodies determine reimbursement eligibility for diabetes and hypertension management tools.
China
Domestic wearable OEMs leverage sub-2mm² photoplethysmography chipsets to embed clinical-grade sensors into ring and earbud form factors. NMPA medical device registration and MIIT data localization requirements shape product certification for algorithms making diagnostic outputs. Shenzhen and Beijing clusters concentrate hardware-software co-development for cuffless blood pressure estimation using optical plethysmography plus machine learning.
India
Ayushman Bharat digitization creates distribution pathways for diabetes and hypertension management tools at population scale. CDSCO regulates software with therapeutic claims while the national health stack enables direct-to-patient deployment through pharmacy networks. Karnataka and Maharashtra host the primary engineering talent pools for clinical-grade algorithm development serving domestic and export markets.
United Kingdom
NHS England technology appraisal processes determine coverage for mental health support and chronic condition management applications. GDPR special category data restrictions and MHRA software-as-a-medical-device oversight create dual compliance burdens for apps processing biometric signals. London health tech clusters concentrate venture-backed platforms targeting export markets across the Commonwealth and European Union.
Digital Health Tracking Apps Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with medically validated platforms commanding institutional procurement premiums while consumer-grade utilities compete on smartphone-native distribution efficiency. The vendor base stratifies across three tiers: wearable-integrated full-stack providers, smartphone-dependent fitness specialists, and chronic disease management platforms requiring regulatory certification. Dominant competitive moves include backward integration into sensor hardware and strategic partnerships with hospital networks for EHR-embedded deployment.
Among wearable-integrated platform providers, Fitbit and Apple Health occupy positions exemplifying the hardware-software convergence archetype, while Garmin Connect represents specialization in GPS-integrated performance metrics for outdoor athletes. Noom and MyFitnessPal sit within the smartphone-native tier, competing on behavioral feedback algorithms without continuous monitoring hardware dependencies. These named entities anchor industry-level commentary on how platform selection increasingly follows wearable device upgrade cycles rather than standalone software features.
| Leading Market Players |
|---|
| Garmin Connect |
| MyFitnessPal (Under Armour) |
| Fitbit (Google) |
| Noom |
| Strava |
| Apple Health |
| Huawei Health |
| Calm |
| Samsung Health |
| Others |
Value Chain & Pricing Dynamics
FDA software-as-a-medical-device clearance and CE marking under EU Medical Device Regulation simultaneously gate supplier qualification and stratify price realization, with diagnostic-grade platforms commanding institutional premiums while smartphone-native utilities compete on free distribution.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise licenses from standard direct-to-consumer subscriptions. Three-tier pricing structure across premium, standard, and economy levels aligns with certification depth, with FDA-cleared chronic disease management tools at the top and unvalidated fitness trackers at the base. Cost compression in the smartphone-native tier is intensifying because iOS and Android embed free step-counters. Individual consumers exhibit highest price sensitivity, while United States hospital procurement committees show lowest sensitivity for full-stack platform bundles.
Supply Chain Analysis
Taiwan anchors photoplethysmography sensor die fabrication, while China and South Korea concentrate wearable device assembly and Bluetooth Low Energy chipset production. Raw material dependencies span silicon wafers, optical polymers, and lithium-polymer batteries. Single-source vulnerability in Taiwan-based foundries creates supply chain risk for heart-rate monitoring hardware. Distribution runs through direct-to-consumer e-commerce, hospital procurement committees, and pharmacy benefit manager channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital health tracking apps sit in early-cycle expansion, with Medicare Advantage reimbursement codes pulling chronic disease management platforms into institutional procurement faster than consumer fitness saturation.
For Market Incumbents: Shield market position through backward integration into photoplethysmography sensor hardware and captive cloud infrastructure, countering the threat of smartphone-native utilities embedding free health tracking. Prioritize FDA 510(k) clearance investment for diagnostic-grade algorithm features to maintain pricing power against consumer-grade entrants. For New Entrants and Emerging Players: Differentiate on algorithmic explainability compliant with EU AI Act transparency requirements, targeting India's Ayushman Bharat digitization as the most penetrable geography. Deploy through pharmacy network partnerships for diabetes and hypertension management tools, bypassing direct-to-consumer churn. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward platforms with established notified body relationships and post-market surveillance infrastructure. Five-to-ten year viability favors full-stack providers bridging patient-facing apps with clinician dashboards and EHR integration. Watch CMS reimbursement code expansion for remote patient monitoring as the signal indicating institutional procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Unlocks Medicare Advantage reimbursement codes for chronic disease platforms in United States hospital networks. |
| CE Marking Pathway under EU MDR | Enables eighteen-to-thirty-six month regulatory timelines for therapeutic claims in German and Dutch procurement. |
| Hospital System Partnership | Secures multi-year enterprise licenses bundling patient apps with Epic or Cerner EHR integration layers. |
| Software Companion Development | Creates clinician dashboard interfaces for continuous glucose monitors and cardiac patches streaming via Bluetooth Low Energy 5.3. |
| Reimbursement Strategy | Aligns product certification with CMS coverage codes and Netherlands health technology assessment eligibility criteria. |
Study Parameters
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, regulatory affairs leads at wearable OEMs, and pharmacy benefit manager contracts specialists, then refined against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, EU Medical Device Regulation notified body registers, and hospital GPO contract repositories. Bottom-up platform deployment estimates and top-down addressable spend calculations were triangulated across the analysis window.
Variance-decomposition framing isolates volume, price, and mix effects across segmentation dimensions including application type, device compatibility tier, target user archetype, and data type regulatory classification. CAGRs were derived from logistic adoption curves fitted to reimbursement code expansion timelines and hardware penetration rates, with continuous monitoring device upgrade cycles and institutional procurement committee consolidation serving as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA software-as-a-medical-device guidance, EU AI Act implementation, and CMS reimbursement policy; material policy shifts in any regime would require re-modeling. Recalibration cycles align with material shifts in Medicare Advantage code expansion, notified body capacity constraints, and wearable hardware form factor innovation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
Digiceuticals Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
Cardiovascular Digital Solutions Market
Digital Health Solutions
Global Plastic Surgery Software Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
Distance Health Technologies Market
Digital Health Solutions
Patient Engagement Technology Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Global Behavioral/Mental Health Software Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
Surgical Planning Software Market