
 Mixed Reality in Healthcare Market | 2026-2036
Mixed Reality in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Mixed Reality in Healthcare Market Intelligence
Hospital procurement departments are bifurcating from early research-institution buyers toward enterprise-scale clinical deployments. Microsoft leverages its cloud-hybrid HoloLens architecture to anchor enterprise health system contracts across North America and Western Europe. Osso VR sustains dominance in orthopedic surgical training through software-only distribution that sidesteps hardware margin compression. Medivis specializes in neurosurgical navigation, occupying a defensible niche against broader-platform competitors.
Mixed Reality in Healthcare denotes the integration of real-world and computer-generated environments through wearable displays, spatial sensors, and real-time rendering engines operating at sub-20-millisecond motion-to-photon latency to prevent user disorientation. These systems enable clinicians to visualize patient-specific anatomy, rehearse procedures, and guide intraoperative decision-making without full sensory isolation. Hardware captures the largest revenue share due to headset unit economics, though software margins expand faster as platforms shift toward recurring licensing. Medical Training and Surgical Simulations lead application adoption, while Rehabilitation trails due to longer reimbursement validation cycles. Augmented Reality dominates technology deployment, with Holography constrained by computational throughput and display fidelity thresholds.
FDA 510(k) and De Novo pathways govern extended reality device clearance in the United States, while the EU MDR and CE marking framework govern European market access, with both regimes intensifying scrutiny of clinical validation evidence. HIPAA and GDPR impose data governance requirements on patient-specific imaging streams processed through mixed reality cloud backends. Stakeholders must monitor evolving payer coverage determinations for procedural reimbursement codes tied to mixed reality-assisted surgery.
Market Dynamics
Hospital procurement departments are bifurcating from early research-institution buyers toward enterprise-scale clinical deployments, creating tiered demand profiles that split hardware purchasing from software licensing negotiations.
Growth Catalysts
- MDR streamlining:The EU MDR framework is accelerating CE marking timelines for extended reality surgical devices, reducing commercial entry friction for European health systems.
- Cloud-hybrid architectures:Real-time rendering engines operating at sub-20-millisecond latency are enabling intraoperative visualization without dedicated on-premise compute infrastructure.
- Academic medical center concentration:United States teaching hospitals with established digital surgery programs are expanding resident training budgets for spatial computing platforms.
Market Restraints
- Optics supply concentration:Waveguide and micro-display manufacturing concentrates among East Asian component suppliers, creating single-source vulnerability for headset producers.
- Reimbursement validation cycles:Procedural codes for mixed reality-assisted surgery lack Category I CPT status, forcing hospitals to absorb capital costs without offsetting reimbursement.
- Computational throughput limits:Holographic display fidelity remains constrained by thermal dissipation thresholds in wearable form factors.
Strategic Opportunities
- Rehabilitation underpenetration:Neurological and orthopedic rehabilitation applications trail surgical simulation in adoption, presenting whitespace for motor-learning protocols validated through payer pilots.
- AI convergence:Real-time segmentation algorithms fused with spatial mapping are enabling patient-specific anatomical overlays without preoperative manual annotation.
- IRAs hospital infrastructure incentives:United States rural hospital capital improvement provisions under the Inflation Reduction Act subsidize technology modernization eligible for mixed reality deployment.
Industry Challenges
- Spatial computing talent scarcity:Health systems face recruitment gaps for clinical engineers capable of integrating mixed reality workflows with existing PACS infrastructure.
- Multi-jurisdictional compliance:Cloud backends processing patient imaging must simultaneously satisfy HIPAA data localization and GDPR cross-border transfer requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixed Reality in Healthcare Market |
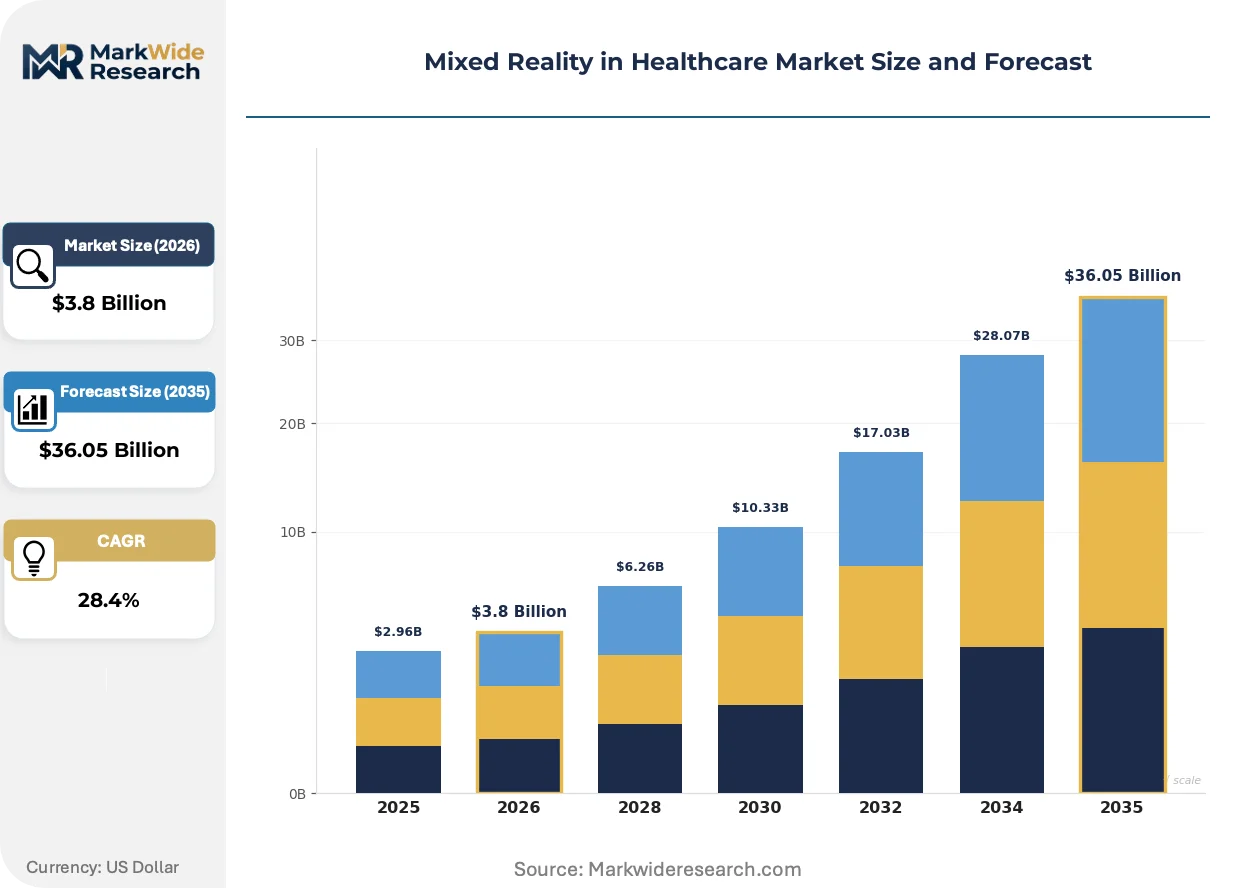
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.05 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Mixed Solutions, Accessories End User: Hospitals, Clinics, Research Institutions, Educational Facilities Application: Medical Training, Surgical Simulations, Patient Treatment, Rehabilitation Technology: Augmented Reality, Virtual Reality, Holography, Interactive 3D |
| Companies Covered | Microsoft, Osso VR, EchoPixel, Surgical Theater, Atheer, Samsung Electronics, HTC Corporation, Magic Leap, Medivis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixed Reality in Healthcare Market Strategic Shifts & Innovations
Rendering pipelines are migrating from headset-local processing to distributed cloud-edge architectures, compressing hardware cost structures while introducing network dependency risks.
Pass-through mixed reality is decomposing the historical boundary between augmented and virtual reality in surgical applications. Neurosurgical teams at Cleveland Clinic and Johns Hopkins are deploying video-see-through headsets for tumor resection planning. This convergence is collapsing the dual-device procurement model into single-platform contracts.
FDA De Novo pathway expansion for extended reality devices is formalizing clinical validation requirements beyond traditional 510(k) predicate equivalence. The agency now demands prospective studies demonstrating non-inferiority to standard visualization. Device manufacturers are responding by embedding clinical affairs teams within product development cycles.
Hospital procurement committees are consolidating vendor relationships through enterprise software licensing that decouples headset hardware from content subscriptions. Academic medical centers in the United States are negotiating multi-year platform agreements spanning surgical navigation, resident training, and patient education. This bundling compresses point-solution vendors into defensive niche positioning.
Mixed Reality in Healthcare Market Segmentation
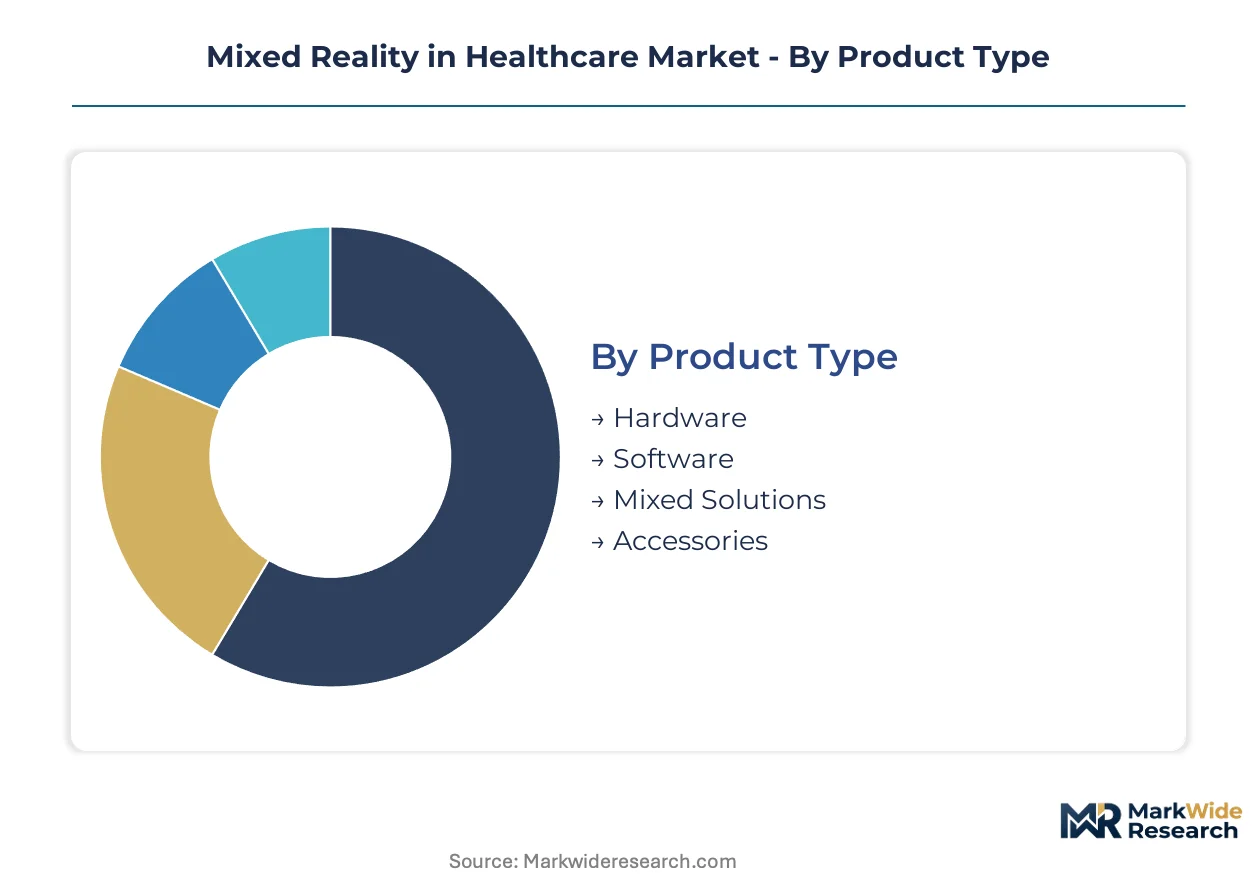
Mixed reality healthcare procurement splits along capital intensity lines, with hardware absorbing upfront budgets while software captures recurring revenue. Understanding substitution pressures across product categories reveals where vendors face margin compression versus pricing power.
Product Type:
Waveguide and micro-display supply concentration in East Asia creates substitution vulnerability for headset-dependent segments, while software-only platforms sidestep component scarcity.
- Hardware:Headset units integrating spatial sensors, optical waveguides, and rendering chipsets at sub-20-millisecond latency thresholds. Demand concentrates in United States academic medical centers expanding digital surgery programs, constrained by thermal dissipation limits in wearable form factors.
- Software:Surgical navigation platforms, anatomical visualization engines, and training modules delivered via cloud-hybrid architectures. Procurement committees at Cleveland Clinic and Johns Hopkins negotiate enterprise licenses decoupled from hardware, compressing point-solution vendors into niche positioning.
- Mixed Solutions:Bundled hardware-software contracts spanning surgical planning and resident education.
- Accessories:Sterilizable controller grips, disposable hygiene interfaces, and calibration targets.
Hardware anchors the volume base while software gains share at the steepest rate.
End User:
Procurement authority bifurcates between centralized health system IT committees and decentralized departmental buyers, reshaping contract structures.
- Hospitals:Enterprise-scale deployments across surgical suites, radiology departments, and simulation centers. United States teaching hospitals with established residency programs drive headset procurement volume, absorbing capital costs without Category I CPT reimbursement offsets.
- Clinics:Outpatient surgical centers and specialty practices deploying video-see-through headsets for preoperative planning.
- Research Institutions:Early-stage validation studies for FDA De Novo pathway evidence generation.
- Educational Facilities:Medical schools licensing orthopedic and neurosurgical training simulations.
Hospitals dominate contract value while clinics expand the addressable footprint fastest.
Application:
Reimbursement validation cycles create divergence between procedurally billable uses and cost-center training investments.
- Medical Training:Spatial computing platforms for resident skill acquisition in orthopedic and neurosurgical procedures. Academic medical centers in the United States expand simulation budgets, validated through prospective studies demonstrating non-inferiority to traditional visualization.
- Surgical Simulations:Patient-specific anatomical rehearsal and intraoperative navigation. Neurosurgical teams deploy real-time segmentation algorithms for tumor resection planning, constrained by HIPAA data localization requirements on cloud backends.
- Patient Treatment:Preoperative education and informed consent visualization.
- Rehabilitation:Motor-learning protocols for neurological and orthopedic recovery, trailing surgical adoption due to longer payer pilot timelines.
Surgical simulations command premium pricing while rehabilitation presents the largest whitespace opportunity.
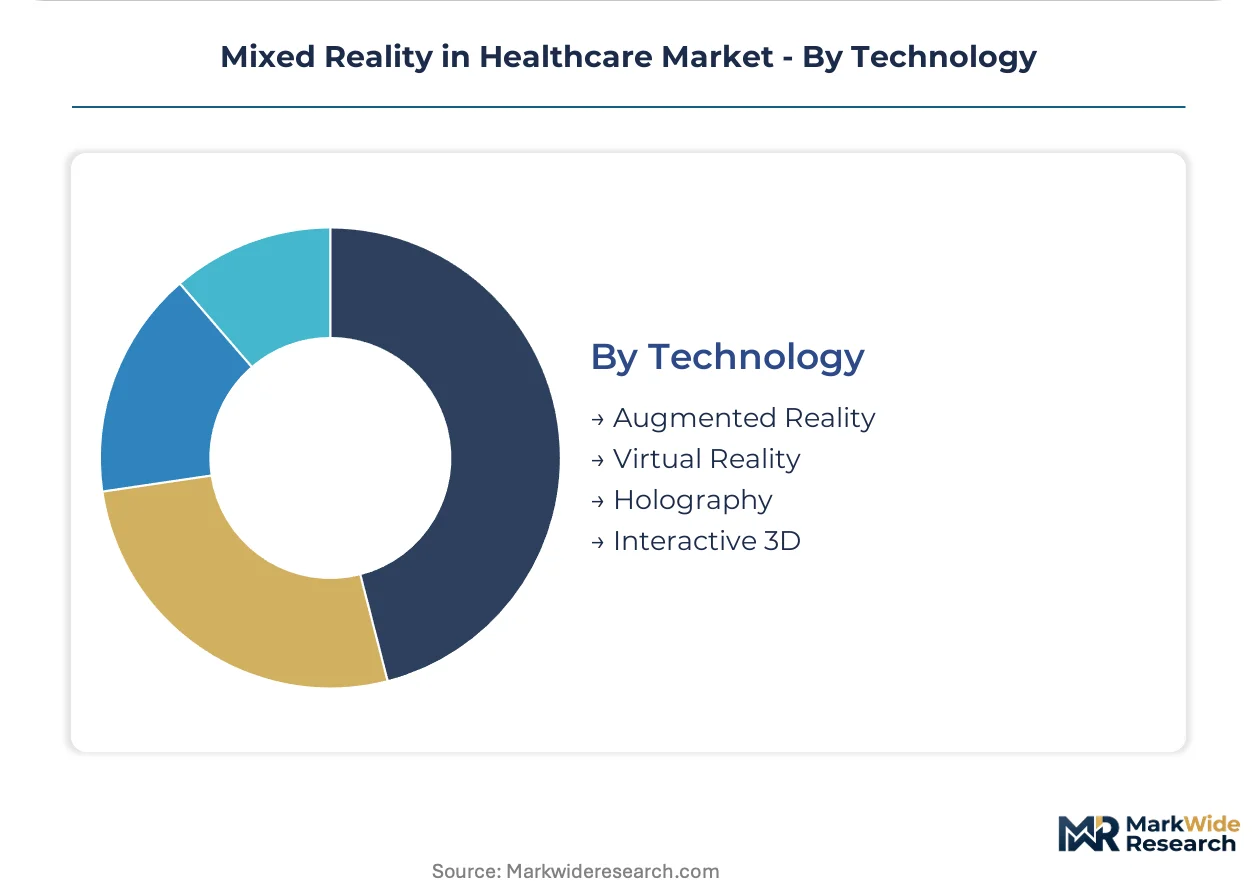
Technology:
Computational throughput thresholds constrain display fidelity, segmenting deployable solutions by rendering architecture.
- Augmented Reality:Video-see-through headsets overlaying patient-specific imaging onto physical anatomy. Pass-through mixed reality collapses the historical dual-device procurement model at Cleveland Clinic and Johns Hopkins into single-platform contracts.
- Virtual Reality:Full sensory isolation for immersive training environments, displaced by AR in intraoperative settings.
- Holography:Volumetric display systems constrained by thermal dissipation and display fidelity thresholds in wearable form factors.
- Interactive 3D:Desktop and mobile-rendered anatomical models without headset dependency.
Augmented reality captures deployment leadership while holography remains furthest from clinical viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors transatlantic data throughput through subsea cable landings at Virginia Beach and New Jersey, routing patient imaging streams to cloud-hybrid mixed reality backends. Germany's DE-CIX Frankfurt exchange handles intra-European medical data traffic for spatial computing platforms. Japan's transpacific fiber links to Oregon and California enable real-time surgical collaboration across time zones.
United States
Academic medical centers at Cleveland Clinic and Johns Hopkins deploy video-see-through headsets for neurosurgical tumor resection planning. FDA De Novo pathway expansion now demands prospective non-inferiority studies for extended reality device clearance. Greater Boston's digital health cluster concentrates venture funding for AI-converged anatomical segmentation startups.
Germany
University hospitals in Baden-Württemberg and Bavaria pilot mixed reality resident training for orthopedic procedures. EU MDR framework acceleration reduces CE marking timelines for surgical navigation devices. The Mannheim-Heidelberg medical technology corridor hosts hardware-software integration labs for holographic display validation.
Japan
Tokyo's metropolitan hospital networks integrate spatial computing for preoperative patient education and informed consent visualization. PMDA consultative pathways streamline software-as-a-medical-device classification for cloud-rendered anatomical overlays. The Osaka-Kobe manufacturing belt supplies precision optical components for waveguide-dependent headsets.
United Kingdom
NHS England's specialized commissioning frameworks evaluate mixed reality-assisted surgery for tariff inclusion. MHRA recognition of FDA clearance decisions accelerates parallel market entry for United States-validated devices. London's Imperial College Healthcare NHS Trust operates simulation centers for laparoscopic skill transfer using immersive training modules.
South Korea
Seoul National University Hospital deploys real-time rendering engines at sub-20-millisecond latency for intraoperative navigation. MFDS digital health guidance documents clarify software validation requirements for patient-specific anatomical overlays. Pangyo Techno Valley clusters health-tech startups developing AI-fused spatial mapping for surgical rehearsal.
Mixed Reality in Healthcare Market Key Industry Players
Listed leaders compete with private specialists across cloud-hybrid architecture and surgical navigation software, creating a bifurcated structure where enterprise health system contracts concentrate among platform-scale vendors while point-solution developers defend niche positioning. The vendor base splits between hardware-integrated providers absorbing waveguide supply risk and software-only distributors sidestepping component scarcity. Three archetypes dominate: cloud-platform incumbents leveraging existing enterprise relationships, surgical training specialists with validated outcome studies, and neurosurgical navigation developers occupying defensible sub-specialty positions. Competitive moves center on enterprise licensing bundling that decouples hardware from recurring subscriptions, and clinical affairs team embedding to satisfy intensifying regulatory evidence requirements.
Within the cloud-platform tier, Microsoft exemplifies enterprise-scale positioning through health system contracts spanning North America and Western Europe. Osso VR and Medivis anchor the specialization vector, with the former representing software-only distribution models that bypass hardware margin compression and the latter occupying neurosurgical navigation positioning against broader-platform competitors. Samsung Electronics and HTC Corporation sit within the consumer-electronics crossover archetype, leveraging display manufacturing scale for headset unit economics. Magic Leap exemplifies the premium hardware developer segment constrained by thermal dissipation thresholds in wearable form factors.
| Leading Market Players |
|---|
| Microsoft |
| Osso VR |
| EchoPixel |
| Surgical Theater |
| Atheer |
| Samsung Electronics |
| HTC Corporation |
| Magic Leap |
| Medivis |
| Others |
Cost & Logistics Intelligence
Cloud-hybrid rendering architectures displacing on-premise compute clusters simultaneously shift procurement geography toward hyperscaler data center regions and compress hardware margin structures for headset-dependent vendors.
Pricing Analysis
Volume-discount tiering structures dominate enterprise health system negotiations, with academic medical centers extracting steeper concessions than decentralized clinic buyers. Pricing stratifies across FDA-cleared premium tiers, CE-marked standard tiers, and research-use-only economy levels, with certification investment acting as the primary differentiation driver. Cost compression in hardware tiers is intensifying because waveguide supply concentration limits vendor negotiation leverage. Clinic buyers exhibit the highest price sensitivity, while teaching hospitals with endowed simulation budgets absorb premium positioning.
Supply Chain Analysis
Just-in-time inventory strategies prevail among software-only platforms, while hardware-integrated vendors maintain strategic stockpiles of optical waveguides and micro-displays against East Asian supply disruption. Manufacturing concentrates in Taiwan, South Korea, and Japan for precision optical components, with final assembly gravitating toward Mexico and Vietnam to manage tariff exposure. Component dependencies center on rare-earth phosphors, gallium nitride semiconductors, and high-index glass substrates. Single-source vulnerability concentrates in diffractive waveguide etching capacity. Distribution runs through health system GPO contracts and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment via FDA De Novo clearance creates substantial switching costs for hospital procurement committees.
For Market Incumbents: Fortify enterprise licensing bundling that decouples hardware from recurring software subscriptions, compressing point-solution vendors into niche positioning. Expand clinical affairs teams to satisfy intensifying non-inferiority study requirements for FDA pathway navigation. Threat vector: AI-converged segmentation startups bypassing predicate-equivalence routes through De Novo innovation claims.
For New Entrants and Emerging Players: FDA 510(k) predicate-equivalence fast-tracks offer the most penetrable regulatory avenue for surgical navigation software without novel hardware claims. Target neurological rehabilitation applications trailing surgical simulation adoption due to longer payer validation cycles. Go-to-market angle: pilot contracts with United States rural hospitals accessing IRA capital improvement subsidies for technology modernization.
For Investors and Strategic Acquirers: Capital is best deployed toward software-only platforms with validated outcome studies and health system reference contracts, avoiding hardware margin compression from waveguide supply concentration. Long-term viability hinges on recurring revenue attachment rates exceeding hardware replacement cycles. Signal to watch: Category I CPT code establishment for mixed reality-assisted procedures as reimbursement inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | Establishes non-inferiority evidence requirements for extended reality surgical devices at Cleveland Clinic validation sites. |
| CE Marking Pathway | Accelerates EU MDR commercial entry for cloud-hybrid anatomical visualization platforms in German university hospitals. |
| Hospital System Partnership | Locks multi-year enterprise licenses spanning surgical navigation, resident training, and patient education at Johns Hopkins. |
| Software Companion Development | Enables real-time AI segmentation overlays without preoperative manual annotation for tumor resection planning. |
| Reimbursement Strategy | Pursues Category I CPT status for mixed reality-assisted procedures to offset capital absorption by United States teaching hospitals. |
Research Approach
Desk research of FDA 510(k) and De Novo filings, EU MDR CE marking databases, and hospital procurement contract disclosures preceded structured interviews with hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and extended reality platform product directors. Secondary validation drew from CMS Medicare reimbursement data, academic medical center simulation budget reports, and hyperscaler health cloud infrastructure disclosures. Bottom-up unit economics for headset deployments and software licensing were triangulated against top-down health system IT spending allocations.
Variance decomposition across hardware unit shipments, software subscription attach rates, and regional reimbursement policy trajectories informed the analytical framework throughout the forecast period. Segmentation dimensions modeled include product type, end user procurement authority, application reimbursement status, and technology rendering architecture. CAGRs were derived from logistic diffusion curves for enterprise health system adoption, with inputs from resident training budget expansion rates and FDA clearance velocity for extended reality devices.
Underlying assumptions cover sustained cloud-hybrid latency performance, stable waveguide supply from East Asian component vendors, and unaltered HIPAA-GDPR data localization requirements, with deviation risk concentrated in reimbursement code establishment timelines and thermal dissipation breakthroughs in wearable holographic displays. Revision becomes warranted when Category I CPT coverage crosses statutory thresholds or when pass-through mixed reality achieves sub-10-millisecond motion-to-photon latency in single-platform deployments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
US Patient Engagement Solutions Market
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
Digital Twins in Healthcare Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Amblyopia Treatment Softwares Market
Digital Health Solutions
Digital Brain Health Market
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
UAE Mhealth Market