
 Digital Therapeutics and Wellness Market | 2026-2036
Digital Therapeutics and Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Therapeutics and Wellness Market Outlook
Subscription-based enterprise licensing and pay-per-outcome contracting is rewriting competitive economics for digital therapeutic developers. Lark Health leverages chronic disease coaching at scale to anchor employer contracts. Akili competes through FDA-cleared gamified cognitive interventions for pediatric ADHD. Welldoc specializes in diabetes management algorithms that sustain payer reimbursement relationships.
Digital therapeutics and wellness encompasses clinically validated software interventions that deliver measurable health outcomes through patient-facing applications, wearable-integrated feedback loops, and algorithm-driven behavioral protocols. Cloud computing infrastructure enables real-time biometric streaming and adaptive protocol adjustment across distributed patient populations. Chronic disease management occupies the deepest reimbursement pools as payers seek alternatives to pharmaceutical spend. Mental health support segments are expanding fastest among employer purchasers seeking EAP replacements. Software solutions command premium pricing when backed by randomized controlled trial evidence and regulatory clearance.
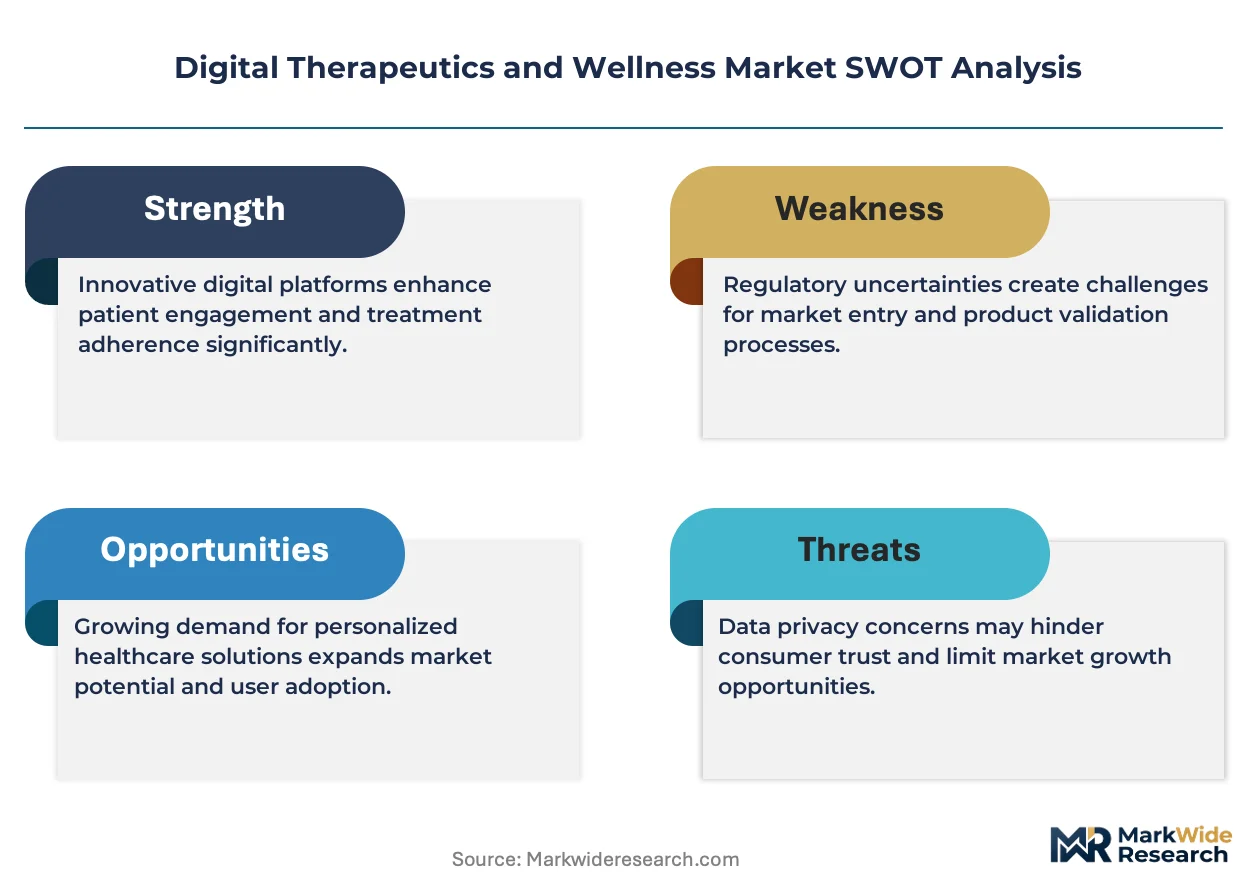
FDA software-as-medical-device oversight, Germany's BfArM DiGA approval pathway, and HIPAA data governance requirements collectively determine market access velocity and product liability exposure. The EU AI Act introduces additional conformity obligations for algorithmic health recommendations that will reshape development roadmaps. Stakeholders must monitor evolving reimbursement codes and interoperability mandates to align platform investments with sustainable revenue models.
Market Dynamics
FDA software-as-medical-device clearance pathways and Germany's BfArM DiGA fast-track are compressing time-to-reimbursement, forcing developers to restructure clinical trial investments around regulatory precedence rather than traditional pharmaceutical timelines.
Growth Catalysts
- DiGA Fast-Track Pathway:Germany's BfArM reimbursement listing within 90 days of provisional approval accelerates European market entry for chronic disease platforms.
- Employer Wellness Mandates:Large self-insured employers in the United States are replacing traditional EAP vendors with prescription digital therapeutic formularies to manage diabetes and mental health spend.
- Cloud-Native Architecture:Real-time biometric streaming and adaptive protocol adjustment enable population-scale deployment without proportional infrastructure cost scaling.
Market Restraints
- Clinical Validation Burden:Randomized controlled trial requirements for FDA SaMD clearance impose capital intensity that excludes early-stage developers without pharmaceutical partnerships.
- Reimbursement Code Fragmentation:Inconsistent CPT code coverage across US state Medicaid programs creates patchwork commercial viability.
- Algorithmic Liability Exposure:The EU AI Act's high-risk system classification for diagnostic recommendations triggers conformity assessment costs that reshape European development roadmaps.
Strategic Opportunities
- Japan's PMDA Digital Health Pathway:The Sakigake designation system offers priority review for software interventions targeting aging-related cognitive decline.
- Remote Patient Monitoring Integration:Convergence of continuous glucose monitors and behavioral coaching algorithms creates closed-loop diabetes management platforms.
- Pharmacy Benefit Manager Channels:CVS Caremark and Express Scripts formulary inclusion represents direct-to-patient distribution bypassing traditional provider sales cycles.
Industry Challenges
- Interoperability Certification Delays:HL7 FHIR compliance testing bottlenecks at ONC-authorized certification bodies extend platform launch timelines.
- Behavioral Science Talent Scarcity:Shortage of clinical health psychologists with computational modeling expertise constrains adaptive protocol development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Therapeutics and Wellness Market |
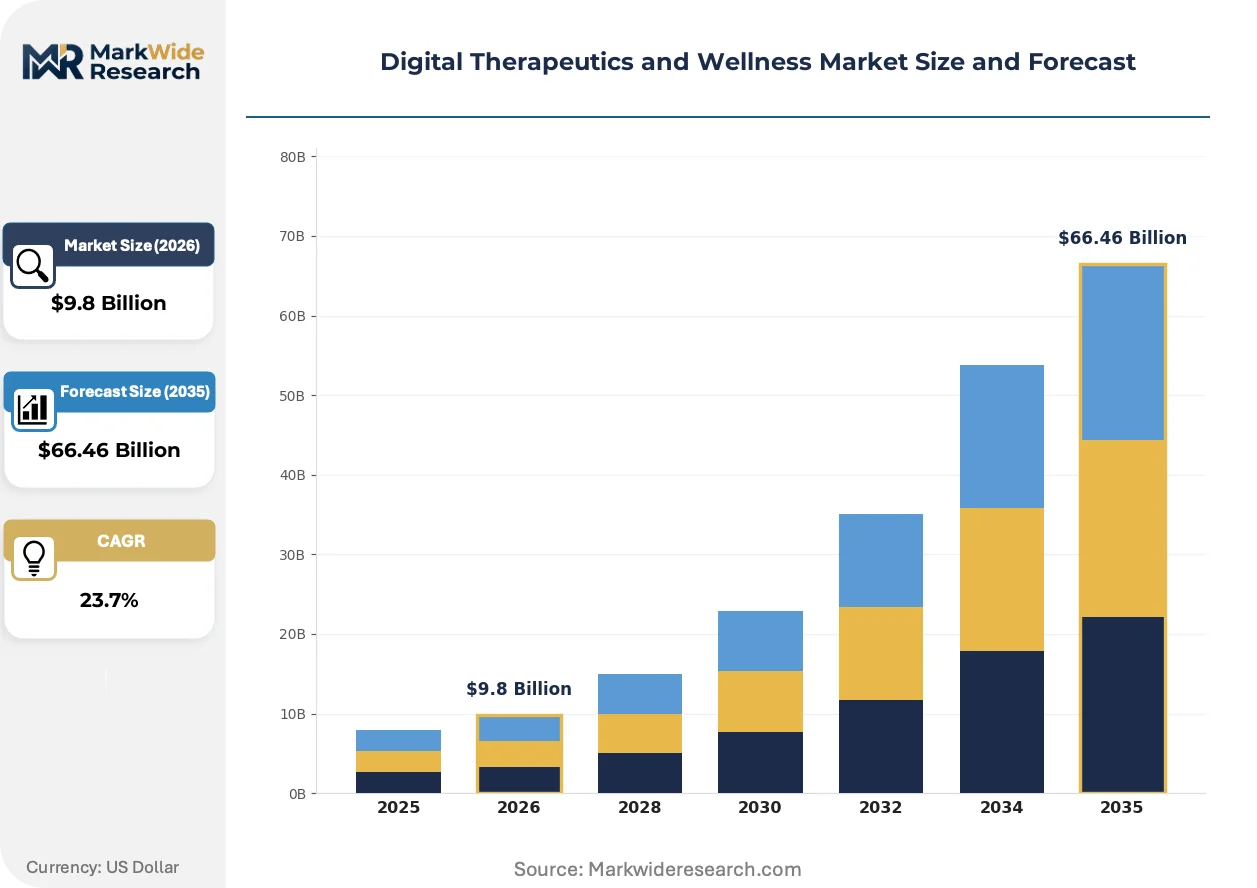
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $66.46 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Wearable Devices, Digital Programs, Software Solutions Use Case: Chronic Disease Management, Mental Health Support, Preventive Care, Rehabilitation End User: Patients, Healthcare Providers, Employers, Insurance Companies Technology: AI Algorithms, Cloud Computing, Machine Learning, Data Analytics |
| Companies Covered | Lark Health, Happify Health, Akili, Click Therapeutics, 2Morrow, Welldoc, Cognoa, Otsuka Holdings, One Drop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Therapeutics and Wellness Market Strategic Shifts
Prescription digital therapeutics are migrating from standalone applications toward embedded clinical workflow tools, with reimbursement models pivoting from per-member-per-month fees to outcome-guaranteed contracts tied to measurable biomarker improvement.
Generative AI is virtualizing patient-facing cognitive behavioral therapy delivery. Large language models trained on structured clinical protocols now power real-time therapeutic dialogue systems. Mental health platforms in the United States are deploying these systems to extend licensed therapist capacity. This architecture is virtualizing the traditional 50-minute therapy session into continuous, asynchronous intervention loops.
The EU AI Act's high-risk classification for medical device software triggers mandatory conformity assessments for algorithmic health recommendations. Developers must implement human oversight mechanisms and training data governance documentation. Mental health diagnostic modules face the steepest compliance burden, with German and French regulators already requiring algorithmic impact assessments prior to DiGA or ANSM notification.
Self-insured employers are unbundling wellness program procurement from traditional health plan contracts. Direct contracting with digital therapeutic developers allows customization of condition-specific interventions outside standard benefit designs. This pattern concentrates among Fortune 500 technology and financial services firms with dedicated health innovation procurement functions, particularly in California and New York employment markets.
Digital Therapeutics and Wellness Market Segmentation
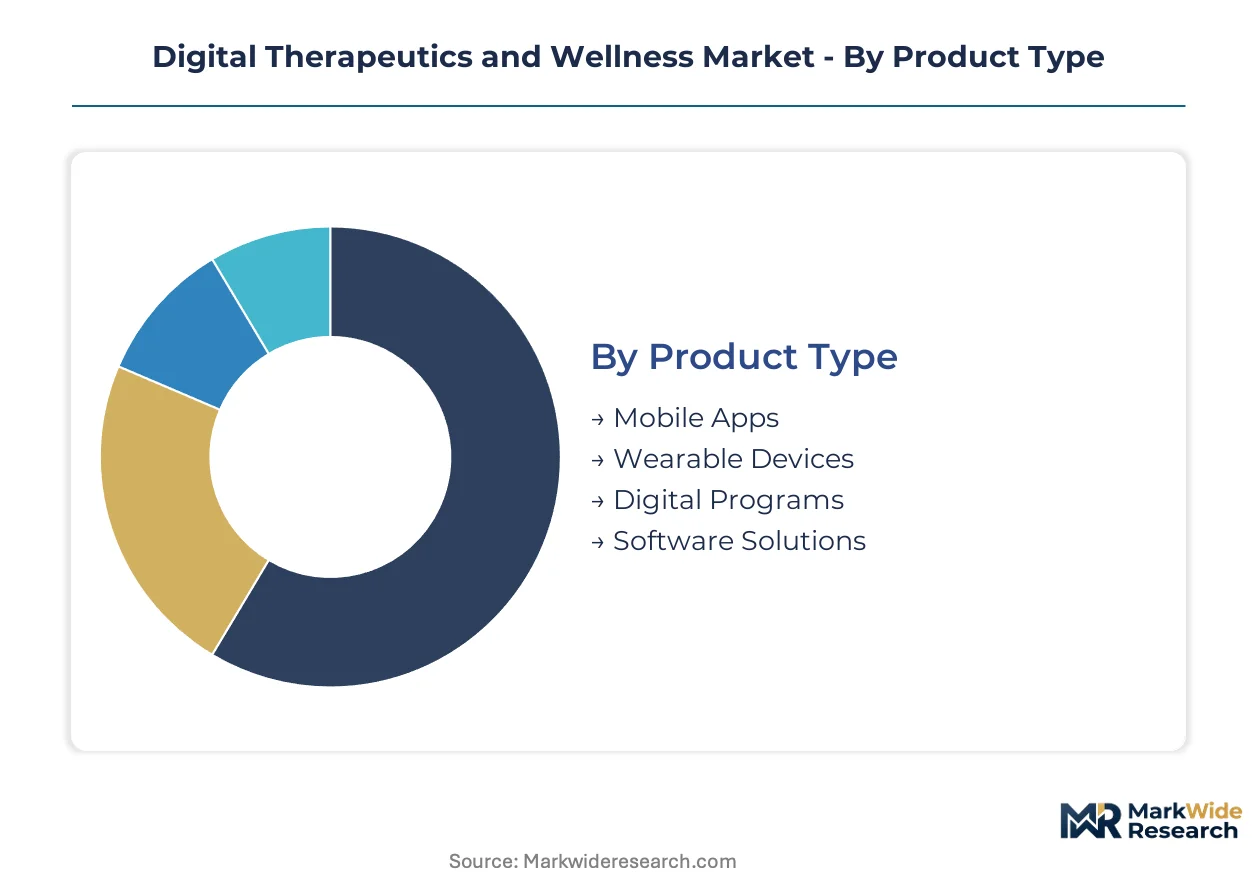
Segmentation in digital therapeutics reveals how reimbursement pathways and clinical validation requirements fragment commercial opportunity. Each dimension—product form, clinical application, purchaser type, and underlying technology—carries distinct regulatory burdens and margin structures that determine viable go-to-market strategies.
Product Type:
Use-case spectrum spans passive monitoring tools through active therapeutic interventions, with regulatory intensity escalating across the progression.
- Software Solutions:FDA-cleared algorithms delivering doseable clinical interventions through prescription pathways command premium reimbursement rates from US payers. Germany's DiGA fast-track listing enables provisional coverage within 90 days for chronic disease platforms meeting BfArM evidence standards.
- Mobile Apps:Patient-facing interfaces integrate biometric streaming from connected devices with adaptive behavioral protocols. Employer wellness contracts in the United States concentrate procurement here for diabetes and hypertension management at population scale.
- Wearable Devices:Continuous physiological monitoring hardware provides the data substrate for closed-loop therapeutic adjustments.
- Digital Programs:Structured curriculum-based interventions delivered through multi-week engagement protocols.
The dominant share belongs to Software Solutions, while Mobile Apps is closing the gap fastest.
Use Case:
Reimbursement depth correlates with pharmaceutical spend displacement potential and measurable biomarker endpoints.
- Chronic Disease Management:Diabetes and cardiovascular platforms occupy the deepest reimbursement pools as US payers seek alternatives to escalating pharmaceutical costs. Continuous glucose monitor integration with behavioral coaching algorithms creates closed-loop systems eligible for remote patient monitoring CPT codes.
- Mental Health Support:Generative AI-powered cognitive behavioral therapy delivery extends licensed therapist capacity through asynchronous intervention loops. Large self-insured employers in California and New York employment markets are unbundling these services from traditional EAP contracts.
- Preventive Care:Risk-stratification platforms targeting pre-diabetic populations and lifestyle modification.
- Rehabilitation:Post-acute recovery protocols for orthopedic and neurological conditions.
Chronic Disease Management captures the largest revenue concentration, with Mental Health Support expanding most quickly among employer purchasers.
End User:
Purchasing authority and budget ownership determine contracting complexity and sales cycle duration.
- Insurance Companies:US payers integrate prescription digital therapeutics into formularies through pharmacy benefit manager channels, with CVS Caremark and Express Scripts representing direct-to-patient distribution that bypasses provider sales cycles. Prior authorization requirements and evidence hierarchies gate access.
- Employers:Fortune 500 technology and financial services firms with dedicated health innovation procurement functions contract directly with developers for condition-specific interventions outside standard benefit designs.
- Healthcare Providers:Health system formulary committees and clinical workflow integration requirements.
- Patients:Direct-to-consumer channels for wellness-oriented applications outside prescription pathways.
Insurance Companies dominate procurement volume, while Employers are gaining share fastest through direct contracting models.
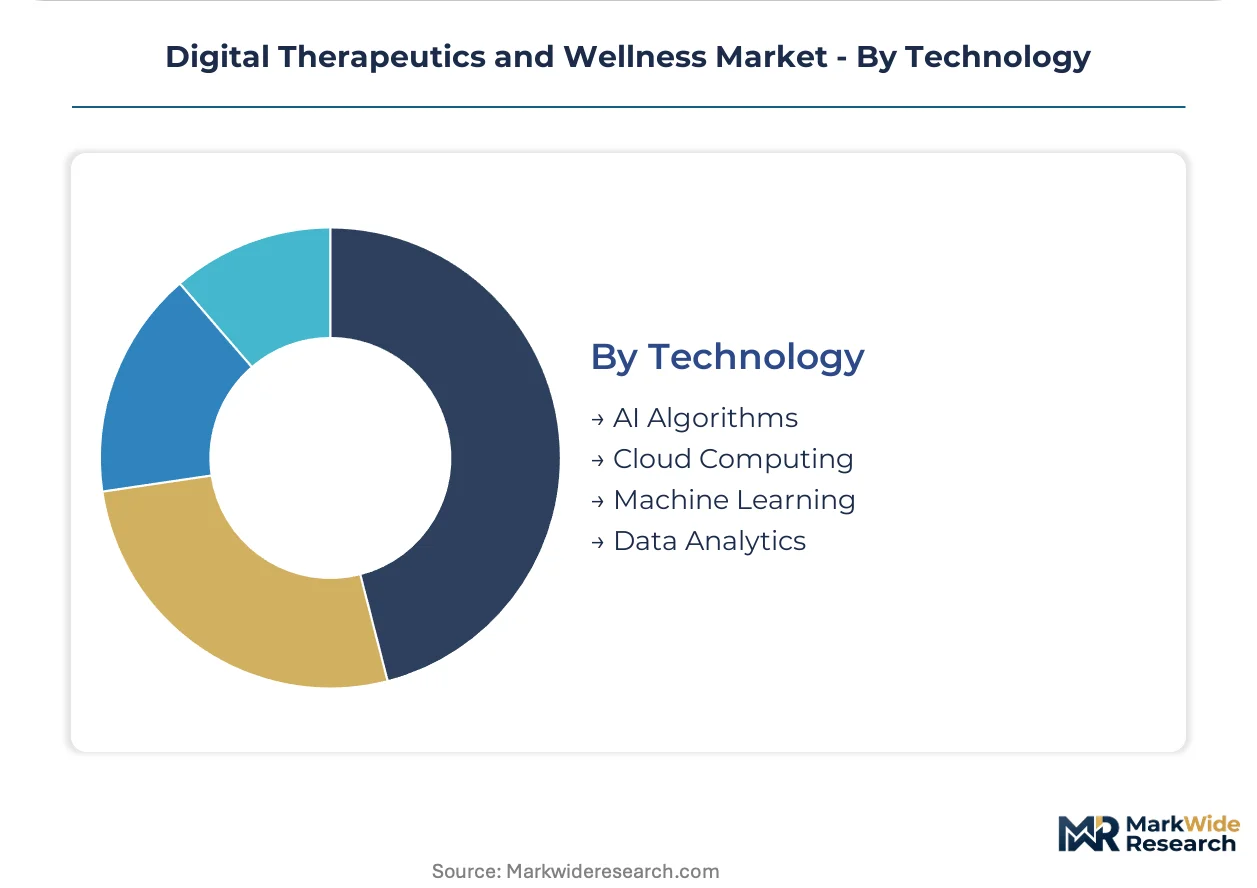
Technology:
Technical architecture determines scalability, regulatory classification, and liability exposure under emerging AI governance frameworks.
- AI Algorithms:Large language models trained on structured clinical protocols power real-time therapeutic dialogue systems for mental health delivery. The EU AI Act's high-risk system classification triggers mandatory conformity assessments and human oversight mechanisms for diagnostic recommendations in Germany and France.
- Cloud Computing:Real-time biometric streaming and adaptive protocol adjustment enable population-scale deployment without proportional infrastructure cost scaling. HIPAA data governance requirements and interoperability mandates shape platform investments.
- Machine Learning:Predictive models for risk stratification and intervention personalization.
- Data Analytics:Population health insights and outcome measurement for value-based contracting.
Cloud Computing anchors current infrastructure investment, while AI Algorithms faces the steepest compliance burden but offers the highest differentiation potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's BfArM DiGA fast-track pathway has compressed time-to-reimbursement to 90 days, triggering competitive positioning shifts among developers seeking European market entry before EU AI Act conformity obligations fully activate.
United States
Large self-insured employers in California and New York employment markets are unbundling wellness procurement from traditional health plan contracts. FDA software-as-medical-device clearance pathways anchor payer formulary integration for chronic disease platforms. The Boston-Cambridge corridor concentrates behavioral health algorithm development teams serving employer direct-contracting channels.
Germany
BfArM's provisional DiGA listing mechanism accelerates reimbursement access for diabetes and mental health applications. The EU AI Act's high-risk system classification triggers mandatory conformity assessments for algorithmic diagnostic recommendations in Berlin and Munich development centers. Bavaria's health technology cluster hosts validation partnerships between developers and statutory health insurance funds.
Japan
PMDA's Sakigake designation system offers priority review for software interventions targeting aging-related cognitive decline. METI digital health reimbursement pilots in Tokyo and Osaka create regulatory sandboxes for remote patient monitoring integration. The Kanto region anchors partnerships between domestic pharmaceutical conglomerates and software developers seeking hybrid therapeutic platforms.
United Kingdom
NICE evidence standards for digital health technologies gate NHS England commissioning decisions for mental health and diabetes applications. MHRA software-as-medical-device guidance shapes clinical trial investment structures in London and Cambridge health technology clusters. The Greater Manchester devolved health system pilots direct-to-patient distribution models bypassing traditional provider sales cycles.
France
ANSM notification requirements and CNIL algorithmic impact assessments impose dual compliance burdens on diagnostic recommendation modules. The Paris-Saclay health innovation cluster concentrates development teams navigating MDR and EU AI Act convergence. Lyon-based university hospitals anchor real-world evidence generation partnerships for chronic disease management platforms.
Digital Therapeutics and Wellness Market Competitive Environment
Channel-controlling players compete with product-specialist players across reimbursement-dependent and employer-direct contracting channels. Market structure fragments across FDA-cleared prescription platforms, employer wellness applications, and hybrid chronic disease management systems. Three archetypes dominate: pharmaceutical-backed developers leveraging regulatory expertise, pure-play software firms scaling cloud-native architectures, and health system spinouts embedding clinical workflow integration. Competitive moves concentrate on formulary inclusion negotiations and direct employer contracting bypassing traditional provider sales cycles.
Within the chronic disease management tier, Welldoc and Lark Health exemplify divergent scale strategies, while Akili occupies a position in pediatric cognitive intervention specialization. These three anchors represent how FDA clearance depth, employer contract anchoring, and condition-specific clinical validation respectively determine reimbursement access velocity and sustainable revenue model architecture across the competitive spectrum.
| Leading Market Players |
|---|
| Lark Health |
| Happify Health |
| Akili |
| Click Therapeutics |
| 2Morrow |
| Welldoc |
| Cognoa |
| Otsuka Holdings |
| One Drop |
| Others |
Value Chain & Pricing Dynamics
The trans-Pacific fiber-optic cable corridor carries algorithmic health data flows between US cloud regions and Asian development centers, with bandwidth cost volatility compressing margins for biometric streaming platforms while concentrating pricing power among hyperscaler-anchored developers with captive infrastructure.
Pricing Analysis
Certification level creates the primary spread between reimbursement-eligible and wellness-tier offerings, with FDA-cleared software-as-medical-device platforms commanding premium enterprise licensing rates against uncertified mobile health applications. Three-tier pricing structure across prescription-grade, employer-sponsored, and direct-to-consumer levels reflects clinical validation depth and regulatory clearance status. Pricing pressure stems from employer procurement teams demanding outcome-guaranteed contracts tied to measurable biomarker improvement. Self-insured employers in California and New York employment markets exhibit lowest price sensitivity due to dedicated health innovation budgets, while state Medicaid programs demonstrate highest sensitivity amid inconsistent CPT code coverage.
Supply Chain Analysis
Contract manufacturing for wearable biometric sensors concentrates in Taiwan and South Korea, with Foxconn and Pegatron holding dominant assembly capacity for continuous glucose monitors and activity trackers. Cloud infrastructure draws from US hyperscaler regions and European data centers governed by GDPR localization requirements. Supply chain risk centers on single-source vulnerability for specialized physiological sensors and FDA-registered component suppliers. Distribution runs through pharmacy benefit manager channels including CVS Caremark and Express Scripts, bypassing traditional medical device sales cycles for direct-to-patient fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital therapeutics represents a high-growth disruption as FDA software-as-medical-device pathways and Germany's DiGA fast-track compress time-to-reimbursement from pharmaceutical timelines to 90-day provisional coverage windows.
For Market Incumbents: Insulate formulary positions by deepening clinical validation investments in randomized controlled trials and securing pharmacy benefit manager channel exclusivity before EU AI Act conformity assessments activate. Defend against pure-play software entrants by embedding platforms into electronic health record workflows through HL7 FHIR interoperability certification. Prioritize backward integration into proprietary algorithm development rather than licensed cognitive behavioral therapy content. For New Entrants and Emerging Players: Pursue white-space opportunity in Japan's PMDA Sakigake pathway for aging-related cognitive decline interventions, where priority review timelines favor first movers. Target mental health support segments among Fortune 500 employers unbundling wellness procurement from traditional EAP contracts. Anchor go-to-market strategy through direct contracting with health innovation procurement functions rather than health system formulary committees. For Investors and Strategic Acquirers: Cloud-native chronic disease management platforms with proven employer contract anchoring and FDA clearance depth represent the highest-conviction acquisition archetype for pharmaceutical-backed portfolio expansion. Long-term viability hinges on sustainable reimbursement code capture across state Medicaid programs and commercial payer formularies. Watch for inflection signals in CMS remote patient monitoring code expansion and EU AI Act high-risk system classification enforcement actions.| Strategic Initiative | Industry Significance |
|---|---|
| DiGA Fast-Track Submission | BfArM provisional listing within 90 days accelerates European reimbursement access for chronic disease platforms. |
| Pharmacy Benefit Manager Formulary Inclusion | CVS Caremark and Express Scripts channels bypass provider sales cycles for direct-to-patient distribution. |
| HL7 FHIR Interoperability Certification | ONC-authorized testing enables clinical workflow embedding required by health system procurement committees. |
| EU AI Act Conformity Assessment | Mandatory human oversight mechanisms and training data governance documentation gate European market entry. |
| Employer Direct Contracting Model | Fortune 500 technology and financial services firms customize condition-specific interventions outside standard benefit designs. |
Study Parameters
A standing panel of digital health regulatory affairs leads, employer benefits directors, pharmacy benefit manager formulary specialists, and hospital biomedical engineers provided ongoing calibration across the study period. Primary interviews with FDA software-as-medical-device clearance consultants and BfArM DiGA application reviewers combined with secondary validation from FDA 510(k) filings, BfArM reimbursement listings, CMS CPT code decisions, and employer wellness procurement databases. Bottom-up triangulation across platform deployment metrics and top-down reconciliation against payer pharmaceutical spend displacement targets anchored market size estimation.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling across product type, clinical application, purchaser archetype, and underlying technical architecture. Deployment model, organization size, vertical integration complexity, and regional regulatory pathway adoption patterns shaped volume and value disaggregation. CAGRs derived from reimbursement code expansion trajectories and employer wellness procurement velocity, with cloud infrastructure cost curves and clinical trial investment intensity as additional forecast inputs.
Sensitivities concentrate around FDA SaMD clearance timeline delays, EU AI Act high-risk system classification enforcement variance, and state Medicaid CPT code coverage fragmentation. Forecasts reflect assumptions on employer unbundling momentum and pharmaceutical partnership appetite for digital therapeutic co-development. Quarterly review of BfArM provisional listing volumes, CMS remote patient monitoring code utilization, and Fortune 500 direct contracting announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
Global Metaverse in Healthcare Market
Digital Health Solutions
Global Patient Engagement Solution Market
Digital Health Solutions
Global Plastic Surgery Software Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
Middle East and Africa Virtual Reality (VR) Health Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
Cardiac AI Monitoring and Diagnostic Market
Digital Health Solutions
Amblyopia Treatment Softwares Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Healthcare Digital Experience Platform Market