
 Augmented and Virtual Reality in Healthcare Market | 2026-2036
Augmented and Virtual Reality in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented and Virtual Reality in Healthcare Market Analysis
EU MDR is rebalancing the cost-of-entry calculus for immersive surgical training platforms seeking CE marking across European markets. SimX leverages its military-derived simulation architecture to anchor defense and civilian healthcare contracts simultaneously. AppliedVR differentiates through FDA-cleared prescription VR for chronic pain, occupying a narrow but defensible regulatory niche. Osso VR leads in orthopedic procedure simulation, sustaining high R&D intensity through partnerships with major medical device manufacturers.
Augmented and virtual reality in healthcare encompasses wearable displays, spatial computing software, and sensor arrays that overlay digital anatomical models onto physical environments or immerse users in fully simulated clinical scenarios; these systems typically operate at sub-20 millisecond motion-to-photon latency to prevent simulator sickness during extended training sessions. The primary purpose is to reduce surgical error rates, accelerate clinician proficiency curves, and deliver non-pharmacological pain interventions at scale. Hardware captures the largest revenue share due to recurring headset refresh cycles and haptic peripheral upgrades, while software and content creation segments exhibit faster growth as institutions shift from perpetual licenses to subscription-based simulation libraries. Services remain the most margin-constrained category, though integration and training bundles command premium pricing when bundled with enterprise hardware deployments.
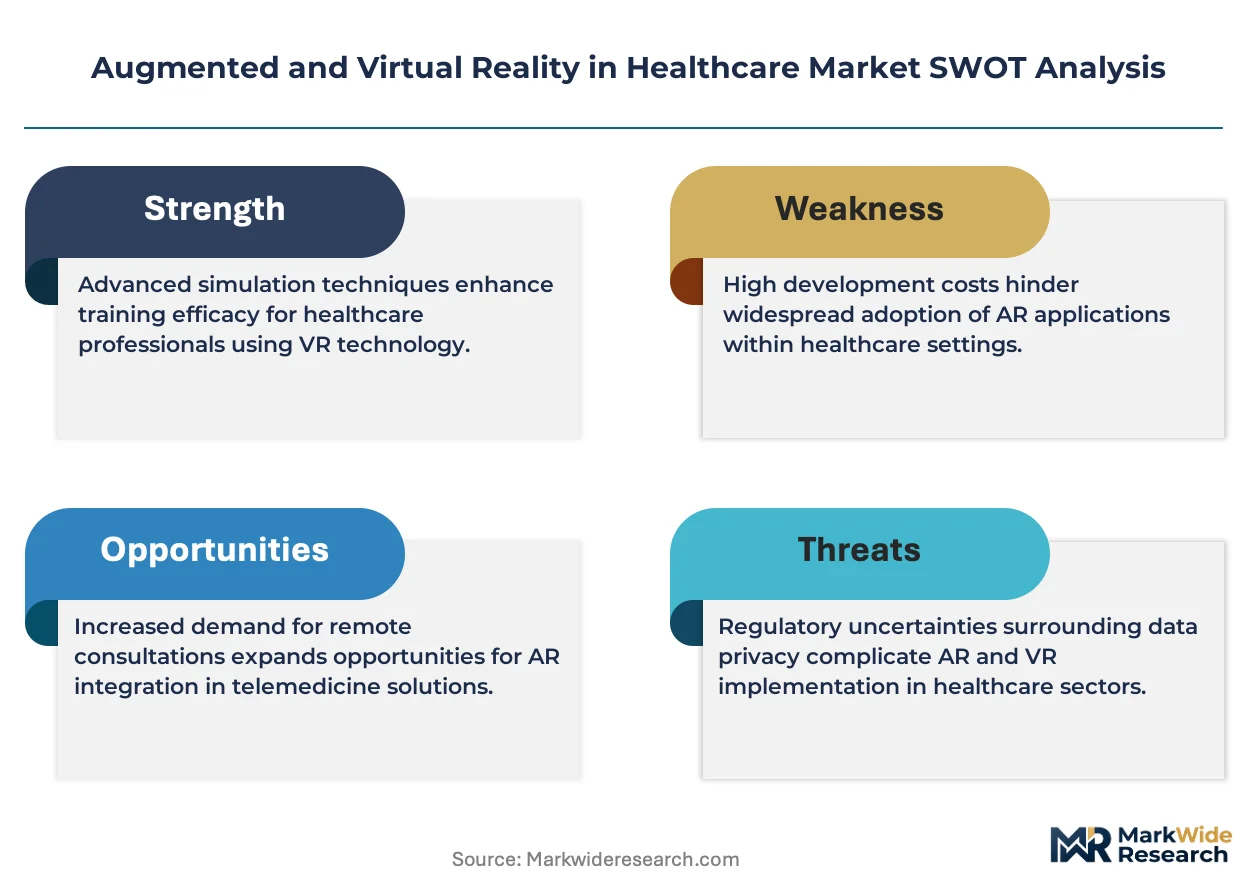
FDA digital health precertification, EU MDR technical documentation requirements, and HIPAA security rule provisions collectively shape product development roadmaps, clinical evidence standards, and data governance architectures for healthcare XR vendors. The FDA's de novo pathway for VR therapeutics has created a template that competitors must navigate for pain management and behavioral health indications. Stakeholders should monitor how CMS coverage determinations for digital therapeutics will either accelerate or stall hospital procurement cycles for immersive rehabilitation platforms.
Market Dynamics
FDA digital health precertification is compressing clinical validation timelines for VR therapeutic developers while simultaneously elevating evidence standards for pain management indications.
Growth Catalysts
- Surgical simulation mandates:Academic medical centers in the United States are embedding immersive training into residency curricula, creating institutional procurement pipelines for haptic-enabled platforms.
- EU MDR pathway clarity:Technical documentation requirements for Class IIa software are stabilizing, enabling CE marking predictability for European market entry.
- Sub-20ms motion-to-photon latency:Hardware advances in optical tracking and display refresh rates are eliminating simulator sickness barriers to extended clinical sessions.
Market Restraints
- Headset hardware concentration:Supply chains for high-resolution micro-OLED displays cluster in East Asian foundries, exposing procurement to regional disruption risk.
- Clinical evidence costs:Randomized controlled trials for FDA de novo clearance require multi-million-dollar investment thresholds that filter mid-stage developers.
- Substitution by conventional simulation:Mannequin-based training retains institutional preference in resource-constrained hospital systems.
Strategic Opportunities
- Rural healthcare networks:Tele-immersive rehabilitation platforms can penetrate underserved counties in the United States where specialist physical therapy access is limited.
- FDA breakthrough device designation:Expedited review pathways for pediatric anxiety and chronic pain applications create regulatory velocity advantages.
- Haptic-glove convergence:Integration of force-feedback peripherals with existing surgical robotics training infrastructure opens retrofit markets.
Industry Challenges
- Biomedical engineer scarcity:Cross-functional talent combining clinical workflow knowledge with Unity/Unreal engine proficiency commands premium compensation and extends hiring cycles.
- HIPAA-compliant cloud architecture:Real-time multiplayer simulation sessions require edge computing deployments that complicate data governance across state lines.
- Interoperability with EHR systems:Training outcome data integration with Epic and Cerner platforms demands custom API development for each health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented and Virtual Reality in Healthcare Market |
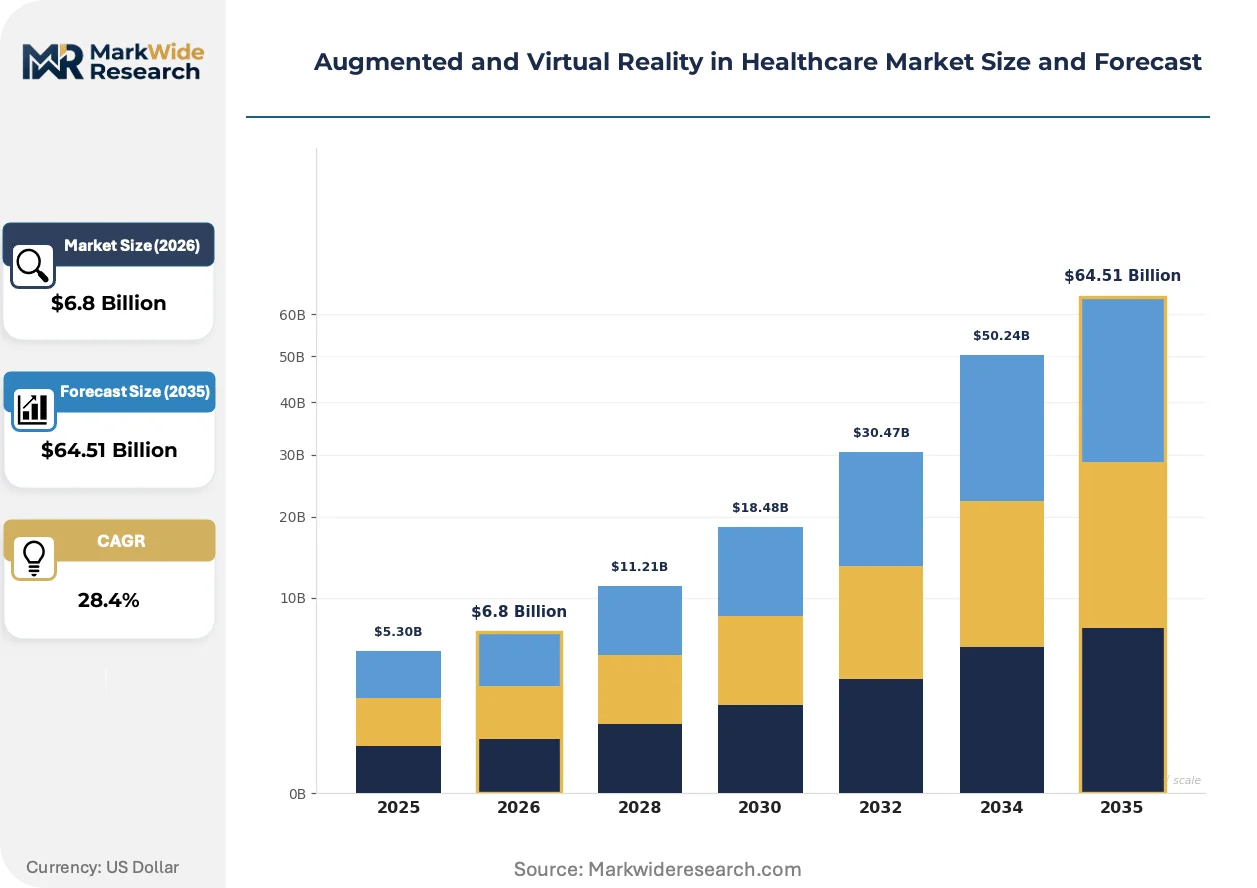
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $64.51 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Content Creation End User: Hospitals, Clinics, Medical Training Institutions, Rehabilitation Centers Application: Surgical Training, Pain Management, Physical Therapy, Patient Education Technology: Motion Tracking, 3D Visualization, Haptic Feedback, Simulation |
| Companies Covered | SimX, Virti, AppliedVR, Treeview Studio, ORamaVR, XRHealth, MyndVR, Saritasa, Osso VR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented and Virtual Reality in Healthcare Market Emerging Trajectories
Cloud-rendered spatial computing is dissolving the hardware-performance barrier that previously tethered immersive training to dedicated simulation centers.
Standalone VR headsets with onboard AI inference chips are decentralizing surgical training from fixed-site laboratories to operating room corridors and ambulatory surgery centers. Rural residency programs in Montana and Idaho are piloting these devices for remote proctoring of orthopedic procedures. The shift is compressing capital expenditure requirements from six-figure simulation suites to sub-five-figure per-learner hardware costs.
The FDA's evolving digital health software precertification framework is rebalancing compliance burdens toward continuous post-market surveillance rather than pre-market trial volume. Manufacturers must now maintain real-world performance dashboards as a condition of clearance maintenance. Pain management VR developers are responding by embedding automated outcome collection into their therapeutic protocols.
Hospital procurement committees are unbundling hardware purchases from content subscriptions, forcing platform vendors to compete on recurring library value rather than initial device margins. Academic medical centers in California and Texas are leading this shift toward software-as-a-service contracting. The model is displacing perpetual licensing arrangements that previously dominated enterprise sales cycles.
Augmented and Virtual Reality in Healthcare Market Segmentation
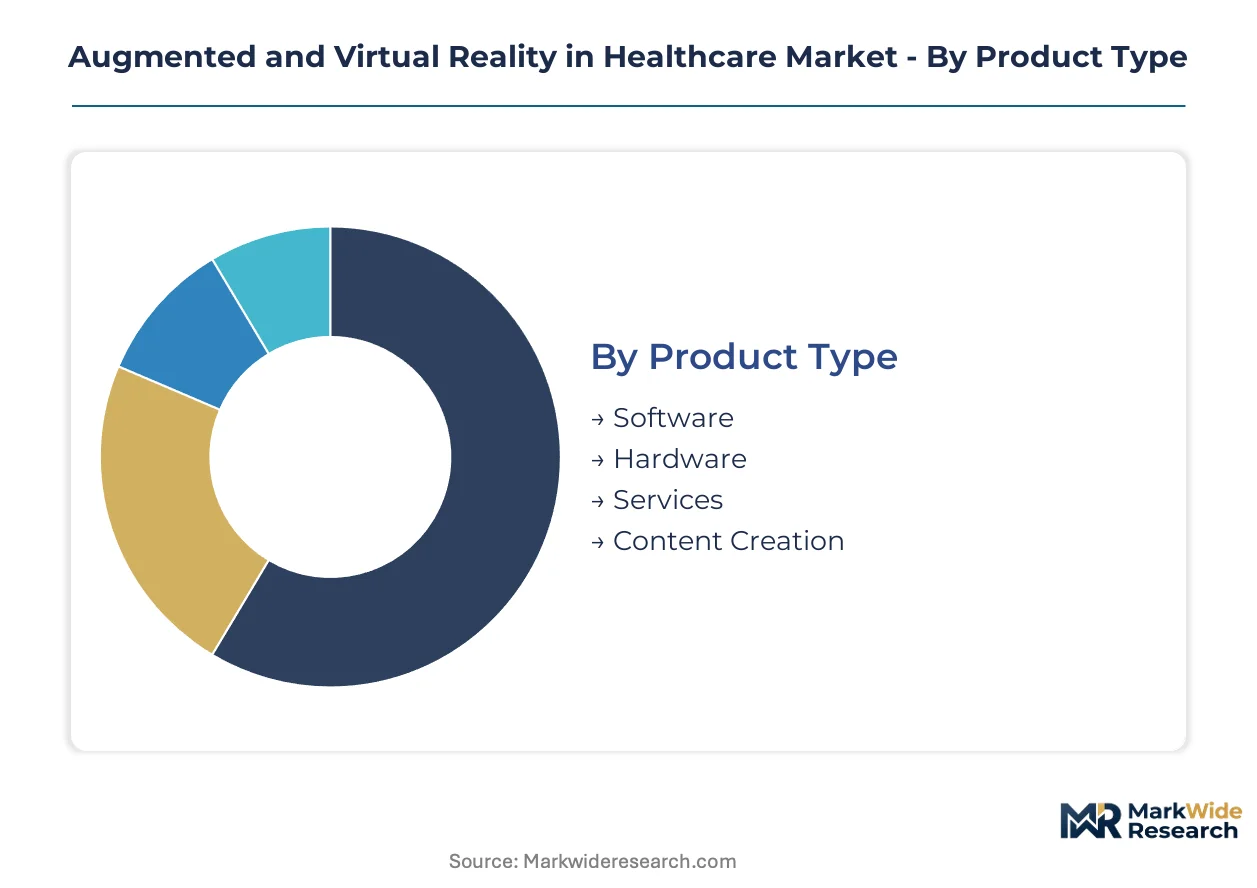
Healthcare XR procurement committees evaluate total cost of ownership across hardware refresh cycles, software licensing models, and integration services. Segmentation reveals where margin concentrates and which technology combinations command premium pricing in institutional budgets.
Product Type:
Capital allocation decisions separate upfront hardware investment from recurring software expenditure, with procurement committees increasingly favoring subscription models over perpetual licenses.
- Hardware:Head-mounted displays, haptic peripherals, and sensor arrays constitute the largest revenue pool due to 18-24 month enterprise refresh cycles. Academic medical centers in the United States prioritize sub-20ms motion-to-photon latency specifications for extended training sessions, driving demand for micro-OLED and pancake lens configurations.
- Software:Spatial computing platforms and simulation engines operate on SaaS licensing that decouples content access from device ownership. California and Texas health systems pioneered this shift, forcing vendors to compete on library depth rather than initial hardware margins.
- Services:Integration, training, and technical support bundles command premium pricing when attached to enterprise deployments. HIPAA-compliant cloud architecture requirements complicate margin capture in this category.
- Content Creation:Custom anatomical modeling and procedure-specific scenario development addresses niche training requirements. Demand concentrates in orthopedic and cardiovascular specializations where device manufacturer partnerships fund development.
Volume sits with Hardware; growth tilts toward Software.
End User:
Institutional scale and reimbursement pathways determine platform complexity and evidence requirements for each buyer category.
- Hospitals:Major health systems deploy dedicated XR laboratories with enterprise-grade haptic suites. FDA digital health precertification requirements elevate vendor selection criteria toward continuous post-market surveillance capabilities.
- Clinics:Ambulatory settings prioritize standalone headsets with onboard AI inference for point-of-care rehabilitation. Montana and Idaho rural residency programs pilot these devices for remote proctoring.
- Medical Training Institutions:Residency curricula mandates create institutional procurement pipelines for immersive simulation. Surgical training programs embed VR proficiency milestones into graduation requirements.
- Rehabilitation Centers:Chronic pain and physical therapy applications require CMS coverage determination alignment. CMS reimbursement policies for digital therapeutics directly influence procurement cycles in this segment.
Revenue concentrates in Hospitals; expansion accelerates fastest in Rehabilitation Centers.
Application:
Clinical evidence thresholds and regulatory pathways fragment development investment across use cases.
- Surgical Training:Orthopedic procedure simulation dominates R&D partnership activity with medical device manufacturers. Osso VR's platform architecture exemplifies the high-fidelity haptic integration required for arthroscopic and spinal techniques.
- Pain Management:FDA de novo clearance for prescription VR therapeutics creates defensible regulatory moats. AppliedVR's chronic pain indication established the evidentiary template competitors must replicate.
- Physical Therapy:Tele-immersive platforms penetrate underserved counties where specialist access is constrained. Edge computing deployments complicate HIPAA-compliant data governance across state lines.
- Patient Education:Pre-operative visualization and anatomical literacy tools reduce informed consent litigation exposure. Demand clusters in cardiovascular and oncological specializations with complex procedure explanations.
Investment flows heaviest into Surgical Training; regulatory velocity favors Pain Management.
Technology:
Performance specifications and interoperability requirements determine vendor differentiation and buyer switching costs.
- Motion Tracking:Optical and inertial tracking systems achieve the sub-20ms latency threshold essential for simulator sickness prevention. East Asian foundry concentration in high-resolution display supply chains introduces procurement risk.
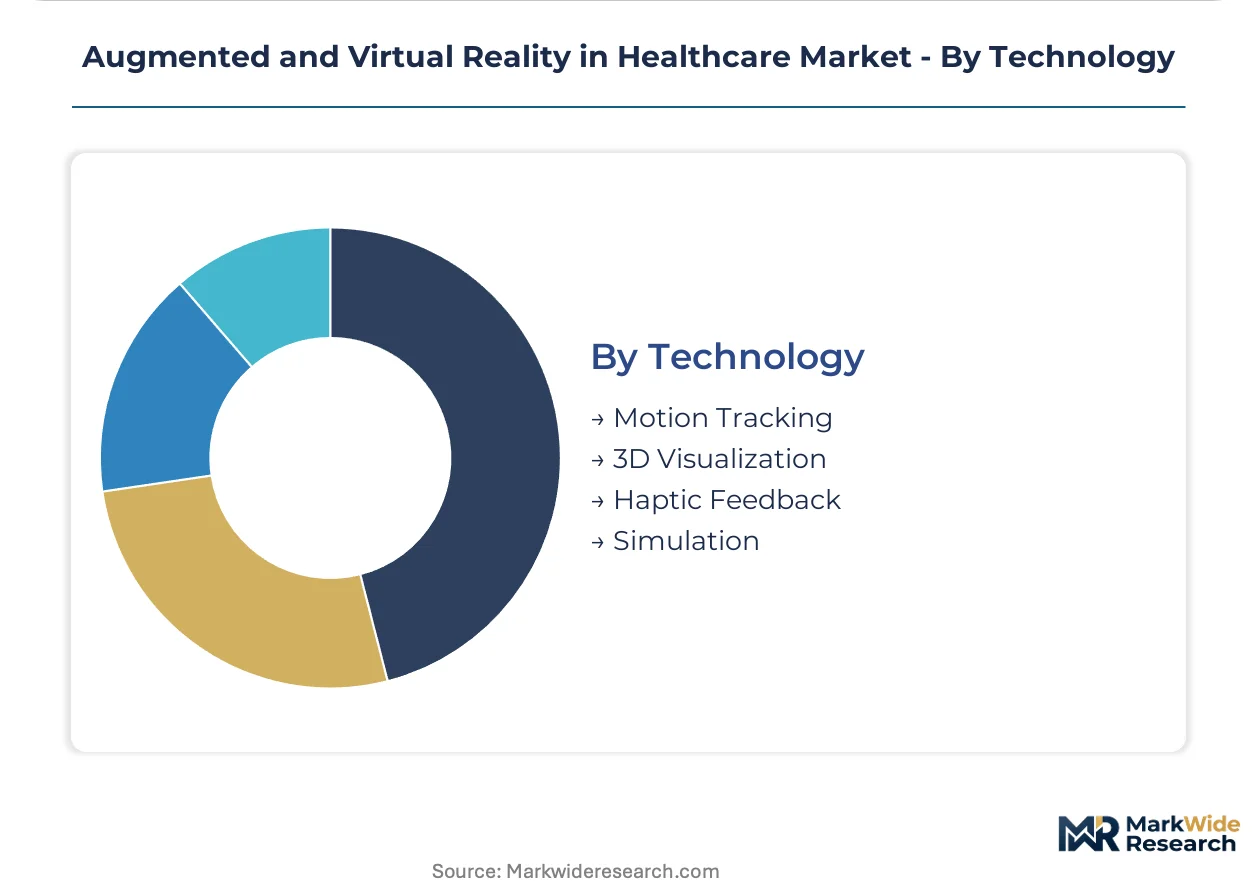
- 3D Visualization:Volumetric rendering and photorealistic anatomical modeling separate premium platforms from basic visualization tools. Cloud-rendered spatial computing dissolves hardware-performance barriers that previously tethered training to fixed simulation centers.
- Haptic Feedback:Force-feedback gloves and instrument replicas enable tactile fidelity in surgical simulation. Integration with existing robotic surgery training infrastructure opens retrofit markets for peripheral vendors.
- Simulation:Physics engines and physiological response modeling underpin scenario fidelity. SimX leverages military-derived architecture to anchor defense and civilian healthcare contracts simultaneously.
Adoption clusters around 3D Visualization; technical differentiation intensifies in Haptic Feedback.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in the United States and special economic corridors in Germany concentrate healthcare XR investment through targeted R&D tax credits and accelerated depreciation allowances for simulation infrastructure.
United States
VA networks and major hospital systems in California and Texas drive procurement of dedicated XR laboratories. FDA digital health precertification compresses validation timelines for therapeutic developers. The Greater Boston cluster anchors academic medical center adoption of haptic-enabled surgical training platforms.
Germany
EU MDR technical documentation requirements stabilize CE marking predictability for Class IIa software entrants. The Baden-Württemberg medical device corridor concentrates orthopedic simulation R&D partnerships. Munich-based health systems pilot cloud-rendered spatial computing for decentralized surgical training.
United Kingdom
NHS England's innovation accelerator programs channel procurement toward immersive rehabilitation platforms. MHRA alignment with FDA breakthrough device pathways expedites pediatric anxiety therapeutic reviews. The Oxford-Cambridge arc clusters tele-immersive physical therapy startups targeting rural specialist access gaps.
Japan
PMDA's structured consultation pathways for SaMD reduce regulatory uncertainty for pain management VR developers. METI funding for digital health infrastructure supports standalone headset deployment in rural prefectures. The Kansai region concentrates haptic peripheral manufacturing for surgical robotics integration.
South Korea
MFDS fast-track designations for AI-enabled medical devices attract XR therapeutic developers seeking regulatory velocity. The Seoul Capital Area anchors micro-OLED display supply chain relationships with East Asian foundries. Busan-Ulsan medical centers pilot edge computing architectures for real-time multiplayer simulation sessions.
Augmented and Virtual Reality in Healthcare Market Vendor Landscape
United States developers anchor the regulatory-cleared therapeutic tier; European specialists hold the CE-marked surgical simulation segment. Market structure tilts toward fragmented competition across application verticals, with concentration emerging in pain management where FDA de novo clearance creates narrow moats. Three archetypes dominate: military-derived simulation architects, device manufacturer-aligned orthopedic platforms, and prescription-grade chronic pain therapeutics. Competitive moves center on strategic partnerships with academic medical centers and portfolio diversification into adjacent rehabilitation applications.
Within the military-to-civilian simulation tier, SimX exemplifies cross-contract architecture leveraging defense infrastructure for healthcare deployment. AppliedVR and Osso VR occupy distinct regulatory niches—prescription VR therapeutics and orthopedic procedure simulation respectively—each representing divergent evidence-generation strategies for market access. These three companies illustrate how FDA pathway selection and device manufacturer partnership strategies segment competitive positioning across the healthcare XR landscape.
| Leading Market Players |
|---|
| SimX |
| Virti |
| AppliedVR |
| Treeview Studio |
| ORamaVR |
| XRHealth |
| MyndVR |
| Saritasa |
| Osso VR |
| Others |
Supply Flow & Price Mechanics
Micro-OLED display panel costs cascade through three pricing tiers as components move from East Asian foundries through enterprise headset assemblers to academic medical center procurement committees. The 18-24 month refresh cycles for sub-20ms motion-to-photon latency hardware create predictable upgrade revenue streams that subsidize software subscription penetration.
Pricing Analysis
Lead-time compression commands premium positioning for sub-20ms motion-to-photon latency headsets delivered within 90-day windows, while spot inventory of prior-generation LCD-based devices trades at substantial discounts. Pricing stratifies across FDA-cleared prescription VR, CE-marked surgical simulation platforms, and unregulated wellness applications based on evidentiary burden and reimbursement alignment. Cost compression in the wellness tier intensifies as consumer-grade hardware substitutes for clinical specifications. Hospital procurement committees exhibit lowest price sensitivity for haptic-enabled surgical training suites, whereas rural rehabilitation clinics prioritize sub-five-figure per-learner hardware costs.
Supply Chain Analysis
Domestic-content mandates in South Korea and Japan are reshaping sourcing patterns for AI inference chips and edge computing components deployed in standalone rehabilitation headsets. High-resolution micro-OLED displays and pancake lens assemblies concentrate in Taiwanese and South Korean foundries, while haptic peripheral manufacturing clusters in Japan's Kansai region and Germany's Baden-Württemberg corridor. Single-source vulnerability in East Asian display supply chains exposes procurement to regional disruption risk. Distribution runs through medical device GPOs and direct enterprise sales teams serving academic medical center procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's digital health precertification pathway functions as a cost-of-compliance moat, filtering mid-stage developers unable to sustain multi-million-dollar clinical evidence investments while rewarding cleared incumbents with accelerated review velocity.
For Market Incumbents: Deepen partnerships with orthopedic and cardiovascular device manufacturers to lock in procedure-specific simulation content exclusivity. Fortify post-market surveillance dashboards to maintain FDA clearance maintenance requirements. Threat substitution from cloud-rendered spatial computing platforms demands continuous R&D intensity in haptic fidelity. For New Entrants and Emerging Players: Begin with tele-immersive rehabilitation platforms targeting underserved rural counties in Montana and Idaho where specialist physical therapy access is constrained. The ambulatory clinic segment offers lowest regulatory barrier-to-entry through standalone AI-enabled headsets. Go-to-market execution should prioritize CMS coverage determination alignment before hospital system expansion. For Investors and Strategic Acquirers: FDA breakthrough device designation for pediatric anxiety applications is the leading indicator that regulatory velocity advantages are concentrating in behavioral health VR developers. Long-term viability favors platforms with demonstrated hospital procurement committee traction and recurring SaaS revenue architecture. Target acquisition profiles center on military-derived simulation architects with dual-use defense and civilian healthcare contract portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | Establishes prescription-grade regulatory moat for chronic pain therapeutics competing against AppliedVR's cleared indication. |
| CE Marking Pathway | EU MDR technical documentation for Class IIa software unlocks procurement pipelines across German and UK hospital systems. |
| Hospital System Partnership | California and Texas academic medical center embedded curricula create institutional procurement pipelines for residency programs. |
| Haptic Peripheral Integration | Force-feedback glove convergence with existing robotic surgery training infrastructure opens retrofit markets in orthopedic specializations. |
| Reimbursement Strategy | CMS coverage determination alignment for digital therapeutics directly influences rehabilitation center procurement cycles. |
Methodological Framework
Document review covered FDA 510(k) and de novo clearance databases, EU MDR technical documentation filings, and hospital procurement contract disclosures, complemented by interviews with biomedical engineers, VR platform developers, academic medical center simulation directors, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, medical device registration databases, and hyperscaler healthcare cloud capex disclosures. Bottom-up unit economics for hardware refresh cycles and subscription licensing were triangulated against top-down health system IT budget allocations.
Historical adoption curves for immersive surgical training were cross-referenced against panel input from procurement committees at major US hospital systems and VA networks. Segmentation modeling incorporated product type, end user institution scale, clinical application evidence threshold, and technology performance tier across the projection horizon. CAGRs were derived from installed base growth rates for haptic-enabled platforms and SaaS library expansion metrics. Forecast inputs included FDA precertification pathway evolution timelines and EU MDR Class IIa software review velocity assumptions.
Underlying measurement precision varies by segment; FDA-cleared prescription VR and CE-marked surgical simulation carry tighter precision than wellness applications lacking regulatory validation. Forecasts reflect assumptions about CMS coverage determination timing and EU MDR technical documentation standardization that could shift with regulatory policy changes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Preventive Healthcare Technologies and Services Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
North America Digital Health Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
North America Eclinical Solutions Market
Digital Health Solutions
Behavioral Mental Health Care Software Market
Digital Health Solutions
Virtual Reality (VR) in Healthcare Market
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Artificial Intelligence in Precision Medicine Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Eclinical Solutions Market