
 North America Digital Health Market | 2026-2036
North America Digital Health Market Size, Share, and Industry Trends Forecast 2026-2036
North America Digital Health Market Intelligence
Subscription-based software licensing and pay-per-use cloud infrastructure is tilting competitive dynamics toward asset-light entrants. Epic Systems Corp. leverages deep integration with hospital workflows to sustain its position in enterprise EHR systems. Teladoc anchors virtual-first care delivery through employer and payer channel control across the United States.
Digital health encompasses software, connected hardware, and data infrastructure designed to deliver, manage, or improve medical care through electronic exchange of health information, typically operating on HL7 FHIR interoperability standards and HIPAA-compliant cloud architectures. The technology stack spans AI Solutions for diagnostic triage, Cloud Computing for scalable data storage, and IoT for continuous biometric streams, with AI Solutions capturing concentrated R&D investment while IoT hardware faces margin compression from component commoditization. Telemedicine platforms and Remote Monitoring systems serve distinct buyer economics: the former monetizes per-visit fees from Healthcare Providers, the latter generates recurring revenue through chronic disease management contracts with Payers.
FDA premarket clearance pathways for Software as a Medical Device, HIPAA security rule enforcement by the Office for Civil Rights, and CMS reimbursement codes for remote therapeutic monitoring collectively determine product viability and go-to-market speed for platform developers. State-level telehealth parity laws in Texas and New York create fragmented access conditions that vendors must navigate for Medicaid eligibility. Stakeholders should track FDA draft guidance on AI-enabled clinical decision support to anticipate which algorithms will require formal submission versus enforcement discretion.
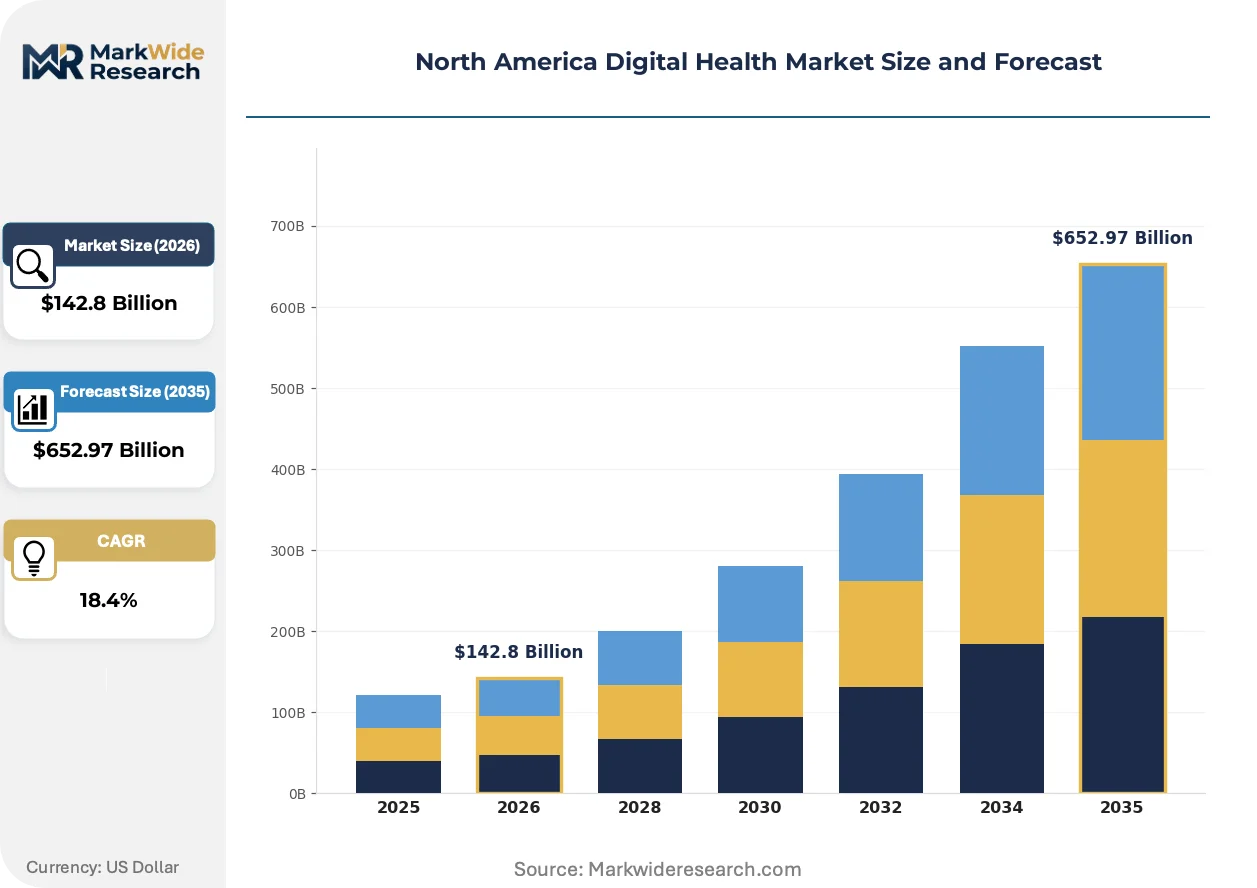
Market Dynamics
CMS value-based reimbursement penalties and readmission reduction mandates are forcing hospital systems to reallocate capital from physical bed expansion toward virtual care infrastructure and remote patient monitoring platforms.
Growth Catalysts
- CMS Remote Therapeutic Monitoring codes:New reimbursement pathways for chronic disease management create direct revenue streams for connected device deployments in cardiology and diabetes care.
- HL7 FHIR interoperability mandates:Data exchange standardization reduces integration friction between wearable biometric streams and enterprise EHR systems across hospital networks.
- California health-tech corridor:Concentrated venture capital and FDA-cleared startup density accelerates pilot-to-scale timelines for AI diagnostic tools.
Market Restraints
- Semiconductor component volatility:IoT sensor module costs fluctuate with foundry capacity constraints in Taiwan and South Korea, compressing hardware margins.
- State-level telehealth parity fragmentation:Inconsistent Medicaid reimbursement rules between Texas and New York create compliance overhead for multi-state platform operators.
- HIPAA security rule enforcement:Office for Civil Rights audit expansion raises liability insurance premiums and legal review costs for cloud-hosted patient data architectures.
Strategic Opportunities
- Mexico nearshoring expansion:Underpenetrated hospital digitization and payer consolidation create first-mover advantage for Spanish-language telemedicine platforms.
- FDA AI-enabled clinical decision support guidance:Draft enforcement discretion criteria will clarify which algorithms require premarket submission versus streamlined clearance.
- AI-IoT convergence in continuous glucose monitoring:Predictive glycemic algorithms paired with wearable sensors open subscription revenue models beyond device sales.
Industry Challenges
- Interoperability engineer scarcity:Shortage of HL7 FHIR implementation specialists delays EHR integration timelines and inflates contractor rates.
- Legacy mainframe EHR migration:Hospital IT departments face multi-year capital cycles to replace on-premise Cerner and Epic instances with cloud-native architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Digital Health Market |
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $652.97 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telemedicine, Wearable Devices, Health Apps, Remote Monitoring Technology: AI Solutions, Blockchain, Cloud Computing, IoT End User: Healthcare Providers, Patients, Payers, Employers Application: Chronic Disease Management, Wellness, Fitness Tracking, Medication Management |
| Companies Covered | Apple Inc., Epic Systems Corp., Cerner Corp., Allscripts, McKesson Corp., Teladoc, Amwell, GE HealthCare Technologies Inc., Medtronic Plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Digital Health Market Strategic Shifts & Innovations
Software architectures are pivoting from monolithic enterprise licenses toward modular API-first platforms that embed clinical decision support directly into physician workflow tools.
Edge computing for real-time biometric processing is hybridizing with cloud-based AI inference to reduce latency in cardiac arrhythmia detection and fall-risk alerting. Hospital IT departments in Massachusetts and Minnesota are piloting these split architectures to maintain sub-100-millisecond response times for emergency notifications. The hybrid model compresses infrastructure costs by filtering raw sensor data locally before transmitting anomaly flags to centralized analytics engines.
FDA draft guidance on predetermined change control plans for machine learning-based devices is altering submission strategies for algorithm developers. Manufacturers must now lock intended modification protocols before clearance, shifting R&D roadmaps toward modular, swappable model components rather than continuous learning architectures. Cardiology AI vendors in California and Massachusetts are restructuring quality management systems to accommodate this pre-specified evolution framework.
Employer-sponsored health plans are unbundling telemedicine from comprehensive insurance packages and negotiating direct-to-platform contracts. This channel disintermediation strips traditional payers of distribution control and forces virtual care providers to build sales teams targeting Fortune 500 benefits departments. The shift is most pronounced in Texas and Illinois manufacturing corridors where self-insured employers dominate coverage decisions.
North America Digital Health Market Segmentation
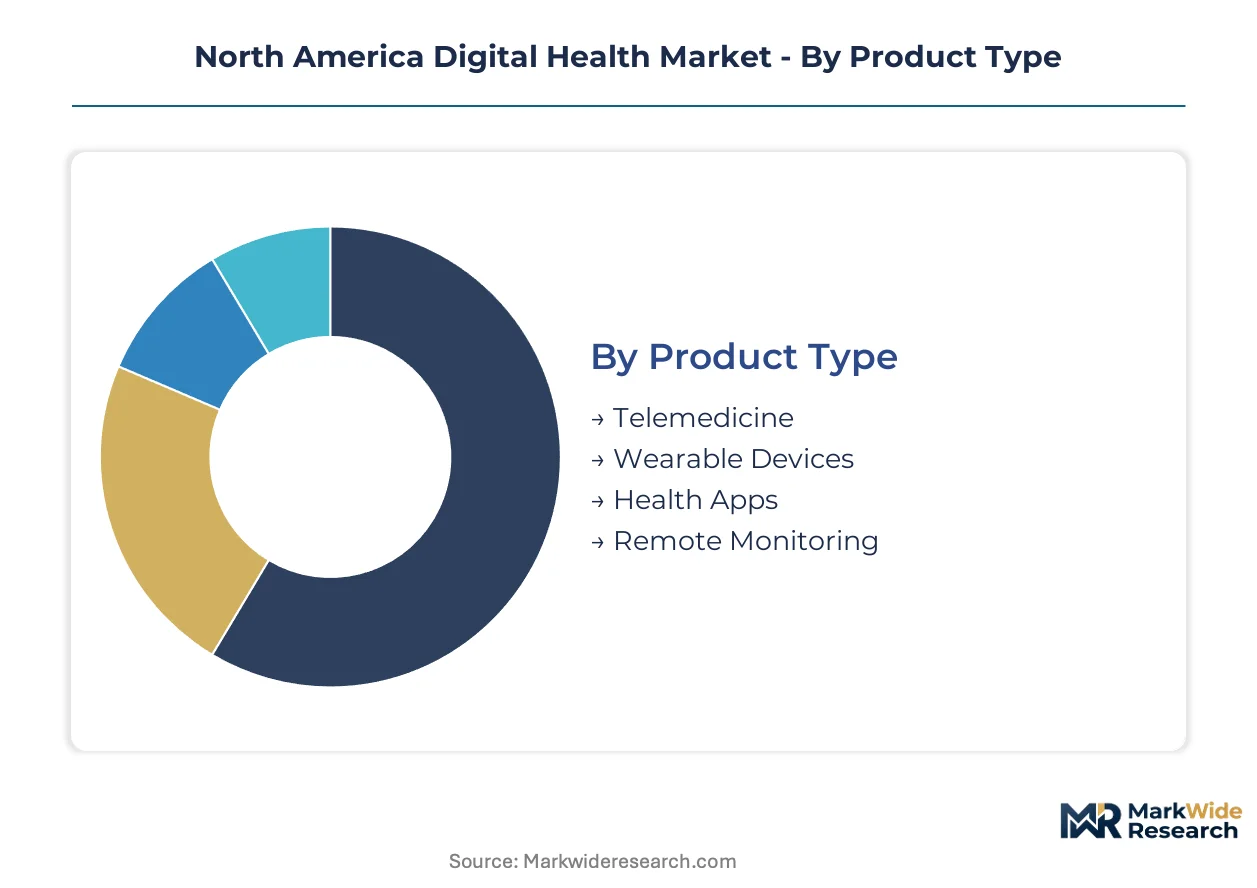
Segmentation in digital health reveals divergent monetization rhythms across hardware, software, and service layers. Product refresh cycles for connected devices lag years behind the quarterly iteration pace of cloud-hosted applications. Understanding these velocity mismatches shapes capital allocation and partnership timing for platform developers.
Product Type:
Cycle times stretch from months for software patches to half-decades for FDA-cleared hardware, creating portfolio balancing challenges for diversified vendors.
- Telemedicine:Cloud-native platforms deploy feature updates continuously through CI/CD pipelines. Hospital systems in California's health-tech corridor and Massachusetts' hospital network cluster drive enterprise contract renewals based on HL7 FHIR integration depth.
- Wearable Devices:Biometric sensors with FDA 510(k) clearance face eighteen-month hardware refresh constraints. Demand concentrates in cardiology and diabetes management where CMS Remote Therapeutic Monitoring codes reimburse continuous data streams.
- Health Apps:Consumer-facing wellness applications iterate monthly through app store releases. Direct-to-patient subscriptions in Texas and New York generate recurring revenue independent of payer intermediation.
- Remote Monitoring:Hospital-at-home programs require paired device-platform submissions to FDA. Pilots in Minnesota and Illinois manufacturing corridors test bundled per-member-per-month pricing.
Telemedicine anchors the volume base while Remote Monitoring gains share at the steepest rate.
Technology:
Investment intensity clusters around inference-heavy layers while infrastructure components commoditize.
- AI Solutions:Clinical decision support algorithms train on de-identified EHR datasets from Epic Systems deployments. FDA draft guidance on predetermined change control plans forces modular architecture designs.
- Blockchain:Distributed ledger implementations secure consent management for multi-site trials. Adoption lags in provider workflows due to latency constraints and integration costs.
- Cloud Computing:HIPAA-compliant architectures from hyperscalers enable elastic scaling for telemedicine traffic spikes. AWS, Azure, and Google Cloud compete on BAA negotiation speed and OCR audit support.
- IoT:Edge computing modules process arrhythmia detection locally before cloud transmission. Foundry capacity constraints in Taiwan and South Korea compress sensor margins.
Cloud Computing underpins infrastructure spending while AI Solutions capture the most concentrated R&D allocation.
End User:
Procurement authority shapes contract structure more than clinical utility in purchase decisions.
- Healthcare Providers:Hospital CIOs prioritize EHR-integrated workflows over standalone functionality. Epic Systems and Cerner migration timelines determine platform deployment schedules.
- Patients:Direct-pay wellness subscriptions bypass prior authorization friction. California and New York consumers show highest willingness-to-pay for mental health coaching apps.
- Payers:Medicare Advantage plans in Texas and Illinois negotiate outcomes-based contracts for chronic disease management. CMS value-based penalties drive remote monitoring adoption.
- Employers:Self-insured manufacturers in the Midwest unbundle telemedicine from carrier packages. Fortune 500 benefits departments now contract directly with virtual care platforms.
Payers anchor the revenue base while Employers are expanding most quickly as a procurement channel.
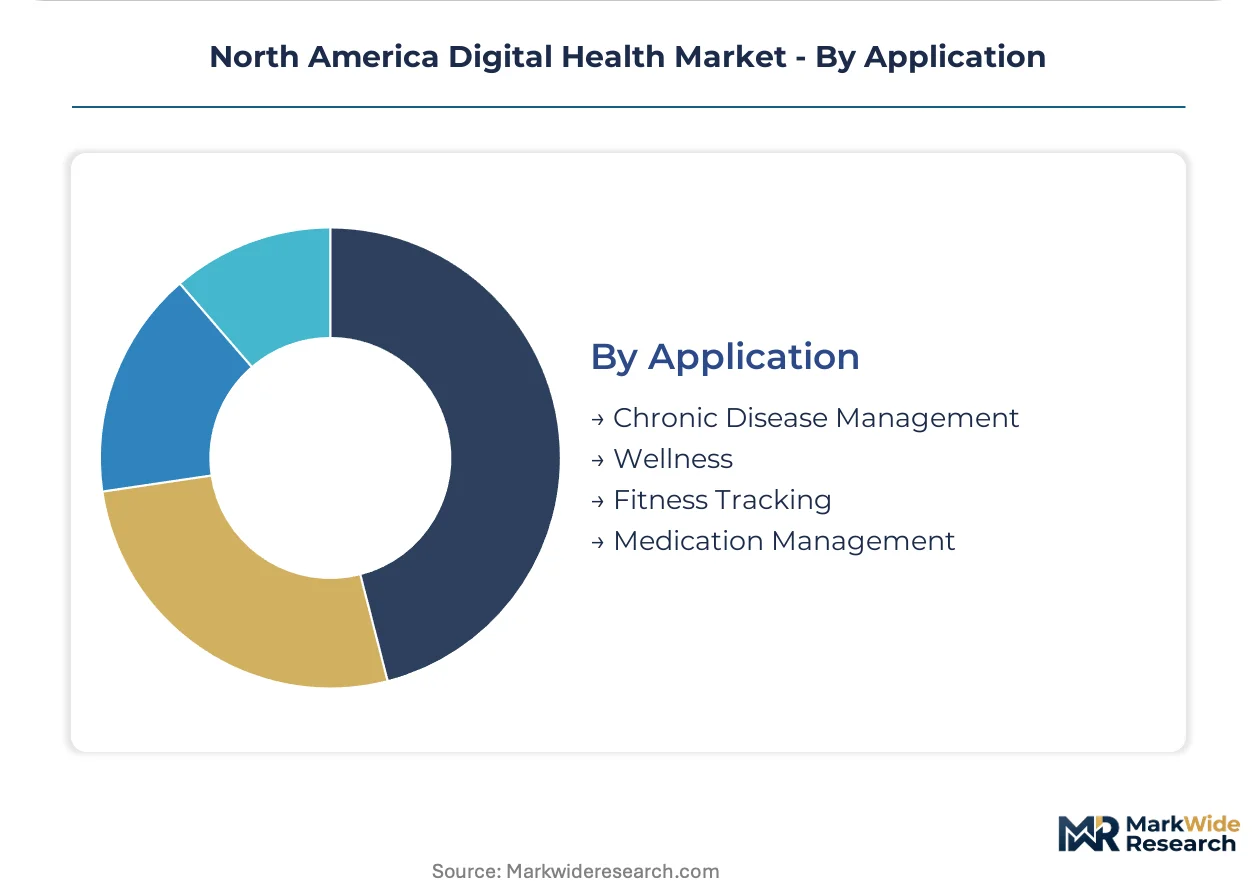
Application:
Clinical validation requirements separate regulated disease management from discretionary wellness categories.
- Chronic Disease Management:Diabetes and heart failure programs require FDA-cleared devices paired with clinical workflow integration. Massachusetts General and Mayo Clinic pilots establish evidence standards.
- Wellness:Stress reduction and sleep optimization apps operate outside FDA enforcement discretion. Employer subsidies in Texas manufacturing corridors subsidize subscription uptake.
- Fitness Tracking:Consumer wearables face reimbursement exclusion but drive brand awareness. Apple Watch and Fitbit data increasingly feeds into payer risk stratification models.
- Medication Management:Pill sensors and adherence algorithms target polypharmacy in Medicare populations. Pharmacy benefit managers in Illinois test integration with mail-order fulfillment.
Chronic Disease Management anchors the clinical revenue base while Medication Management is climbing the fastest toward reimbursement parity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America runs a digital health trade surplus driven by software and platform exports to Europe and Asia-Pacific, while importing specialized semiconductor components and foundry services from Taiwan and South Korea for wearable device manufacturing.
United States
Hospital systems in California's health-tech corridor and Massachusetts' hospital network cluster drive enterprise EHR contract renewals based on HL7 FHIR integration depth. CMS value-based reimbursement penalties and Remote Therapeutic Monitoring codes reshape capital allocation toward virtual care infrastructure. FDA premarket clearance pathways for Software as a Medical Device determine product viability timelines for platform developers in the San Francisco Bay Area and Greater Boston.
Canada
Provincial health authorities in Ontario and Quebec accelerate hospital digitization timelines to reduce surgical backlogs and emergency department congestion. Health Canada regulates medical device software under the Medical Devices Regulations while provincial privacy commissioners enforce PIPEDA-compliant data architectures. Toronto and Vancouver health-tech clusters concentrate AI diagnostic startups targeting FDA clearance for simultaneous US market entry.
Mexico
Underpenetrated hospital digitization and payer consolidation in Mexico City and Monterrey create first-mover advantage for Spanish-language telemedicine platforms. COFEPRIS medical device registration pathways align with FDA convergence agreements to streamline cross-border product approvals. Guadalajara's software development corridor supplies nearshore engineering talent for US-based health platform operators seeking cost-efficient technical operations.
Texas
Self-insured employers in Houston and Dallas-Fort Worth manufacturing corridors unbundle telemedicine from comprehensive insurance packages and negotiate direct-to-platform contracts. State-level telehealth parity laws create fragmented Medicaid reimbursement conditions that vendors must navigate for eligibility. Austin's health-tech cluster concentrates venture-backed startups targeting employer-sponsored direct contracting channels.
New York
Medicaid managed care plans in New York City and Buffalo negotiate outcomes-based contracts for chronic disease management platforms. State telehealth parity mandates exceed federal minimums, expanding reimbursement eligibility for remote patient monitoring services. The Hudson Valley biotech corridor integrates digital health tools into clinical trial operations for pharmaceutical sponsors.
North America Digital Health Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in hardware and connectivity layers. The vendor base stratifies between enterprise EHR incumbents with deep hospital workflow integration and asset-light virtual care entrants monetizing through subscription-based software licensing. Two dominant strategic archetypes emerge: workflow-embedded platform providers and channel-controlling virtual-first care delivery networks. Competitive moves concentrate on strategic partnerships for data interoperability and portfolio diversification into adjacent chronic disease management segments.
Within the enterprise platform tier, Epic Systems Corp. and Cerner Corp. exemplify the EHR-integrated archetype, while Teladoc occupies a position representing the virtual-first care delivery network model. Apple Inc. anchors the consumer-facing wearable and health app ecosystem, bridging patient-generated data streams with clinical workflows. These three entities collectively represent the structural poles around which competitive positioning organizes.
| Leading Market Players |
|---|
| Apple Inc. |
| Epic Systems Corp. |
| Cerner Corp. |
| Allscripts |
| McKesson Corp. |
| Teladoc |
| Amwell |
| GE HealthCare Technologies Inc. |
| Medtronic Plc |
| Others |
Cost & Logistics Intelligence
Foundry overcapacity in Taiwan's semiconductor manufacturing base is compressing sensor module costs and forcing IoT hardware vendors toward volume-commitment contracts that lock in pricing floors while cloud infrastructure hyperscalers extract premium margins from HIPAA-compliant compute services.
Pricing Analysis
Healthcare provider CIOs anchor three-tier pricing structure across premium, standard, and economy levels for EHR-integrated platforms. FDA 510(k) clearance tier and HL7 FHIR certification depth drive price differentiation between enterprise and mid-market deployments. Pricing pressure stems from employer direct-contracting channels that bypass traditional payer intermediation and squeeze per-visit telemedicine fees. Self-insured manufacturers in Texas and Illinois show highest price sensitivity while academic medical centers in Massachusetts accept premium pricing for workflow depth.
Supply Chain Analysis
Foxconn, Jabil, and Flex hold concentrated electronics manufacturing capacity across Mexico, Malaysia, and China's Pearl River Delta for wearable device assembly. Biometric sensor modules draw from TSMC and Samsung foundry output in Taiwan and South Korea. Single-source vulnerability in FDA-cleared glucose sensor substrates creates supply continuity risk for continuous monitoring platforms. Distribution runs through GPO contracts and direct hospital procurement committees rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
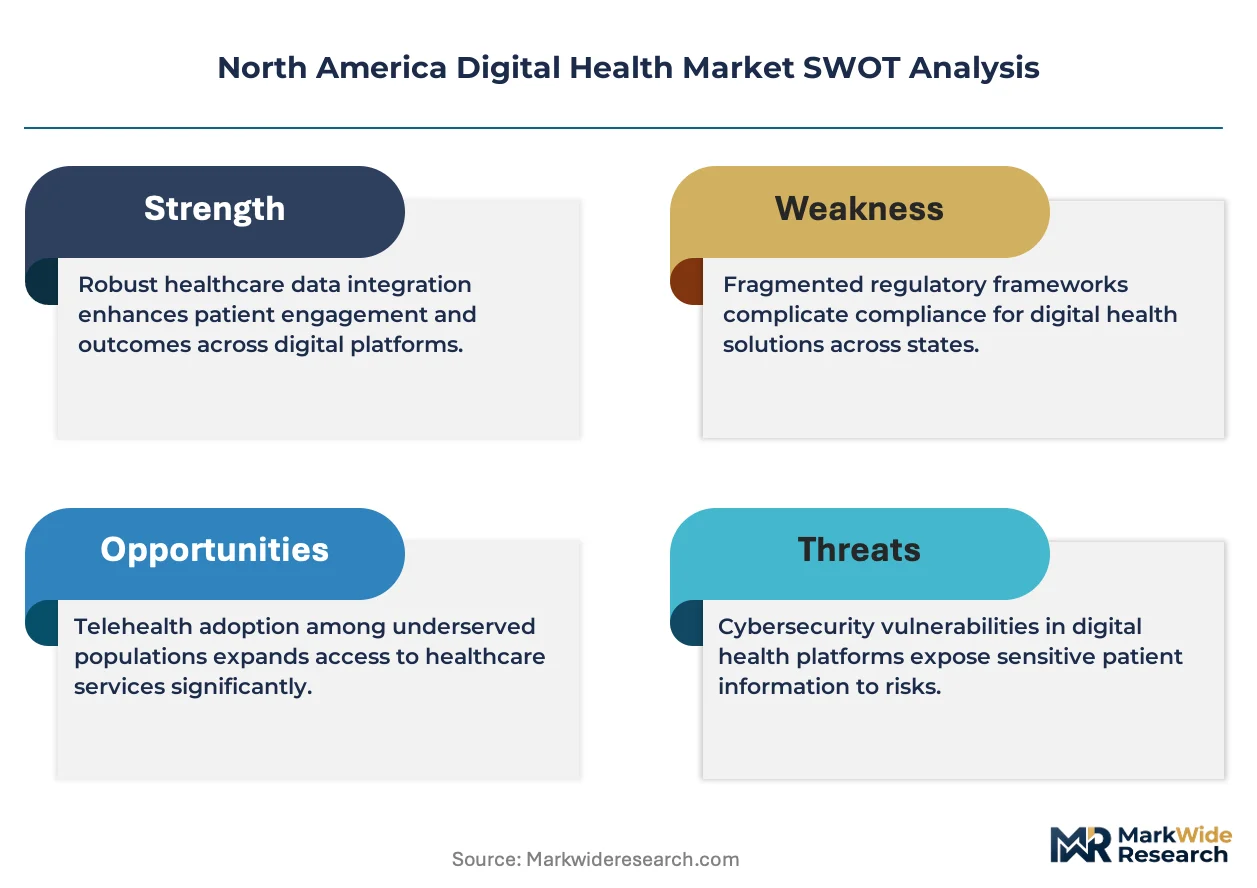
The North America digital health market is exiting a capital-contraction cycle as CMS reimbursement code expansion and FDA AI guidance clarity restore predictable monetization timelines for platform developers.
For Market Incumbents: Build data moats through exclusive EHR integration partnerships with Epic Systems and Cerner deployments. Consolidate position by acquiring HL7 FHIR implementation specialists to address engineer scarcity and accelerate hospital onboarding timelines. Channel control through employer direct-contracting relationships represents the critical defensive lever against virtual-first entrants.
For New Entrants and Emerging Players: Spanish-language telemedicine platforms for Mexico City's underpenetrated hospital networks represent the most penetrable entry point in the analysis window. AI-enabled clinical decision support tools targeting cardiology and diabetes management in Texas and New York Medicaid plans offer second-mover advantage through outcomes-based contracting. Go-to-market execution should prioritize pilot-to-scale velocity with single health system deep integration over multi-state breadth.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native telemedicine platforms as AWS, Azure, and Google Cloud compete on BAA negotiation speed. Long-term viability over the next decade hinges on reimbursement code capture and FDA clearance durability rather than user growth metrics. Acquisition targets should demonstrate locked CMS Remote Therapeutic Monitoring contracts with Medicare Advantage plans. The signal to watch is Office for Civil Rights audit expansion that raises compliance costs for subscale cloud architectures and accelerates consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA AI-Enabled Clinical Decision Support Submission | Predetermined change control plans lock in modular algorithm architectures before clearance. |
| Hospital System EHR Integration Partnership | Epic Systems and Cerner workflow embedding creates switching costs for enterprise platforms. |
| CMS Remote Therapeutic Monitoring Reimbursement Strategy | Cardiology and diabetes code capture enables recurring revenue beyond device sales. |
| Employer Direct-Contracting Channel Development | Fortune 500 benefits departments in Texas and Illinois bypass traditional payer control. |
| HL7 FHIR Interoperability Certification Investment | Standardized data exchange reduces hospital IT integration friction and accelerates deployment. |
Research Approach
A standing panel of hospital CIOs, health system procurement committees, payer contracts managers, and FDA regulatory affairs leads provided ongoing calibration across the study. Primary interviews with biomedical engineers and GPO contracts managers combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and hyperscaler HIPAA business associate agreement disclosures. Bottom-up platform deployment counts and top-down healthcare IT spending estimates were triangulated to anchor market sizing.
Scenario bracketing around CMS reimbursement code expansion timelines and FDA draft guidance finalization shaped projection boundaries across the analysis window. Segmentation modeling captured product type, technology layer, end-user procurement authority, and clinical application with geographic resolution to state-level regulatory clusters. CAGRs were derived from fitted adoption curves calibrated to hospital EHR migration timelines and employer telemedicine contract renewal cycles. Forecast inputs included foundry capacity utilization signals from Taiwan and South Korea and state-level telehealth parity law adoption rates.
Practitioners should monitor FDA enforcement discretion criteria revision and CMS value-based penalty threshold adjustments for early signals of platform monetization inflection. Forecasts reflect assumptions regarding interoperability mandate implementation pace and semiconductor supply normalization. Quarterly review of hospital capital expenditure disclosures and employer benefits survey data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Mhealth Solutions Market
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Asia-Pacific Digital Therapeutic (Dtx) Market
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Digital Biomarkers Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Global Patient Portal Market
Digital Health Solutions
Pregnancy Tracking and Postpartum Care Apps Market
Digital Health Solutions
North America Virtual Reality (VR) Health Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Amblyopia Treatment Softwares Market