
 Cognitive Neuroscience Market | 2026-2036
Cognitive Neuroscience Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Neuroscience Market Outlook
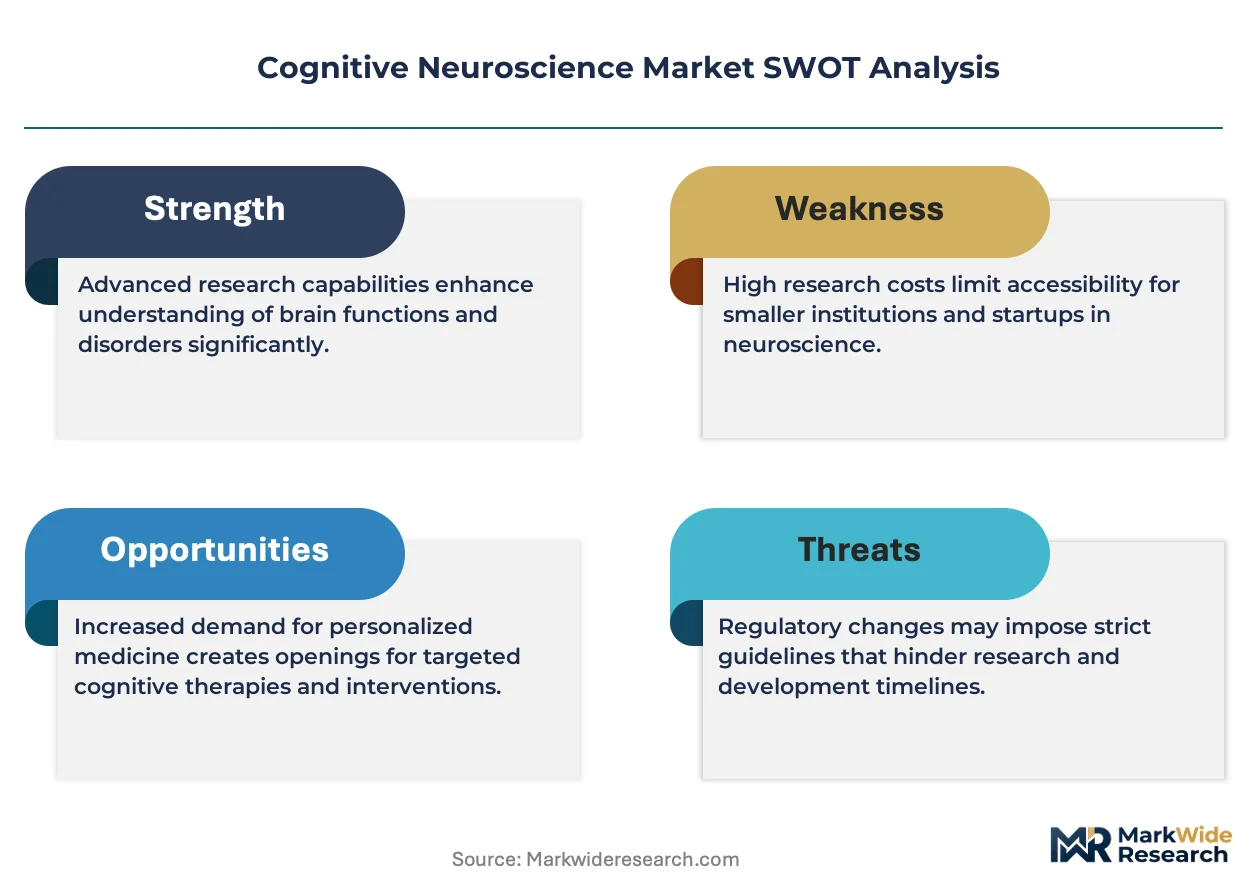
Academic labs is bifurcating from hospitals as the dominant buyer archetype for high-resolution neuroimaging systems. Siemens Healthineers anchors European supply chains through vertically integrated magnet manufacturing for MRI platforms. Brain Products GmbH specializes in dense-array EEG amplifiers for research-grade cognitive paradigms. Emotiv Inc. competes at the frontier of portable brain-computer interfaces for real-world neural monitoring.
Cognitive neuroscience encompasses the interdisciplinary study of neural substrates underlying mental processes, employing spatial resolutions from millimeter-scale fMRI voxels to microvolt-level EEG potentials for mapping perception, memory, and decision circuitry. Its primary commercial purpose centers on validating therapeutic mechanisms for psychiatric and neurological disorders while optimizing human performance systems. Diagnostic instruments command the deepest margin pools due to capital intensity and regulatory barriers, while software solutions for neuroimaging analytics represent the fastest-expanding segment as laboratories prioritize computational biomarker extraction. Wearable devices remain nascent but attract venture funding for ambulatory cognitive monitoring applications.
The FDA breakthrough device program accelerates market access for novel neural diagnostics, while HIPAA frameworks constrain how patient-derived neuroimaging data migrates across research networks. ISO 13485 certification requirements shape manufacturing standards for EEG and TMS hardware destined for clinical environments. Stakeholders must monitor how the EU AI Act classifies predictive neuroimaging algorithms, as this determination will reshape commercialization pathways for AI-augmented cognitive assessment tools.
Market Dynamics
Pharmaceutical companies now dominate capital deployment for neuroimaging infrastructure, redirecting procurement patterns from academic research centers toward CNS drug development pipelines that demand higher throughput and regulatory-grade data outputs.
Growth Catalysts
- FDA Breakthrough Device Pathway:The accelerated review timeline compresses market entry for novel brain-computer interface developers, incentivizing venture capital flows into neural diagnostic startups.
- NIH Funding Priorities:Federal research allocations in the United States specifically target translational neuroscience infrastructure, expanding shared imaging facilities across major medical centers.
- CNS Drug Pipeline Expansion:Pharmaceutical sponsors require mechanistic biomarker validation for psychiatric and neurological therapeutics, driving sustained demand for fMRI and EEG platforms.
Market Restraints
- Superconducting Magnet Supply Concentration:Cryogenic cooling systems and niobium-titanium wire production concentrate among European and Japanese specialty suppliers, creating input vulnerability for MRI manufacturers.
- HIPAA Data Migration Friction:Patient-derived neuroimaging datasets face strict cross-institutional transfer protocols, fragmenting multi-site research networks and slowing collaborative biomarker discovery.
- EEG Spatial Resolution Ceiling:Scalp-recorded potentials cannot resolve deep subcortical structures, limiting cognitive neuroscience applications for limbic circuit disorders.
Strategic Opportunities
- Ambulatory Cognitive Monitoring:Wearable EEG and near-infrared spectroscopy devices open real-world neural data collection outside laboratory environments, targeting aging populations and occupational safety verticals.
- EU AI Act Classification Window:Predictive neuroimaging algorithms face pending regulatory categorization in Europe, creating first-mover advantage for compliant biomarker extraction software.
- India Translational Infrastructure:Low-cost clinical trial execution and expanding medical device manufacturing capacity position the country for contract neuroimaging services.
Industry Challenges
- Computational Neuroscience Talent Scarcity:Laboratory demand for machine learning engineers with domain expertise in neural signal processing exceeds supply, inflating compensation and extending hiring cycles.
- ISO 13485 Certification Burden:Clinical-grade EEG and TMS hardware manufacturers face 18-24 month quality management system audits, delaying revenue recognition for research-to-clinical product transitions.
- Legacy System Integration Complexity:Academic hospitals operate heterogeneous neuroimaging equipment fleets spanning multiple vendor generations, complicating unified data pipeline architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Neuroscience Market |
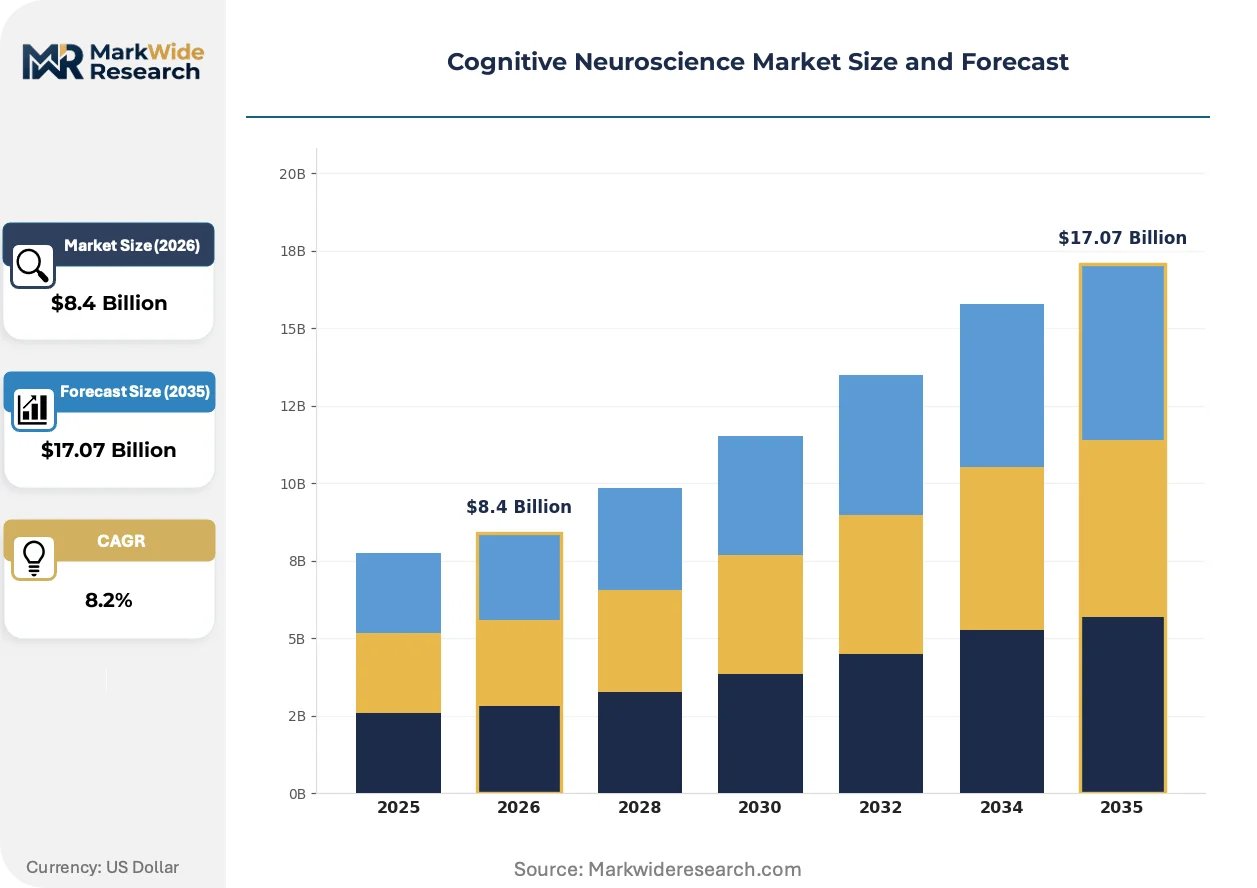
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Clinical Research, Drug Development, Cognitive Assessment, Neuroimaging End User: Hospitals, Research Institutions, Academic Labs, Pharmaceutical Companies Technology: Magnetic Resonance Imaging, Electroencephalography, Transcranial Magnetic Stimulation, Functional MRI Product Type: Software Solutions, Wearable Devices, Diagnostic Instruments, Laboratory Equipment |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Philips Healthcare, Medtronic PLC, Brain Products GmbH, ANT Neuro, Emotiv Inc., Natus Medical Incorporated, Compumedics Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Neuroscience Market Strategic Shifts
Dry-electrode sensor arrays and edge-computing architectures are compressing the form factor and cost structure of neural recording equipment, opening deployment scenarios beyond traditional laboratory settings.
Portable EEG hardware is miniaturizing through polymer-based dry electrodes that eliminate conductive gel requirements. Pharmaceutical field trial units and occupational safety departments are adopting these systems for rapid deployment. The technology is miniaturizing the addressable market from specialized research facilities toward point-of-care and workplace screening applications.
EU AI Act algorithm classification rules will determine whether predictive neuroimaging tools face high-risk medical device obligations or lighter conformity assessment pathways. Developers of AI-augmented cognitive assessment software face urgent compliance architecture decisions. European neurotechnology startups are restructuring quality management systems preemptively to secure notified body engagement.
Academic medical centers now unbundle neuroimaging analytics from hardware procurement, licensing cloud-based biomarker extraction platforms on subscription terms. Traditional capital equipment vendors face margin compression as recurring software revenue displaces upfront system sales. This pattern concentrates in United States research hospitals with established institutional review board frameworks for cloud-hosted patient data.
Cognitive Neuroscience Market Segmentation
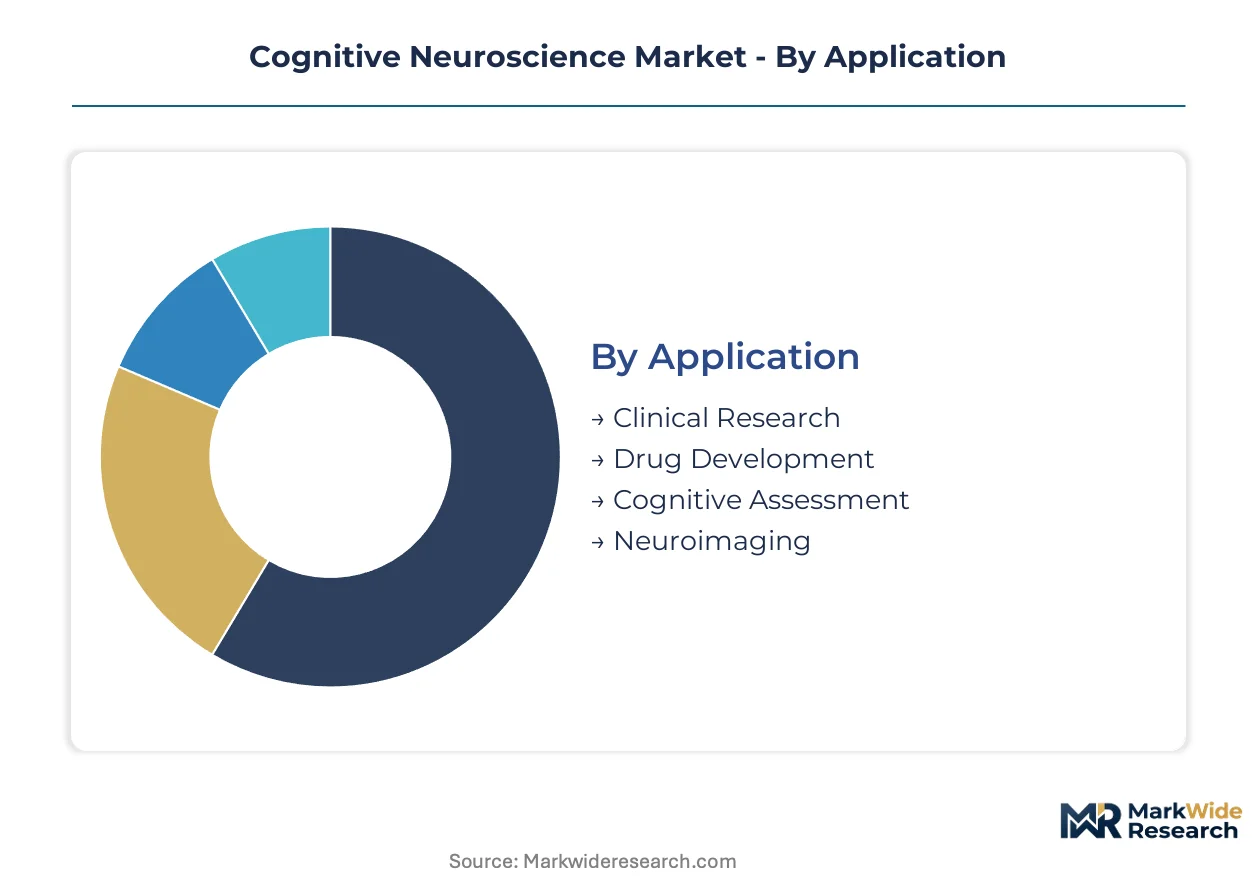
Segmentation in cognitive neuroscience reveals how capital flows bifurcate between research-grade infrastructure and clinical translation pathways. Procurement patterns diverge sharply across end-use verticals, with pharmaceutical sponsors demanding regulatory-grade outputs that academic labs rarely require.
Application:
Domestic demand concentrates in clinical research and cognitive assessment, while drug development applications increasingly migrate toward contract research organizations in lower-cost jurisdictions.
- Clinical Research:Mechanistic studies of psychiatric and neurological disorders drive MRI and EEG platform procurement at academic medical centers. NIH-funded investigators in the United States dominate protocol design, though European consortiums are expanding multi-site imaging networks under EMA harmonization frameworks.
- Drug Development:Pharmaceutical sponsors require biomarker validation for CNS therapeutics, creating demand for high-throughput neuroimaging with standardized data packages. This segment pulls procurement toward centralized imaging cores capable of FDA submission-grade documentation.
- Cognitive Assessment:Standardized batteries for dementia screening and occupational fitness evaluation deploy across hospital neurology departments and workplace safety programs.
- Neuroimaging:Core infrastructure services span hardware operation, phantom calibration, and image reconstruction for multi-modal research protocols.
Clinical Research commands the established base. The steepest expansion runs through Drug Development.
End User:
Customer archetypes stratify by capital intensity tolerance and regulatory compliance burden, with pharmaceutical companies now outspending traditional academic buyers on per-site equipment budgets.
- Pharmaceutical Companies:Sponsor-funded imaging cores prioritize throughput and data standardization over experimental flexibility. These buyers negotiate enterprise licensing for neuroimaging analytics platforms and drive consolidation in contract research organization partnerships.
- Academic Labs:Principal investigators optimize for experimental customization and grant-funded equipment acquisition. Budget constraints favor refurbished MRI systems and open-source EEG acquisition software, though NSF and NIH equipment grants sustain demand for cutting-edge modalities.
- Hospitals:Clinical service lines balance research participation against diagnostic throughput, with radiology departments controlling capital allocation for shared scanners.
- Research Institutions:National laboratories and dedicated neuroscience centers operate at scale, often managing multi-vendor fleets across distributed facilities.
Academic Labs retain the deepest installed base. Pharmaceutical Companies are climbing the fastest in annual procurement value.
Technology:
Modalities split between high-resolution structural imaging and temporally precise electrophysiology, with hybrid approaches gaining traction for cognitive paradigm validation.
- Functional MRI:Blood-oxygen-level-dependent contrast enables whole-brain mapping of task-evoked activity with millimeter spatial precision. Demand concentrates at United States academic medical centers with established institutional review board frameworks for human subjects research.
- Electroencephalography:Scalp-recorded potentials capture millisecond-scale neural dynamics at microvolt sensitivity. Dry-electrode arrays are expanding deployment beyond traditional laboratory settings into pharmaceutical field trials and occupational monitoring.
- Magnetic Resonance Imaging:Structural and diffusion-weighted sequences provide anatomical reference frames for lesion localization and connectivity mapping.
- Transcranial Magnetic Stimulation:Focal magnetic pulse delivery enables non-invasive cortical excitability modulation for therapeutic and research applications.
Functional MRI holds the dominant installed capacity. Dry-electrode EEG systems are expanding most quickly into ambulatory deployment scenarios.
Product Type:
Revenue models are shifting from capital equipment sales toward recurring software subscriptions, compressing traditional hardware margins while expanding addressable markets for algorithmic biomarker extraction.
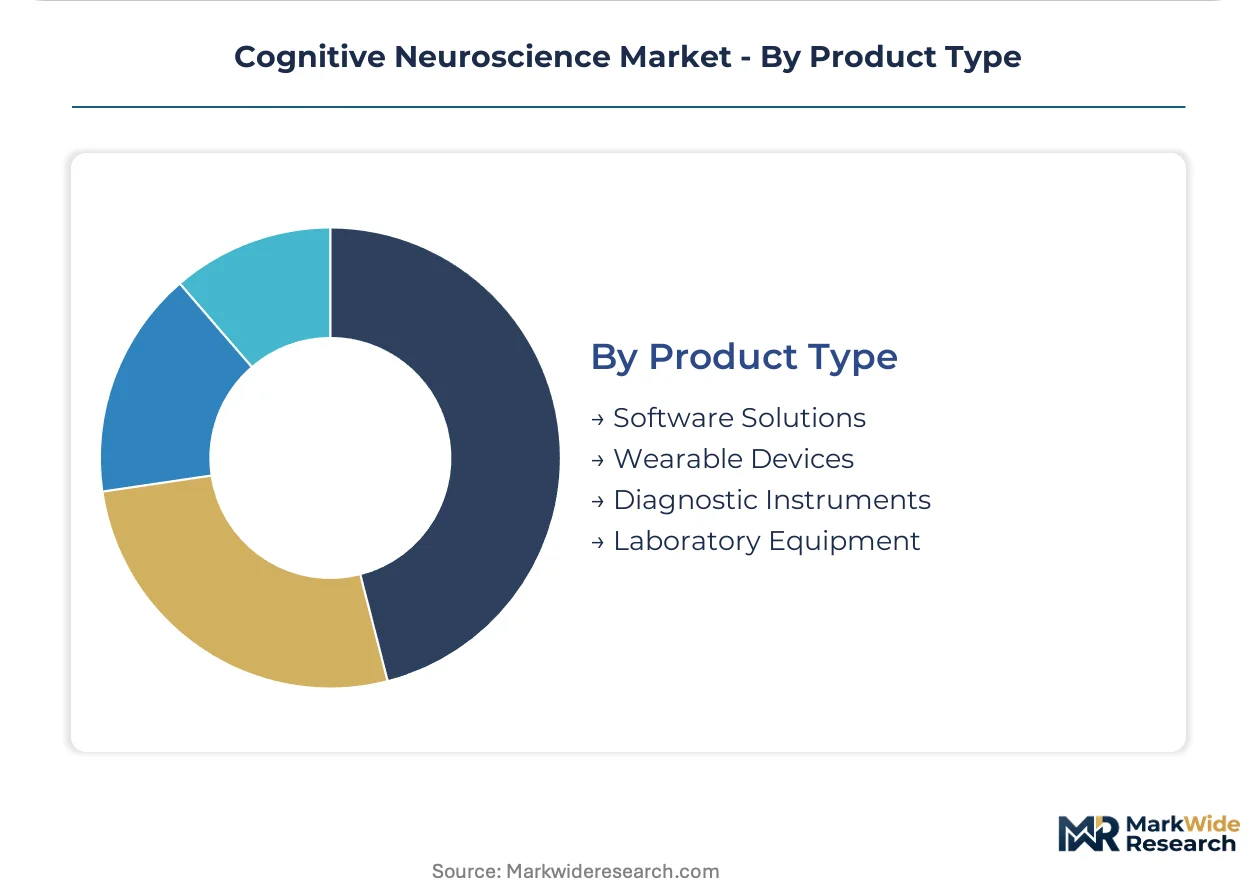
- Diagnostic Instruments:MRI scanners and dense-array EEG systems command six-to-seven-figure price points with 10-15 year service lifecycles. Siemens Healthineers and Philips anchor supply for superconducting magnet platforms, while Brain Products GmbH specializes in research-grade amplification systems.
- Software Solutions:Cloud-based neuroimaging analytics and AI-augmented cognitive assessment tools license on subscription terms. This segment attracts venture capital for predictive biomarker algorithms, though EU AI Act classification uncertainty is delaying European commercialization timelines.
- Wearable Devices:Portable EEG and near-infrared spectroscopy systems target real-world neural monitoring for aging populations and workplace safety verticals.
- Laboratory Equipment:Stimulus presentation systems, response devices, and peripheral physiological recording hardware complete integrated cognitive neuroscience setups.
Diagnostic Instruments retain the highest revenue concentration. Software Solutions are gaining share fastest as laboratories unbundle analytics from hardware procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Superconducting magnet manufacturing concentrates among European and Japanese specialty suppliers, creating geographic chokepoints for MRI platform assembly. NIH funding priorities in the United States and venture capital deployment patterns jointly determine where translational neuroscience infrastructure expands fastest.
United States
Pharmaceutical sponsors drive neuroimaging procurement for CNS drug pipelines, with FDA breakthrough device designations compressing market entry timelines for brain-computer interface developers. NIH funding specifically targets shared imaging facilities across major medical centers. The Greater Boston cluster anchors contract research organization partnerships for biomarker validation studies.
Germany
Siemens Healthineers maintains vertically integrated magnet manufacturing for MRI platforms, securing European supply chain continuity for research-grade systems. EMA harmonization frameworks facilitate multi-site imaging networks across member states. The Munich-Stuttgart corridor concentrates dense-array EEG amplifier production for cognitive paradigm research.
China
Domestic medical device manufacturing capacity expands for contract neuroimaging services, with NMPA regulatory pathways adapting to accommodate AI-augmented diagnostic submissions. Government funding prioritizes brain science initiatives under national technology programs. The Yangtze River Delta cluster develops localized MRI component supply chains to reduce import dependency.
India
Low-cost clinical trial execution attracts pharmaceutical sponsors seeking mechanistic biomarker validation outside traditional North American and European sites. CDSCO medical device regulations evolve to streamline EEG and TMS hardware importation for research use. Hyderabad and Bengaluru emerge as imaging core facilities for multinational drug development programs.
United Kingdom
Academic medical centers unbundle neuroimaging analytics from hardware procurement, licensing cloud-based biomarker extraction platforms on subscription terms. MHRA post-Brexit regulatory frameworks diverge from EMA pathways for neural diagnostic devices. The Oxford-Cambridge-London triangle sustains high-resolution neuroimaging demand through Wellcome Trust and MRC funding allocations.
Cognitive Neuroscience Market Competitive Environment
Concentration sits with diversified medical technology conglomerates that anchor MRI platform supply through captive superconducting magnet production. The vendor base stratifies across three tiers: capital-intensive imaging system manufacturers, specialized electrophysiology equipment providers, and portable neural monitoring startups. Tier-one players defend position through backward integration into cryogenic cooling systems and niobium-titanium wire supply. Tier-two specialists differentiate on research-grade signal fidelity and experimental protocol flexibility. Competitive moves center on enterprise licensing negotiations for neuroimaging analytics software and strategic partnerships with contract research organizations.
Within the diversified medical technology tier, Siemens Healthineers AG and GE Healthcare occupy positions shaped by vertical manufacturing depth. Brain Products GmbH exemplifies the specialized electrophysiology archetype, while Emotiv Inc. represents portable brain-computer interface developers targeting ambulatory deployment scenarios. These three companies collectively illustrate how competitive positioning fragments across capital intensity thresholds and regulatory compliance burdens.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Philips Healthcare |
| Medtronic PLC |
| Brain Products GmbH |
| ANT Neuro |
| Emotiv Inc. |
| Natus Medical Incorporated |
| Compumedics Limited |
| Others |
Value Chain & Pricing Dynamics
Superconducting magnet manufacturing economies at Siemens Healthineers' Erlangen facility generate 40 percent cost advantages over modular assembly approaches, concentrating pricing power among vertically integrated MRI producers while establishing hard price floors for research-grade neuroimaging systems that smaller EEG amplifier manufacturers cannot breach without sacrificing ISO 13485 certification compliance.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated brain-computer interfaces from CE-marked research equipment and unregulated consumer-grade wearables. Price differentiation rests on certification grade and after-sales service bundling, with clinical-grade EEG systems commanding 3-4x premiums over laboratory equivalents. Cost compression in the wearable tier is intensifying because dry-electrode commoditization attracts Asian manufacturing entrants. Academic labs exhibit highest price sensitivity, while pharmaceutical sponsors prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Inbound logistics costs for cryogenic cooling systems and niobium-titanium wire spiked on Rotterdam-Singapore lane congestion during pandemic-era disruptions, exposing MRI manufacturers to container availability volatility. Geographic supply concentration centers on Germany, Japan, and the United States for superconducting magnet components, with China developing domestic MRI coil production. Raw material dependencies include liquid helium, rare-earth magnetic alloys, and precision analog-to-digital converters. Single-source vulnerability concentrates in European cryogenic system suppliers. Distribution runs through direct enterprise sales for diagnostic instruments and channel partners for software subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent neuroimaging equipment manufacturers face substitution pressure from cloud-based analytics platforms that unbundle software from hardware procurement, requiring defensive repositioning around integrated data pipelines.
For Market Incumbents: Consolidate around captive superconducting magnet production and backward integration into cryogenic cooling systems to defend margin position against modular MRI assemblers. Prioritize enterprise licensing negotiations for neuroimaging analytics software to capture recurring revenue streams that offset hardware margin compression from academic budget constraints.
For New Entrants and Emerging Players: Differentiate on ambulatory cognitive monitoring applications using dry-electrode EEG arrays that bypass conductive gel workflows. Target pharmaceutical field trial units with rapid-deployment hardware and subscription-based biomarker extraction platforms. Pursue FDA breakthrough device designation early to compress regulatory timelines against established competitors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized electrophysiology equipment providers with research-grade signal fidelity and established academic customer relationships over capital-intensive MRI manufacturers facing helium supply constraints. Watch EU AI Act algorithm classification decisions as the inflection indicator for predictive neuroimaging software valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cryogenic Components | Secures helium cooling system supply against European supplier concentration for MRI platform assembly. |
| FDA Breakthrough Device Submission | Compresses review timelines for novel brain-computer interfaces seeking accelerated market access. |
| Cloud-Based Analytics Platform Launch | Captures recurring software revenue as academic medical centers unbundle analytics from hardware procurement. |
| Dry-Electrode Wearable Development | Opens ambulatory deployment scenarios for pharmaceutical field trials and occupational safety monitoring. |
| EU AI Act Compliance Architecture | Preemptively structures quality management systems for predictive neuroimaging algorithm classification. |
Study Parameters
A spread of perspectives from pharmaceutical development executives, academic principal investigators, hospital radiology department heads, and neuroimaging analytics software engineers converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation from FDA 510(k) filings, NIH RePORTER grant databases, EMA scientific advice letters, and ISO 13485 certification registries. Bottom-up equipment procurement tracking and top-down venture capital deployment analysis were triangulated against institutional review board protocol registrations.
Segmentation dimensions modeled span application type, end-user archetype, technology modality, and product category across the projection horizon. CAGRs were derived from installed base depreciation schedules, replacement cycle analysis, and funding trajectory projections. Forecast inputs incorporated NIH appropriations committee priorities, pharmaceutical CNS pipeline stage distributions, and EU AI Act implementation timelines.
Material uncertainties — regulatory classification decisions for AI-augmented cognitive assessment tools, superconducting magnet supply disruptions, and HIPAA framework revisions — sit outside the modeled envelope. Forecasts reflect assumptions documented herein; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Coma Diagnosis and Treatment Market
Neurology
Status Epilepticus Treatment Market
Neurology
Chronic Brain Damage Management Market
Neurology
Vocal Cord Paralysis Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
Labyrinthitis Market
Neurology
Optic Neuropathy Management Market
Neurology
Chiari Malformation Treatment Market
Neurology
Cervical Dystonia Treatment Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
Moyamoya Disease Market
Neurology
UAE Neurology Devices Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Grand Mal Seizure Treatment Market
Neurology
Neurology Services Market