
 US Advance Care Planning Solutions Market | 2026-2036
US Advance Care Planning Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
US Advance Care Planning Solutions Market Intelligence
Modular bundling of software with consultation services is recalibrating how health systems procure advance care planning tools. ACP Decisions leverages video-based decision aids to anchor its position in provider workflows. MyDirectives, Inc. competes through direct-to-patient digital vault architecture that extends consumer control over document portability. VyncaCare specializes in EHR-integrated advance care planning modules that dominate inpatient and post-acute settings.
Advance care planning solutions encompass digital platforms, clinical protocols, and legal documentation systems designed to capture, store, and retrieve patient treatment preferences across care transitions. These systems employ structured data formats, interoperable APIs, and clinical decision support algorithms to ensure preference-aligned care delivery. Software solutions and web platforms currently lead product type segmentation, while telehealth and hybrid delivery modes are expanding fastest as remote engagement protocols mature. Healthcare providers remain the dominant end-user segment, though patient-facing mobile applications are gaining traction as direct enrollment tools.
CMS, HIPAA, and the ADA shape market requirements through reimbursement rules, privacy safeguards, and accessibility mandates that dictate product design and deployment standards. State-level POLST and advance directive statutes create additional compliance complexity, particularly for multi-state health systems operating across incompatible legal frameworks. Stakeholders must monitor evolving Medicare Advantage supplemental benefit expansions and state Medicaid waiver innovations that could redefine funding flows for advance care planning services.
Market Dynamics
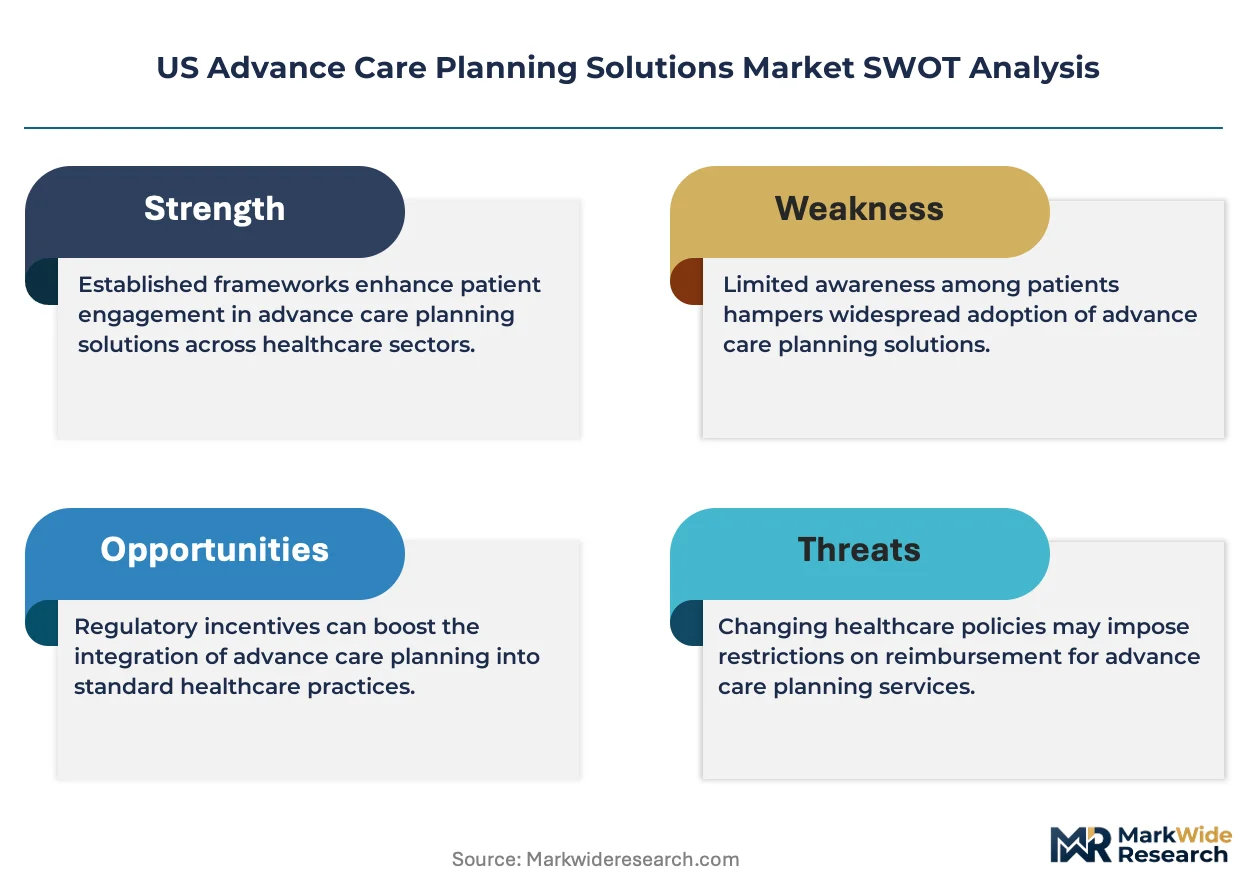
CMS reimbursement policy shifts toward value-based care are forcing health systems to embed advance care planning into standard clinical workflows, creating structural demand for interoperable digital platforms that capture patient preferences across acute and post-acute transitions.
Growth Catalysts
- HIPAA-compliant data exchange frameworks:Federal privacy safeguards mandate interoperable patient record portability, accelerating provider investment in standardized advance directive vaults that integrate with existing EHR infrastructure.
- Integrated delivery networks:Consolidated health systems spanning hospitals, skilled nursing facilities, and home health agencies require unified preference documentation systems to reduce care variation and penalty exposure under Medicare Advantage quality metrics.
- Natural language processing:AI-driven clinical decision support tools embedded in EHR workflows automatically surface patient treatment preferences at point-of-care, reducing manual documentation burden and improving alignment rates.
Market Restraints
- State-level POLST incompatibility:Incompatible legal frameworks across California, New York, and Massachusetts create compliance complexity for multi-state health systems, forcing redundant documentation processes and legal review overhead.
- Legacy EHR fragmentation:Dominant inpatient systems from Epic and Cerner maintain proprietary data architectures that resist third-party advance care planning module integration, limiting vendor market access.
- Behavioral substitution by informal family documentation:Informal advance directive completion through estate attorneys and paper-based family discussions persists as a zero-cost alternative, particularly among rural Medicare populations with limited digital literacy.
Strategic Opportunities
- Texas Medicaid waiver innovations:State-level Medicaid expansion of community-based advance care planning services creates new reimbursement pathways for telehealth-enabled consultation platforms targeting underserved rural counties.
- Patient-facing mobile application channels:Direct-to-consumer enrollment tools bypass provider-controlled EHR gatekeepers, capturing preference documentation upstream before acute episodes and creating portable data assets.
- Medicare Advantage supplemental benefit expansions:CMS guidance permitting in-home advance care planning as a covered supplemental benefit opens new payment streams for hybrid telehealth-clinical consultation service bundles.
Industry Challenges
- Clinical workflow integration complexity:Embedding preference documentation triggers into existing EHR order sets requires health system-specific customization, extending implementation timelines and consuming IT resources.
- Behavioral health specialist shortages:Licensed social workers and palliative care clinicians capable of conducting reimbursable advance care planning consultations remain concentrated in urban academic medical centers, constraining service expansion into community hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Advance Care Planning Solutions Market |
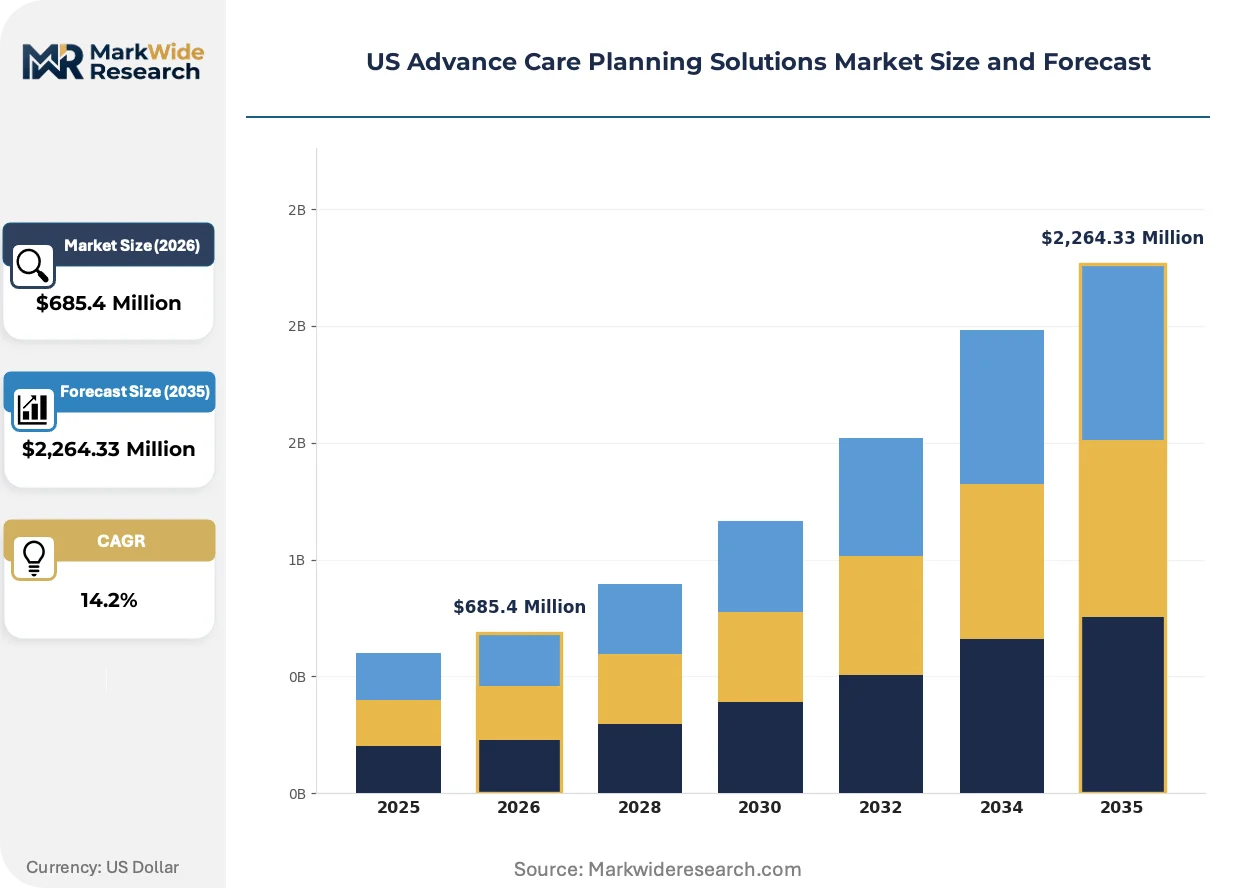
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,264.33 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Mobile Applications, Web Platforms, Consultation Services End User: Healthcare Providers, Patients, Family Members, Caregivers Delivery Mode: Online, In-Person, Hybrid, Telehealth Compliance Area: Regulatory Guidance, Legal Documentation, Ethical Considerations, Best Practices |
| Companies Covered | ACP Decisions, WiserCare, MyDirectives, Inc., ThoroughCare, Inc., VyncaCare, Aledade, Sharp HealthCare, Respecting Choices, Bronson Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Advance Care Planning Solutions Market Strategic Shifts & Innovations
Digital advance care planning platforms are absorbing functionality from adjacent clinical documentation systems, blurring traditional boundaries between legal document management, clinical decision support, and patient engagement tools.
Structured data formats for advance directive elements are absorbing HL7 FHIR standards to enable seamless EHR interoperability. Epic, Cerner, and Meditech health systems are deploying these modules in inpatient and emergency department settings at accelerating pace. This standardization is absorbing vendor differentiation toward workflow customization and clinical training services rather than proprietary data architectures.
CMS Medicare Advantage supplemental benefit guidance is reshaping reimbursement eligibility for in-home advance care planning consultations. The policy expansion enables licensed clinical social workers to bill for telehealth-enabled preference documentation sessions. Medicare Advantage plans in Florida and Arizona are responding with contracted provider network expansions targeting retiree-dense counties.
Patient-controlled data vault architectures are displacing provider-centric document storage as the preferred portability mechanism. Direct-to-patient platforms enable cross-health system document transfer without institutional IT integration. California and Texas consumers are driving adoption through employer-sponsored benefits and state health insurance marketplace education campaigns.
US Advance Care Planning Solutions Market Segmentation
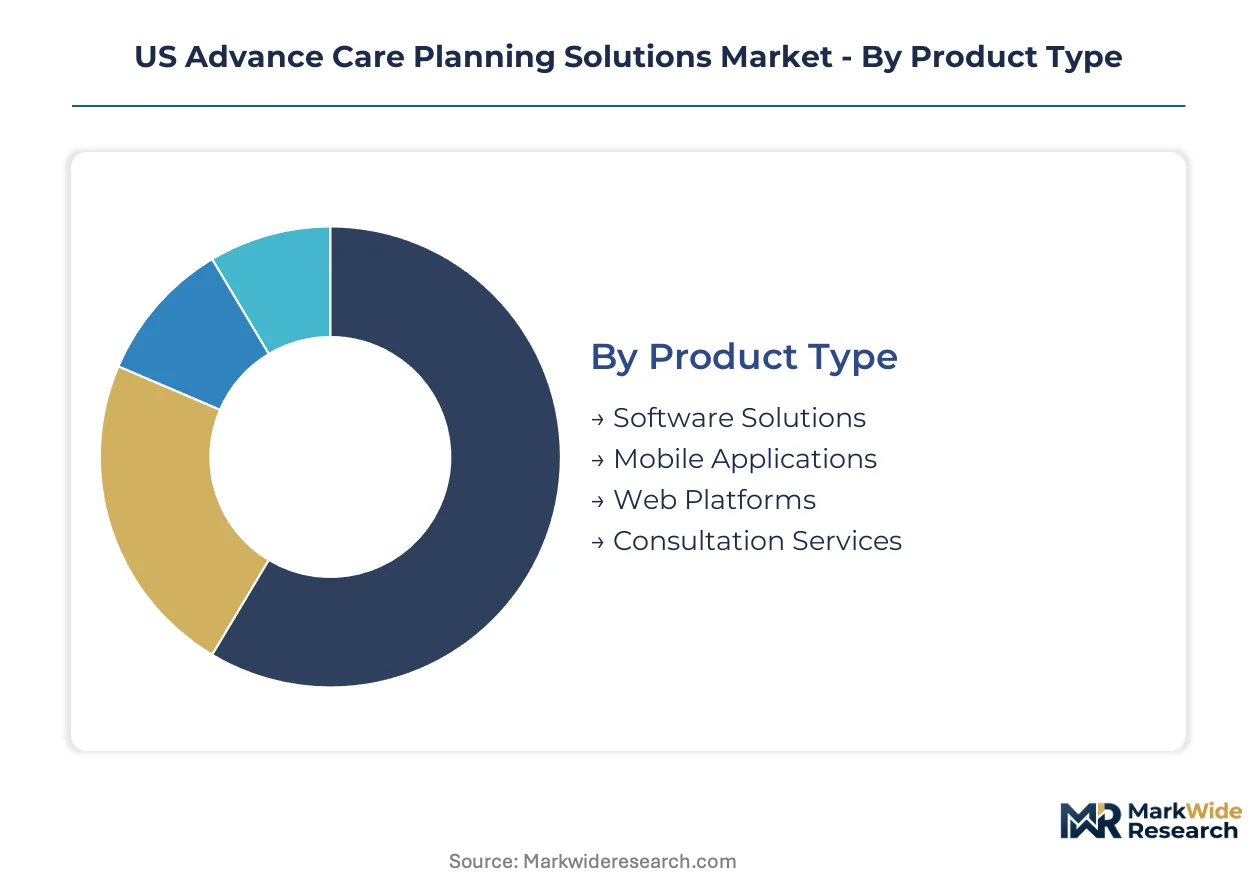
Segmentation in US advance care planning solutions reveals how regulatory complexity, reimbursement pathways, and user workflow preferences fragment procurement decisions across health systems and consumer channels.
Product Type:
HIPAA compliance mandates and state POLST variations create divergent certification burdens across product categories, with EHR-integrated modules facing the most stringent interoperability requirements.
- Software Solutions:Enterprise-grade platforms deploy structured data formats and HL7 FHIR APIs to embed preference documentation directly into Epic and Cerner workflows. Demand concentrates in California integrated delivery networks where Medicare Advantage quality metrics penalize care variation across acute-to-post-acute transitions.
- Web Platforms:Browser-accessible vaults enable cross-health system document portability without institutional IT integration. Texas and Florida consumers drive adoption through employer-sponsored benefits and state marketplace education campaigns, bypassing provider-controlled EHR gatekeepers.
- Mobile Applications:Direct-to-patient enrollment tools capture preference documentation upstream before acute episodes.
- Consultation Services:Licensed clinical social workers deliver reimbursable telehealth-enabled sessions under CMS Medicare Advantage supplemental benefit guidance.
Leading the category by volume: Software Solutions. Growing fastest: Web Platforms.
End User:
Procurement authority and reimbursement eligibility split unevenly across user types, with institutional buyers controlling EHR-integrated deployments while patient-directed purchases accelerate in direct-to-consumer channels.
- Healthcare Providers:Hospitals and skilled nursing facilities dominate procurement through value-based care contracts that embed advance care planning into standard clinical workflows. California, Texas, and Florida health systems invest most heavily as integrated delivery network consolidation creates unified preference documentation requirements across acute and post-acute settings.
- Patients:Direct enrollment through mobile and web platforms accelerates as portable data vault architectures displace provider-centric storage. Urban Medicare populations in Arizona and Florida adopt fastest where digital literacy and retiree density align.
- Family Members:Surrogate decision-makers access documented preferences through patient-granted portal permissions.
- Caregivers:Home health aides and informal caregivers retrieve treatment instructions via simplified mobile interfaces.
Dominating procurement volume: Healthcare Providers. Expanding most quickly: Patients.
Delivery Mode:
Reimbursement policy and clinical workforce distribution reshape modality mix, with telehealth expansion constrained by behavioral health specialist shortages in rural counties.
- Hybrid:Combined telehealth-clinical consultation bundles capture Medicare Advantage supplemental benefit payments while addressing workflow integration complexity. Florida and Arizona plans contract network expansions targeting retiree-dense counties where in-home advance care planning qualifies for reimbursement.
- Telehealth:Remote-enabled preference documentation sessions billable under CMS guidance accelerate where licensed social worker shortages limit in-person capacity.
- Online:Self-directed platform completion without clinical facilitation.
- In-Person:Traditional bedside consultation in academic medical centers.
Highest current volume: Hybrid. Steepest expansion trajectory: Telehealth.
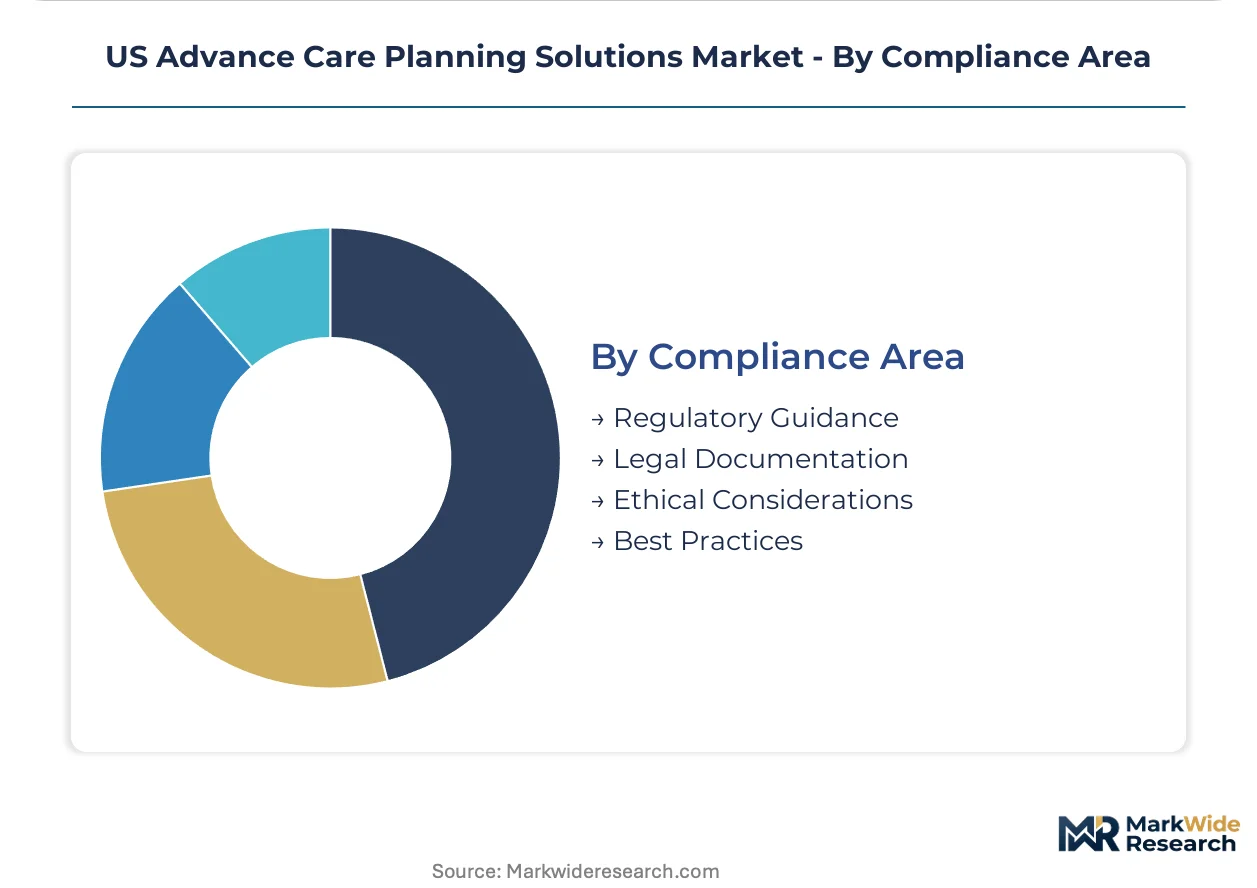
Compliance Area:
Multi-state health system operations face compounding legal complexity as state-level POLST and advance directive statutes create incompatible documentation requirements.
- Legal Documentation:State-specific advance directive and POLST form variations force redundant processes for California, New York, and Massachusetts operations. Legal review overhead concentrates procurement decisions toward vendors with multi-jurisdictional template libraries.
- Regulatory Guidance:CMS reimbursement rules and Medicare Advantage supplemental benefit guidance dictate service bundling and billing eligibility. Federal policy shifts accelerate provider investment in compliant workflow integration.
- Ethical Considerations:Surrogate decision-making protocols and capacity assessment standards vary by state medical board guidance.
- Best Practices:Clinical training and workflow customization services differentiate vendor offerings as standardized data formats commoditize core platform functionality.
Consuming largest compliance investment: Legal Documentation. Gaining strategic priority: Regulatory Guidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solution development concentrates in California and Texas while consumption spreads across retiree-dense states with integrated delivery networks. CMS reimbursement policy shifts create divergent adoption timelines across state Medicaid programs.
California
Medicare Advantage quality metrics penalize care variation across acute-to-post-acute transitions, driving health system investment in unified preference documentation. State POLST form requirements create compliance complexity for multi-jurisdictional operators. Kaiser Permanente and Sutter Health anchor deployment in the San Francisco Bay Area and Los Angeles metro corridors.
Texas
Aging rural populations and Medicaid waiver innovations for community-based advance care planning services expand addressable demand. State-level reimbursement pathway experiments create new payment streams for telehealth-enabled consultation platforms. Houston Methodist and Baylor Scott & White Health systems dominate procurement in the Texas Medical Center and Dallas-Fort Worth clusters.
Florida
Retiree density and Medicare Advantage plan concentration generate the highest per-capita solution adoption rates. CMS supplemental benefit guidance permits in-home advance care planning as a covered service, triggering contracted provider network expansions. Mayo Clinic Florida and AdventHealth anchor implementation in Jacksonville and Orlando metropolitan zones.
New York
Incompatible POLST statutes with neighboring states force redundant documentation processes for multi-state health systems operating across New England and Mid-Atlantic corridors. State medical board guidance on surrogate decision-making protocols adds ethical compliance layers. Northwell Health and NYU Langone drive procurement in the New York City metropolitan and Long Island regions.
Massachusetts
Academic medical center concentration and palliative care specialist density support reimbursable consultation service expansion. State-specific advance directive legal frameworks create procurement friction for national platform vendors. Mass General Brigham and Beth Israel Lahey Health anchor adoption in the Greater Boston and Route 128 technology corridors.
US Advance Care Planning Solutions Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the US Advance Care Planning Solutions Market. Tiered vendor structure separates EHR-integrated platform providers from direct-to-consumer document vault operators. Two strategic archetypes dominate: workflow-embedded clinical decision support vendors and patient-controlled data portability platforms. M&A activity concentrates on telehealth consultation service acquisitions and EHR interoperability capability builds.
Among video-based decision aid specialists, ACP Decisions occupies a position exemplifying workflow-anchored clinical content delivery. MyDirectives, Inc. and VyncaCare represent contrasting architectural approaches—direct-to-patient vault portability versus EHR-native module integration—each anchoring distinct procurement channels within health system and consumer segments.
| Leading Market Players |
|---|
| ACP Decisions |
| WiserCare |
| MyDirectives, Inc. |
| ThoroughCare, Inc. |
| VyncaCare |
| Aledade |
| Sharp HealthCare |
| Respecting Choices |
| Bronson Healthcare |
| Others |
Cost & Logistics Intelligence
Licensed clinical social worker compensation flows through hybrid telehealth-clinical consultation bundles as the dominant cost input, with CMS Medicare Advantage supplemental benefit reimbursement rates determining pricing floors for service delivery across California, Texas, and Florida health systems.
Pricing Analysis
Margin tightening in EHR-integrated software tiers reflects Epic and Cerner proprietary architecture resistance forcing vendor customization overhead. Three-tier pricing structure across enterprise, mid-market, and direct-to-consumer levels separates workflow-embedded modules from standalone web vaults. Cost-down pressure on consultation services accelerates because behavioral health specialist shortages concentrate licensed capacity in urban academic medical centers. Safety-net hospitals and rural Medicare populations exhibit highest price sensitivity; integrated delivery networks with value-based care contracts show lowest.
Supply Chain Analysis
Domestic-content mandates under HIPAA and state-level POLST statutes reshape sourcing toward US-based cloud infrastructure and legal template libraries. Software development concentrates in California and Massachusetts; clinical consultation workforce draws from Texas and Florida. Cloud hosting and API middleware dependencies rest on AWS and Azure domestic regions. Single-source vulnerability sits with Epic's dominance in inpatient EHR architecture. Distribution runs through health system procurement committees and direct-to-consumer app stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where licensed clinical social worker scarcity props pricing power for consultation-enabled platforms.
For Market Incumbents: Anticipate patient-controlled data vault architectures displacing provider-centric storage by deepening EHR interoperability investments and acquiring telehealth consultation service capabilities. State-level POLST incompatibility threats demand multi-jurisdictional legal template libraries as a defensive lever. For New Entrants and Emerging Players: Launch via direct-to-consumer mobile channels targeting Texas Medicaid waiver innovations and Florida Medicare Advantage supplemental benefit expansions. Rural counties with behavioral health specialist shortages represent the most penetrable geography; hybrid telehealth-clinical bundles offer the clearest go-to-market angle. For Investors and Strategic Acquirers: CMS Medicare Advantage supplemental benefit guidance expansion is the leading indicator that reimbursement pathway breadth will determine long-term platform viability. Target acquisition archetypes combine EHR-native module integration with telehealth consultation service networks. Watch for state Medicaid waiver adoption velocity as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| HL7 FHIR API Integration | Epic and Cerner health systems demand seamless EHR embedding for advance care planning modules. |
| Telehealth Consultation Acquisition | Licensed clinical social worker networks unlock Medicare Advantage supplemental benefit revenue streams. |
| Multi-State POLST Template Expansion | California, New York, and Massachusetts legal variations force redundant compliance overhead. |
| Direct-to-Consumer Mobile Launch | Patient-controlled data vaults bypass provider IT gatekeepers in Texas and Florida. |
| Hybrid Service Bundle Development | CMS guidance permits in-home advance care planning as covered supplemental benefit. |
Research Approach
Document review covered CMS reimbursement guidance, state POLST statutes, and HIPAA technical safeguards, complemented by interviews with chief medical information officers, palliative care clinicians, Medicare Advantage plan contract managers, and advance care planning platform product directors. Secondary sources included CMS Medicare data, hospital procurement databases, GPO contracts, and state Medicaid waiver filings. Bottom-up health system deployment estimates triangulated against top-down market sizing.
Cross-reference between historical EHR adoption patterns and expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, end user, delivery mode, and compliance area alongside state-level regulatory cluster. CAGRs derived from reimbursement policy trajectory and workforce supply constraints. Forecast inputs incorporated Medicare Advantage supplemental benefit expansion velocity and telehealth regulatory permanence assumptions.
The model assumes a particular technology adoption path; alternative pathways for AI-driven clinical decision support would alter the outlook. Forecasts reflect assumptions about HIPAA interoperability enforcement and state Medicaid waiver continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Middle East and Africa Heart Failure Software Market
Digital Health Solutions
Global Mhealth Solutions Market
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
North America Digital Health Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
US Digital Therapeutics Market
Digital Health Solutions
Global Smart Hospital Market
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Healthcare Navigation Platform Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
US Real World Evidence Solutions Market