
 Europe Diabetic Foot Ulcer Treatment Market | 2026-2036
Europe Diabetic Foot Ulcer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Diabetic Foot Ulcer Treatment Market Intelligence
European wound care manufacturing is shifting toward integrated biologics and active dressing platforms. Smith & Nephew Plc leverages its R&D footprint in the United Kingdom to sustain leadership in negative pressure systems. Molnlycke Health Care AB anchors its position through specialized foam dressing production for chronic wound segments. ConvaTec Group PLC competes by controlling direct hospital channels across Northern Europe.
Diabetic foot ulcer treatment encompasses medical interventions designed to manage open wounds on the lower extremities of patients with diabetes mellitus, typically employing moisture-retentive dressings, enzymatic or surgical debridement, topical antimicrobial agents, and cellular or tissue-based products to promote granulation tissue formation and prevent infection progression. The primary purpose is to reduce amputation risk, accelerate closure timelines, and lower overall healthcare system burden from recurrent hospitalizations. Wound dressings dominate value pools given their recurring consumption model and premium pricing for advanced modalities such as hydrocolloid and alginate variants. Growth factors represent the fastest-expanding treatment type segment, though from a smaller base, as cellular therapy adoption widens in specialty clinics. Negative pressure wound therapy occupies the highest-margin tier within product categories, constrained mainly by capital equipment requirements and trained clinician availability.
The EU Medical Device Regulation and CE marking framework shape product approval pathways, extending clinical evidence requirements for novel dressings and biologics entering European markets. EMA guidelines on advanced therapy medicinal products intersect with national health technology assessments in Germany, France, and Italy to determine reimbursement eligibility for cellular treatments. France's ANSM and Germany's BfArM enforce post-market surveillance obligations that influence manufacturer quality management investments. Stakeholders must monitor divergence between centralized EU authorization and country-specific pricing negotiations as reimbursement becomes the decisive gate for commercial traction.
Market Dynamics
EU Medical Device Regulation clinical evidence requirements are compressing product development timelines and forcing manufacturers to consolidate pipeline priorities around proven modalities. This regulatory pressure is reshaping competitive positioning across wound care portfolios.
Growth Catalysts
- Silver-integrated antimicrobial dressings:Home care providers in France and the Netherlands are expanding coverage of advanced hydrocolloid and alginate variants with sustained-release ionic silver.
- Germany's reimbursement recalibration:Specialty clinics are expanding diabetic foot ulcer protocols as health technology assessments under BfArM guidance broaden eligibility for cellular therapy interventions.
- Negative pressure wound therapy:Capital equipment investments by hospital procurement consortia in Northern Europe are accelerating trained clinician availability for high-margin system deployment.
Market Restraints
- CE marking pathway extension:Novel biologics face elongated clinical evidence timelines under EU MDR Article 10 requirements, delaying commercial entry by 18-24 months versus previous directives.
- Alginate raw material concentration:Seaweed harvesting and processing capacity clusters in Scotland and Norway, creating supply vulnerability for foam dressing manufacturers dependent on specific polysaccharide grades.
- Enzymatic debridement substitution:Autolytic methods using hydrogel dressings are displacing collagenase-based products in cost-conscious outpatient settings, compressing enzyme segment volume.
Strategic Opportunities
- Italy's underpenetrated home care segment:Regional health authorities in Lombardy and Veneto are piloting remote wound monitoring integration with dressing delivery logistics.
- EMA advanced therapy medicinal product convergence:Cellular and tissue-based products are gaining accelerated assessment pathways when combined with biodegradable scaffold platforms.
- Direct-to-clinic distribution platforms:Specialized wound care distributors in Belgium and the Netherlands are bypassing traditional hospital procurement layers for chronic wound segments.
Industry Challenges
- Biologics manufacturing technician scarcity:GMP-compliant cleanroom operations for cellular products face recruitment gaps across the United Kingdom and Germany.
- Post-market surveillance system integration:ANSM and BfArM adverse event reporting requirements demand IT infrastructure upgrades that smaller manufacturers struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Diabetic Foot Ulcer Treatment Market |
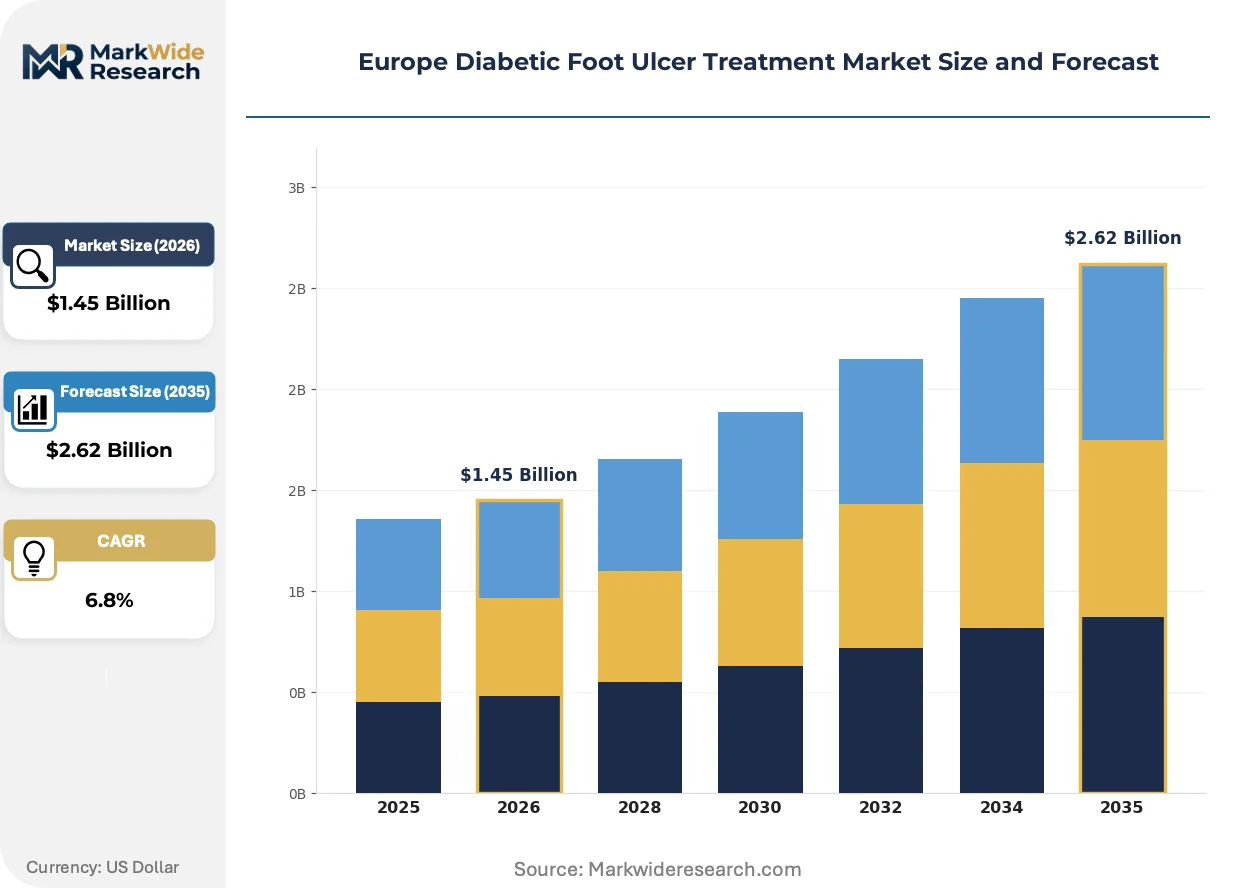
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Wound Dressings, Antibiotics, Debridement, Growth Factors End User: Hospitals, Home Care Providers, Specialty Clinics, Rehabilitation Centers Distribution Channel: Direct Sales, Distributors, E-commerce, Retail Pharmacies Product Type: Hydrocolloid Dressings, Foam Dressings, Alginate Dressings, Negative Pressure Wound Therapy |
| Companies Covered | ConvaTec Group PLC, Smith & Nephew Plc, Coloplast Corp, 3M Health Care, Molnlycke Health Care AB, B. Braun SE, Medline Industries, LP, Organogenesis, Inc., Medtronic, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Diabetic Foot Ulcer Treatment Market Strategic Shifts & Innovations
Active dressing platforms are converging with digital wound assessment tools, creating integrated care protocols that compress healing timelines and reduce specialist consultation frequency. This convergence is redrawing value capture across the treatment pathway.
Negative pressure wound therapy systems are modularizing around disposable cartridge designs that separate pump hardware from exudate collection. German hospital procurement groups are adopting these configurations to reduce per-patient capital allocation while maintaining clinical efficacy. The architecture is enabling rental-to-consumable revenue model transitions that compress payback periods for equipment investments.
EU MDR post-market clinical follow-up requirements are extending evidence obligations for hydrocolloid and alginate dressings previously grandfathered under prior directives. Manufacturers must now generate real-world performance data for legacy SKUs or withdraw from European markets. Wound dressing portfolios with extensive historical lines face disproportionate compliance burden versus newer, narrower product ranges.
Home care nursing networks in France are consolidating purchasing through regional procurement hubs that negotiate multi-year dressing supply contracts. This channel concentration is displacing fragmented individual clinic ordering patterns and forcing manufacturers to dedicate account management resources to fewer, larger relationships. The shift is most visible in the Ile-de-France and Provence-Alpes-Côte d'Azur regions where nursing cooperative density is highest.
Europe Diabetic Foot Ulcer Treatment Market Segmentation
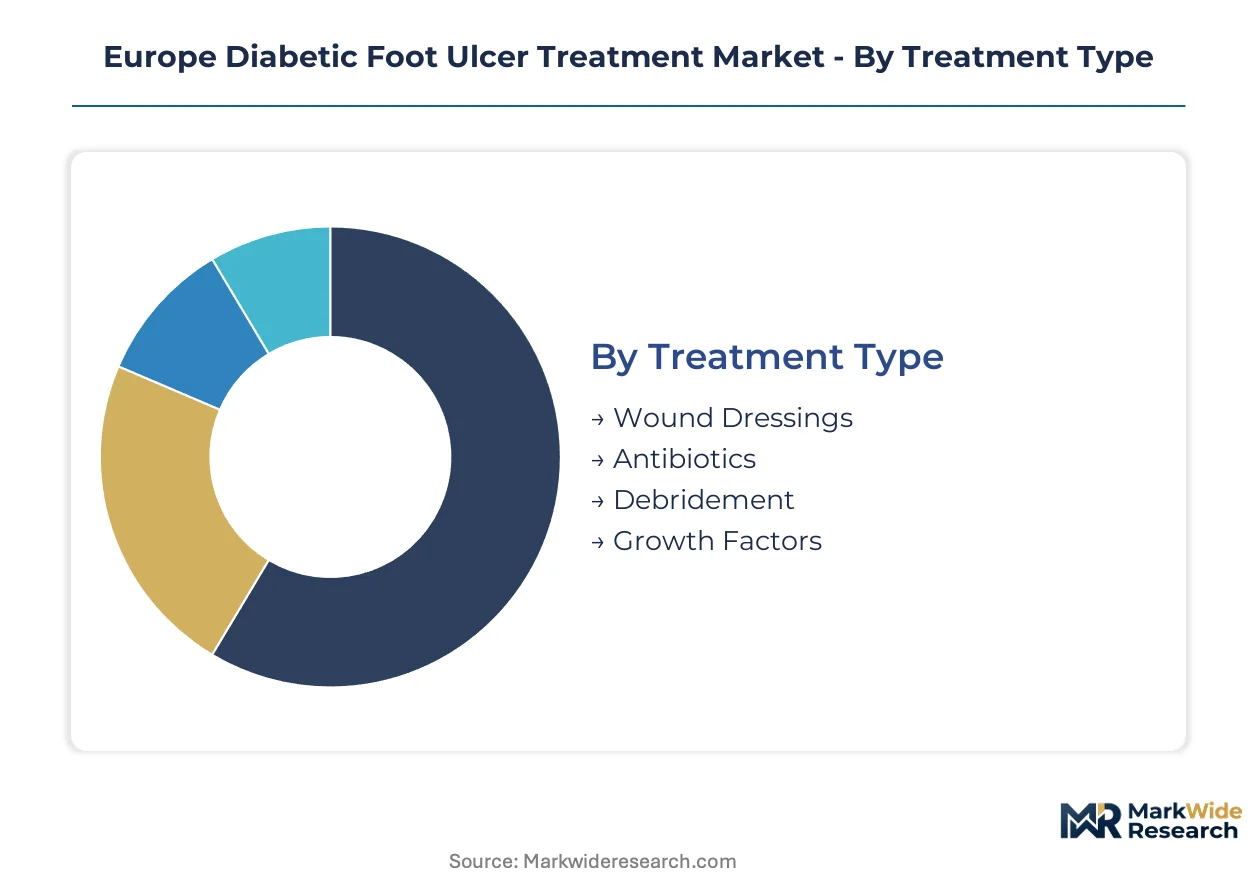
Diabetic foot ulcer treatment markets fragment across therapeutic modality, care setting, and supply pathway. Each segmentation axis reveals distinct margin structures and regulatory exposure that shape manufacturer prioritization.
Treatment Type:
Standardized protocols dominate antibiotic and debridement categories, while cellular therapies and advanced dressings demand customized formulation and dosing calibration.
- Wound Dressings:Moisture-retentive materials including hydrocolloid, alginate, and foam variants form the consumption backbone. Home care networks in France and the Netherlands are expanding coverage of sustained-release silver-integrated formats as outpatient protocols lengthen.
- Growth Factors:Cellular and tissue-based products require cold-chain logistics and specialty clinic administration. Germany's BfArM is broadening reimbursement eligibility under health technology assessment pathways, accelerating clinical adoption from a smaller installed base.
- Antibiotics:Systemic and topical antimicrobial regimens follow established prescribing guidelines across hospital formularies.
- Debridement:Enzymatic and surgical methods face substitution pressure from autolytic hydrogel alternatives in cost-sensitive settings.
Leading the category by volume: Wound Dressings. Expanding most quickly: Growth Factors.
End User:
Procurement authority concentrates differently across settings — hospital consortia negotiate capital equipment, while home care purchasing fragments across regional nursing cooperatives.
- Specialty Clinics:German wound care centers are expanding diabetic foot ulcer protocols amid reimbursement recalibration under EU MDR. These sites drive adoption of negative pressure systems and cellular therapies requiring trained clinician availability.
- Home Care Providers:French regional nursing networks in Ile-de-France and Provence-Alpes-Côte d'Azur are consolidating purchasing through procurement hubs. Multi-year dressing supply contracts are displacing fragmented clinic-level ordering.
- Hospitals:Northern European procurement consortia allocate capital for negative pressure wound therapy hardware.
- Rehabilitation Centers:Post-acute facilities manage longer-duration dressing regimens with emphasis on patient mobility preservation.
Dominant by procurement value: Specialty Clinics. Steepest expansion trajectory: Home Care Providers.
Distribution Channel:
Channel structure varies by product complexity — capital equipment flows through direct relationships, while consumables fragment across intermediaries.
- Distributors:Specialized wound care distributors in Belgium and the Netherlands are bypassing traditional hospital procurement layers for chronic wound segments. These intermediaries aggregate demand across smaller clinic footprints.
- Direct Sales:Negative pressure wound therapy systems and cellular products require clinical training support that mandates manufacturer field presence.
- E-commerce:Basic dressing formats are penetrating remote regions with limited distributor coverage.
- Retail Pharmacies:Over-the-counter hydrocolloid and alginate variants serve patient self-pay segments.
Capturing largest flow: Distributors. Gaining share fastest: Direct Sales.
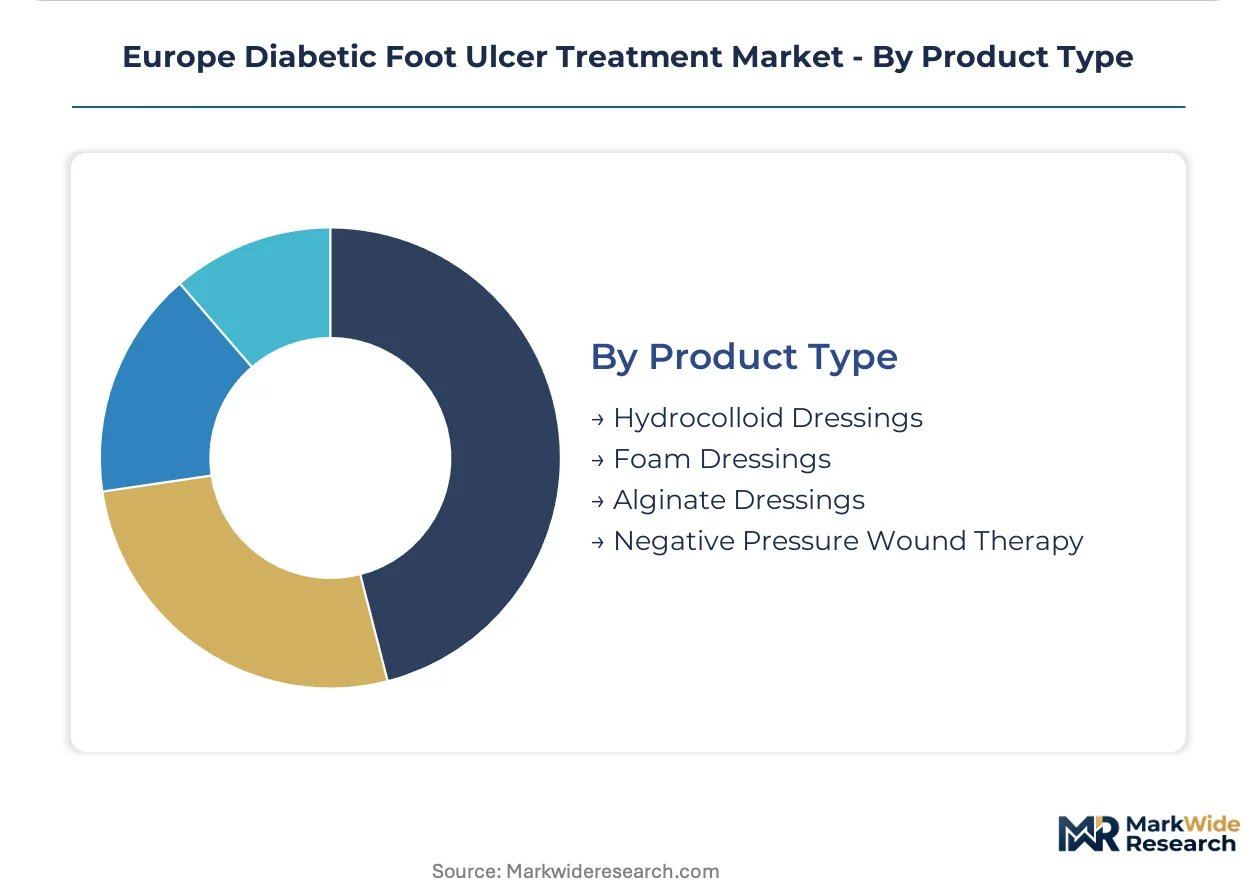
Product Type:
Material science differentiation separates commodity dressing tiers from premium active platforms with integrated antimicrobial or biologic components.
- Negative Pressure Wound Therapy:Modular pump-and-cartridge architectures are separating capital hardware from disposable exudate collection. German hospital groups are adopting these configurations to reduce per-patient capital allocation.
- Foam Dressings:Molnlycke Health Care AB anchors European supply through specialized production for chronic wound segments. Alginate raw material concentration in Scotland and Norway creates supply vulnerability for manufacturers dependent on specific polysaccharide grades.
- Hydrocolloid Dressings:EU MDR post-market clinical follow-up requirements are extending evidence obligations for legacy SKUs previously grandfathered under prior directives.
- Alginate Dressings:Seaweed-derived polysaccharide formats face processing capacity constraints in North Atlantic harvesting regions.
Highest margin tier: Negative Pressure Wound Therapy. Climbing the fastest: Foam Dressings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seaweed harvesting clusters in Scotland and Norway supply alginate polysaccharides that underpin advanced dressing manufacturing across Northern Europe. This raw material geography shapes wound care production economics and supply security calculations for formulators in Germany, France, and the Netherlands.
Germany
Specialty wound care clinics in North Rhine-Westphalia and Bavaria are expanding diabetic foot ulcer protocols as BfArM health technology assessments broaden reimbursement for cellular therapies. The EU MDR framework extends clinical evidence requirements for novel biologics entering German markets. Berlin-Brandenburg hosts concentrated procurement consortia negotiating capital equipment contracts for negative pressure wound therapy systems.
France
Regional nursing networks in Île-de-France and Provence-Alpes-Côte d'Azur are consolidating dressing purchases through multi-year procurement hubs. ANSM enforces post-market surveillance obligations that elevate quality management investments for manufacturers serving French home care channels. Lyon-based wound care distributors are piloting remote monitoring integration with dressing logistics platforms.
United Kingdom
GMP-compliant cleanroom operations for cellular products face technician recruitment gaps across Greater London and the Southeast. The Medicines and Healthcare products Regulatory Agency aligns with EMA advanced therapy medicinal product guidelines to determine market access for biologic interventions. Yorkshire hosts specialized foam dressing production facilities serving chronic wound segments.
Netherlands
Eindhoven Region distributors are bypassing traditional hospital procurement layers to aggregate demand across smaller chronic wound clinic footprints. Silver-integrated antimicrobial dressings are penetrating home care networks as outpatient protocols lengthen treatment durations. Dutch wound care cooperatives are negotiating direct-to-clinic supply contracts that displace fragmented ordering patterns.
Italy
Lombardy and Veneto regional health authorities are piloting remote wound monitoring integration with dressing delivery logistics for underpenetrated home care segments. Italian reimbursement pathways for advanced dressings lag Northern European benchmarks, creating pricing pressure on premium modalities. Milan-based specialty clinics are expanding diabetic foot ulcer assessment capacity amid rising diabetes prevalence.
Europe Diabetic Foot Ulcer Treatment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue biologic-active dressing convergence and digital wound assessment integration. The vendor base stratifies across three tiers: multinational wound care portfolios with hospital channel control, specialized dressing manufacturers with regional feedstock advantages, and cellular therapy developers navigating EMA advanced therapy pathways. Competitive dynamics center on M&A consolidation around biologics capabilities and direct-to-clinic distribution platform investments that bypass traditional procurement layers.
Within the multinational portfolio tier, Smith & Nephew Plc and ConvaTec Group PLC exemplify divergent channel strategies for European market presence. Molnlycke Health Care AB represents the specialized manufacturer archetype with concentrated production advantages. These three entities anchor competitive positioning discussions without exhausting the participant field.
| Leading Market Players |
|---|
| ConvaTec Group PLC |
| Smith & Nephew Plc |
| Coloplast Corp |
| 3M Health Care |
| Molnlycke Health Care AB |
| B. Braun SE |
| Medline Industries, LP |
| Organogenesis, Inc. |
| Medtronic |
| Others |
Cost & Logistics Intelligence
EU MDR sustainability mandates for biodegradable scaffold platforms gate qualified supply access and premium-tier pricing power for cellular therapy developers across German and French specialty clinics. Manufacturers lacking GMP-compliant cleanroom certification face exclusion from reimbursement-eligible product tiers while certified competitors command service-bundled premiums.
Pricing Analysis
Extended warranty and field clinical training bundles separate premium negative pressure system vendors from unbundled equipment suppliers in Northern European hospital consortia. Three-tier pricing structure across premium, standard, and economy levels tracks CE marking tier, alginate raw material grade, and volume commitment scale. Pricing pressure stems from enzymatic debridement displacement by autolytic hydrogel alternatives in French outpatient settings. Home care nursing cooperatives exhibit highest price sensitivity; German specialty clinics demonstrate lowest sensitivity due to cellular therapy reimbursement buffers.
Supply Chain Analysis
Dual-sourcing requirements for alginate polysaccharides mandate Scottish and Norwegian supplier qualification alongside backup Irish seaweed processing capacity for major dressing formulators. Raw material dependencies center on North Atlantic seaweed harvesting, ionic silver antimicrobial integration, and biodegradable polymer scaffold production. Single-source vulnerability concentrates in Scotland-Norway alginate clusters exposed to marine ecosystem variability. Distribution runs through specialized wound care distributors in Belgium and the Netherlands aggregating fragmented clinic demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom technician scarcity across Greater London and the Southeast props pricing for GMP-certified cellular therapy manufacturing capacity. Supply constraints in qualified biologics production sustain margin premiums for incumbent producers.
For Market Incumbents: Deploy backward integration into alginate raw material harvesting to secure Scottish and Norwegian polysaccharide supply against emerging entrant formulation challenges. Consolidate direct hospital channel control in Germany through negative pressure system clinical training investments that lock procurement consortia into multi-year service contracts.
For New Entrants and Emerging Players: Direct-to-clinic e-commerce platforms offer the lowest friction route into underpenetrated Italian home care segments where regional nursing cooperatives lack consolidated procurement hubs. Target Lombardy and Veneto pilot programs integrating remote wound monitoring with dressing logistics. Partner with Belgian specialized distributors to bypass entrenched hospital procurement layers.
For Investors and Strategic Acquirers: BfArM cellular therapy reimbursement expansion announcements are the leading indicator that German specialty clinic demand inflection is materializing. Five-to-ten year viability favors cellular therapy developers with EMA advanced therapy medicinal product pathway progress and biodegradable scaffold platform convergence. Monitor ANSM post-market surveillance IT infrastructure investment requirements as a signal for smaller manufacturer distress acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance accelerates German BfArM reimbursement eligibility timelines. |
| Backward Integration | Scottish seaweed harvesting control secures alginate supply against Norwegian capacity constraints. |
| Hospital System Partnership | Berlin-Brandenburg procurement consortia lock negative pressure system deployment at scale. |
| Software Companion Development | Remote wound monitoring integration captures Lombardy regional health authority pilot contracts. |
| Reimbursement Strategy | French ANSM quality management alignment secures multi-year home care nursing cooperative supply agreements. |
Research Approach
Document review covered EU MDR regulatory filings, EMA advanced therapy medicinal product assessments, and BfArM health technology assessment decisions, complemented by interviews with wound care clinicians, hospital GPO contracts managers, biomedical engineers, and specialized distributor operations leads. Secondary validation drew from hospital procurement databases, GPO contract repositories, and ANSM post-market surveillance records. Bottom-up demand modeling triangulated against top-down market sizing across treatment modality segments.
Market value and volume outputs emerged from integrated segmentation across wound dressing material type, care setting procurement authority, and distribution channel structure over the projection horizon. CAGRs derived from clinician adoption curve analysis for cellular therapies and negative pressure system replacement cycle modeling. Key inputs included alginate raw material processing capacity constraints and German specialty clinic protocol expansion rates.
The model holds under stable EU MDR enforcement and sustained BfArM reimbursement expansion; deviation in ANSM adverse event reporting stringency or Scottish seaweed harvest yields would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
Digital Diabetes Care Market
Diabetes Care
Antidiabetics Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
North America Insulin Infusion Pumps Market