
 Self-Monitoring Blood Glucose (SMBG) Market | 2026-2036
Self-Monitoring Blood Glucose (SMBG) Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Monitoring Blood Glucose (SMBG) Market Analytics
Recurring consumable revenue is tilting toward sensor-integrated platforms and away from legacy strip-dependent models. Abbott Laboratories leverages vertical integration across biosensor wafer fabrication to sustain margin capture on continuous glucose hardware. Roche dominates European laboratory channels while competing in home-use segments through Accu-Chek distribution scale. Sinocare anchors Asia-Pacific volume through cost-optimized electrochemical strip production.
Self-monitoring blood glucose encompasses portable diagnostic systems that measure capillary glucose concentration via enzymatic reactions on disposable strips or subcutaneous interstitial fluid sensors, typically reporting values within 15% of laboratory reference standards per ISO 15197. These devices enable real-time metabolic management for insulin-dependent and non-insulin-dependent diabetes patients, reducing acute hyperglycemic events and long-term complication risk. Continuous glucose monitors and smart meters command expanding margin pools as electrochemical sensor technology matures and optical spectroscopy approaches commercial viability. Traditional meters and test strips retain volume dominance in price-sensitive markets and cash-pay segments where reimbursement for advanced systems remains limited.
FDA premarket review under 21 CFR 862.1345 and ISO 15197 accuracy standards shape product development timelines and market access requirements for US and European manufacturers. The EU Medical Device Regulation and Japan's PMDA quality management standards impose additional clinical validation burdens that filter out smaller competitors. Stakeholders must monitor evolving CMS and national health technology assessment decisions on continuous glucose monitor reimbursement parity, as these coverage determinations will dictate whether sensor-based platforms displace strip-based systems in mainstream diabetes care.
Market Dynamics
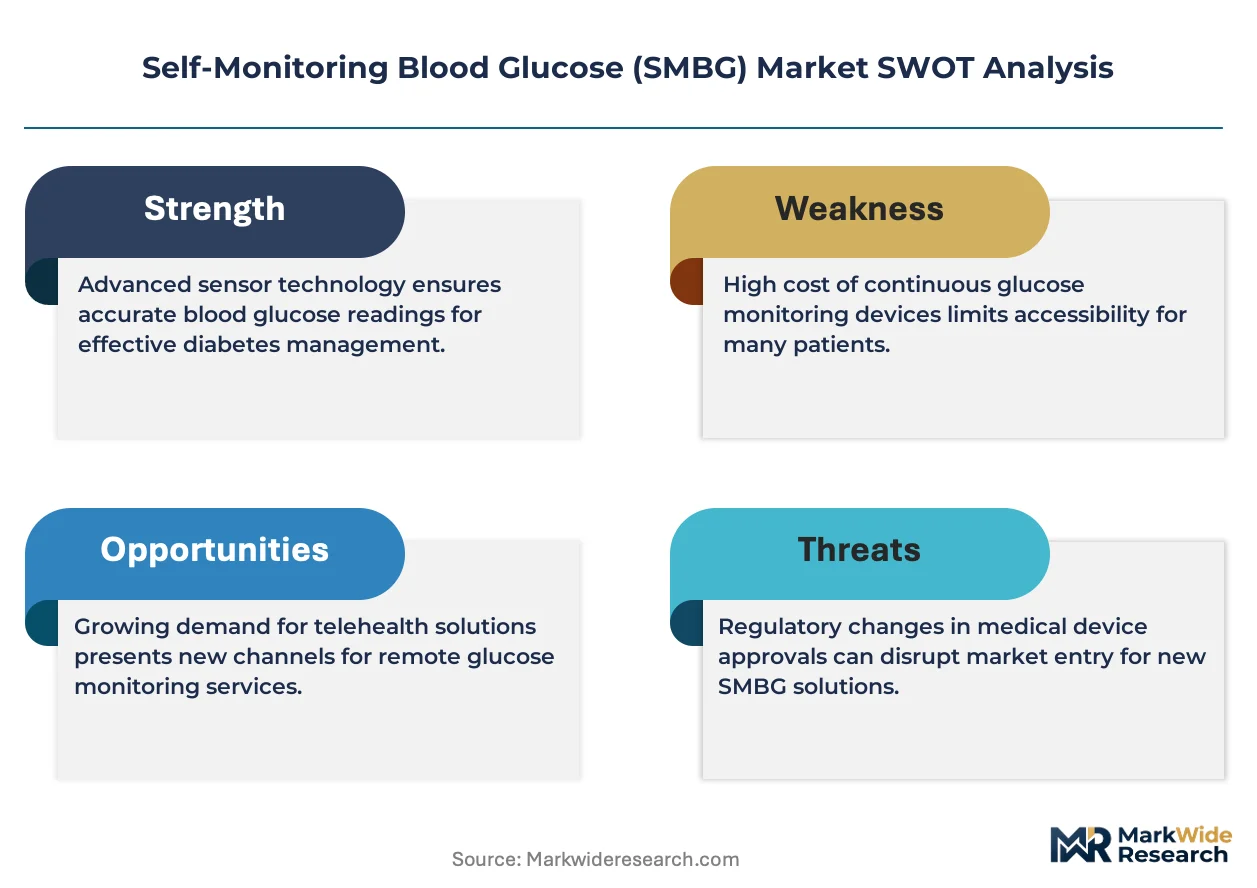
Continuous glucose monitoring platforms are compressing the addressable market for traditional strip-based meters as reimbursement pathways widen and sensor accuracy thresholds tighten under ISO 15197.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage for therapeutic continuous glucose monitors removes out-of-pocket barriers for Type 1 and intensive Type 2 patients in the United States.
- Optical spectroscopy maturation:Non-invasive glucose sensing using near-infrared light promises elimination of fingerstick calibration and disposable consumables.
- Aging demographics in Germany and Japan:Rising diabetes prevalence among patients over 65 drives demand for connected, caregiver-accessible monitoring systems.
Market Restraints
- Precious metal cost volatility:Platinum and palladium price swings in electrochemical sensor electrodes compress margins on strip production.
- FDA premarket notification burdens:510(k) clearance timelines for novel glucose sensors extend 18-24 months, filtering out capital-constrained entrants.
- Non-invasive accuracy limitations:Optical and transdermal alternatives struggle to achieve the 15% mean absolute relative difference threshold under ISO 15197.
Strategic Opportunities
- India's tier-2 and tier-3 cities:Underpenetrated outpatient diabetes management creates volume potential for cost-optimized strip and meter bundles.
- EU Medical Device Regulation harmonization:MDR compliance creates first-mover advantage for manufacturers with established quality management systems.
- Smartphone-integrated biosensors:Convergence of electrochemical sensing with Bluetooth Low Energy and app-based analytics enables direct-to-consumer subscription models.
Industry Challenges
- Biocompatibility engineering talent scarcity:Shortage of specialists in hydrogel chemistry and enzymatic stabilization prolongs sensor development cycles.
- Legacy health record integration:HL7 FHIR compliance requirements complicate data exchange between proprietary CGM platforms and hospital EHR systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Monitoring Blood Glucose (SMBG) Market |
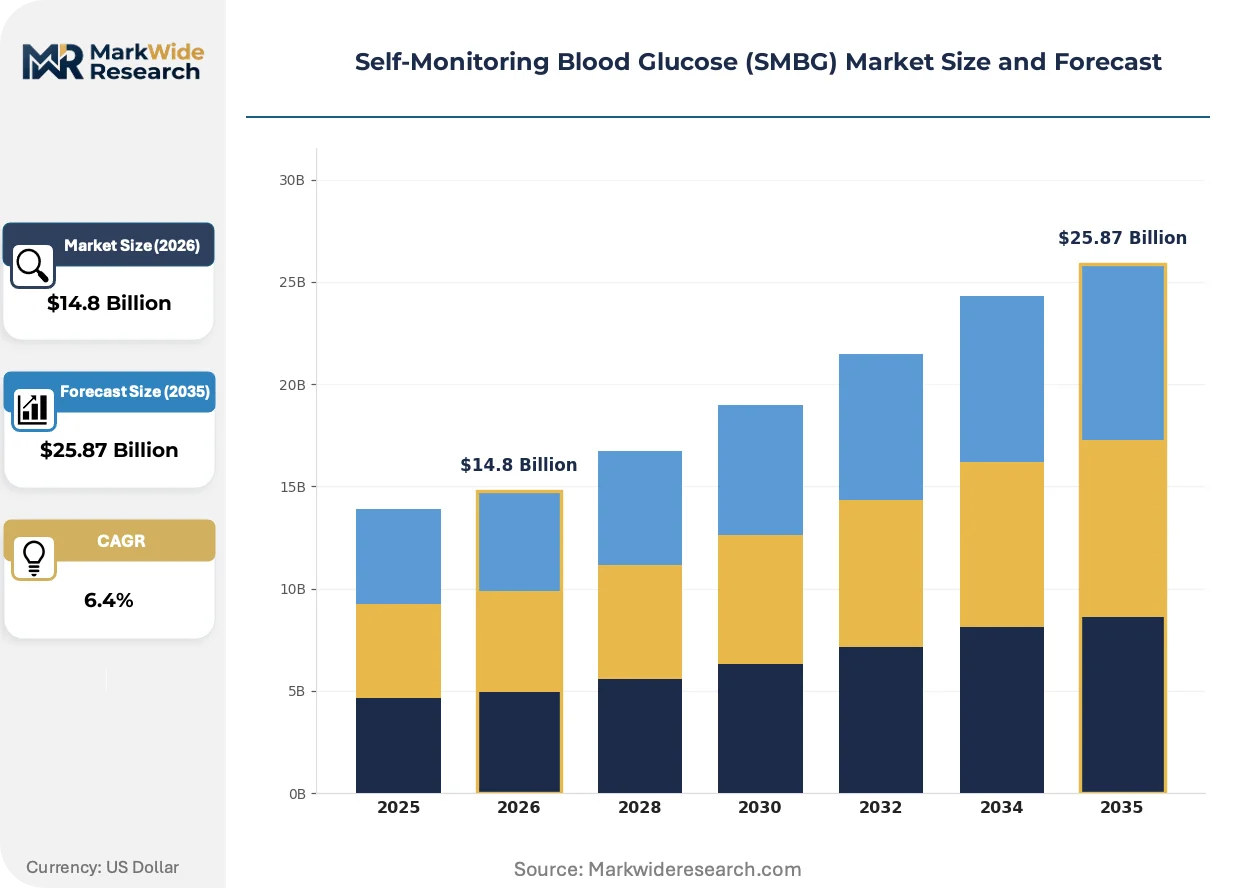
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Meters, Continuous Glucose Monitors, Smart Meters, Test Strips Delivery Mode: Blood Testing, Urine Testing, Non-Invasive Devices, Wearable Technologies End User: Diabetes Patients, Healthcare Providers, Home Users, Pharmacies Technology: Electrochemical Sensors, Optical Sensors, Spectroscopy, Biosensors |
| Companies Covered | F. Hoffmann-La Roche Ltd., Abbott Laboratories, Ascensia Diabetes Care Holdings AG, LifeScan IP Holdings, Sinocare, PHC Holdings Corporation, ARKRAY, B. Braun Melsungen AG, Trividia Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Monitoring Blood Glucose (SMBG) Market Evolving Landscape
Sensor miniaturization and algorithmic calibration advances are collapsing the performance gap between factory-calibrated continuous systems and laboratory reference methods.
Factory-calibrated continuous glucose monitors eliminate fingerstick confirmation requirements through advanced predictive algorithms and stable enzyme formulations. Intensive insulin users in the United States and Germany are migrating to these systems at accelerating rates. This shift is rendering obsolete the traditional meter-plus-strip model for patients requiring frequent glycemic feedback.
The EU Medical Device Regulation imposes stricter clinical evidence requirements for glucose monitoring devices entering the European market. Manufacturers must now submit post-market surveillance data and usability validation studies that exceed previous CE-marking thresholds. Small and mid-sized device companies are responding by consolidating regulatory affairs functions or exiting the European market entirely.
Subscription-based sensor replenishment programs are displacing pharmacy-based strip purchasing among commercially insured populations. Direct-to-consumer channels and employer wellness platforms are capturing patients who previously relied on retail distribution. This pattern is most pronounced in the United States, where high-deductible health plans drive price transparency and cash-pay acceptance for consumable supplies.
Self-Monitoring Blood Glucose (SMBG) Market Segmentation
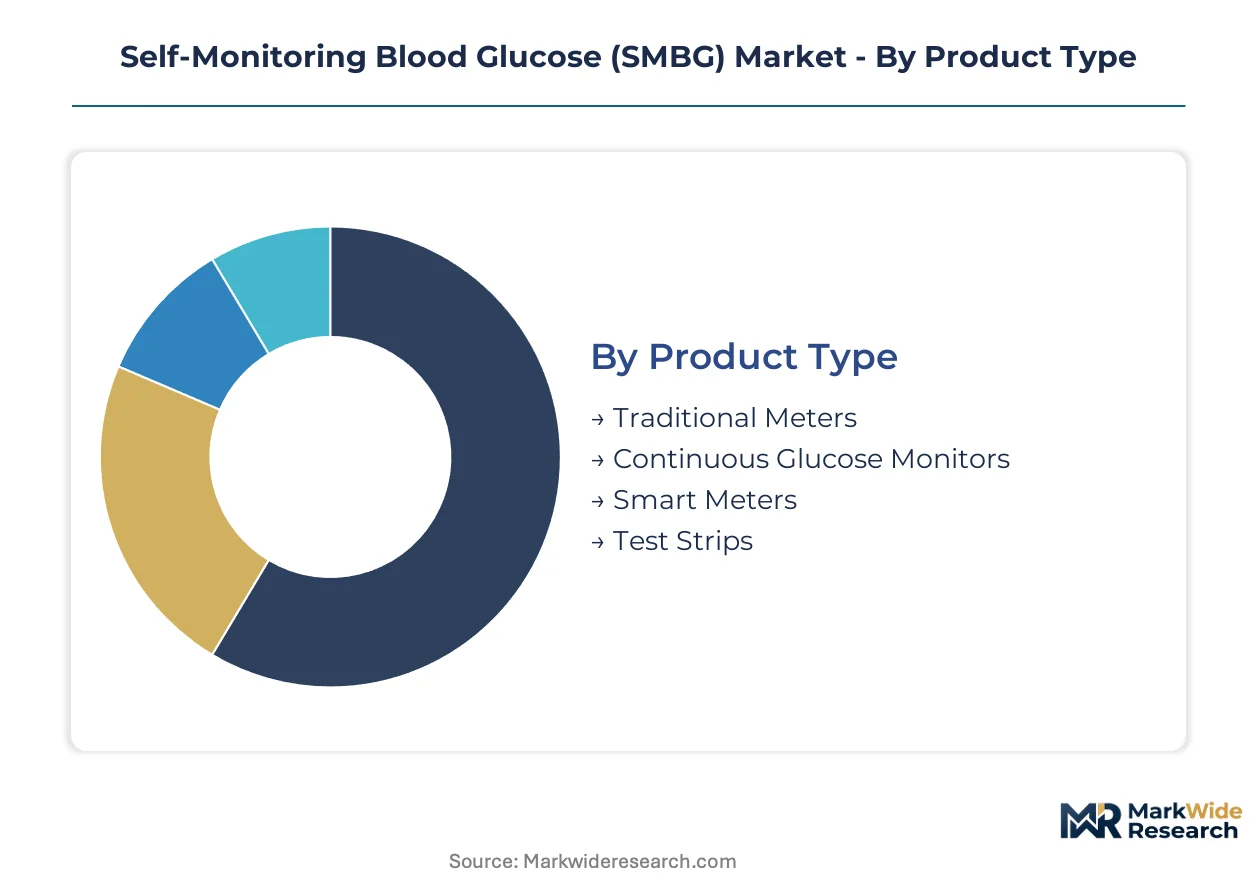
Product architecture in glucose monitoring determines reimbursement eligibility, patient adherence patterns, and manufacturing margin structures. Technology choices across electrochemical, optical, and biosensor platforms shape regulatory pathways and competitive positioning differently.
Product Type:
Cost tier differentiation separates premium sensor-integrated systems from economy strip-dependent models.
- Traditional Meters:Portable electrochemical devices utilizing disposable enzyme-impregnated strips for capillary blood sampling. Demand concentrates in India's tier-2 and tier-3 cities and cash-pay segments across Southeast Asia where CMS-equivalent reimbursement remains absent.
- Continuous Glucose Monitors:Factory-calibrated interstitial fluid sensors with predictive algorithms eliminating fingerstick confirmation. Medicare coverage expansion in the United States and statutory health insurance integration in Germany are accelerating patient migration from legacy meters.
- Smart Meters:Bluetooth-enabled devices with smartphone app connectivity for data logging and caregiver sharing. Compact units serve Japan's aging patient populations requiring remote monitoring support.
- Test Strips:Single-use consumables with glucose oxidase or glucose dehydrogenase chemistry. Volume production anchors in China and India for price-sensitive export markets.
Continuous Glucose Monitors hold installed capacity. Smart Meters is rotating up the share rankings.
Delivery Mode:
Application context determines accuracy requirements, calibration burden, and patient compliance thresholds.
- Blood Testing:Fingerstick capillary sampling with enzymatic strip reaction, the reference standard for insulin dosing decisions. Intensive Type 1 patients in Germany and the United States maintain dual-system deployment alongside CGM for calibration verification.
- Non-Invasive Devices:Optical spectroscopy and transdermal approaches eliminating consumables and pain points. FDA 510(k) clearance timelines and ISO 15197 accuracy thresholds remain unmet by commercial systems.
- Urine Testing:Semi-quantitative glucose detection for screening and gestational diabetes monitoring. Limited clinical utility for precise glycemic management restricts deployment to resource-constrained settings.
- Wearable Technologies:Skin-adhesive patches with factory-calibrated sensors enabling 14-day continuous wear. Employer wellness platforms in the United States are adopting subscription models for pre-diabetic employee populations.
Blood Testing maintains procedure volume leadership. Wearable Technologies is climbing the fastest among emerging modalities.
End User:
Customer type dictates purchasing authority, reimbursement access, and device complexity tolerance.
- Diabetes Patients:Insulin-dependent and non-insulin-dependent individuals performing self-monitoring for medication adjustment and lifestyle optimization. Type 1 populations in Japan and Germany demonstrate highest CGM adoption rates.
- Healthcare Providers:Endocrinology clinics and hospital diabetes centers utilizing professional-grade meters for point-of-care testing. EHR integration requirements under HL7 FHIR standards complicate procurement decisions.
- Home Users:Family caregivers managing elderly patients with Type 2 diabetes or cognitive impairment. Connected devices with remote data sharing address caregiver accessibility needs in aging societies.
- Pharmacies:Retail distribution channels for over-the-counter meter and strip sales. Direct-to-consumer subscription models are displacing pharmacy-based replenishment among commercially insured US patients.
Diabetes Patients command volume concentration. Healthcare Providers is gaining share fastest through institutional procurement consolidation.
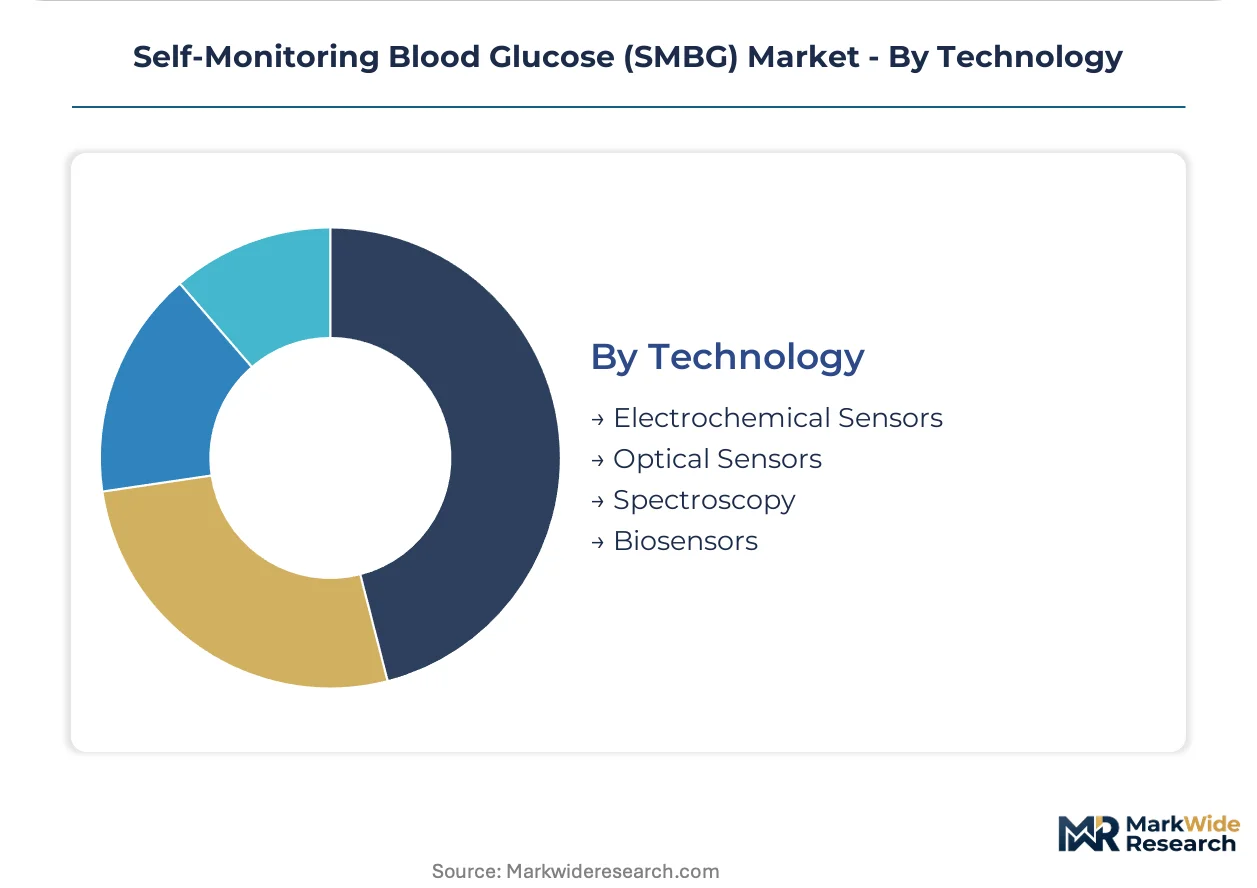
Technology:
Maturity curves separate commercially validated electrochemical platforms from developmental optical approaches.
- Electrochemical Sensors:Amperometric detection of hydrogen peroxide generated by glucose oxidase catalysis. Platinum electrode cost volatility constrains margin stability for strip manufacturers.
- Optical Sensors:Near-infrared spectroscopy and photonic crystal approaches for non-invasive glucose quantification. Accuracy limitations under ISO 15197 MARD thresholds delay regulatory clearance.
- Spectroscopy:Raman and mid-infrared absorption techniques for transdermal glucose measurement. Academic and venture-backed development programs dominate with limited commercial deployment.
- Biosensors:Enzyme-stabilized hydrogel matrices with extended functional lifetimes for CGM applications. Biocompatibility engineering talent scarcity prolongs development cycles for next-generation formulations.
Electrochemical Sensors holds installed manufacturing base. Biosensors is rotating up the share rankings through CGM platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States and Germany favor sensor-integrated continuous monitoring platforms with broad reimbursement coverage, while India and Southeast Asia remain anchored to strip-based systems due to price sensitivity and limited insurance penetration.
United States
Medicare coverage expansion for therapeutic continuous glucose monitors removes cost barriers for Type 1 and intensive Type 2 patients. FDA premarket review under 21 CFR 862.1345 shapes product development timelines for domestic manufacturers. The Boston-Cambridge corridor concentrates biosensor R&D activity, with venture-backed startups advancing optical spectroscopy approaches toward clinical validation.
Germany
Statutory health insurance integration of continuous glucose monitors accelerates patient migration from legacy meter systems. EU Medical Device Regulation imposes stricter clinical evidence requirements than previous CE-marking thresholds. The Baden-Württemberg industrial cluster hosts precision electrochemical sensor fabrication facilities serving both domestic and export markets.
Japan
Aging demographics drive demand for connected, caregiver-accessible monitoring systems among patients over 65. PMDA quality management standards filter out smaller competitors through extended validation timelines. The Kanto region around Tokyo anchors domestic manufacturing of compact Bluetooth-enabled smart meters for home-use segments.
India
Tier-2 and tier-3 cities present volume potential for cost-optimized strip and meter bundles in underpenetrated outpatient diabetes management. CDSCO medical device registration requirements are harmonizing with international standards to streamline market access. Manufacturing concentrates in Gujarat and Maharashtra, where domestic producers achieve scale in electrochemical strip production for price-sensitive export markets.
China
Domestic demand for continuous glucose monitors expands among commercially insured urban populations. NMPA medical device approval pathways are tightening performance benchmarks to match international accuracy standards. The Yangtze River Delta region, particularly Shanghai and surrounding provinces, hosts the principal concentration of biosensor wafer fabrication and enzymatic reagent production capacity.
Self-Monitoring Blood Glucose (SMBG) Market Competitive Landscape
Capability concentration sits with vertically integrated biosensor specialists; scale advantage sits with diversified diagnostics conglomerates. The market exhibits tiered structure with premium sensor-integrated platforms, mid-range connected meters, and economy strip-dependent systems occupying distinct competitive positions. Dominant archetypes include integrated device-consumable platforms, pure-play sensor technology licensors, and regional distribution-scale operators. Competitive moves center on backward integration into biosensor manufacturing and geographic expansion through distributor acquisition.
Among Swiss-based diagnostics conglomerates, F. Hoffmann-La Roche Ltd. exemplifies the integrated platform archetype spanning laboratory and home-use segments. Abbott Laboratories and Ascensia Diabetes Care Holdings AG represent contrasting approaches to sensor-integrated versus traditional meter-plus-strip models. Sinocare anchors the Asia-Pacific volume tier through cost-optimized production positioning.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Abbott Laboratories |
| Ascensia Diabetes Care Holdings AG |
| LifeScan IP Holdings |
| Sinocare |
| PHC Holdings Corporation |
| ARKRAY |
| B. Braun Melsungen AG |
| Trividia Health |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta biosensor fabrication cluster anchors global electrochemical strip capacity, with wafer throughput scaling directly determining pricing power across tiered product lines. Factory-calibrated continuous glucose monitors command premium positioning through Medicare reimbursement parity, while cost-optimized meter-plus-strip bundles face compression from platinum electrode volatility and Chinese export pricing.
Pricing Analysis
Long-term offtake contracts between OEM manufacturers and hospital procurement organizations dominate institutional channels, insulating premium sensor-integrated platforms from spot-market volatility. Three-tier pricing structure across premium, standard, and economy levels separates factory-calibrated CGM systems with predictive algorithms from Bluetooth-enabled smart meters and basic electrochemical strip models. Pricing pressure stems from precious metal cost swings in biosensor electrodes and CMS reimbursement rate compression on consumable supplies. Cash-pay patients in India's tier-2 cities exhibit highest price sensitivity, while commercially insured populations in Germany and the United States demonstrate lowest elasticity due to statutory coverage integration.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electrochemical sensor manufacturers with cross-border component flows. Manufacturing concentrates in China, India, and Germany for enzymatic reagent production, precision electrode fabrication, and final device assembly respectively. Raw material dependencies center on platinum and palladium for amperometric detection, glucose oxidase enzyme formulations, and medical-grade hydrogel matrices. Single-source vulnerability in specialized biosensor wafer fabrication feeds from concentrated cleanroom capacity in the Yangtze River Delta. Distribution runs through hospital GPO contracts, pharmacy retail channels, and direct-to-consumer subscription platforms with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Self-Monitoring Blood Glucose market is entering a cyclical recovery phase driven by Medicare reimbursement expansion for therapeutic continuous glucose monitors, resetting demand baselines after years of strip-market stagnation.
For Market Incumbents: Pre-empt optical spectroscopy disruption by accelerating factory-calibrated CGM algorithm development and securing backward integration into biosensor wafer fabrication. Abbott Laboratories and Roche must defend sensor-integrated platform margins against emerging non-invasive entrants through FDA 510(k) clearance accumulation and statutory health insurance lock-in across Germany and Japan. Channel control through direct-to-consumer subscription models represents the critical lever for consumable revenue retention. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 and tier-3 cities with cost-optimized electrochemical strip bundles before domestic producers achieve full scale. Smartphone-integrated biosensors with Bluetooth Low Energy connectivity offer the most penetrable white-space target, enabling app-based analytics subscription models that bypass pharmacy distribution entirely. Employer wellness platforms in the United States provide a cash-pay entry vector for pre-diabetic populations outside traditional reimbursement pathways. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated device-consumable platforms with captive biosensor manufacturing and established regulatory dossiers. The five-to-ten-year viability window rewards acquisition targets possessing EU MDR compliance infrastructure and Medicare coverage determination track records. The signal to watch is CMS National Coverage Decision timing on non-invasive glucose monitoring, which would trigger immediate sensor-integrated platform repricing and consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Medicare coverage determination for therapeutic CGM removes out-of-pocket barriers for Type 1 patients. |
| CE Marking Pathway | EU MDR compliance creates first-mover advantage for manufacturers with post-market surveillance infrastructure. |
| Hospital System Partnership | HL7 FHIR integration with EHR systems secures institutional procurement preference for connected platforms. |
| Software Companion Development | App-based predictive algorithms enable factory calibration elimination and direct-to-consumer subscription models. |
| Backward Integration | In-house biosensor wafer fabrication insulates margins from platinum electrode cost volatility and supply disruption. |
Research Methodology
Operator-level perspectives from endocrinology clinic directors, hospital GPO contract managers, biomedical engineers, and diabetes device regulatory affairs leads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, CMS National Coverage Determination records, EU MDR notified body submissions, and PMDA quality management audit reports. Bottom-up patient population modeling triangulated against top-down manufacturer shipment data and statutory health insurance reimbursement claims.
Scenario-bracketing around reimbursement expansion velocity and optical spectroscopy commercialization timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture tier, delivery mode, end-user purchasing authority, and technology maturity curve. CAGRs derived from installed base migration rates and consumable replenishment frequency by patient type. Industry-specific inputs incorporated platinum futures pricing volatility and ISO 15197 accuracy threshold evolution.
Sensitivities concentrate around CMS coverage determination timing, EU MDR transition completion rates, and non-invasive sensor accuracy breakthroughs. Forecasts reflect assumptions on patient migration from strip-based to sensor-integrated platforms and statutory insurance integration patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Implantable Insulin Pump Market
Diabetes Care
Spain Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Hyperglycemia Treatment Market
Diabetes Care
Diabetic Shoes Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Saudi Arabia Diabetes Care Devices Market
Diabetes Care
Global Needle Free Diabetes Care Market