
 Digital Diabetes Market | 2026-2036
Digital Diabetes Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Diabetes Market Intelligence
The shift toward real-time, closed-loop systems is rotating the market toward integrated care platforms. Medtronic leads in combining insulin pumps with CGM technology into automated delivery systems. Dexcom, Inc. specializes in high-accuracy standalone CGM sensors for a broad patient base. Abbott Laboratories competes through its widely adopted FreeStyle Libre flash glucose monitoring portfolio, emphasizing user convenience.
Digital diabetes management involves the use of connected electronic devices to monitor and treat diabetes. These systems integrate hardware, such as sensors that track interstitial glucose levels, with software for data analysis and insulin dosing calculations. Continuous Glucose Monitors and mobile apps constitute the largest product segments, providing the core data collection and user interface functions. The home healthcare setting is the primary end-user environment, facilitating remote patient monitoring and self-management.
Regulatory oversight from bodies like the US FDA and compliance with the EU's Medical Device Regulation (MDR) are critical. These frameworks govern device accuracy, cybersecurity standards, and the clinical validation required for market approval. Interoperability between different devices and software platforms is emerging as a key differentiator. Success will depend on the ability to create seamless ecosystems that integrate data from multiple sources for comprehensive patient care.
Market Dynamics
The convergence of continuous glucose monitoring with automated insulin delivery systems, enabled by interoperability standards, is the central force shaping the market. This shift moves the focus from discrete devices to integrated, closed-loop therapeutic ecosystems that automate patient care and data analysis.
Growth Catalysts
- Favorable Regulatory Pathways:The US FDA's iCGM designation and the EU's MDR framework streamline the approval process for interoperable devices, encouraging new product introductions from a wider range of manufacturers.
- Home Healthcare Expansion:Increased reimbursement for remote patient monitoring tools in countries like the United States and Germany drives adoption in the home care setting, facilitating self-management.
- Sensor Technology Advances:Improvements in the accuracy, longevity, and miniaturization of CGM sensors enhance user experience and adherence, expanding the addressable patient population for these systems.
Market Restraints
- High Upfront Costs:The significant initial expense for insulin pumps and CGM systems remains a major adoption barrier for patients in markets without comprehensive insurance coverage or public reimbursement.
- Data Security Compliance:Adherence to strict data privacy regulations like HIPAA in the US and GDPR in Europe adds considerable complexity and cost to software development and data management.
- Interoperability Gaps:The absence of a universal data standard across all device manufacturers creates vendor lock-in, complicates the integration of different system components, and limits patient choice.
Strategic Opportunities
- Emerging Market Penetration:Untapped patient populations in countries with high diabetes prevalence, such as India and Brazil, represent significant expansion opportunities for affordable digital health solutions.
- Predictive Analytics Integration:Incorporating AI and machine learning into management apps can provide predictive alerts for glycemic events, shifting patient care from a reactive to a proactive model.
- Expansion into Pre-Diabetes:Digital tools are being adapted for wellness and pre-diabetes management, addressing a larger population segment focused on prevention rather than chronic disease treatment.
Industry Challenges
- Legacy System Integration:Connecting new digital platforms with entrenched hospital electronic health record (EHR) systems presents significant technical and workflow integration challenges for healthcare providers.
- Complex Approval Pathways:Navigating lengthy and stringent clinical validation processes under the US FDA and EU MDR frameworks delays market access for innovative devices and software updates.
- Cybersecurity Talent Gaps:A shortage of software engineers skilled in medical device security protocols constrains the development of secure, connected platforms, increasing vulnerability risks across the ecosystem.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Diabetes Market |
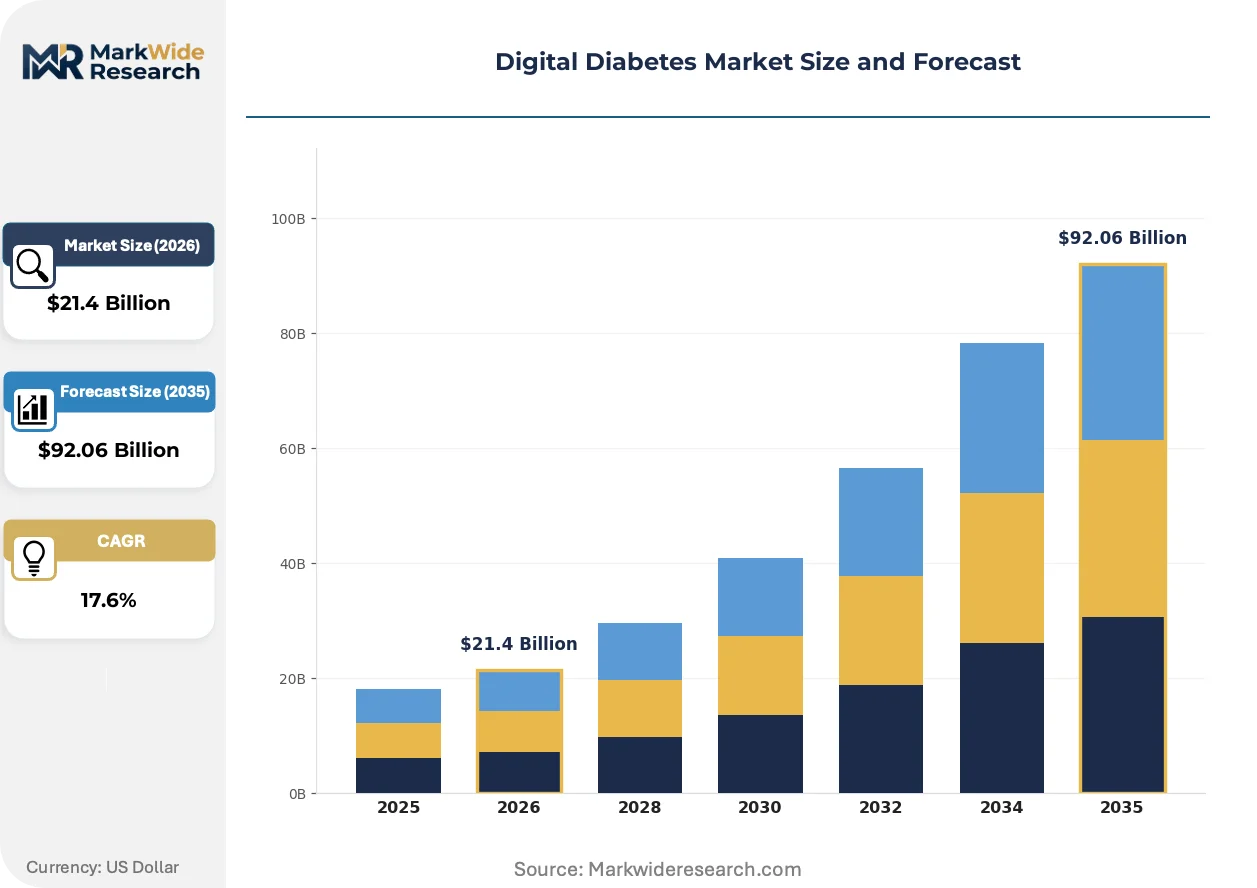
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $92.06 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Glucose Monitors, Insulin Pumps, Mobile Apps, Digital Therapeutics, Smart Pens Technology: Cloud-Based Platforms, AI Algorithms, Bluetooth Connectivity, Data Analytics, Sensor Fusion Application: Blood Glucose Tracking, Insulin Management, Diet Planning, Remote Patient Monitoring, Behavior Modification End User: Hospitals, Diabetes Care Centers, Home Healthcare, Research Institutions, Telemedicine Providers |
| Companies Covered | Abbott Laboratories, Medtronic, Dexcom, Inc., F. Hoffmann-La Roche Ltd., Insulet Corporation, Bayer AG, LifeScan, Inc., Ascensia Diabetes Care Holdings AG, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Diabetes Market Strategic Shifts & Innovations
The evolution of digital diabetes care is defined by a move toward automated, personalized interventions. Software and data analytics are transforming standalone monitoring devices into intelligent systems that can predict and help manage glycemic control with minimal user input, enhancing patient autonomy and clinical outcomes.
Non-invasive glucose monitoring technologies are emerging, using methods like optical spectroscopy to measure glucose levels without penetrating the skin. Patients seeking to eliminate the pain and inconvenience of traditional testing are driving early interest and investment in these platforms. This development is supplanting the need for frequent fingerstick calibrations and even some patch-based sensors for daily management.
Heightened regulatory focus on medical device cybersecurity, particularly from the US FDA, is a defining shift. This forces manufacturers to embed robust security protocols and threat modeling throughout the product lifecycle, from design to post-market surveillance. Automated insulin delivery and smart pen segments are most affected due to the direct link between software security and patient safety.
A transition from device-centric transactions toward subscription platforms that bundle hardware, software, and coaching is gaining traction. This model disrupts traditional durable medical equipment channels, enabling direct-to-consumer relationships and partnerships with health insurers. The shift is most pronounced in the United States for managing type 2 diabetes and promoting wellness.
Digital Diabetes Market Segmentation
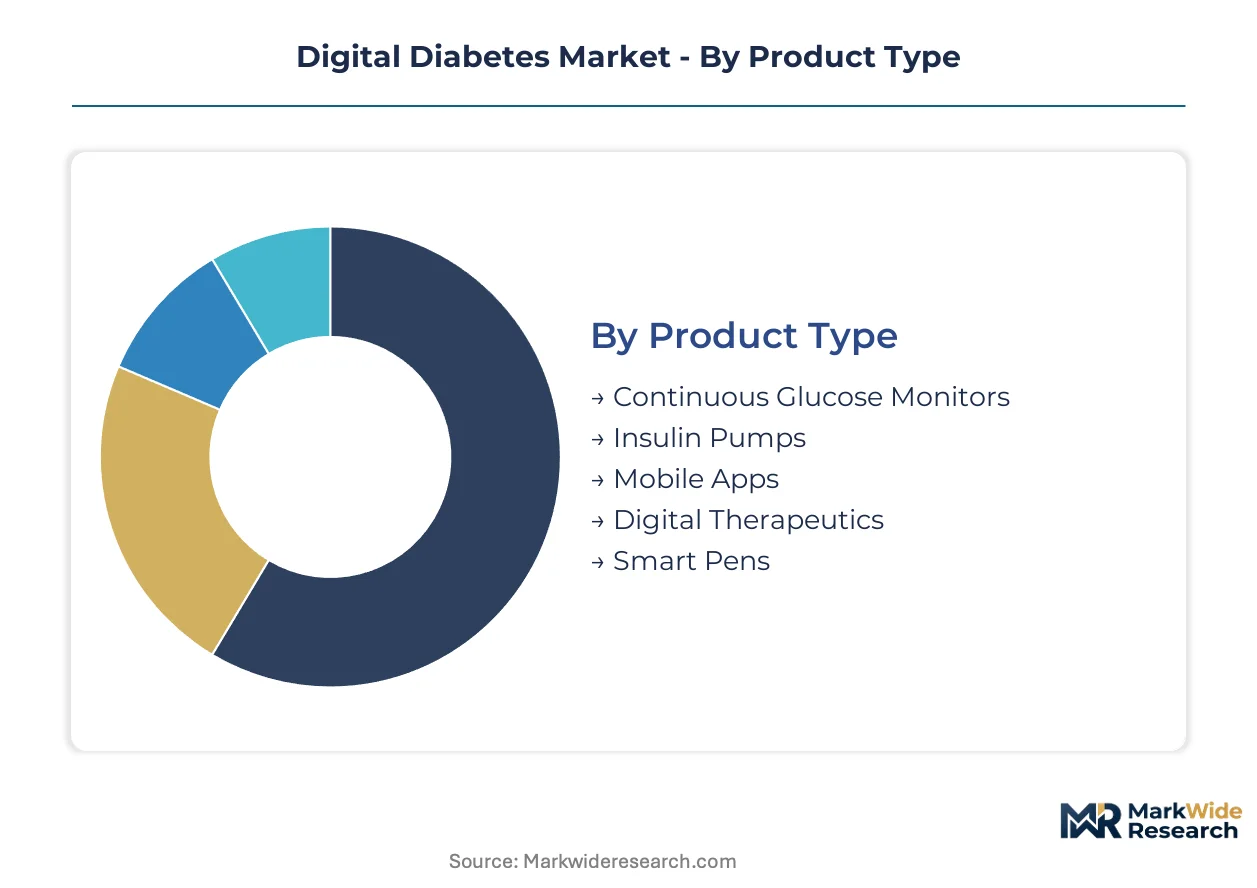
Understanding the varied components of the digital diabetes market reveals distinct value chains and user needs. Product types, underlying technologies, diverse applications, and end-user environments define the market's operational structure. This granular breakdown helps identify specific growth pockets and areas for technological differentiation within diabetes care.
Product Type:
Margin pools within product type segmentation often concentrate on proprietary sensor technologies and integrated software platforms.
- Continuous Glucose Monitors:These devices measure interstitial glucose levels continuously, providing real-time data to users. Demand concentrates heavily in the United States, driven by high patient awareness and increasing reimbursement for advanced monitoring.
- Insulin Pumps:Automated devices deliver insulin subcutaneously, often integrating with CGM data for closed-loop systems. Demand is rising in developed economies where advanced diabetes management tools are increasingly covered by insurance.
- Mobile Apps:Software applications for smartphones and tablets facilitate data analysis, insulin dosing calculations, and personalized insights. Demand for these applications is strong in home healthcare settings, enhancing remote patient monitoring and self-management capabilities.
- Digital Therapeutics:Software-based interventions provide evidence-based therapeutic care for diabetes management.
- Smart Pens:Connected insulin pens record dosing data, syncing with apps for improved adherence tracking.
Continuous Glucose Monitors hold installed capacity. Mobile Apps are rotating up the share rankings.
Technology:
The technological underpinnings dictate the cost structure and scalability of digital diabetes solutions.
- Cloud-Based Platforms:These systems enable secure data storage, remote access, and interoperability across various devices. Demand is high for these scalable solutions in telemedicine providers, supporting comprehensive patient data management and accessibility.
- AI Algorithms:Artificial intelligence and machine learning models analyze glucose data to predict glycemic events and personalize treatment recommendations. Demand for AI integration is rising within digital therapeutics, shifting care towards proactive management.
- Bluetooth Connectivity:Wireless technology facilitates seamless data transfer between sensors, pumps, and mobile devices.
- Data Analytics:Tools and processes transform raw glucose data into actionable insights for patients and clinicians.
- Sensor Fusion:Combining data from multiple sensor types enhances accuracy and reliability for complex monitoring systems.
Sensor Fusion technology offers enhanced data reliability. Cloud-Based Platforms are expanding most quickly.
Application:
Application segmentation reveals distinct user engagement patterns and clinical utility.
- Blood Glucose Tracking:Core functionality involves continuous or intermittent monitoring of glucose levels and historical data logging. Demand for this foundational application remains strong across all end-user segments, particularly in home healthcare for self-management.
- Remote Patient Monitoring:Tools enable healthcare providers to remotely track patient data, adjust treatment plans, and intervene proactively. Demand is accelerating in countries with favorable reimbursement for remote care, such as the United States and Germany.
- Insulin Management:Features assist in calculating insulin dosages and tracking administration schedules.
- Diet Planning:Applications provide nutritional guidance and track food intake to support glycemic control.
- Behavior Modification:Digital programs encourage lifestyle changes through coaching and educational content.
Insulin Management applications provide critical daily support. Remote Patient Monitoring is experiencing significant uptake.
End User:
End-user segments reflect diverse operational requirements and adoption rates for digital diabetes solutions.
- Home Healthcare:This segment involves patients managing diabetes independently with digital tools in their residences. Demand is heavily concentrated here due to increased reimbursement for remote monitoring and the convenience of self-management solutions.
- Hospitals:Healthcare facilities utilize digital platforms for inpatient glucose management, data integration, and patient education. Demand in hospitals focuses on interoperability with existing EHR systems and robust cybersecurity protocols.
- Diabetes Care Centers:Specialized clinics offer comprehensive diabetes education and technology support.
- Research Institutions:Academic and clinical research leverages digital tools for data collection and clinical trials.
- Telemedicine Providers:Virtual care platforms integrate digital diabetes tools for remote consultations and chronic disease management.
Research Institutions drive innovation in new digital tools. Home Healthcare is seeing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The supply-side for digital diabetes solutions heavily concentrates in developed economies, particularly where advanced medical technology ecosystems thrive. These regions benefit from established healthcare infrastructure and robust regulatory frameworks. Demand drivers often intersect with technological innovation and patient access to specialized care.
United States
Patient awareness and comprehensive insurance coverage drive significant demand for digital diabetes tools in the United States. The US FDA's iCGM designation streamlines approval for interoperable devices, fostering market growth. California's Silicon Valley and Boston's biotech corridor are hubs for digital health innovation and startup activity.
Germany
Increased reimbursement for remote patient monitoring tools fuels the adoption of digital diabetes solutions in Germany. The EU's Medical Device Regulation (MDR) ensures high standards for device accuracy and clinical validation. Munich and Berlin host significant medical technology clusters, attracting investment in integrated care platforms.
Japan
Japan's aging population and high technology adoption rates create strong demand for advanced digital diabetes management systems. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees stringent approval processes for new medical devices. Tokyo's extensive healthcare network supports the integration of smart pens and connected glucose monitors.
India
Untapped patient populations and a rising prevalence of diabetes present substantial expansion opportunities for affordable digital health solutions in India. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, influencing market entry for new technologies. Bengaluru, known as India's Silicon Valley, is a growing center for digital health startups developing localized solutions.
Digital Diabetes Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the digital diabetes market. The market exhibits a tiered structure, with established medical device giants alongside agile software-focused innovators. Strategic archetypes include integrated solution providers, specialized sensor manufacturers, and digital therapeutics developers. Companies frequently engage in strategic partnerships and portfolio diversification to enhance their market reach.
Integrated solution providers, such as Medtronic, exemplify the convergence of automated insulin delivery systems with continuous glucose monitoring, offering comprehensive closed-loop solutions. Dexcom, Inc. anchors the specialized sensor manufacturing segment, focusing on high-accuracy standalone CGM devices that cater to a broad patient population seeking precise glucose data. Abbott Laboratories occupies a significant position with its widely adopted FreeStyle Libre flash glucose monitoring portfolio, emphasizing user convenience and accessibility for a broad patient base through its unique flash glucose monitoring technology.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Dexcom, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Insulet Corporation |
| Bayer AG |
| LifeScan, Inc. |
| Ascensia Diabetes Care Holdings AG |
| B. Braun Melsungen AG |
| Others |
Cost & Logistics Intelligence
The US FDA's iCGM designation and the EU's MDR framework gate device qualification, simultaneously influencing supply capabilities and price differentiation for digital diabetes solutions. These regulatory hurdles ensure device accuracy and cybersecurity, directly impacting market entry and perceived value. The market's pricing structure reflects these stringent requirements for product validation.
Pricing Analysis
The EU's Medical Device Regulation dictates the pricing tier structure for advanced digital diabetes devices, emphasizing compliance and clinical validation. Pricing predominantly follows a hybrid model, combining subscription platforms for software and coaching with per-unit transactional sales for hardware like CGMs and insulin pumps. Price differentiation arises from device accuracy, brand premium for established players, and bundled after-sales service. Cost compression in basic mobile app segments is intensifying due to increasing competition and initiatives promoting broader accessibility. Patients without comprehensive insurance or public reimbursement represent the most price-sensitive segment.
Supply Chain Analysis
Strategic stockpiling of critical components balances against just-in-time manufacturing for digital diabetes solutions. Supply concentration for high-tech components like semiconductor chips and specialized sensors remains in developed economies such as the United States, Germany, and Japan. Raw material dependencies include advanced polymers for device casings and secure cloud infrastructure for data management. Single-source vulnerability for specialized sensor components presents a structural supply chain risk. Distribution occurs through direct-to-consumer subscription models, partnerships with health insurers, and established durable medical equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital diabetes market embodies an early-cycle expansion story, driven by the significant tailwind of home healthcare penetration and remote patient monitoring reimbursement. This momentum offers substantial opportunities for various stakeholders.
For Market Incumbents: Consolidate market share by acquiring niche software developers specializing in AI analytics and digital therapeutics. Deepen the integration of predictive algorithms into existing automated insulin delivery platforms to counter the threat from agile software-focused innovators. Invest in R&D for next-generation non-invasive monitoring technologies to maintain a competitive edge. Secure channel control through strategic partnerships with major health insurers and pharmacy benefit managers.
For New Entrants and Emerging Players: Anchor in underserved patient populations within emerging markets like India and Brazil, focusing on affordable, localized digital health solutions. The pre-diabetes management segment and wellness applications offer highly penetrable white-space targets. A direct-to-consumer subscription model, coupled with partnerships with corporate wellness programs, provides a viable go-to-market angle. Develop interoperable solutions to integrate seamlessly with existing healthcare ecosystems.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger medical device conglomerates seeking to divest non-core digital assets. The market demonstrates significant long-term viability, with substantial growth potential over the next 5-10 years. Acquisition targets should include specialized AI analytics firms, non-invasive sensor startups, and digital therapeutics developers with strong clinical validation. Broad payer coverage for predictive analytics tools serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Combining different devices enhances comprehensive patient data management for Medtronic. |
| Regulatory Approval Pathway | Securing US FDA iCGM designation streamlines market access for new Dexcom devices. |
| Software Companion Development | Enhancing AI-driven analytics improves personalized insights for Abbott Laboratories' users. |
| Geographic Expansion | Targeting untapped patient populations in India drives new market penetration. |
| Reimbursement Strategy | Advocating for broader coverage of digital therapeutics expands patient access in Germany. |
Research Approach
Operator-level perspectives from clinicians, digital health platform developers, medical device engineers, and health insurance executives anchored the qualitative base of this study. Primary interviews with these industry stakeholders were rigorously validated against secondary data. Secondary sources included US FDA filings, EU MDR compliance documents, peer-reviewed medical journal publications, and company financial reports. This approach facilitated comprehensive bottom-up and top-down triangulation.
A sensitivity analysis framework guided the quantitative assessment of market dynamics across the analysis window. Segmentation dimensions modeled included product type, core technology, application area, end-user environment, and regional regulatory environments. Compound annual growth rates were derived from historical trends, projected market dynamics, and anticipated technological advancements. Key industry-specific forecast inputs included diabetes prevalence rates and shifts in remote patient monitoring reimbursement policies.
Material uncertainties — unforeseen technological breakthroughs or major shifts in regulatory approval timelines — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Revision becomes warranted when significant changes in market fundamentals or macro-environmental factors cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Iran Diabetes Care Devices Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
Hyperglycemia Treatment Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
Diabetic Ketoacidosis Treatment Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market