
 Decubitus Ulcer Treatment Products Market | 2026-2036
Decubitus Ulcer Treatment Products Market Size, Share, and Industry Trends Forecast 2026-2036
Decubitus Ulcer Treatment Products Market Outlook
Advanced antimicrobial dressing tiers is rotating demand away from basic gauze across acute and post-acute settings. Mölnlycke Health Care AB leverages its proprietary Safetac adhesive platform to command premium positioning in silicone foam dressings. Smith & Nephew plc anchors its competitive stance through ALLEVYN Life, a multi-layered dressing system designed for exudate management. ConvaTec Group Plc differentiates via AQUACEL foam technology, which integrates hydrofiber layers for prolonged wear time.
Decubitus ulcer treatment products encompass dressings, support surfaces, topical agents, and positioning devices engineered to prevent, manage, and heal pressure injuries caused by sustained tissue ischemia. Foam dressings with vapor-permeable polyurethane membranes maintain moist wound environments while managing moderate-to-heavy exudate loads. Hydrocolloid and alginate dressings capture concentrated margin pools due to their indication for Stage II-IV wounds with necrotic or highly exuding tissue. Hospitals remain the dominant end-user channel, though home care segments are expanding fastest as reimbursement shifts toward outpatient wound management protocols.
The FDA regulates decubitus ulcer dressings as Class II medical devices under 21 CFR 878.4022, requiring substantial equivalence demonstrations for market entry, while the EU Medical Device Regulation (MDR) imposes enhanced clinical evidence standards for wound care products bearing CE marking. Health Canada's Therapeutic Products Directorate aligns with ISO 13485 quality management requirements for pressure ulcer prevention devices distributed domestically. Stakeholders must monitor evolving post-market surveillance obligations under MDR Article 83 and FDA's Safer Technologies Program to anticipate compliance costs and competitive access barriers.
Market Dynamics
Reimbursement compression across acute care settings is forcing product selection toward value-engineered dressings that demonstrate measurable healing velocity, while long-term care operators simultaneously face staffing shortages that elevate demand for extended-wear solutions.
Growth Catalysts
- Germany's statutory long-term care insurance:Mandated pressure ulcer prevention protocols in nursing homes create institutional procurement pull for advanced support surfaces and hydrocolloid dressings.
- Silicone adhesive platforms:Atraumatic removal properties reduce epidermal stripping incidents, expanding indication into fragile skin populations previously excluded from foam dressing therapy.
- EU Medical Device Regulation:Enhanced clinical evidence requirements for CE-marked wound care products filter marginal competitors and consolidate shelf access for substantiated portfolios.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane foam production depends on isocyanate and polyol pricing swings that compress margin predictability for vapor-permeable dressing manufacturers.
- Alginate raw material concentration:Brown seaweed harvesting clusters in cold-water coastal zones, exposing hydrofiber supply to climate-driven harvest variability and geographic sourcing risk.
- Silver antimicrobial regulatory friction:Environmental release concerns trigger ECHA biocidal product review timelines that delay novel silver-hydrogel composite launches.
Strategic Opportunities
- Home care channel expansion:Remote patient monitoring integration enables dressing change adherence tracking, unlocking reimbursement codes for outpatient wound management protocols.
- India's Ayushman Bharat:Public health insurance scale-up creates first-time institutional access to pressure injury prevention devices in tier-2 and tier-3 hospital networks.
- 3D-printed negative pressure interfaces:Customized wound bed conformability converges with disposable pump miniaturization, opening ambulatory surgical center adoption.
Industry Challenges
- Specialized wound care nurse scarcity:Tissue viability certification programs face enrollment bottlenecks that limit bedside implementation of advanced dressing protocols.
- MDR technical documentation burden:Clinical evaluation report preparation for hydrofiber variants consumes 18-24 month regulatory timelines, compressing product refresh cycles.
- Legacy electronic health record integration:Wound photography and measurement tools require API development for seamless documentation within existing hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decubitus Ulcer Treatment Products Market |
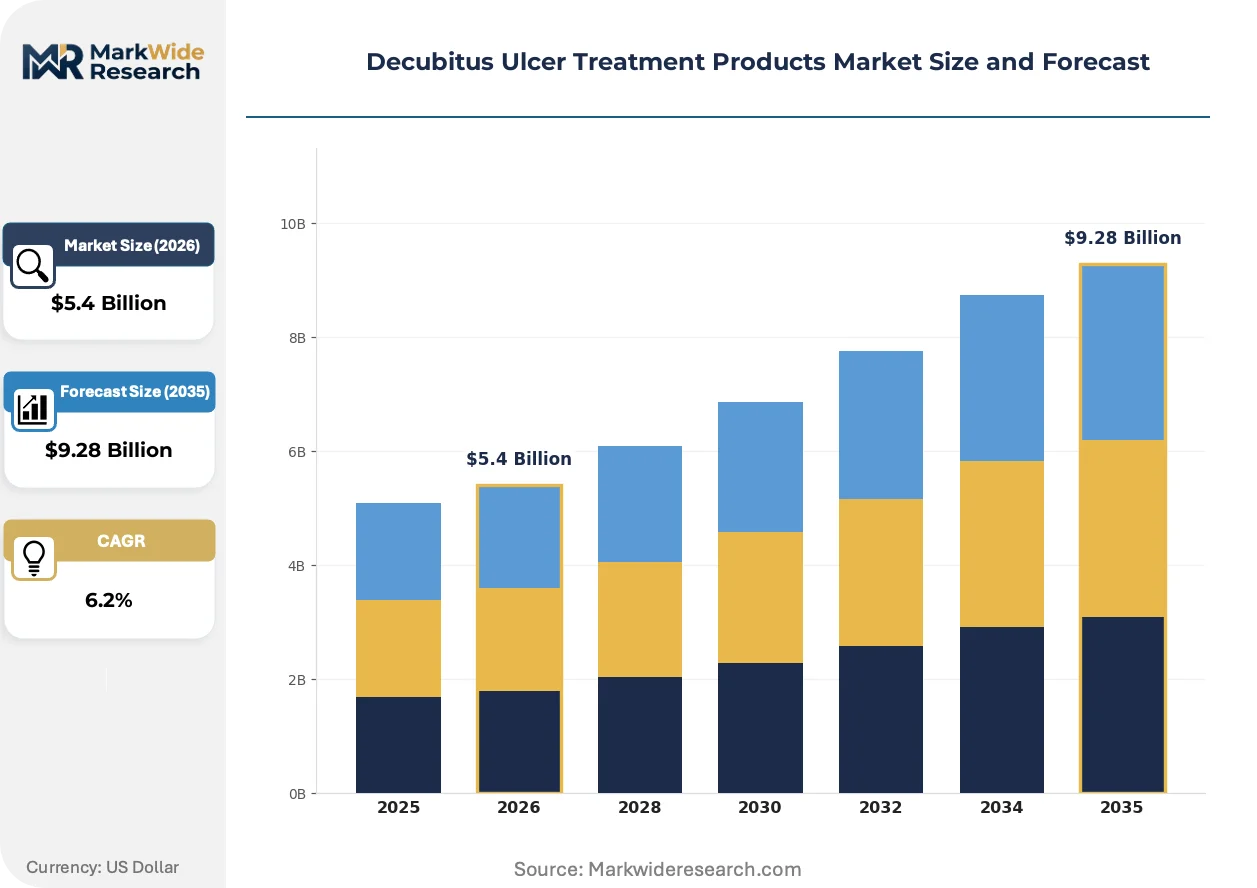
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Mattresses, Cushions, Topical Agents End User: Hospitals, Home Care, Nursing Facilities, Rehabilitation Centers Application: Pressure Relief, Wound Healing, Infection Control, Patient Comfort Material: Foam, Gel, Hydrocolloid, Alginate |
| Companies Covered | Mölnlycke Health Care AB, ConvaTec Group Plc, B. Braun Melsungen AG, Smith & Nephew plc, 3M Company, Coloplast A/S, Hill-Rom Holdings Inc, Invacare Corporation, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decubitus Ulcer Treatment Products Market Strategic Shifts
Smart material integration and regulatory evidence escalation are redefining competitive differentiation beyond basic moisture retention, while channel restructuring accelerates direct-to-facility distribution models.
Antimicrobial dressing technology is bifurcating between ionic silver elution systems and novel non-silver alternatives including polyhexamethylene biguanide and dialkylcarbamoyl chloride chemistries. Long-term care procurement committees now demand antimicrobial efficacy data against biofilm-forming organisms. This technology divergence is bifurcating supplier portfolios into infection-prevention premium tiers versus cost-optimized standard offerings.
The FDA's Safer Technologies Program for medical devices is accelerating 510(k) review timelines for novel hydrocolloid formulations demonstrating substantial equivalence with enhanced biocompatibility profiles. Wound care manufacturers are redirecting clinical study investment toward predicate device comparisons that satisfy streamlined pathway criteria. Foam dressing submissions with integrated temperature-responsive polymers are prioritizing this regulatory route over standard premarket notification tracks.
Hospital supply chain consolidation is compressing vendor panels and mandating standardized formularies across integrated delivery networks. Group purchasing organizations are unbundling dressing procurement from support surface rentals, forcing manufacturers to demonstrate standalone economic value. This behavioral shift is most visible in United States multi-hospital systems where wound care committees now mandate head-to-head healing outcome studies prior to contract renewal.
Decubitus Ulcer Treatment Products Market Segmentation
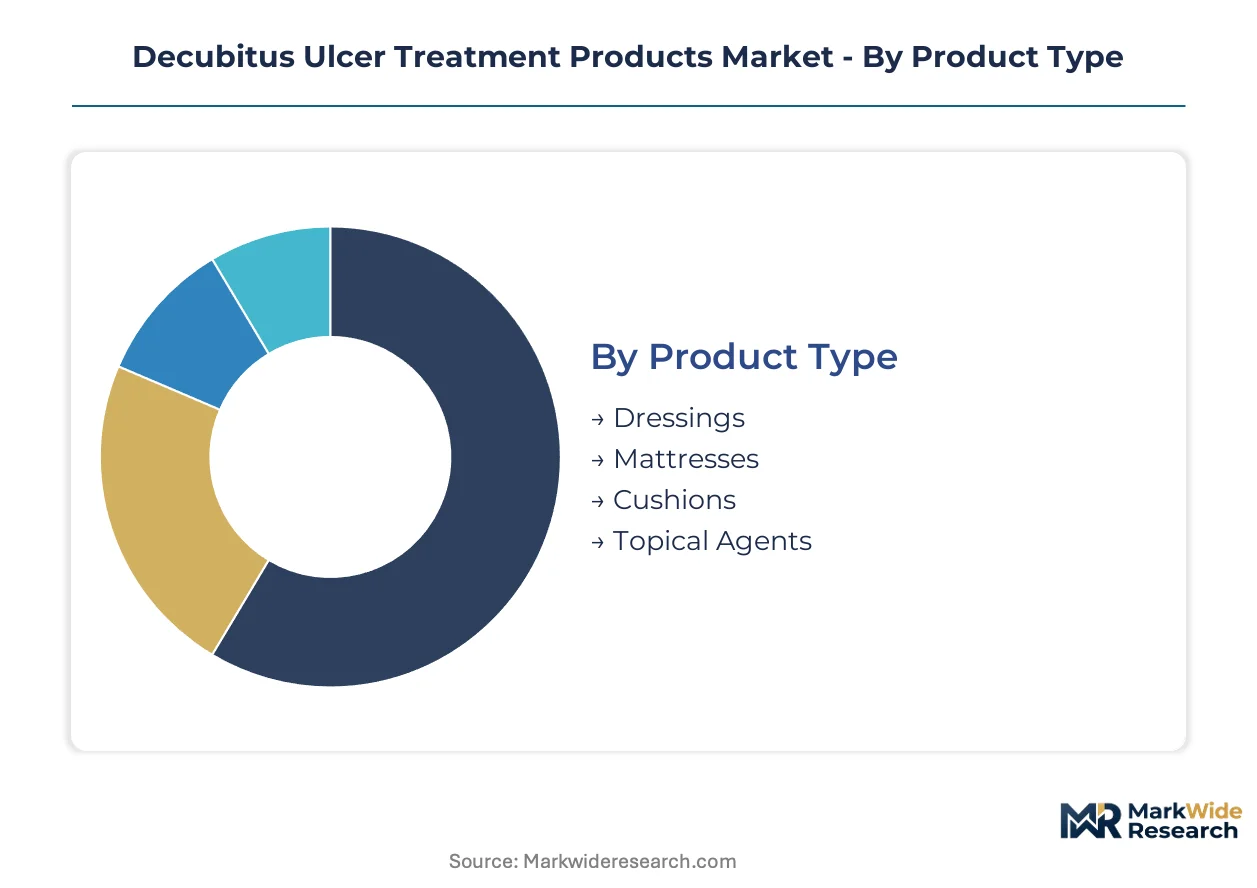
Segmentation in decubitus ulcer treatment products reveals distinct margin architectures across wound care technologies and care delivery settings. Product type and material composition drive pricing power, while end-user channel selection determines volume scalability and reimbursement capture.
Product Type:
Margin pools concentrate in advanced dressing systems where hydrofiber and silicone adhesive technologies command premium positioning against commodity alternatives.
- Dressings:Multi-layered foam and hydrocolloid systems with vapor-permeable polyurethane membranes capture concentrated margin pools through extended wear time and reduced change frequency. Demand concentrates in German nursing homes where statutory long-term care insurance mandates pressure ulcer prevention protocols, institutionalizing procurement of advanced hydrocolloid and alginate variants over basic gauze.
- Mattresses:Dynamic support surfaces with alternating pressure and low-air-loss technologies dominate capital expenditure budgets in acute care settings. Hospital procurement committees in the United States prioritize mattresses with integrated pressure mapping sensors that demonstrate measurable pressure redistribution outcomes for CMS reimbursement justification.
- Cushions:Viscoelastic and air-fluidized seating systems target wheelchair-dependent populations with Stage I-II pressure injury risk. German statutory insurance reimbursement codes drive cushion replacement cycles in outpatient settings.
- Topical Agents:Enzymatic debriders and antimicrobial hydrogels serve adjunctive roles in necrotic tissue management. Silver sulfadiazine and polyhexamethylene biguanide formulations face ECHA biocidal review timelines that constrain novel launch velocity.
Dressings hold installed capacity. Mattresses is rotating up the share rankings.
End User:
Channel selection determines reimbursement pathway complexity and product specification requirements, with institutional buyers demanding outcome documentation that home care segments currently lack.
- Hospitals:Integrated delivery networks in the United States mandate standardized formularies across multi-facility systems, compressing vendor panels to manufacturers with substantiated healing velocity data. Group purchasing organizations unbundle dressing procurement from support surface rentals, forcing standalone economic value demonstration.
- Home Care:Remote patient monitoring integration enables dressing change adherence tracking, unlocking reimbursement codes for outpatient wound management protocols. This channel is expanding most quickly as CMS shifts toward value-based outpatient care models.
- Nursing Facilities:Germany's statutory long-term care insurance creates institutional procurement pull for advanced support surfaces and hydrocolloid dressings through mandated prevention protocols.
- Rehabilitation Centers:Post-acute settings prioritize positioning devices and pressure redistribution cushions for mobility-impaired patients transitioning from hospital discharge.
Hospitals hold installed capacity. Home Care is climbing the fastest in share rankings.
Application:
Functional segmentation aligns with wound severity staging and clinical outcome metrics that determine reimbursement eligibility and product selection criteria.
- Pressure Relief:Proactive support surface technologies target Stage I pressure injury prevention in immobilized patients. German nursing home regulatory compliance drives specification requirements for pressure redistribution performance.
- Wound Healing:Moisture-retentive dressing systems with exudate management capabilities address Stage II-IV wounds. FDA 510(k) clearance pathways for novel hydrocolloid formulations accelerate commercialization timelines for products demonstrating substantial equivalence.
- Infection Control:Antimicrobial dressing tiers bifurcate between ionic silver elution and non-silver alternatives including polyhexamethylene biguanide. Long-term care procurement committees demand efficacy data against biofilm-forming organisms.
- Patient Comfort:Atraumatic silicone adhesive platforms reduce epidermal stripping incidents, expanding indication into fragile skin populations previously excluded from foam dressing therapy.
Wound Healing holds installed capacity. Infection Control is gaining share fastest.
Material:
Raw material chemistry determines manufacturing cost structure, clinical indication breadth, and vulnerability to supply concentration risks in coastal harvesting zones and petrochemical feedstock markets.
- Foam:Vapor-permeable polyurethane membranes with open-cell structures manage moderate-to-heavy exudate loads while maintaining moist wound environments. Petrochemical feedstock volatility in isocyanate and polyol pricing compresses margin predictability for manufacturers.
- Gel:Amorphous hydrogels and sheet gels provide hydration for dry necrotic wounds and autolytic debridement. Demand concentrates in home care settings where patient self-application reduces nursing visit frequency.
- Hydrocolloid:Carboxymethylcellulose and gelatin matrix dressings form cohesive gels upon exudate contact, enabling extended wear time. Brown seaweed harvesting concentration in cold-water coastal zones exposes supply to climate-driven variability.
- Alginate:Calcium-sodium ion exchange fibers derived from brown seaweed provide hemostasis and absorbency for highly exuding wounds. Geographic sourcing risk in harvesting clusters constrains supply security.
Foam holds installed capacity. Hydrocolloid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in decubitus ulcer treatment products reflect divergent reimbursement architectures and regulatory harmonization gaps. The United States and Germany function as net importers of advanced hydrofiber and silicone adhesive technologies, while China and India export commodity foam substrates and basic wound dressings.
United States
Hospital supply chain consolidation compresses vendor panels to manufacturers with FDA 510(k) clearance for multi-layered dressing systems. The FDA's Safer Technologies Program accelerates review timelines for novel hydrocolloid formulations demonstrating enhanced biocompatibility. Greater Boston hosts wound care technology clusters where remote patient monitoring integration enables outpatient reimbursement capture.
Germany
Statutory long-term care insurance mandates pressure ulcer prevention protocols in nursing homes, institutionalizing procurement of advanced support surfaces and alginate dressings. The EU Medical Device Regulation imposes enhanced clinical evidence standards for CE-marked hydrofiber variants. North Rhine-Westphalia concentrates manufacturing capacity for dynamic air-fluidized mattresses serving institutional buyers.
China
NMPA alignment with international quality management standards accelerates domestic manufacturer access to advanced wound care segments. Provincial procurement centralization in Jiangsu and Zhejiang drives volume concentration for basic foam dressings. The Yangtze River Delta hosts polyurethane raw material suppliers feeding regional dressing fabricators.
India
Ayushman Bharat public health insurance scale-up creates first-time institutional demand for pressure injury prevention devices in tier-2 hospital networks. CDSCO regulatory pathways for Class B medical devices streamline market entry for silicone adhesive platforms. Maharashtra and Gujarat concentrate domestic manufacturing of cotton-based wound care substrates for price-sensitive segments.
Japan
PMDA post-market surveillance requirements for antimicrobial dressings extend product lifecycle management obligations. METI industrial policy supports domestic production of advanced hydrocolloid matrices for aging population demand. The Kansai region maintains specialized coating capabilities for vapor-permeable polyurethane membranes.
Decubitus Ulcer Treatment Products Market Competitive Environment
Concentration sits with diversified medical technology conglomerates controlling integrated dressing-to-device portfolios. The vendor base separates into three functional tiers: premium innovators with proprietary adhesive platforms, scale manufacturers optimizing commodity foam production, and regional specialists serving price-sensitive procurement channels. Competitive dynamics center on M&A activity targeting hydrofiber technology assets and strategic partnerships with remote patient monitoring platforms.
Within the premium technology tier, Mölnlycke Health Care AB and ConvaTec Group Plc exemplify archetypes built on proprietary material science differentiation. Smith & Nephew plc occupies a position bridging advanced dressing systems and surgical wound care portfolios. B. Braun Melsungen AG represents the integrated hospital supply model extending from basic gauze through dynamic support surfaces.
| Leading Market Players |
|---|
| Mölnlycke Health Care AB |
| ConvaTec Group Plc |
| B. Braun Melsungen AG |
| Smith & Nephew plc |
| 3M Company |
| Coloplast A/S |
| Hill-Rom Holdings Inc |
| Invacare Corporation |
| Cardinal Health |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance pathways gate both supplier qualification and price differentiation in decubitus ulcer treatment products, compressing margin pools for uncertified manufacturers while enabling premium capture for substantiated hydrofiber and silicone adhesive platforms. German statutory long-term care insurance reimbursement codes institutionalize procurement of CE-marked advanced dressings, creating parallel price ceilings and floors across Atlantic markets.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels, with hydrocolloid and alginate variants commanding spreads based on wear-time certification and antimicrobial efficacy data. Cost compression in standard foam tiers intensifies because group purchasing organizations unbundle dressing procurement from support surface rentals, forcing standalone economic value demonstration. Long-term care operators exhibit highest price sensitivity due to per-diem reimbursement constraints, while integrated delivery networks prioritize healing velocity metrics over unit cost.
Supply Chain Analysis
Just-in-time inventory preferences dominate vapor-permeable polyurethane membrane sourcing, though alginate hydrofiber manufacturers maintain strategic stockpiles of brown seaweed extracts given climate-driven harvest variability. Production draws from Germany, China, and the United States for dynamic support surfaces, with petrochemical feedstock volatility in isocyanate and polyol pricing creating margin unpredictability. Single-source vulnerability concentrates in cold-water coastal harvesting zones for brown seaweed. Distribution runs through group purchasing organizations and direct-to-facility contracts serving hospital systems and nursing homes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The decubitus ulcer treatment products market tracks cyclical recovery patterns tied to hospital capital expenditure cycles, with integrated delivery network consolidation driving procurement standardization waves that favor substantiated portfolios.
For Market Incumbents: Shield proprietary adhesive platform positions through backward integration into polyurethane raw material supply and accelerated FDA Safer Technologies Program submissions for temperature-responsive polymer variants. Mölnlycke Health Care AB's Safetac technology demonstrates how atraumatic removal properties create switching costs that resist commodity substitution.
For New Entrants and Emerging Players: FDA Safer Technologies Program fast-track pathways enable first-mover positioning in silicone foam dressings for fragile skin populations previously excluded from standard therapy. India's Ayushman Bharat tier-2 hospital networks present the most penetrable geography, with CDSCO Class B device streamlined pathways supporting direct institutional sales models bypassing established distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core wound care assets amid portfolio rationalization pressures. Long-term viability over the next decade hinges on remote patient monitoring integration capabilities and reimbursement code capture for outpatient protocols. Watch for CMS value-based care model expansion signals as inflection indicators for home care channel acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Safer Technologies Program Submission | Accelerated 510(k) review timelines compress regulatory barriers for novel hydrocolloid formulations. |
| CE Marking Pathway Investment | MDR Article 83 compliance enables sustained shelf access across German nursing home procurement. |
| Hospital System Partnership | Integrated delivery network formulary inclusion secures multi-facility volume commitments. |
| Software Companion Development | Remote patient monitoring integration unlocks CMS reimbursement codes for outpatient wound management. |
| Reimbursement Strategy | German statutory long-term care insurance code capture institutionalizes prevention protocol procurement. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with wound care clinicians, hospital purchasing committee members, GPO contracts managers, and biomedical engineers; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR technical documentation, and hospital procurement records. Bottom-up demand modeling triangulated with top-down market sizing across product type, end user, application, and material segmentation dimensions.
Across the analysis window, volume and value projections employed CAGRs derived from historical penetration rates and elasticity-adjusted demand curves, with wound severity staging and reimbursement pathway complexity serving as industry-specific forecast inputs. Segmentation modeling captured dressing technology tiers, care delivery setting migration patterns, and raw material chemistry substitution dynamics.
Underlying assumptions cover petrochemical feedstock price stability and MDR compliance timeline adherence, with deviation risk concentrated in alginate supply disruptions from climate-driven seaweed harvest variability. Revision becomes warranted when CMS outpatient reimbursement thresholds or ECHA biocidal review timelines cross material impact thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Wound Cleanser Products Market
Wound Care
France Wound Care Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Global Diabetic Foot Ulcers Market
Wound Care
Alginate Dressing Market
Wound Care
Pressure Bandages Market
Wound Care
Liquid Bandages Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Negative Pressure Wound Therapy Market