
 Global Cardiac Monitoring and Cardiac Rhythm Management Device Market | 2026-2036
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market Foresight
Project finance and hospital leasing arrangements for high-value implantable systems is narrowing the competitive field to vendors with balance-sheet capacity and service infrastructure. Medtronic leverages its integrated manufacturing footprint to sustain long-term supply contracts with major health systems. Abbott Laboratories anchors its position through specialized catheter-based diagnostic platforms that compete on procedural workflow integration.
Cardiac monitoring and cardiac rhythm management devices encompass implantable and external systems that detect, record, and intervene in electrical conduction abnormalities, with specifications including sensing thresholds measured in millivolts, battery longevity exceeding five years for implantable pulse generators, and biocompatible titanium or polymer housings designed for chronic tissue contact. Their primary commercial purpose is to reduce sudden cardiac death incidence and manage chronic arrhythmia burden across acute and ambulatory care settings. Implantable cardioverter defibrillators occupy the dominant value position given high unit costs and replacement cycle predictability, while wearable sensors represent the fastest-expanding technology dimension as home-based atrial fibrillation detection protocols gain clinical acceptance. Cloud-based data analytics concentrates margin pools through recurring software licensing and remote monitoring service fees.
FDA premarket notification and EU MDR conformity assessment frameworks govern device safety and clinical evidence requirements, with FDA breakthrough device designations accelerating pathways for AI-enabled arrhythmia detection algorithms. Japan's PMDA enforces separate clinical trial standards that shape market entry sequencing for non-Japanese manufacturers. Stakeholders must monitor evolving reimbursement codes for remote patient management and wearable diagnostics as these determine adoption velocity across home healthcare services and cardiology clinics.
Market Dynamics
Hospital capital budgeting cycles and FDA premarket approval timelines are compressing vendor planning horizons, forcing manufacturers to synchronize R&D pipelines with institutional procurement calendars and regulatory submission windows.
Growth Catalysts
- Aging Demographics:The United States, Germany, and Japan exhibit expanding patient populations requiring chronic arrhythmia management, with specialty cardiac hospitals expanding electrophysiology capabilities to capture this demand.
- EU MDR Recertification:Stricter conformity assessment frameworks are accelerating consolidation among vendors with robust clinical evidence portfolios, elevating barriers for undercapitalized competitors.
- Cloud-Based Analytics:Remote monitoring service fees and recurring software licensing are concentrating margin pools, incentivizing hardware manufacturers to develop integrated data platforms.
Market Restraints
- Titanium Supply Concentration:Biocompatible metal sourcing for implantable pulse generator housings depends on limited specialty alloy suppliers, exposing manufacturers to input cost volatility.
- PMDA Clinical Trial Requirements:Japan's separate clinical trial standards extend market entry sequencing for non-Japanese manufacturers, compressing effective patent life in that jurisdiction.
- Reimbursement Code Uncertainty:Evolving remote patient management coding creates adoption velocity risk across home healthcare services and cardiology clinics.
Strategic Opportunities
- Home-Based AF Detection:Wearable sensors represent underpenetrated territory for atrial fibrillation screening protocols outside traditional hospital settings.
- AI-Enabled Algorithms:FDA breakthrough device designations create accelerated pathways for machine learning-based arrhythmia detection, rewarding first-movers with regulatory precedence.
- Project Finance Structures:Hospital leasing arrangements for high-value implantable systems favor vendors with balance-sheet capacity to underwrite long-term service contracts.
Industry Challenges
- Electrophysiologist Workforce Scarcity:Procedure volume growth outpaces specialist training pipeline capacity, constraining catheter-based diagnostic platform utilization.
- Legacy System Integration:New cloud-based data analytics platforms must interface with hospital IT infrastructure spanning multiple vendor ecosystems, extending implementation timelines.
- EU MDR Documentation Burden:Recertification timelines compress planning horizons for technical file updates and clinical evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Monitoring and Cardiac Rhythm Management Device Market |
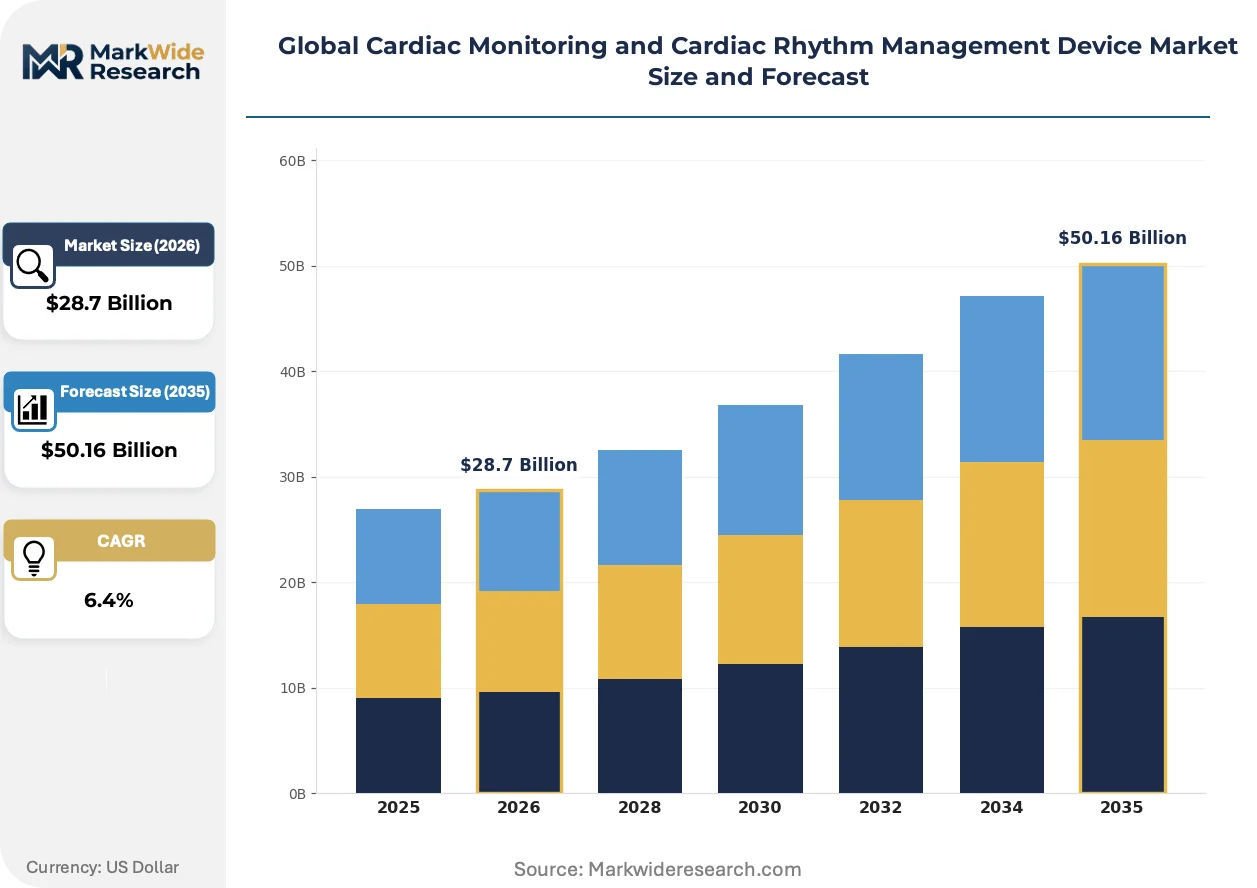
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Cardioverter Defibrillators, Pacemakers, Cardiac Monitors, External Defibrillators, Cardiac Resynchronization Therapy Devices Technology: Wireless Monitoring, Remote Patient Management, Wearable Sensors, Telemetry Systems, Cloud-Based Data Analytics Application: Atrial Fibrillation Detection, Ventricular Tachycardia Management, Heart Failure Monitoring, Post-Surgery Surveillance, Arrhythmia Diagnosis, Stroke Prevention End User: Cardiology Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers, Specialty Cardiac Hospitals, Home Healthcare Services |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, Koninklijke Philips N.V., GE Healthcare, Biotronik, Nihon Kohden Corporation, Stryker, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market Shifts & Advancements
Digital health convergence and miniaturization are redefining device specifications, with sensing thresholds, battery longevity benchmarks, and biocompatible housing materials becoming competitive differentiators.
Leadless pacemaker technology is hybridizing traditional implantable pulse generator functionality with catheter-based delivery systems. Electrophysiology laboratories in Germany and the United States are adopting these systems to reduce procedural complication rates. This convergence is hybridizing the historical separation between implantable device manufacturers and interventional cardiology tool vendors.
EU MDR recertification requirements are extending clinical evidence obligations for legacy implantable cardioverter defibrillator platforms. Manufacturers must generate additional post-market surveillance data or risk certificate suspension. High-value implantable systems face the most severe documentation burdens, with Swissmedic and TGA aligning their frameworks to EU stringency.
Health system procurement departments are consolidating vendor relationships through integrated service contracts spanning devices, remote monitoring, and data analytics. Cardiac rhythm management device purchasing is concentrating among IDNs with dedicated electrophysiology service lines. This pattern is most visible in the United States, where Medicare reimbursement stability supports multi-year capital planning.
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market Segmentation
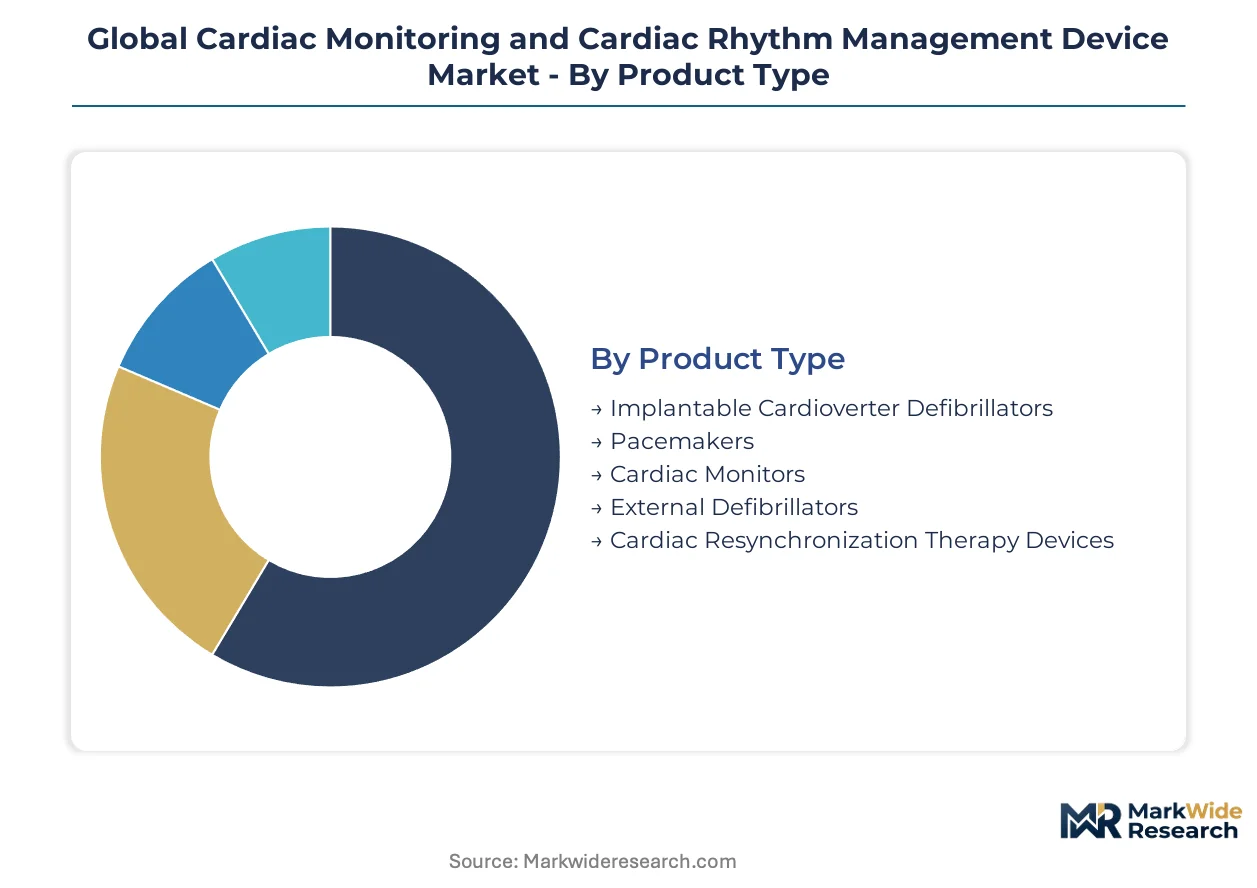
Segmentation in cardiac monitoring and rhythm management reveals distinct replacement cycles and margin profiles across hardware and service layers. Cycle-time differentials between implantable systems and external diagnostics shape capital allocation and R&D prioritization for manufacturers.
Product Type:
Replacement cycles span from five-year battery-driven implantables to disposable external units with sub-annual turnover, creating divergent revenue recognition patterns across the portfolio.
- Implantable Cardioverter Defibrillators:These devices incorporate high-voltage capacitors and lithium-silver vanadium oxide batteries within hermetically sealed titanium housings. Demand concentrates in specialty cardiac hospitals across the United States and Germany, where Medicare stability and statutory health insurance reimbursement support predictable replacement scheduling.
- Pacemakers:Dual-chamber and leadless variants manage bradycardia through programmable pulse generators with sub-millivolt sensing thresholds. Japanese cardiology clinics drive adoption of miniaturized units, though PMDA trial requirements compress effective commercialization windows for imported systems.
- Cardiac Monitors:Insertable loop recorders capture subcutaneous electrograms for cryptogenic stroke evaluation.
- External Defibrillators:Automated and manual variants serve emergency response and public access deployment.
- Cardiac Resynchronization Therapy Devices:Biventricular pacing systems coordinate atrioventricular and interventricular timing for heart failure management.
Implantable Cardioverter Defibrillators dominate installed base value. Wearable-enabled monitoring categories are where expansion concentrates.
Technology:
Margin architecture shifts from hardware shipment economics toward recurring software and data service fees, with connectivity infrastructure determining customer lock-in duration.
- Wireless Monitoring:Bluetooth Low Energy and proprietary radio protocols transmit device diagnostics to home-based receivers. Cardiology clinics in Germany prioritize interoperable standards that reduce IT integration burden across multi-vendor device fleets.
- Cloud-Based Data Analytics:Machine learning pipelines process longitudinal arrhythmia datasets to generate clinical decision support. United States-based integrated delivery networks pay annual licensing fees for predictive analytics that stratify patient rehospitalization risk.
- Remote Patient Management:Automated alert systems flag transmission anomalies for clinical review.
- Wearable Sensors:Photoplethysmography and single-lead ECG patches enable ambulatory atrial fibrillation screening.
- Telemetry Systems:Bedside and centralized monitoring stations serve acute care surveillance.
Cloud-Based Data Analytics captures the steepest expansion trajectory as hardware vendors pivot to service revenue models. Telemetry Systems retain the largest hospital-installed base despite slower growth.
Application:
Clinical utility varies by detection sensitivity requirements and intervention urgency, with stroke prevention protocols creating the most expansive addressable patient population.
- Atrial Fibrillation Detection:Algorithms discriminate fibrillatory from organized atrial activity using R-R interval irregularity and P-wave absence criteria. Home healthcare services in the United States deploy wearable patches for post-discharge monitoring, reimbursed under evolving remote patient management codes.
- Stroke Prevention:Oral anticoagulation decisions depend on AF burden quantification from implantable or external monitors. Japanese stroke centers integrate device-detected episode duration with CHA2DS2-VASc scoring to guide therapy intensity.
- Ventricular Tachycardia Management:Tiered therapy programming balances antitachycardia pacing against high-energy shocks.
- Heart Failure Monitoring:Intrathoracic impedance and heart rate variability trends predict decompensation.
- Post-Surgery Surveillance:Temporary pacing and ischemia detection follow cardiac and non-cardiac procedures.
- Arrhythmia Diagnosis:Symptom-rhythm correlation resolves unexplained syncope or palpitations.
Stroke Prevention commands the broadest clinical indication. Atrial Fibrillation Detection is gaining share fastest as screening protocols extend beyond symptomatic patients.
End User:
Procurement sophistication ranges from centralized IDN contracting to fragmented home health agency purchasing, with facility type determining service bundling expectations.
- Specialty Cardiac Hospitals:Dedicated electrophysiology laboratories perform complex ablation and device implantation procedures. German centers of excellence negotiate multi-year service contracts covering devices, remote monitoring, and clinical training.
- Home Healthcare Services:Skilled nursing and remote monitoring vendors manage post-acute transitions for chronic cardiac patients. United States Medicare Advantage plans increasingly require home-based vital sign transmission as a condition of bundled payment participation.
- Cardiology Clinics:Office-based practices handle device interrogation and medication management.
- Diagnostic Laboratories:Holter and event monitor analysis services support referring physicians.
- Ambulatory Surgical Centers:Same-day implantation and extraction procedures compete with hospital outpatient departments.
Specialty Cardiac Hospitals anchor high-value implantable volume. Home Healthcare Services represent the most rapidly diversifying channel as reimbursement shifts toward site-neutral payment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement stability and statutory health insurance frameworks are concentrating device procurement in markets with predictable payment cycles. The United States, Germany, and Japan anchor installed base expansion, while regulatory divergence shapes vendor entry sequencing.
United States
Specialty cardiac hospitals in Cleveland Clinic and Mayo Clinic networks are expanding electrophysiology laboratories to capture aging demographic demand. FDA breakthrough device designations accelerate pathways for AI-enabled arrhythmia detection algorithms, rewarding first-movers with regulatory precedence. Integrated delivery networks in Texas and Florida are consolidating vendor relationships through multi-year service contracts spanning implantable systems and remote monitoring.
Germany
Statutory health insurance reimbursement supports predictable replacement scheduling for implantable cardioverter defibrillators in centers of excellence across Bavaria and North Rhine-Westphalia. EU MDR recertification requirements extend clinical evidence obligations for legacy platforms, elevating barriers for undercapitalized competitors. Berlin-based procurement consortia are negotiating integrated service contracts that bundle devices with cloud-based data analytics and clinical training.
Japan
Japanese stroke centers in Tokyo and Osaka integrate device-detected atrial fibrillation episode duration with CHA2DS2-VASc scoring to guide oral anticoagulation intensity. PMDA enforces separate clinical trial standards that compress effective patent life for non-Japanese manufacturers entering the market. Miniaturized pacemaker adoption concentrates in Kansai region cardiology clinics, though import-dependent vendors face extended market entry timelines.
China
Domestic manufacturers in Shanghai and Beijing are capturing share in external defibrillator categories as NMPA streamlines approval pathways for Class II devices. Public hospital procurement reforms are shifting toward centralized volume-based purchasing for cardiac rhythm management systems. Yangtze River Delta medical device clusters are developing leadless pacemaker capabilities to reduce dependence on imported implantable pulse generators.
Switzerland
Swissmedic alignment with EU MDR stringency creates parallel documentation burdens for manufacturers maintaining European market access. Geneva and Zurich-based research hospitals are adopting wearable sensor protocols for post-discharge atrial fibrillation monitoring in home healthcare transitions. The country's precision manufacturing ecosystem supports specialty alloy supply for biocompatible titanium housings used in implantable device production.
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base stratifies between diversified medical technology conglomerates with integrated service infrastructure and focused electrophysiology tool manufacturers with catheter-based platform expertise. Three archetypes dominate: balance-sheet-capable systems integrators underwriting hospital leasing arrangements, workflow-optimized diagnostic specialists competing on procedural integration, and emerging wearable sensor vendors capturing home-based detection volume. Consolidation pressure intensifies through EU MDR recertification timelines and health system vendor rationalization.
Among diversified medical technology conglomerates, Medtronic and Boston Scientific Corporation exemplify systems-integrator positioning with manufacturing footprint scale to sustain long-term supply contracts. Abbott Laboratories occupies the diagnostic-specialist archetype through catheter-based platform development. These three anchors represent contrasting strategic postures: integrated manufacturing depth versus procedural workflow optimization versus hybrid device-interventional convergence.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Biotronik |
| Nihon Kohden Corporation |
| Stryker |
| MicroPort Scientific Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in specialty titanium alloy smelting across the United States and Germany drives supplier rationing behavior and amplifies pricing power for implantable pulse generator manufacturers with long-term offtake contracts. This utilization squeeze cascades through biocompatible housing procurement, forcing hardware vendors to absorb input volatility or pass costs to health systems with fixed reimbursement ceilings.
Pricing Analysis
Certification level creates the primary spread across implantable device tiers, with FDA PMA-grade systems commanding substantial premiums over CE-marked equivalents in United States specialty cardiac hospitals. Three-tier pricing structure across premium, standard, and economy levels stratifies by battery longevity and algorithm sophistication, though cost compression in standard-tier pacemakers is intensifying due to Japanese PMDA trial requirements extending development timelines. Integrated delivery networks exhibit lowest price sensitivity through bundled service contracts, while ambulatory surgical centers face acute margin pressure from site-neutral Medicare reimbursement.
Supply Chain Analysis
Extended payment terms from specialty alloy suppliers in Switzerland and Germany now stretch to 180 days for biocompatible titanium orders, compressing working capital for mid-tier manufacturers. Lithium-silver vanadium oxide cell production concentrates in Japan and South Korea, with hermetic sealing equipment sourcing anchored in German precision engineering clusters. Single-source vulnerability around high-voltage capacitor fabrication exposes vendors to tariff exposure from United States-China trade friction. Distribution runs through health system GPO contracts and direct hospital procurement channels with embedded remote monitoring service bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home-based atrial fibrillation detection protocols represent an early-cycle expansion story, with wearable sensor penetration running below 15 percent of addressable cryptogenic stroke patients despite clinical guideline endorsement. This underpenetration creates runway for hardware-software hybrid models before reimbursement codes fully mature.
For Market Incumbents:Entrench through captive supply of lithium-silver vanadium oxide cells via backward integration into Japanese battery manufacturing, while locking electrophysiologist training capacity through exclusive fellowship sponsorships at Cleveland Clinic and Mayo Clinic network sites. Cloud-based analytics competitors threaten margin migration from hardware to recurring service fees, necessitating defensive software licensing acquisitions.
For New Entrants and Emerging Players:Japanese stroke center outpatient clinics offer the most penetrable entry point for wearable patch vendors, as PMDA trial requirements have suppressed import competition and created pricing umbrellas for localizable AF detection algorithms. Partner with Kansai region home healthcare agencies for post-discharge monitoring pilots, leveraging CHA2DS2-VASc integration as the clinical workflow wedge.
For Investors and Strategic Acquirers:Long-term, this sits as a recurring-revenue infrastructure play because remote monitoring service fees concentrate margin pools and create decade-long customer lock-in through data platform switching costs. Target acquisition archetypes include catheter-based diagnostic specialists with FDA breakthrough device designations for AI-enabled arrhythmia detection. Watch for EU MDR certificate suspension announcements as inflection indicators for distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates AI-enabled arrhythmia algorithm pathways, rewarding first-movers with regulatory precedence. |
| Hospital System Partnership | Texas and Florida IDNs consolidate vendor relationships through multi-year service contracts spanning implantables. |
| Software Companion Development | Machine learning pipelines for stroke risk stratification generate annual licensing fees from United States networks. |
| CE Marking Pathway | EU MDR recertification elevates barriers for undercapitalized competitors in German statutory insurance markets. |
| Reimbursement Strategy | Medicare remote patient management code evolution determines adoption velocity across home healthcare services. |
Research Methodology
Initial hypotheses were tested against primary input from electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers, and refined through secondary validation across FDA PMA filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up installed base modeling and top-down epidemiological prevalence estimates were triangulated to cross-check addressable patient population assumptions.
Demand-supply balance framing anchored the forecast framework, with segmentation across implantable versus external hardware, wireless versus cloud-based connectivity, and United States-Germany-Japan regulatory clusters modeled explicitly across the projection horizon. CAGRs were derived from replacement cycle analysis and penetration curve fitting, incorporating PMDA trial timeline delays and EU MDR recertification bottlenecks as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by leadless pacemaker catheter-platform specialists would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
Global Fetal and Neonatal Monitoring Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Home Care Monitoring and Diagnostics Market
Patient Monitoring
Dehydration Monitoring Systems Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market