
 Biodegradable Hemostat Market | 2026-2036
Biodegradable Hemostat Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Hemostat Market Intelligence
Recurring maintenance and software-defined performance calibration is hardening as a discrete revenue layer atop physical hemostat sales. Johnson & Johnson leverages its DePuy Synthes service infrastructure to bundle absorbable sponge products with intraoperative training and compliance auditing. Baxter anchors North American hospital contracts through long-term technical support agreements that lock in oxidized cellulose replenishment schedules. BD competes on the strength of its automated inventory management systems embedded within ambulatory surgical center supply chains.
A biodegradable hemostat is an absorbable medical device engineered from gelatin, oxidized regenerated cellulose, collagen, chitosan, or synthetic polymers such as polylactic acid, designed to accelerate clot formation and dissolve within the body within 24 hours to 8 weeks depending on material composition and porosity. Its primary commercial purpose is to reduce operative blood loss and eliminate the need for mechanical removal in minimally invasive and open surgical procedures. Gelatin-based formats occupy the largest installed base due to their established hemostatic efficacy and compatibility with thrombin adjuncts, while chitosan-based segments are gaining share in trauma and military medicine applications where pH-independent clotting action matters. Powder and sponge forms dominate procedural volume, though film and foam variants are carving out margin-rich niches in laparoscopic and endoscopic delivery channels.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) establish biocompatibility, degradation rate, and pyrogenicity benchmarks that determine which formulations achieve commercial access in the United States and European markets. BIS certification in India and NMPA registration in China impose additional localized testing protocols that shape regional product development priorities. Stakeholders must monitor how evolving biodegradability certification standards and green chemistry procurement mandates in public health systems reshape competitive qualification criteria.
Market Dynamics
Integrated delivery networks in the United States are consolidating purchasing authority for operating room consumables, compressing vendor negotiation cycles and favoring suppliers with automated inventory systems and bundled technical service agreements.
Growth Catalysts
- FDA 510(k) clearance pathway compression:The streamlined premarket notification process for absorbable surgical materials accelerates commercialization timelines for novel biopolymer formulations.
- Minimally invasive surgical volume expansion:Laparoscopic and endoscopic procedure growth drives demand for film and foam hemostat variants optimized for narrow delivery channels.
- Chitosan pH-independent clotting:Military and trauma medicine applications favor this marine-derived polysaccharide where conventional thrombin adjuncts fail in acidic wound environments.
Market Restraints
- Recombinant collagen input cost volatility:Bioreactor-derived matrix proteins face price instability from fermentation substrate supply fluctuations.
- EU MDR technical documentation burden:The Medical Device Regulation's enhanced biocompatibility and degradation rate testing protocols extend certification timelines for European market entry.
- Mechanical hemostasis substitution:Advanced electrocautery and ultrasonic dissection devices reduce reliance on absorbable sponges in certain general surgery applications.
Strategic Opportunities
- Ambulatory surgical center channel penetration:Outpatient procedure migration creates demand for compact, single-use hemostat formats with embedded inventory tracking.
- India BIS biodegradability certification:The Bureau of Indian Standards' emerging green procurement mandates for public hospitals open preferential access for certified biopolymer suppliers.
- Chitosan-gelatin composite convergence:Hybrid matrices combining marine polysaccharide pH stability with gelatin thrombin compatibility address unmet needs in emergency medicine.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with expertise in controlled degradation kinetics command premium compensation, constraining R&D expansion.
- Pyrogenicity testing facility bottlenecks:Limited contract laboratory capacity for endotoxin validation creates queue delays ahead of regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Hemostat Market |
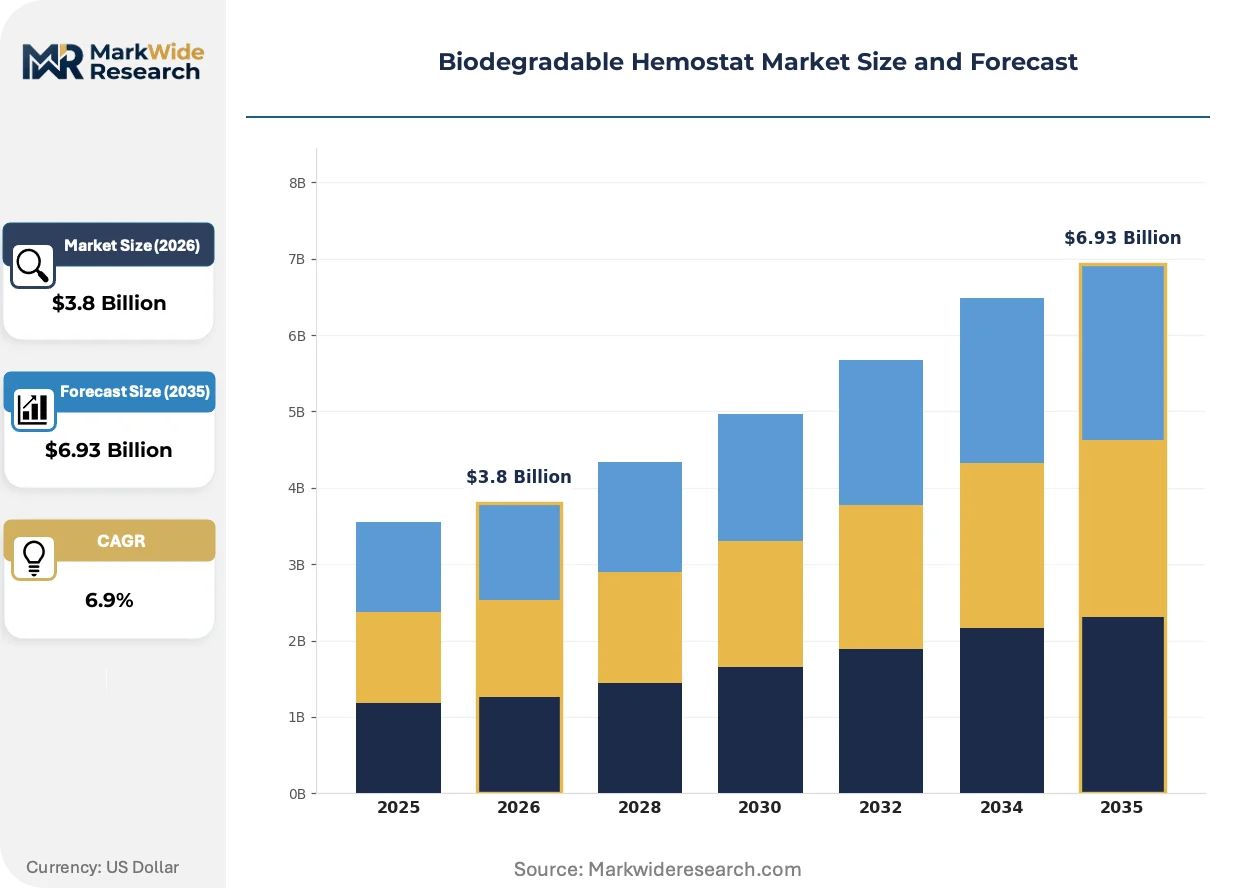
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.93 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin-Based, Oxidized Cellulose, Collagen-Based, Chitosan-Based, Synthetic Polymers Application: Cardiovascular Surgery, Orthopedic Procedures, Neurosurgery, Gynecological Surgery, General Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Form: Powder, Sponge, Film, Foam, Strip |
| Companies Covered | Johnson & Johnson, BD, Baxter, B. Braun, GELITA MEDICAL, Pfizer Inc., Cura Medical, Curasan AG, Meril Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Hemostat Market Strategic Shifts & Innovations
Recombinant protein engineering and service-layer unbundling are restructuring how hemostat value is captured, moving competition from physical product specifications toward integrated procedural support ecosystems.
Recombinant human collagen matrices produced via tobacco plant expression systems are rewriting hemostat supply economics by eliminating animal-derived raw material dependencies. Tertiary hospital surgical suites are piloting these formats for patients with religious or allergy constraints on bovine and porcine sources. The technology is compressing lot-to-lot variability and enabling lot-specific digital traceability that mechanical hemostasis cannot match.
EU MDR Article 10 post-market surveillance requirements now mandate systematic degradation rate documentation across patient subpopulations. Manufacturers must maintain clinical follow-up registries that track absorption timelines in diabetic, immunocompromised, and elderly cohorts. High-porosity oxidized cellulose formats face particular scrutiny in Germany and France where notified bodies apply stricter pyrogenicity thresholds.
Hospital supply chain managers are unbundling technical service contracts from physical product purchases, forcing vendors to price training and compliance auditing as standalone line items. This purchasing behavior change concentrates contract awards among suppliers with dedicated field clinical specialist teams. The shift is most pronounced in United States integrated delivery networks where procurement committees now separate consumable unit costs from implementation support fees.
Biodegradable Hemostat Market Segmentation
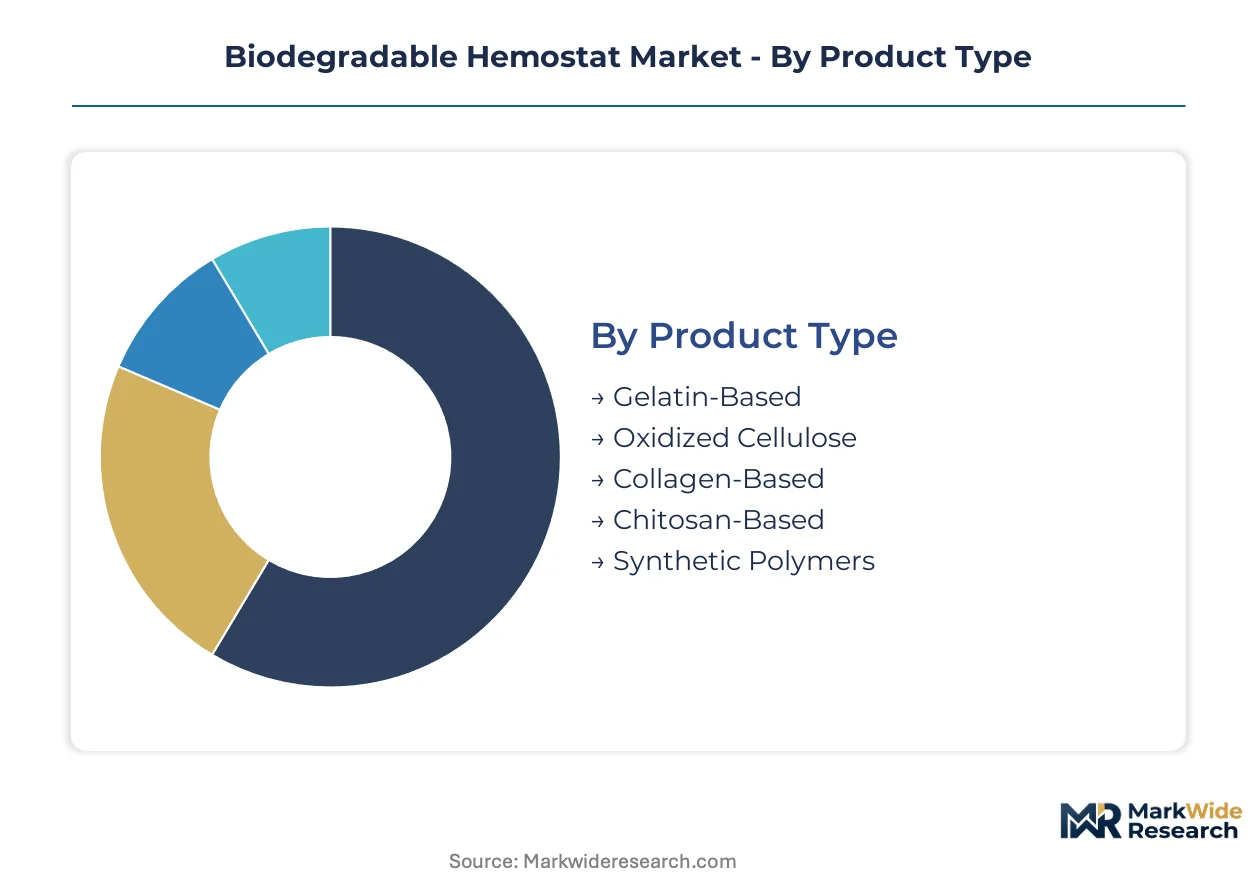
Segmentation in biodegradable hemostats reveals how material science, procedural site, and delivery format intersect to determine pricing power and regulatory pathway complexity. Manufacturers configure product portfolios across these dimensions to match hospital procurement hierarchies and surgeon training requirements.
Product Type:
Gelatin-based and oxidized cellulose formulations function as standalone hemostatic systems requiring minimal adjunct preparation, while chitosan and synthetic polymer variants embed into broader trauma and laparoscopic platforms.
- Gelatin-Based:Cross-linked porcine or bovine gelatin matrices absorb within 4-6 weeks and demonstrate superior thrombin adjunct compatibility. Tertiary hospital general surgery suites in the United States favor these formats for their established degradation predictability and lower pyrogenicity failure rates.
- Oxidized Cellulose:Regenerated cellulose oxidized to carboxyl functionality achieves hemostasis through acidic pH and physical compression. Demand concentrates in cardiovascular surgery applications across Germany and France where EU MDR notified bodies apply stringent degradation documentation requirements.
- Collagen-Based:Bovine or equine-derived collagen sponges provide platelet aggregation scaffolding with 8-week absorption profiles.
- Chitosan-Based:Marine-derived polysaccharide enables clotting independent of pH or coagulation cascade status.
- Synthetic Polymers:Polylactic acid and polyglycolic acid formulations offer tunable degradation kinetics via molecular weight control.
Volume placements concentrate in Gelatin-Based formats; the faster expansion belongs to Chitosan-Based segments.
Application:
Procedure type dictates hemostat selection through bleeding risk severity, anatomical access constraints, and reimbursement coding alignment.
- General Surgery:Open abdominal and soft tissue procedures consume the highest unit volumes of sponge and powder formats. United States integrated delivery networks negotiate system-wide contracts for these applications, compressing vendor margins while locking in multi-year replenishment schedules.
- Cardiovascular Surgery:Sternotomy and vascular anastomosis sites demand rapid hemostasis under full anticoagulation. German cardiac centers specify oxidized cellulose with documented degradation rates in diabetic patient registries to satisfy EU MDR Article 10 surveillance mandates.
- Orthopedic Procedures:Bone bleeding and joint capsule management favor collagen and gelatin matrices with extended absorption timelines.
- Neurosurgery:Dural and cortical surface applications require film and foam variants with minimal swelling to prevent compression injury.
- Gynecological Surgery:Laparoscopic hysterectomy and myomectomy drive demand for narrow-delivery powder and strip formats.
General Surgery generates the highest absolute unit demand; Neurosurgery commands the steepest price premiums per application.
End User:
Customer type determines packaging configuration, inventory management integration, and technical service bundling requirements.
- Hospitals:Tertiary and community hospital operating rooms purchase hemostats through value-analysis committees that separate product cost from implementation support fees. United States health systems increasingly unbundle these components, favoring suppliers with dedicated field clinical specialists.
- Ambulatory Surgical Centers:Outpatient facilities prioritize compact single-use packaging with embedded RFID tracking for automated replenishment. These sites migrate fastest toward powder and film formats optimized for narrow storage footprints.
- Specialty Clinics:Dermatology and dental surgery applications consume smaller volumes of strip and sponge variants.
- Research Institutes:Academic medical centers pilot recombinant collagen and chitosan-gelatin composites under investigator-initiated protocols.
Hospitals account for the dominant revenue share; Ambulatory Surgical Centers are climbing the fastest as procedure migration accelerates.
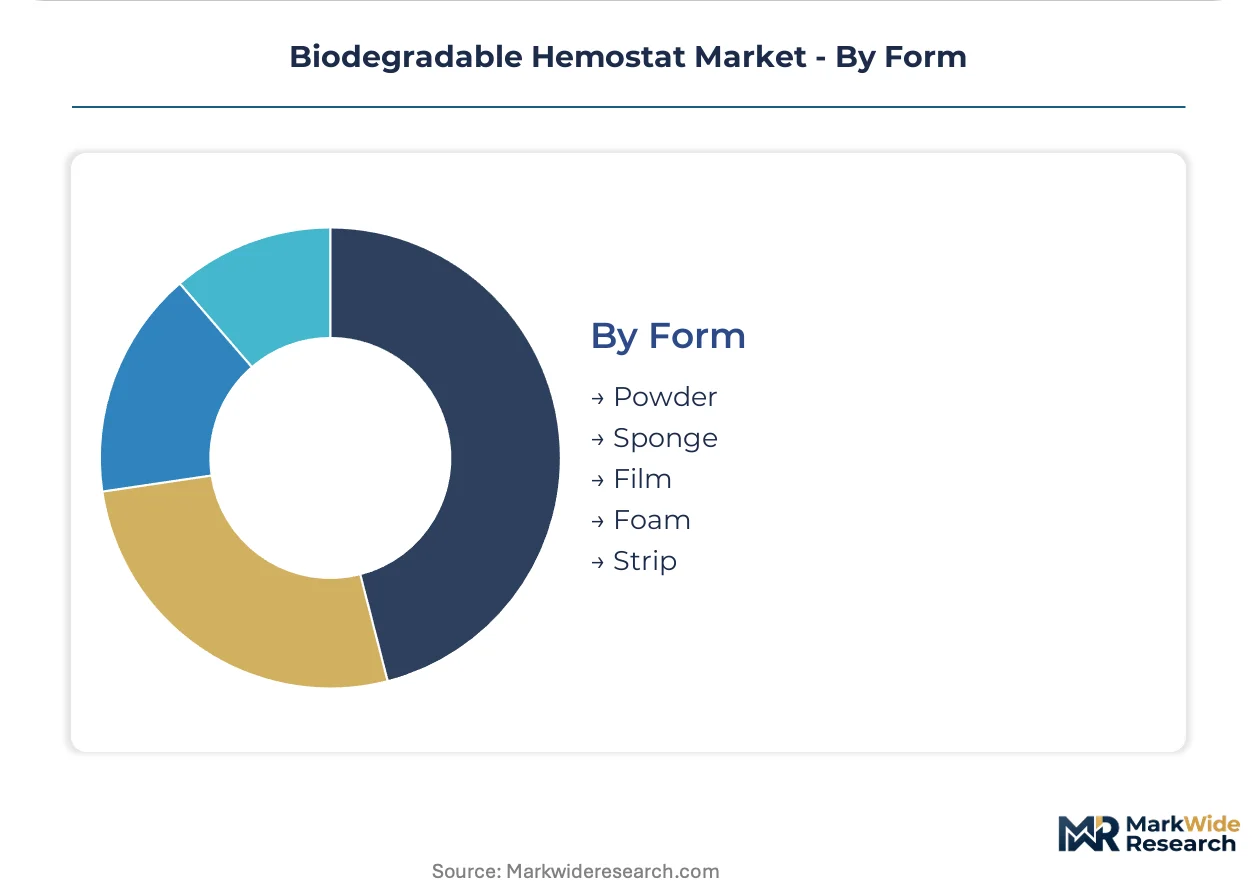
Form:
Physical configuration determines delivery channel compatibility, absorption rate control, and manufacturing capital intensity.
- Sponge:Pre-formed matrices with controlled porosity dominate open surgical applications. These formats require the lowest surgeon training investment and maintain the broadest reimbursement coverage across United States Medicare and commercial payers.
- Powder:Flowable granules enable laparoscopic and endoscopic delivery through narrow working channels. Trauma medicine applications in military and emergency settings favor powder for rapid deployment across irregular wound geometries.
- Film:Thin-sheet configurations address neurosurgical and ophthalmic requirements for minimal mass and predictable swelling.
- Foam:High-expansion variants conform to cavity shapes in orthopedic and thoracic applications.
- Strip:Pre-cut dimensions match linear incision patterns in dermatological and plastic surgery.
Sponge formats retain the largest installed base; Powder configurations are gaining share fastest through minimally invasive procedure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States where polymer science infrastructure supports absorbable biopolymer production, while consumption tilts toward hospital systems in North America and Western Europe with advanced surgical procedure penetration.
United States
Integrated delivery networks consolidate operating room consumable purchasing across multi-hospital systems, compressing vendor negotiation cycles toward bundled service agreements. FDA 510(k) clearance pathways for absorbable surgical materials compress commercialization timelines for novel gelatin and oxidized cellulose formulations. Tertiary hospital surgical suites in the Cleveland Clinic and Mayo Clinic networks pilot recombinant collagen matrices under investigator-initiated protocols.
Germany
Cardiovascular surgery centers drive oxidized cellulose demand under full anticoagulation protocols with stringent degradation documentation requirements. EU MDR Article 10 post-market surveillance mandates systematic absorption tracking across diabetic and immunocompromised patient registries. Notified bodies in Berlin and Munich apply elevated pyrogenicity thresholds that filter market access for high-porosity cellulose formats.
China
Public hospital procurement expansion under centralized volume-based purchasing creates price pressure on imported absorbable sponge products. NMPA registration protocols impose localized biocompatibility testing that extends certification timelines for foreign biopolymer suppliers. Manufacturing clusters in Suzhou and Shanghai host domestic gelatin matrix producers serving tier-one hospital surgical departments.
India
Government hospital procurement under Ayushman Bharat insurance expansion creates volume opportunities for cost-optimized hemostat formats. BIS biodegradability certification requirements for public sector tenders favor suppliers with documented green chemistry compliance. Medical device manufacturing zones in Gujarat and Karnataka attract contract production of chitosan-based matrices for military and trauma medicine applications.
Japan
Aging surgical populations and laparoscopic procedure growth drive demand for film and foam hemostat variants with minimal swelling profiles. PMDA marketing authorization requirements emphasize degradation rate predictability in elderly patient cohorts. Academic medical centers in Tokyo and Osaka evaluate chitosan-gelatin composite matrices for emergency medicine applications where pH-independent clotting offers clinical advantage.
Biodegradable Hemostat Market Key Industry Players
Top-tier vendors anchor integrated delivery network contracts through bundled technical service agreements, while mid-scale specialists compete on automated inventory integration and narrow-format product portfolios. The vendor base stratifies across three archetypes: diversified medical device conglomerates with service infrastructure, pure-play hemostat manufacturers with material science specialization, and regional contract producers serving price-sensitive procurement channels. Consolidation pressure intensifies through long-term hospital replenishment schedules that lock in oxidized cellulose and gelatin matrix supply relationships.
Among diversified medical device conglomerates, Johnson & Johnson and Baxter occupy positions that exemplify service-layer bundling strategies, while BD represents the automated supply chain integration archetype. These entities anchor competitive positioning through field clinical specialist teams that separate consumable unit costs from implementation support fees. Pure-play specialists including GELITA MEDICAL and Curasan AG sit within material-focused tiers where porcine-derived gelatin expertise and recombinant protein engineering command premium positioning. Regional contract manufacturers across India and China compete on BIS and NMPA certification speed for public hospital tenders.
| Leading Market Players |
|---|
| Johnson & Johnson |
| BD |
| Baxter |
| B. Braun |
| GELITA MEDICAL |
| Pfizer Inc. |
| Cura Medical |
| Curasan AG |
| Meril Life Sciences |
| Others |
Cost & Logistics Intelligence
Polymer science talent scarcity in Germany and the United States feeds directly into pricing-tier spreads, as formulation chemists with controlled degradation expertise command premium compensation that manufacturers pass through to premium-tier recombinant collagen and chitosan-gelatin composite formats.
Pricing Analysis
Cost-down pressure on standard-tier gelatin sponges accelerates because United States integrated delivery networks unbundle technical service contracts and negotiate consumable unit costs separately from implementation support. Three-tier pricing structure across premium, standard, and economy levels separates recombinant collagen matrices with embedded RFID traceability from conventional oxidized cellulose and imported chitosan variants. Price differentiation hinges on FDA 510(k) clearance tier and EU MDR notified body certification grade. Ambulatory surgical centers exhibit highest price sensitivity due to narrow reimbursement bands, while German cardiovascular centers tolerate premium pricing for documented degradation rate predictability under anticoagulation protocols.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled absorbable matrices remain minimal given biodegradability constraints, though German and French notified bodies mandate lot-specific tracking through post-market surveillance registries that extend chain-of-custody documentation. Manufacturing concentrates in Germany, the United States, and China, with domestic gelatin matrix producers in Suzhou and Shanghai serving tier-one hospital surgical departments under NMPA registration protocols. Raw material dependencies span porcine and bovine gelatin feedstocks, marine chitosan from crustacean processing, and fermentation-derived recombinant collagen proteins. Single-source vulnerability in bioreactor-derived matrix protein supply creates exposure to fermentation substrate price volatility. Distribution runs through hospital value-analysis committees and group purchasing organizations that lock in multi-year replenishment schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biodegradable hemostat market functions as a consolidation play where EU MDR technical documentation burdens and pyrogenicity testing facility bottlenecks force weaker players toward exit or acquisition.
For Market Incumbents: Lock in integrated delivery network contracts through bundled field clinical specialist teams that separate consumable unit costs from compliance auditing fees. Deepen backward integration into recombinant collagen production via tobacco plant expression systems to neutralize animal-derived raw material volatility. Anchor capacity in Germany and the United States where polymer science infrastructure supports absorbable biopolymer manufacturing and EU MDR notified body relationships filter competition. For New Entrants and Emerging Players: Chitosan-gelatin composite engineering offers a technology-first wedge into military and trauma medicine applications where pH-independent clotting action commands clinical preference over conventional thrombin adjuncts. Target India's BIS biodegradability certification pathway for public hospital procurement under Ayushman Bharat expansion, where green chemistry compliance creates preferential tender access. Penetrate ambulatory surgical center channels through compact powder formats with embedded RFID inventory tracking that aligns with automated replenishment mandates. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play hemostat specialists possessing material science depth and EU MDR Article 10 post-market surveillance infrastructure given consolidation pressure from diversified conglomerates. Long-term viability over the projection horizon favors manufacturers with demonstrated degradation rate documentation across diabetic and immunocompromised patient registries. Monitor notified body pyrogenicity threshold tightening in Germany and France as inflection indicator for competitive filtering intensity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined premarket notification accelerates novel biopolymer commercialization timelines for absorbable surgical materials. |
| EU MDR Article 10 Compliance | Post-market surveillance registries tracking absorption in diabetic cohorts satisfy notified body degradation documentation mandates. |
| Hospital System Partnership | Integrated delivery network contracts bundle oxidized cellulose replenishment with field clinical specialist implementation support. |
| Backward Integration into Recombinant Collagen | Tobacco plant expression systems eliminate animal-derived raw material dependencies and compress lot-to-lot variability. |
| Ambulatory Surgical Center Channel Expansion | Compact powder formats with RFID tracking align with automated inventory management in outpatient procedure migration. |
Research Approach
Independent corroboration across hospital purchasing committee interviews, biomedical engineer consultations, and GPO contracts manager discussions underwrites the qualitative findings. Primary fieldwork engaged formulation chemists at gelatin matrix manufacturers, regulatory affairs leads navigating FDA 510(k) pathways, and EU MDR notified body auditors in Berlin and Munich. Secondary validation drew from FDA 510(k) premarket notification databases, EUDAMED post-market surveillance registries, hospital procurement databases, and customs records of absorbable surgical material trade flows. Bottom-up segmentation modeling triangulated against top-down macroeconomic healthcare expenditure trends.
Rate-of-change decomposition across the analysis window isolates volume expansion from price-mix effects and regulatory timeline compression. Segmentation dimensions modeled include material composition tier, procedural application site, end-user facility type, and physical delivery format. CAGRs derive from surgical procedure volume trajectories, reimbursement code alignment shifts, and biopolymer adoption curve penetration rates. Forecast inputs incorporate EU MDR certification queue delays, pyrogenicity testing facility capacity constraints, and integrated delivery network contract renewal cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden notified body pyrogenicity threshold elevation or raw material bioreactor supply disruption. Forecasts reflect assumptions regarding regulatory pathway stability and surgical procedure migration velocity. Practitioners should monitor BIS biodegradability certification rollout in India and NMPA registration timeline compression in China for early signals of regional competitive reordering.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Hemostats Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Asia-Pacific N95 Mask Market
Medical Supplies
Evidence Collection Tubes Market
Medical Supplies
Asia-Pacific Syringe Market
Medical Supplies
Luer Plug Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Casting and Splinting Market
Medical Supplies
Ostomy Care and Accessories Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
MENA Syringes and Cannula Market