
 Malaysia Insulin Infusion Pump Market | 2026-2036
Malaysia Insulin Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Insulin Infusion Pump Market Insights
Malaysia's Medical Device Act 2012 is restructuring the cost-of-entry calculus for insulin pump manufacturers seeking market authorization. Medtronic leverages its established regulatory dossiers to sustain first-mover advantage across private hospital channels. Ypsomed specializes in patch pump miniaturization, while Insulet Corporation competes through tubeless form factors that differentiate its Omnipod platform in home healthcare settings.
An insulin infusion pump is a programmable electromechanical device that delivers rapid-acting insulin through a subcutaneous cannula at calibrated basal rates and bolus doses, typically with delivery precision of 0.025 to 0.1 units per increment. Its primary purpose is to replicate physiological pancreatic beta-cell secretion for glycemic control in insulin-dependent diabetes patients. Continuous Subcutaneous Insulin Infusion dominates hospital procurement due to established reimbursement pathways, while Patch Pumps represent the fastest-growing technology segment as patients prioritize discretion and reduced tubing burden. Smart Insulin Pumps with integrated continuous glucose monitoring algorithms command premium positioning where endocrinologists prescribe closed-loop configurations.
Malaysia's Medical Device Authority enforces conformity assessment procedures aligned with ASEAN Medical Device Directive harmonization, while the Ministry of Health's pharmaceutical services programme governs insulin reimbursement eligibility that directly shapes pump adoption economics. BIS-equivalent electrical safety standards and IEC 60601-2-24 compliance for infusion pump electromagnetic compatibility create technical barriers that filter import channels. Stakeholders must monitor how Malaysia's planned national health insurance reform reframes durable medical equipment coverage decisions for diabetes technology.
Market Dynamics
Malaysia's Medical Device Authority is tightening conformity assessment timelines under ASEAN Medical Device Directive harmonization, forcing manufacturers to accelerate technical documentation for pump registration while private hospital procurement committees demand closed-loop system compatibility as a baseline specification.
Growth Catalysts
- Medical Device Act 2012 enforcement:The legislation's expanded scope captures insulin pumps under Class C risk classification, creating predictable registration pathways that reduce market entry uncertainty for device manufacturers.
- Klang Valley endocrinology clustering:Specialist diabetes centers concentrated around Kuala Lumpur and Selangor generate concentrated prescription volumes that justify dedicated pump sales infrastructure.
- Continuous glucose monitoring convergence:Algorithm-enabled sensor-augmented pump therapy is reshaping clinical expectations for glycemic targets among Type 1 diabetes patients.
Market Restraints
- Reimbursement fragmentation:Malaysia's Ministry of Health pharmaceutical services programme maintains inconsistent insulin pump coverage across public and private channels, forcing patients to absorb substantial out-of-pocket costs.
- Import dependency for consumables:Infusion sets and reservoirs flow primarily through Singapore distribution hubs, exposing supply continuity to cross-border logistics friction.
- IEC 60601-2-24 electromagnetic compliance:The infusion pump-specific safety standard requires specialized testing protocols that extend product registration timelines by six to nine months.
Strategic Opportunities
- East Malaysia geographic expansion:Sabah and Sarawak present underpenetrated demand where telemedicine-enabled pump training could overcome specialist scarcity.
- National health insurance reform:Malaysia's planned social health insurance restructuring may reclassify durable medical equipment for diabetes technology under standard benefit packages.
- Patch pump home healthcare migration:Tubeless form factors align with Ministry of Health ambulatory care priorities that shift chronic disease management from hospital to community settings.
Industry Challenges
- Certified diabetes educator shortage:Pump initiation and troubleshooting require specialized nursing competencies that Malaysian training programs produce at insufficient volume.
- Legacy hospital information system integration:Glycemic data export from smart pumps into electronic medical records demands custom interface development that stretches hospital IT resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Insulin Infusion Pump Market |
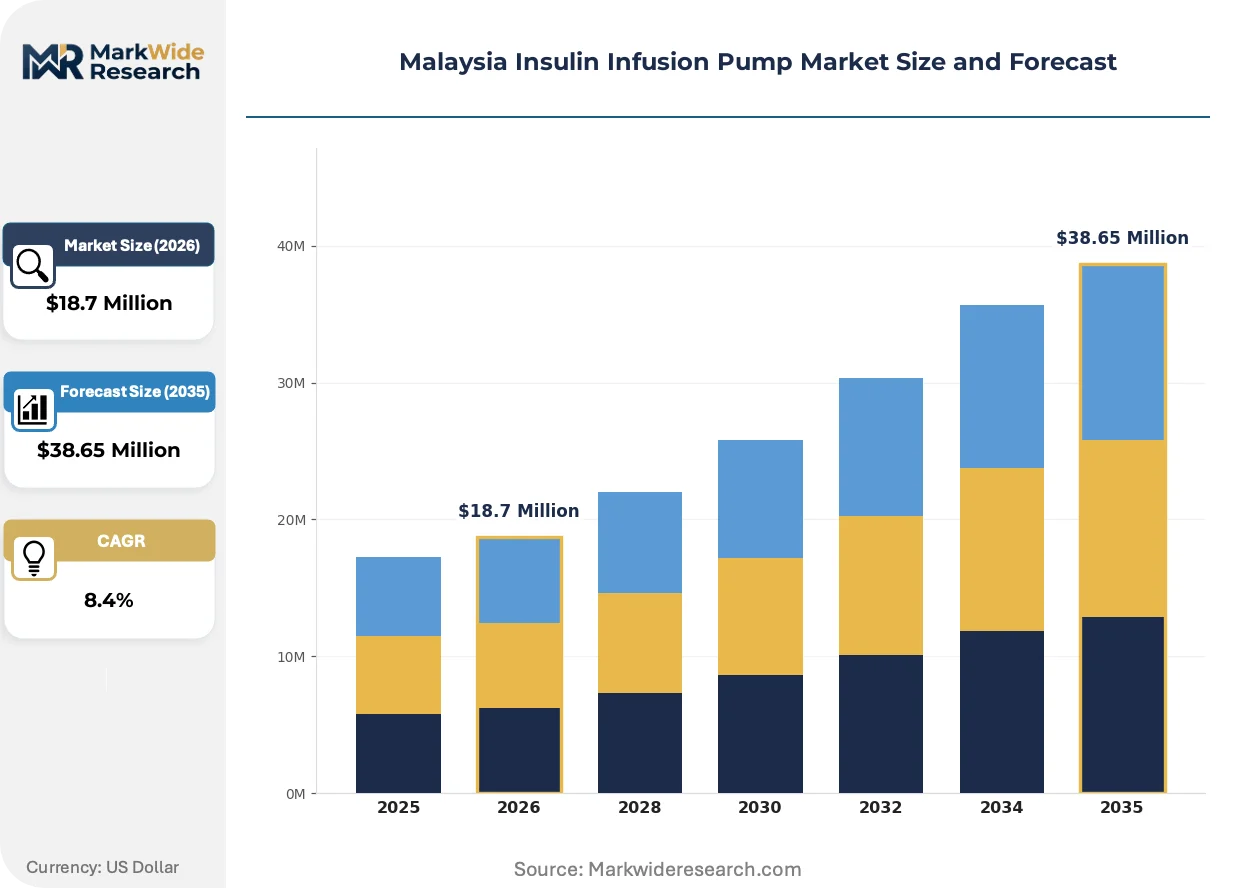
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $38.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Subcutaneous Insulin Infusion, Implantable Pumps, Prefilled Insulin Cartridges, Disposable Pumps Technology: Micro-Delivery Systems, Smart Insulin Pumps, Patch Pumps, Remote Monitoring End User: Hospitals, Clinics, Home Healthcare, Pharmacies Distribution Channel: Direct Sales, Online Platforms, Third-Party Distributors, Retail Outlets |
| Companies Covered | Medtronic, Ascensia Diabetes Care, Insulet Corporation, Tandem Diabetes Care, Ypsomed, Becton Dickinson, Roche Diabetes Care, B. Braun Melsungen AG, Sooil Development Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Insulin Infusion Pump Market Trends and Innovations
Algorithm-driven automation is compressing the clinical skill gap required for intensive insulin management, while hardware miniaturization and disposable economics are redrawing the boundary between durable and consumable device categories.
Smart insulin pumps with embedded continuous glucose monitoring algorithms are integrating predictive low-glucose suspend and auto-basal adjustment functions that previously required physician intervention. Private endocrinology practices in Selangor are adopting these closed-loop configurations faster than public hospital settings where procurement cycles lag. This capability convergence is integrating insulin delivery and sensing into single-platform value propositions that command premium positioning against conventional pump-only systems.
Malaysia's Medical Device Authority is aligning conformity assessment procedures with ASEAN Medical Device Directive technical documentation requirements, compressing the variance between member state registration standards. Manufacturers must now submit clinical evidence summaries and post-market surveillance plans in standardized formats that accelerate multi-country approvals. This regulatory harmonization is most affecting patch pump entrants seeking rapid deployment across Southeast Asian markets without duplicative testing expenditures.
Patient self-management preferences are fragmenting traditional hospital-centered pump initiation models, with home-based training protocols and remote monitoring subscriptions displacing inpatient admission requirements. Younger Type 1 diabetes cohorts in urban Peninsular Malaysia are driving this channel shift through direct-to-consumer research and peer community influence. The behavioral pivot is most visible in Kuala Lumpur where specialist practices unbundle device provision from mandatory follow-up schedules to compete with regional medical tourism destinations.
Malaysia Insulin Infusion Pump Market Segmentation
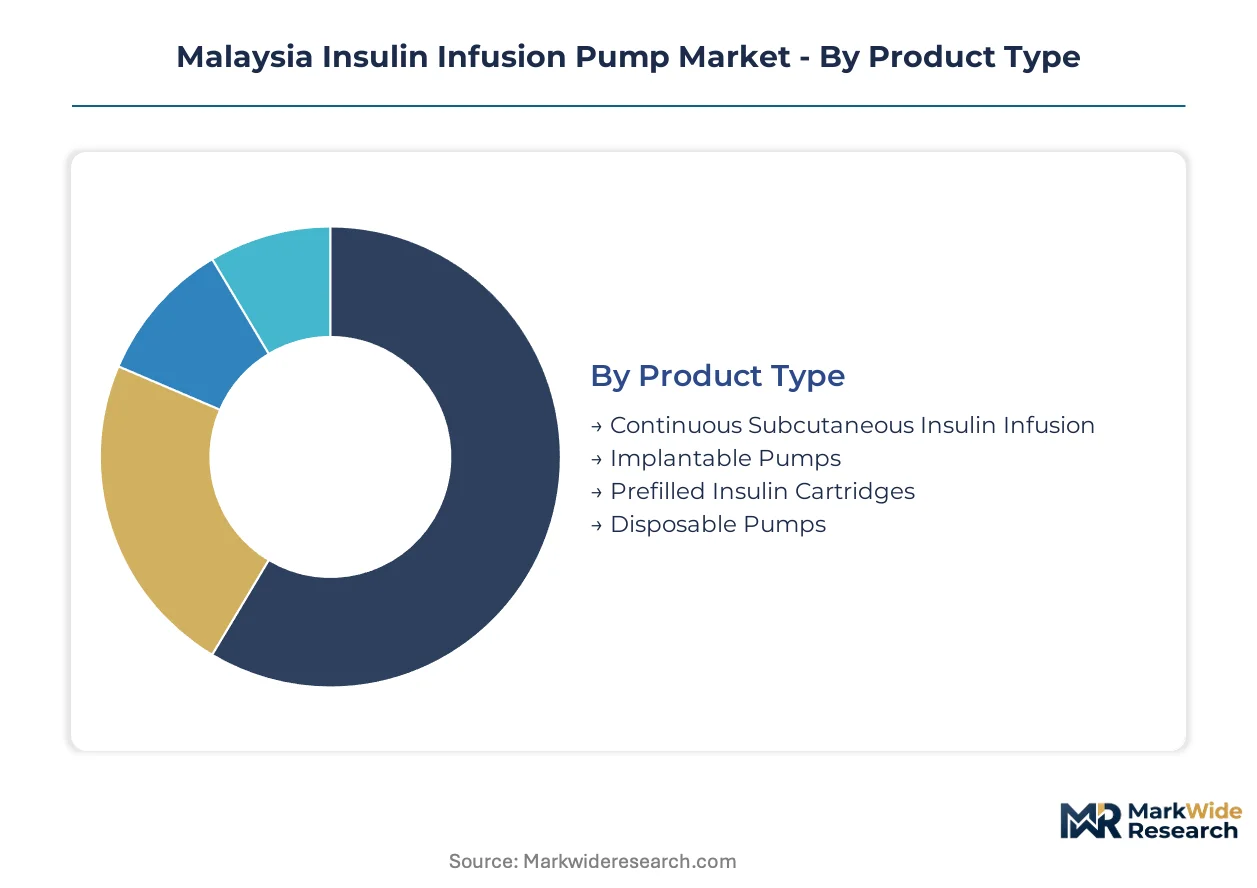
Malaysia's insulin pump market fragments across device configurations, connectivity layers, and care delivery settings. Each segment carries distinct regulatory burdens and reimbursement pathways that shape manufacturer investment priorities.
Product Type:
Capital intensity varies sharply across these device categories, with durable systems requiring substantial R&D amortization against consumable platforms that shift revenue toward recurring cartridge sales.
- Continuous Subcutaneous Insulin Infusion:These programmable electromechanical systems deliver rapid-acting insulin through subcutaneous cannulas at calibrated basal rates and bolus doses. Demand concentrates in Klang Valley private hospitals where endocrinology specialists prescribe closed-loop configurations for Type 1 diabetes patients. Malaysia's Medical Device Authority classifies these as Class C devices under the Medical Device Act 2012, extending registration timelines.
- Implantable Pumps:Fully implanted devices with refillable reservoirs deliver insulin directly into the peritoneal cavity, eliminating external tubing. Adoption remains limited to Kuala Lumpur quaternary referral centers where surgical implantation capabilities exist. High upfront surgical costs and limited local explant expertise constrain penetration.
- Prefilled Insulin Cartridges:Single-use reservoirs eliminate manual filling errors and reduce infection risk. These consumables generate recurring revenue streams that offset lower device margins in patch pump economics.
- Disposable Pumps:Fully integrated single-use systems combine reservoir, pump mechanism, and cannula in one disposable unit. These lower-cost alternatives appeal to price-sensitive patients in East Malaysia where reimbursement coverage gaps persist.
Most installed capacity flows through Continuous Subcutaneous Insulin Infusion. Expansion is steepest in Disposable Pumps.
Technology:
Technology differentiation separates premium-positioned systems from commodity alternatives, with algorithm-enabled platforms commanding reimbursement premiums over basic mechanical delivery.
- Micro-Delivery Systems:Precision piston or peristaltic mechanisms achieve delivery increments of 0.025 to 0.1 units, critical for pediatric and insulin-sensitive patients. Peninsular Malaysia's specialist diabetes centers specify these for gestational diabetes and brittle Type 1 cases.
- Smart Insulin Pumps:Embedded continuous glucose monitoring algorithms enable predictive low-glucose suspend and auto-basal adjustment without physician intervention. Selangor private endocrinology practices adopt these faster than public hospital settings where procurement cycles lag.
- Patch Pumps:Tubeless adhesive-mounted devices integrate pump and cannula in a single disposable unit worn directly on the body. Younger Type 1 cohorts in urban Peninsular Malaysia drive this segment through peer community influence and discretion preferences.
- Remote Monitoring:Cloud-connected platforms transmit glycemic data to caregiver dashboards, enabling telemedicine follow-up. Sabah and Sarawak adoption depends on these capabilities to overcome specialist scarcity.
Revenue concentrates in Smart Insulin Pumps. Patch Pumps are climbing the fastest as patients prioritize reduced tubing burden.
End User:
Care setting determines training infrastructure requirements and reimbursement eligibility, with hospital-based initiation giving way to ambulatory models.
- Hospitals:Tertiary centers handle complex pump initiations for newly diagnosed Type 1 patients and gestational diabetes cases. Klang Valley clusters around Kuala Lumpur and Selangor generate concentrated prescription volumes.
- Clinics:Specialist endocrinology practices unbundle device provision from mandatory follow-up schedules to compete with regional medical tourism destinations. These settings favor closed-loop system compatibility as baseline specification.
- Home Healthcare:Community-based pump training and remote monitoring subscriptions displace inpatient admission requirements. Ministry of Health ambulatory care priorities align with this channel shift.
- Pharmacies:Retail channels handle consumable resupply for established pump patients, though device initiation remains clinically restricted.
Procurement volume centers on Hospitals. Home Healthcare is gaining share fastest as chronic disease management shifts from hospital to community settings.
Distribution Channel:
Channel economics reflect device complexity, with direct sales dominating high-touch systems and digital platforms emerging for consumable replenishment.
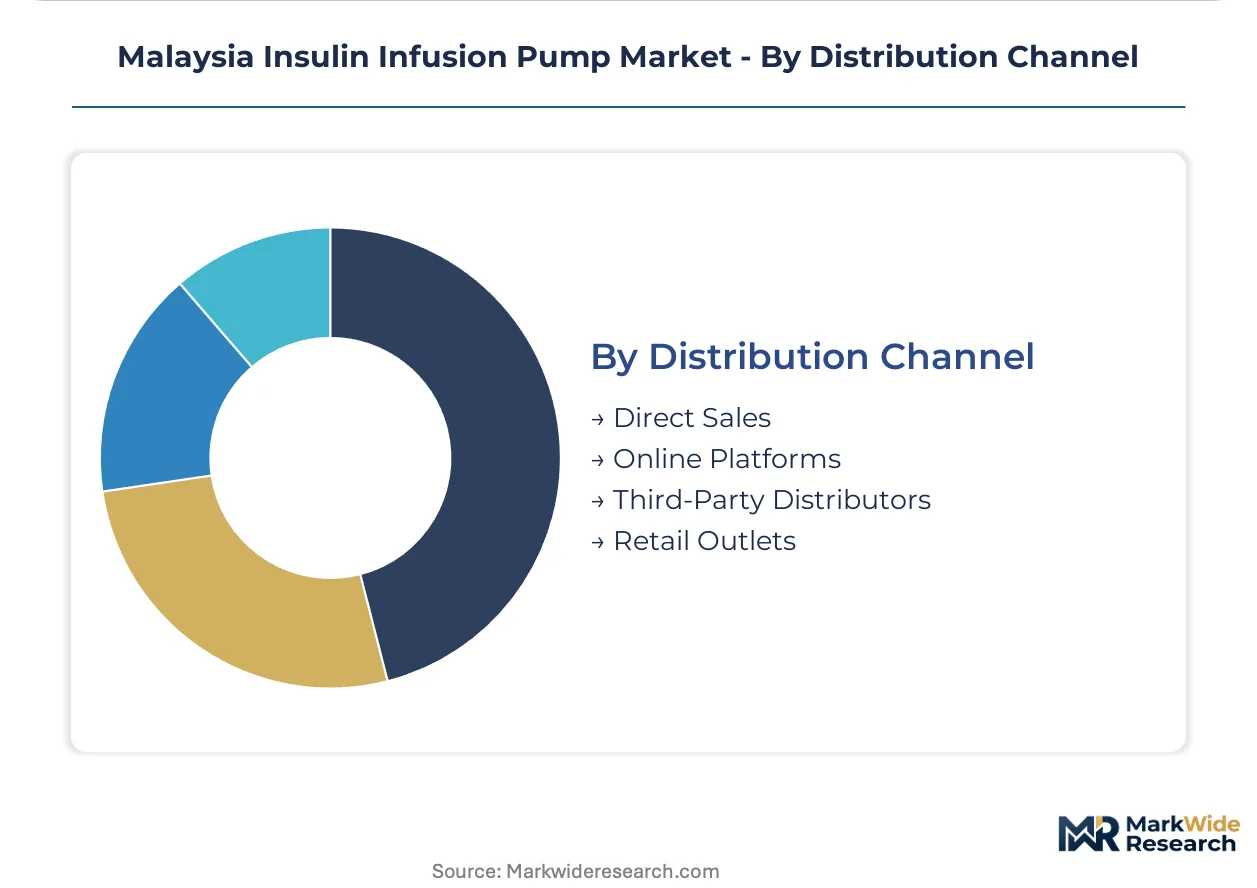
- Direct Sales:Manufacturer field forces provide clinical training and technical support for complex programmable systems. Private hospital procurement committees in Kuala Lumpur demand this service layer.
- Online Platforms:E-commerce channels serve established patients seeking consumable resupply, though device purchases require prescription verification.
- Third-Party Distributors:Singapore-based logistics hubs manage infusion sets and reservoirs, exposing supply continuity to cross-border friction. These intermediaries handle import compliance for multinational manufacturers.
- Retail Outlets:Pharmacy chains and medical supply stores serve walk-in consumable demand, particularly in East Malaysia where specialist density is lowest.
Transaction value concentrates in Direct Sales. Third-Party Distributors are expanding most quickly as manufacturers seek to localize inventory positions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Endocrinology specialist density concentrates in Peninsular Malaysia's urban corridors, while East Malaysia faces pronounced healthcare workforce gaps that telemedicine infrastructure attempts to bridge.
Klang Valley
Type 1 diabetes patient volumes and private hospital procurement committees cluster around Kuala Lumpur and Selangor. Malaysia's Medical Device Act 2012 registration requirements filter device entrants through Class C conformity assessments. Specialist diabetes centers in Petaling Jaya and Ampang generate concentrated prescription volumes for closed-loop pump configurations.
Penang and Northern Corridor
Medical tourism positioning attracts regional patients seeking advanced diabetes technology unavailable in home markets. The Ministry of Health's pharmaceutical services programme maintains inconsistent reimbursement that forces private payment for pump therapy. George Town's quaternary hospitals host surgical implantation capabilities for fully implanted systems.
Johor Bahru and Southern Region
Proximity to Singapore creates cross-border referral patterns for complex pump initiations. Singapore-based distributors manage infusion set logistics through this corridor, exposing supply continuity to customs friction. Specialist practices in Iskandar Malaysia unbundle device provision from mandatory follow-up schedules.
Sabah
Specialist scarcity constrains pump adoption despite rising Type 1 diabetes prevalence. Remote monitoring subscriptions and telemedicine-enabled training protocols attempt to overcome geographic barriers. Kota Kinabalu's limited endocrinology capacity refers complex cases to Klang Valley centers.
Sarawak
Home healthcare migration aligns with Ministry of Health ambulatory care priorities shifting chronic disease management from hospital settings. Kuching's emerging diabetes centers adopt patch pump form factors for patient discretion preferences. Consumable resupply flows through Singapore distribution hubs with extended lead times.
Malaysia Insulin Infusion Pump Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Malaysia's insulin pump market, creating a tiered structure where regulatory dossier depth separates sustainable positions from transient entrants. Medtronic leverages established Medical Device Authority registrations to sustain first-mover advantage in private hospital channels. Three archetypes dominate: multinational device conglomerates with integrated diabetes portfolios, dedicated pump specialists emphasizing form factor innovation, and Asia-Pacific regional players competing on consumable economics. Competitive moves center on registration acceleration under ASEAN Medical Device Directive harmonization and closed-loop algorithm partnerships with continuous glucose monitoring platforms.
Among multinational conglomerates, Medtronic and Roche Diabetes Care exemplify diversified medical device structures spanning multiple therapeutic areas. Dedicated pump specialists include Insulet Corporation with its tubeless platform and Ypsomed with patch pump miniaturization capabilities. Tandem Diabetes Care occupies a position emphasizing algorithm-enabled automation. These named entities represent distinct strategic postures rather than exhaustively mapping competitive positions.
| Leading Market Players |
|---|
| Medtronic |
| Ascensia Diabetes Care |
| Insulet Corporation |
| Tandem Diabetes Care |
| Ypsomed |
| Becton Dickinson |
| Roche Diabetes Care |
| B. Braun Melsungen AG |
| Sooil Development Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive distribution through Singapore-based logistics hubs anchors both supply continuity and pricing power for Malaysia's insulin pump market, with cross-border customs friction creating natural segmentation between premium direct-sales channels and economy-tier distributor-reliant alternatives. Malaysia's Medical Device Authority registration timelines under the Medical Device Act 2012 compress margin flexibility for entrants lacking established conformity dossiers.
Pricing Analysis
Bundled device-plus-service contracts dominate private hospital procurement in Kuala Lumpur and Selangor, while unbundled consumable-only transactions prevail in East Malaysia where reimbursement gaps force patient self-pay. Price differentiation rests on closed-loop algorithm certification and after-sales clinical training depth. Pricing pressure stems from Ministry of Health pharmaceutical services programme inconsistencies that expand out-of-pocket burdens. Public hospital procurement committees exhibit highest price sensitivity; private endocrinology practices in Petaling Jaya show lowest sensitivity due to medical tourism positioning.
Supply Chain Analysis
Direct-to-hospital channels handle complex programmable system demand in Klang Valley, while third-party distributor networks manage consumable flow to East Malaysia. Manufacturing concentrates in the United States, Switzerland, and Germany for precision pump mechanisms; South Korea and Japan supply micro-delivery components. Supply chain risk centers on Singapore hub dependency for infusion sets and reservoirs, exposing continuity to customs friction. Distribution runs through biomedical engineering specialists and pharmacy retail chains for established patient resupply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's insulin pump market compounds steadily as Type 1 diabetes prevalence rises and Medical Device Act 2012 enforcement clarifies registration pathways for compliant manufacturers.
For Market Incumbents: To counter patch pump miniaturization from specialized competitors, deepen closed-loop algorithm partnerships with continuous glucose monitoring platforms and secure exclusive biomedical engineer training contracts with Klang Valley private hospital procurement committees. Expand captive supply of prefilled insulin cartridges through backward integration into reservoir manufacturing to defend margin position against consumable-only entrants. For New Entrants and Emerging Players: Capture East Malaysia's underpenetrated demand in Sabah and Sarawak where telemedicine-enabled pump training overcomes specialist scarcity and reimbursement fragmentation blocks incumbent expansion. Prioritize tubeless disposable form factors aligned with Ministry of Health ambulatory care priorities, deploying direct-to-patient digital platforms that bypass traditional hospital initiation requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional Asia-Pacific distributors with established Medical Device Authority registration capabilities because ASEAN Medical Device Directive harmonization creates multi-country leverage from single conformity investments. Target acquisition archetypes with certified diabetes educator networks and existing Singapore logistics infrastructure. Watch national health insurance reform negotiations as the signal for durable medical equipment reclassification timing.| Strategic Initiative | Industry Significance |
|---|---|
| Medical Device Authority Registration Acceleration | Class C conformity dossiers under Medical Device Act 2012 unlock private hospital procurement in Kuala Lumpur corridors. |
| Closed-Loop Algorithm Partnership | Continuous glucose monitoring integration commands premium positioning against conventional pump-only systems in Selangor specialist practices. |
| Telemedicine-Enabled Training Protocol | Remote pump initiation overcomes certified diabetes educator scarcity constraining Sabah and Sarawak penetration. |
| Consumable Cartridge Backward Integration | In-house reservoir production defends margin compression from Singapore distribution hub dependency. |
| Home Healthcare Channel Migration | Community-based pump management aligns with Ministry of Health ambulatory care policy shifts from hospital settings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with endocrinologists, hospital biomedical engineers, private procurement committee members, and GPO contracts managers with secondary validation from Medical Device Authority registration databases, Ministry of Health pharmaceutical services programme documentation, and ASEAN Medical Device Directive technical harmonization records. Bottom-up patient volume estimates triangulated against top-down device shipment data through Singapore distribution hubs.
Segment-weighting across product type, technology tier, end-user setting, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from installed base growth rates and replacement cycle analysis, with continuous glucose monitoring convergence velocity and patch pump adoption curves as diabetes-specific forecast inputs.
Regulatory timeline delays, reimbursement policy reversals, and supply chain chokepoint disruptions are the dominant revision risks for forecast trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
France Diabetes Devices Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
Diabetic Footwear Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
Digital Diabetes Management Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Continuous Glucose Monitoring Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
Diabetic Shoes Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
North America Insulin Infusion Pumps Market