
 Type 2 Diabetes Drugs and Devices Market | 2026-2036
Type 2 Diabetes Drugs and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Type 2 Diabetes Drugs and Devices Market Insights
Multi-source procurement for active pharmaceutical ingredients is restructuring supply security across the Type 2 Diabetes Drugs and Devices Market. Novo Nordisk A/S anchors its peptide manufacturing through captive fermentation capacity in Denmark. Eli Lilly and Company extends its position via differentiated GLP-1 receptor agonist dosing profiles. Sanofi competes through established basal insulin portfolios and emerging biosimilar positioning.
Type 2 diabetes drugs and devices comprise pharmacologic agents and delivery technologies targeting insulin resistance and beta-cell dysfunction in non-insulin-dependent diabetes mellitus, with GLP-1 agonists requiring cold-chain distribution at 2-8°C and continuous glucose monitors functioning via interstitial fluid enzymatic biosensors calibrated to plasma glucose correlation algorithms. GLP-1 Agonists command premium pricing and physician preference amid cardiovascular outcome benefits, while SGLT2 Inhibitors occupy expanding heart-failure-adjacent prescribing. Continuous Glucose Monitoring within the Delivery Mode dimension leads technology adoption curves as real-time data integration reshapes homecare and clinic workflows.
FDA premarket approval pathways for closed-loop insulin delivery systems and CMS national coverage determinations for therapeutic continuous glucose monitoring shape product development priorities and reimbursement access in the United States. EMA's MDR requirements for wearable devices and the EU Green Deal pharmaceutical sustainability directives influence manufacturing location decisions and packaging material selections for European market entry. Stakeholders must monitor evolving FDA guidance on artificial pancreas interoperability standards and prepare for state-level Medicaid GLP-1 coverage variations that will fragment access dynamics.
Market Dynamics
GLP-1 agonist formularies are restructuring competitive positioning across hospital procurement, with integrated delivery networks consolidating purchasing power around cardiovascular outcome data and cold-chain reliability metrics.
Growth Catalysts
- CMS Reimbursement Expansion:National coverage determinations for therapeutic continuous glucose monitoring in obesity-linked diabetes indications are unlocking institutional procurement at scale across United States hospital systems.
- Cardiovascular Outcome Integration:Prescribing workflows now embed heart-failure-adjacent protocols, pulling SGLT2 inhibitors into primary care settings previously dominated by endocrinology specialists.
- Real-Time Data Interoperability:Closed-loop insulin delivery systems are consolidating technical standards around artificial pancreas interoperability, enabling device ecosystem integration.
Market Restraints
- Peptide Fermentation Bottlenecks:Active pharmaceutical ingredient production concentrates in Denmark and China, exposing supply security to single-source biological manufacturing dependencies.
- Cold-Chain Distribution Costs:GLP-1 agonists require 2-8°C preservation through last-mile delivery, elevating logistics expenditure and limiting rural pharmacy access.
- Medicaid Fragmentation:State-level coverage variations for obesity-linked indications are creating access inequities that compress addressable patient populations in lower-income demographics.
Strategic Opportunities
- Interstitial Fluid Biosensor Convergence:Enzymatic glucose monitoring paired with predictive algorithms opens ambulatory surgical center partnerships for perioperative glycemic management.
- EU Green Deal Alignment:Pharmaceutical sustainability directives favor biodegradable packaging and reduced carbon-footprint manufacturing, rewarding early compliance with preferential formulary placement.
- Homecare Workflow Integration:Remote patient monitoring platforms are capturing data streams from continuous glucose monitors, enabling value-based contracting with Medicare Advantage plans.
Industry Challenges
- Artificial Pancreas Certification Timelines:FDA premarket approval pathways for closed-loop systems impose multi-year validation requirements that delay revenue recognition.
- Legacy Insulin Pump Interoperability:Existing installed bases operate on proprietary protocols, forcing device manufacturers to maintain backward-compatible engineering teams.
- Biosimilar Manufacturing Skill Scarcity:Basal insulin biosimilar production requires fermentation expertise concentrated among incumbent peptide specialists, constraining new entrant capacity buildout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Type 2 Diabetes Drugs and Devices Market |
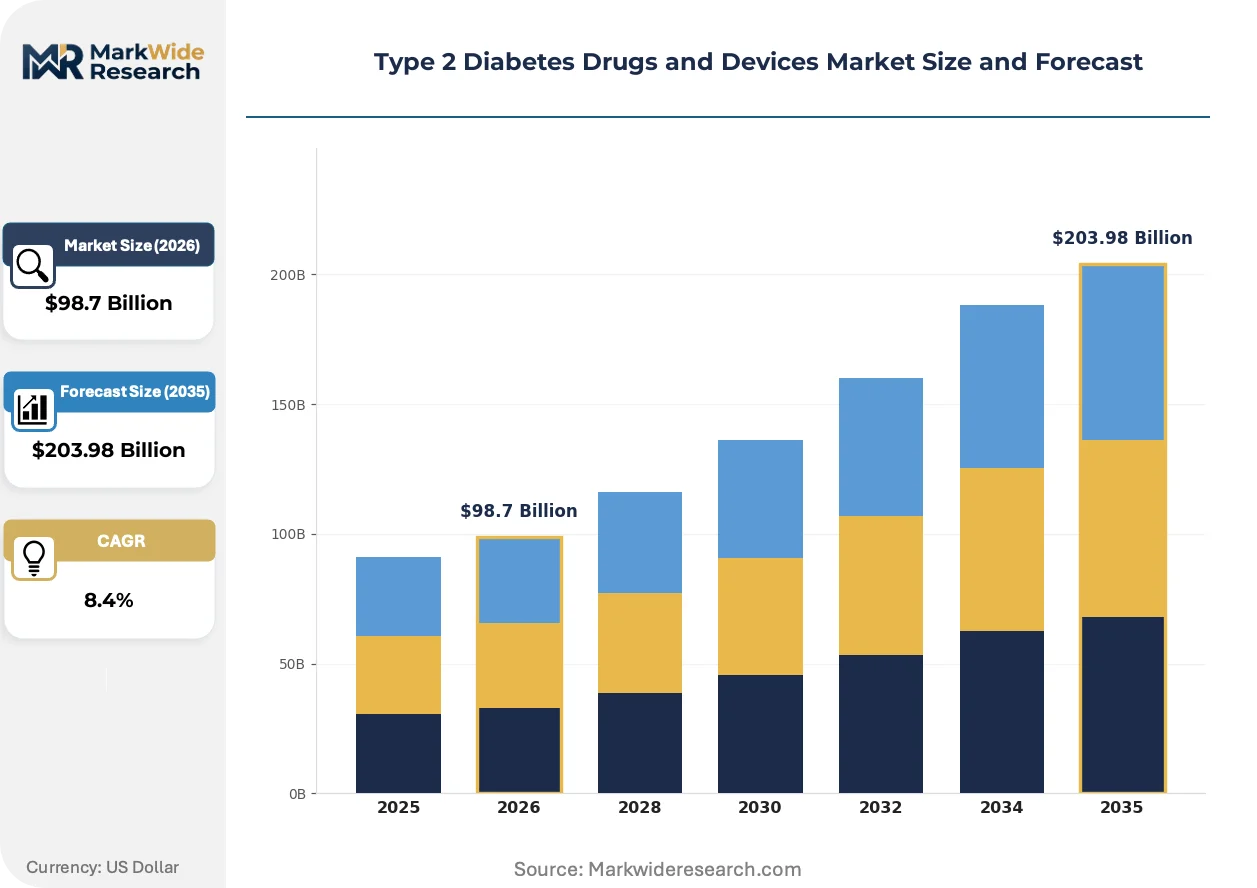
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, DPP-4 Inhibitors, SGLT2 Inhibitors Delivery Mode: Injection, Oral, Patch, Continuous Glucose Monitoring End User: Hospitals, Clinics, Homecare, Pharmacies Technology: Wearable Devices, Smartphone Apps, Insulin Pumps, Biosensors |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi, Abbott Laboratories, Medtronic plc, F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Boehringer Ingelheim, Dexcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Type 2 Diabetes Drugs and Devices Market Trends and Innovations
Device-data convergence is compressing the gap between pharmacologic intervention and automated glycemic control, with software-defined delivery systems displacing hardware-centric legacy platforms.
Dual-hormone artificial pancreas systems is consolidating technical architectures around glucagon-insulin co-formulation pumps. Pediatric endocrinology departments at academic medical centers are piloting these devices for type 1 diabetes overlap populations. The technology is consolidating competitive differentiation away from basal-bolus titration toward predictive algorithm performance.
EMA's Medical Device Regulation (MDR) is elevating clinical evidence requirements for wearable glucose sensors, forcing manufacturers to generate prospective real-world data. European notified bodies are extending review timelines for interstitial fluid enzymatic biosensors. German hospital procurement coalitions are prioritizing CE-marked devices with post-market surveillance registries, compressing vendor selection pools.
Integrated delivery networks are unbundling device procurement from pharmaceutical contracting, creating separate RFP streams for continuous glucose monitors and insulin pumps. United States health systems now negotiate volume-based agreements directly with device manufacturers, bypassing traditional distributor markups. This channel disintermediation concentrates purchasing leverage among the largest IDNs in California, Texas, and Florida.
Type 2 Diabetes Drugs and Devices Market Segmentation
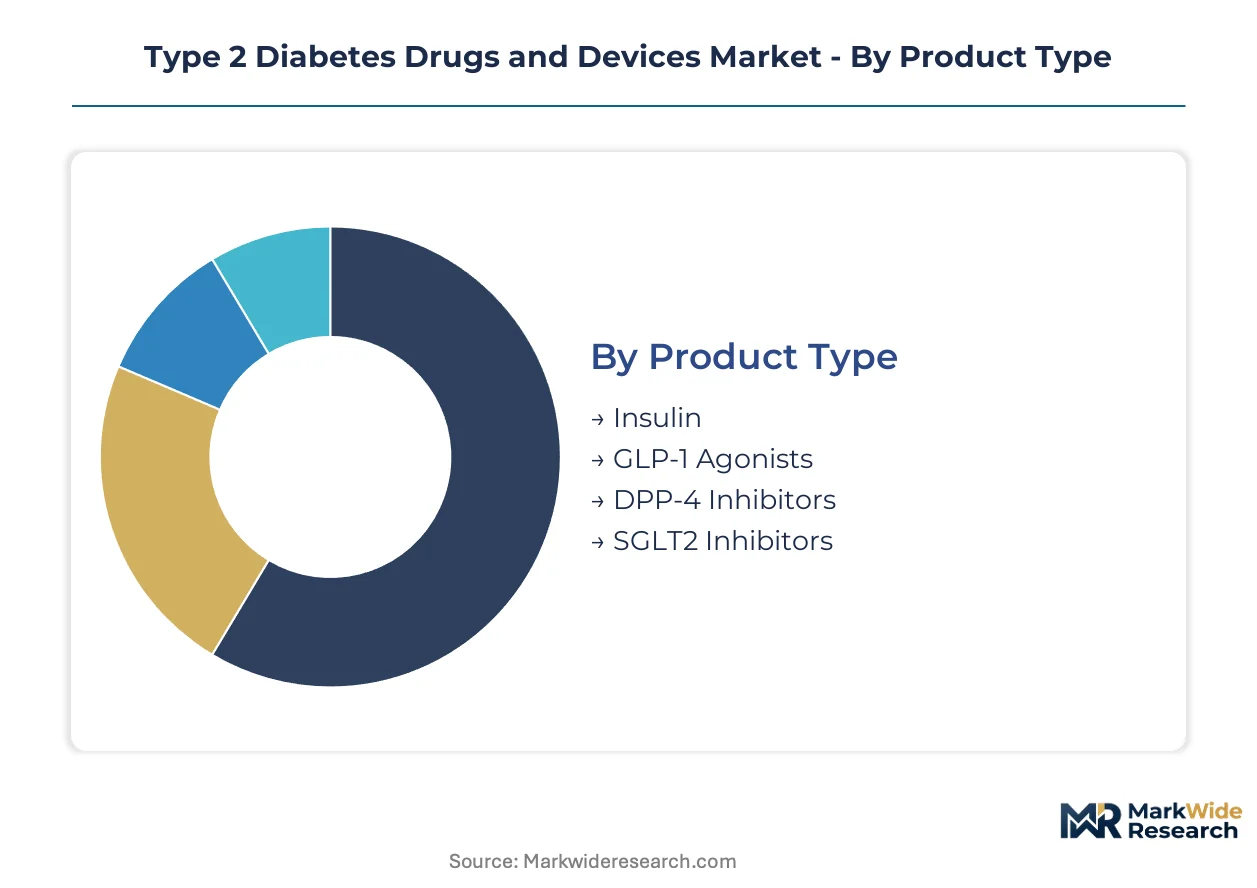
Supply chain configuration determines competitive outcomes across each segment boundary. Manufacturers align fermentation capacity, cold-chain infrastructure, and regulatory dossiers to specific product-delivery combinations, creating distinct margin profiles and entry barriers.
Product Type:
Peptide fermentation capacity concentrates in Denmark and China, anchoring supply security for biological diabetes therapies.
- Insulin:Recombinant human and analog formulations manufactured via microbial or yeast expression systems. Demand clusters in United States Medicare Part D formularies and emerging market tender programs, constrained by biosimilar price erosion in European hospital procurement.
- GLP-1 Agonists:Synthetic peptide therapeutics requiring 2-8°C cold-chain preservation from fermentation through patient administration. United States integrated delivery networks negotiate multi-year volume contracts around cardiovascular outcome data, while Medicaid state-level coverage variations fragment access in lower-income demographics.
- DPP-4 Inhibitors:Oral small-molecule enzyme inhibitors with established generic substitution in mature markets. Indian and Chinese domestic manufacturers capture volume through centralized procurement schemes.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers with heart-failure-adjacent prescribing expansion. Primary care protocols in Germany and Japan pull utilization beyond endocrinology specialty settings.
GLP-1 Agonists absorb the bulk of installed capacity; SGLT2 Inhibitors are expanding most quickly.
Delivery Mode:
Cost tier stratification separates premium device-mediated delivery from commoditized oral administration, reshaping distribution infrastructure requirements.
- Injection:Subcutaneous delivery via prefilled pens or syringes, requiring patient training and sharps disposal logistics. United States retail pharmacy chains consolidate purchasing around disposable pen formats with integrated needle safety mechanisms.
- Oral:Tablet and capsule formulations with established bioequivalence pathways for generic substitution. Volume concentrates in Indian pharmacy retail and United States 90-day mail-order fulfillment.
- Patch:Transdermal delivery systems with limited current penetration in diabetes care. Development programs at academic medical centers in Boston and Basel target closed-loop integration with continuous monitoring.
- Continuous Glucose Monitoring:Interstitial fluid enzymatic biosensors with real-time data transmission to receiver devices or smartphone applications. Medicare Advantage plans in Florida and California negotiate value-based contracts pairing sensor utilization with HbA1c outcome guarantees.
Injection retains the largest installed patient base; Continuous Glucose Monitoring is climbing the fastest.
End User:
Customer type determines procurement channel, with institutional buyers exercising consolidated purchasing power distinct from fragmented retail pharmacy demand.
- Hospitals:Inpatient glycemic management protocols and discharge planning drive formulary decisions. United States health systems in Texas and Ohio unbundle device procurement from pharmaceutical contracting, creating separate RFP streams.
- Clinics:Outpatient endocrinology and primary care prescribing with sample-driven initiation and prior authorization navigation. Nurse educator staffing ratios influence technology adoption velocity.
- Homecare:Self-administered therapy with remote patient monitoring platform integration. Medicare Advantage penetration in Arizona and Pennsylvania creates capitated reimbursement incentives for glucose control.
- Pharmacies:Retail dispensing with cold-chain last-mile requirements for biological therapies. Independent rural pharmacies face access constraints from GLP-1 agonist refrigeration mandates.
Hospitals command the largest procurement volumes; Homecare is gaining share fastest.
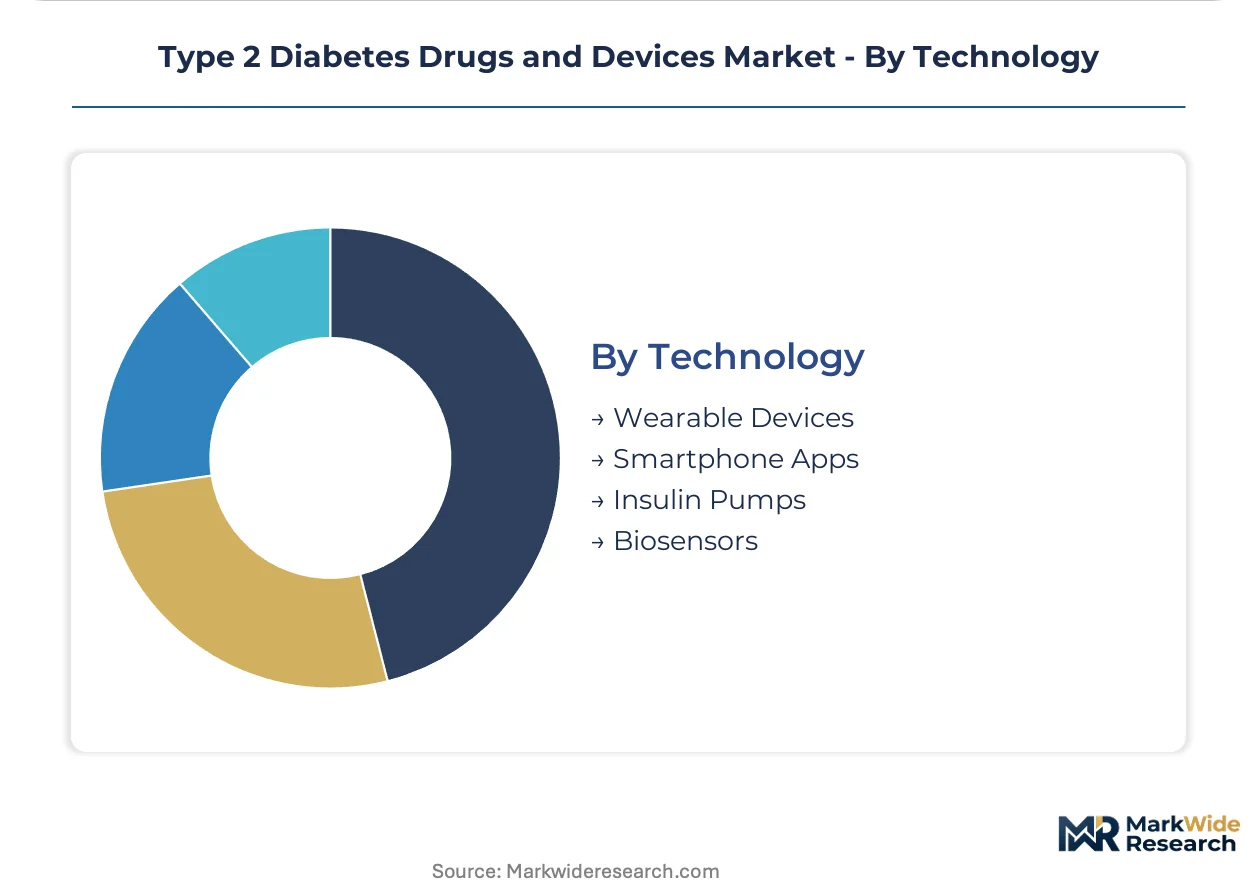
Technology:
Maturity differentiation separates FDA-cleared Class III devices from software-based wellness applications with lighter regulatory burden.
- Wearable Devices:Interstitial glucose sensors and activity monitors with skin-adhesive form factors. EMA MDR requirements extend review timelines for European market entry, favoring manufacturers with post-market surveillance registries.
- Smartphone Apps:Digital therapeutics and data visualization platforms with varying FDA enforcement discretion. Prescription digital health pathways in the United States create reimbursement codes distinct from wellness applications.
- Insulin Pumps:Electromechanical delivery systems with proprietary cartridge and tubing interfaces. Legacy installed bases in Sweden and Israel force backward-compatible engineering investment from new entrants.
- Biosensors:Enzymatic and optical glucose detection technologies with factory calibration or patient calibration requirements. German hospital procurement coalitions prioritize CE-marked devices with demonstrated accuracy in hypoglycemic range.
Insulin Pumps absorb the bulk of legacy installed base investment; Biosensors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide fermentation capacity clusters in Denmark and China anchor biological manufacturing for GLP-1 agonists, while enzymatic biosensor production concentrates in California and Bavaria. United States integrated delivery networks negotiate volume contracts that reshape procurement patterns across state Medicaid programs. German hospital coalitions prioritize CE-marked devices with post-market surveillance registries, filtering vendor pools.
United States
Medicare Advantage plans in Florida and California drive value-based contracting for continuous glucose monitoring paired with HbA1c outcome guarantees. FDA premarket approval pathways for closed-loop insulin delivery systems impose multi-year validation timelines that delay revenue recognition for device manufacturers. The Boston-Cambridge corridor anchors artificial pancreas interoperability development at academic medical centers.
Germany
Hospital procurement coalitions in North Rhine-Westphalia prioritize CE-marked continuous glucose monitors with demonstrated hypoglycemic-range accuracy. EMA Medical Device Regulation extends review timelines for interstitial fluid enzymatic biosensors, favoring manufacturers with established post-market surveillance infrastructure. The Rhine-Main region concentrates SGLT2 inhibitor prescribing expansion into primary care protocols beyond endocrinology specialty settings.
China
Centralized procurement schemes for DPP-4 inhibitors compress margins for domestic manufacturers while expanding volume access. NMPA regulatory pathways for biosimilar insulin products accelerate local production scale-up in Jiangsu and Zhejiang provinces. The Yangtze River Delta anchors microbial expression system capacity for recombinant human insulin manufacturing.
India
Domestic manufacturers capture DPP-4 inhibitor volume through centralized government procurement and pharmacy retail consolidation. CDSCO regulatory frameworks for medical devices create compliance thresholds that filter wearable glucose sensor market entry. The Mumbai-Pune corridor concentrates oral antidiabetic formulation capacity serving both domestic tender programs and export markets.
Japan
PMDA approval pathways for closed-loop insulin delivery systems align with METI industrial policy priorities for healthcare technology exports. Primary care protocols in Osaka and Nagoya pull SGLT2 inhibitor utilization beyond traditional endocrinology referral patterns. The Kanto region anchors continuous glucose monitor distribution infrastructure serving aging population diabetes management.
Type 2 Diabetes Drugs and Devices Market Competitive Landscape
Capacity expansion dominates the current landscape as peptide fermentation bottlenecks force incumbent biological manufacturers to secure captive supply chains. The vendor base stratifies across three tiers: integrated pharmaceutical-device conglomerates with dual revenue streams, pure-play biological specialists with fermentation scale advantages, and emerging biosimilar challengers facing skill scarcity barriers. M&A activity concentrates around continuous glucose monitoring assets and artificial pancreas algorithm portfolios. Geographic expansion into Medicaid-fragmented state markets represents a secondary competitive vector.
Among Danish and American biological specialists, Novo Nordisk A/S and Eli Lilly and Company occupy positions exemplifying the integrated peptide manufacturing archetype with cardiovascular outcome differentiation. Sanofi represents the diversified pharmaceutical incumbent navigating biosimilar transition pressures in basal insulin portfolios. These three entities anchor competitive dynamics around cold-chain reliability metrics and volume-based hospital procurement consolidation.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi |
| Abbott Laboratories |
| Medtronic plc |
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Boehringer Ingelheim |
| Dexcom |
| Others |
Pricing and Supply Chain Analysis
Cardiovascular outcome certification separates premium GLP-1 agonist contracts from commoditized basal insulin tenders, with integrated delivery networks in Texas and Florida extracting price concessions tied to cold-chain reliability guarantees while state Medicaid programs fragment access through obesity indication exclusions. This bifurcation concentrates margin capture among Danish and American biological specialists with captive fermentation capacity, forcing biosimilar challengers into price-competitive hospital procurement channels with compressed service bundling.
Pricing Analysis
Warranty and calibration service bundling distinguishes continuous glucose monitor contracts from unbundled insulin pump transactions, with Medicare Advantage plans in Arizona and Pennsylvania negotiating outcome-based subscriptions that wrap sensor replacement and algorithm updates into per-patient monthly fees. Price differentiation rests on hypoglycemic-range accuracy certification and FDA premarket approval tier, with CE-marked devices from German manufacturers commanding formulary preference over uncertified alternatives. Pricing pressure stems from biosimilar basal insulin entrants in European hospital procurement, tightening margins for legacy analog portfolios. Retail pharmacy chains exhibit highest price sensitivity for disposable pen formats, while academic medical centers absorb premium pricing for closed-loop interoperability.
Supply Chain Analysis
Cold-chain freight costs consume disproportionate logistics expenditure for GLP-1 agonists, with 2-8°C preservation requirements from Danish fermentation facilities through United States last-mile delivery elevating distribution spend relative to oral small-molecule alternatives. Peptide active pharmaceutical ingredient production anchors in Denmark and China, drawing from microbial expression systems and synthetic peptide synthesis capacity. Supply chain risk concentrates in single-source biological manufacturing dependencies, with Novo Nordisk's captive Danish facilities and Eli Lilly's distributed network exposing contrasting vulnerability profiles. Distribution runs through integrated delivery network direct contracting, bypassing traditional pharmaceutical wholesale markups for continuous glucose monitors and insulin pump systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over peptide fermentation capacity and forward integration into remote patient monitoring platforms determine competitive durability. Incumbents and challengers alike must secure captive supply or algorithm assets to defend margin structures.
For Market Incumbents: To counter biosimilar price erosion in basal insulin portfolios, secure additional fermentation capacity in Denmark or China through brownfield expansion or contractual offtake guarantees with peptide specialists. Deepen integration into continuous glucose monitoring algorithm development through academic medical center partnerships in the Boston-Cambridge corridor, capturing artificial pancreas interoperability standards ahead of FDA guidance finalization. For New Entrants and Emerging Players: Independent rural pharmacies in Medicaid-expansion states represent the most penetrable channel, with refrigeration infrastructure gaps creating white-space opportunity for oral small-molecule DPP-4 inhibitor formulations that bypass cold-chain requirements. Target capitated Medicare Advantage plans in Arizona and Pennsylvania with value-based contracting proposals that pair remote patient monitoring platform integration with HbA1c outcome guarantees, leveraging existing smartphone application development capacity. For Investors and Strategic Acquirers: Re-rating potential sits with artificial pancreas algorithm specialists given FDA premarket approval pathway acceleration for closed-loop interoperability standards. Long-term viability over the coming decade favors targets with demonstrated post-market surveillance registry infrastructure under EMA MDR requirements, positioned for European hospital procurement coalition qualification. Watch CMS national coverage determination expansions for therapeutic continuous glucose monitoring in obesity-linked indications as the inflection signal for institutional procurement scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Captive 2-8°C distribution networks secure GLP-1 agonist formulary placement against supply reliability failures. |
| Artificial Pancreas Algorithm Acquisition | FDA interoperability standards consolidation rewards early movers with closed-loop system ecosystem lock-in. |
| Post-Market Surveillance Registry Development | EMA MDR compliance accelerates CE marking timelines for enzymatic biosensor European market entry. |
| Medicare Advantage Value-Based Contracting | Capitated reimbursement structures in Florida and California create outcome-guarantee revenue streams. |
| Peptide Fermentation Capacity Buildout | Biological manufacturing scale in Denmark and China anchors supply security against single-source bottlenecks. |
Research Methodology
Document review covered FDA premarket approval filings, EMA MDR submission databases, CMS national coverage determinations, and hospital procurement RFP archives, complemented by interviews with formulary directors at integrated delivery networks, regulatory affairs leads at device manufacturers, and payer access specialists at Medicare Advantage plans. Secondary validation drew from ClinicalTrials.gov protocol registrations, GPO contract databases, and SEC 10-K pharmaceutical segment disclosures. Bottom-up patient population modeling and top-down prescription volume triangulation anchored market sizing across the analysis window.
Segmentation outputs reflect treatment line stratification, delivery mode differentiation, end-user procurement channel, and regional regulatory cluster variations across the projection horizon. CAGRs derived from epidemiological prevalence trajectories, patent expiration sequencing, and reimbursement pathway expansion modeling. Forecast inputs incorporated GLP-1 agonist cardiovascular outcome trial readouts, SGLT2 inhibitor heart-failure protocol adoption curves, and continuous glucose monitor Medicare Advantage penetration rates.
Caveats apply where state-level Medicaid fragmentation, peptide fermentation supply disruptions, or FDA artificial pancreas interoperability standard delays could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Global Non-Invasive Glucose Meter Market
Diabetes Care
Russia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
Australia Insulin Infusion Pump Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
North America Insulin Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market