
 Artificial Intelligence in Diabetes Management Market | 2026-2036
Artificial Intelligence in Diabetes Management Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Diabetes Management Market Analysis
Modular glucose management ecosystems is pivoting buyer choice away from standalone devices toward integrated platforms. Dexcom Inc anchors its position through sensor-to-cloud connectivity architecture. Abbott Laboratories leverages freestyle data streams to sustain competitive differentiation. Medtronic plc dominates insulin algorithm automation through its closed-loop system investments.
Artificial intelligence in diabetes management deploys machine learning models on continuous glucose monitor data streams, predictive algorithms, and natural language processing interfaces to forecast glycemic events and automate insulin dosing decisions with therapeutic precision. Continuous glucose monitors and insulin delivery systems command the dominant product value pools, while mobile applications capture the fastest expansion trajectory due to lower deployment barriers and direct-to-consumer accessibility. Machine learning and predictive analytics concentrate development investment, whereas natural language processing remains nascent in patient-facing education tools.
FDA Software as a Medical Device guidance, HIPAA privacy mandates, and EU MDR certification requirements collectively determine market access timelines and data governance standards for algorithm-based diabetes tools. The EU AI Act introduces additional conformity obligations for clinical decision-support systems deployed across European healthcare networks. Stakeholders must monitor evolving reimbursement codes for automated insulin dosing and remote patient monitoring to align commercial strategy with payer recognition.
Market Dynamics
Modular glucose management ecosystems are restructuring competitive positioning around sensor-to-cloud connectivity architectures rather than standalone device sales, forcing manufacturers to integrate continuous data streams with automated insulin delivery algorithms.
Growth Catalysts
- FDA Software as a Medical Device guidance:Clearer clearance pathways accelerate algorithm-based product launches for predictive glucose monitoring systems.
- Hospital-based endocrinology departments:Clinical adoption of AI-augmented decision support is expanding across tertiary care networks in the United States, Germany, and Japan.
- Machine learning on CGM data streams:Real-time pattern recognition capabilities enable automated hypoglycemia prediction with therapeutic precision.
Market Restraints
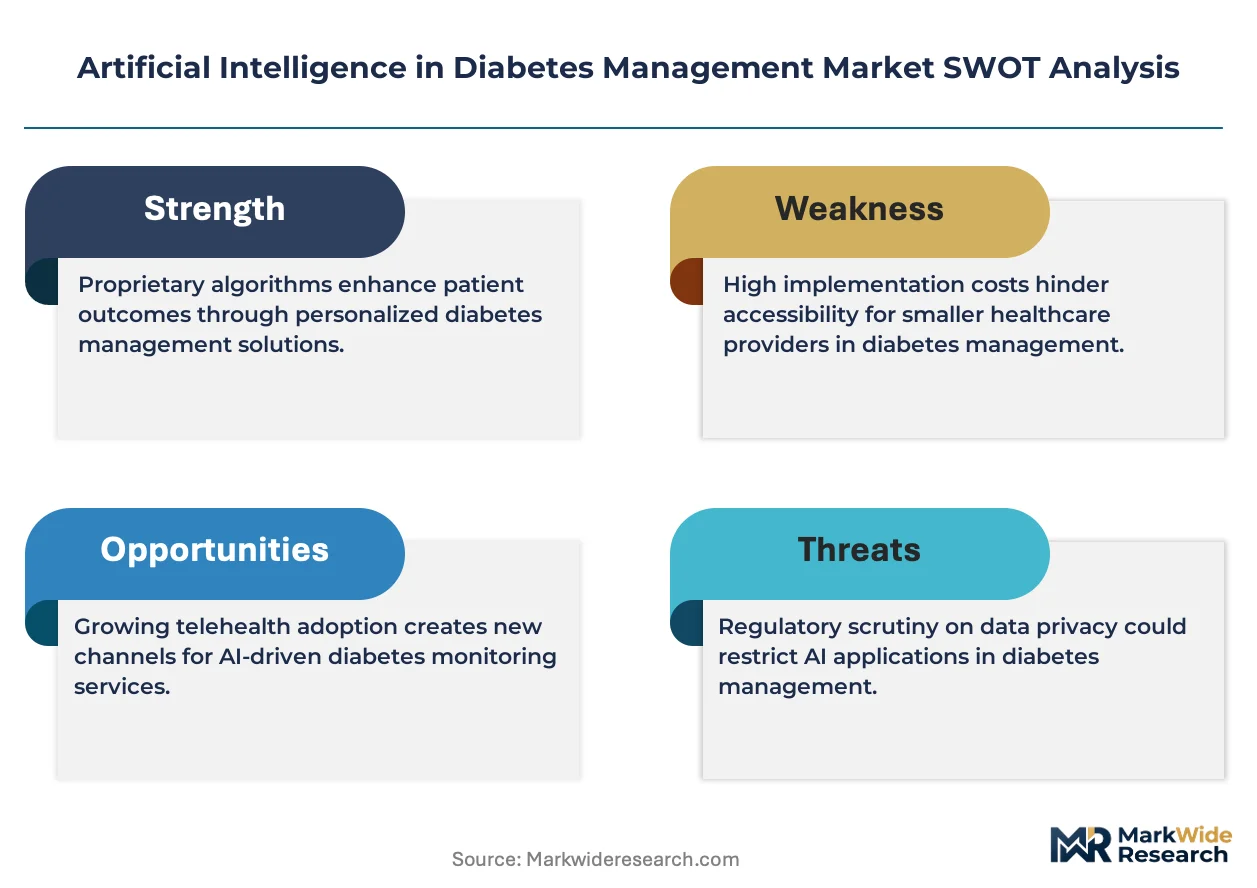
- EU MDR certification timelines:Extended conformity assessment periods delay algorithm deployment across European healthcare networks.
- HIPAA privacy mandates:Cross-border data governance restrictions complicate cloud-based glucose analytics platform architectures.
- Sensor manufacturing concentration:Supply vulnerability exists in specialized glucose oxidase membrane production facilities.
Strategic Opportunities
- Direct-to-consumer mobile applications:Lower deployment barriers enable algorithm accessibility outside traditional clinical procurement channels.
- EU AI Act compliance infrastructure:Clinical decision-support system obligations create first-mover advantages for certified algorithm vendors.
- Natural language processing interfaces:Patient-facing education tools represent underdeveloped white space in automated diabetes coaching.
Industry Challenges
- Interoperability with legacy insulin pumps:Integration friction delays closed-loop system adoption in existing patient populations.
- Algorithm validation talent scarcity:Shortage of clinical data scientists with endocrinology domain expertise constrains development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Diabetes Management Market |
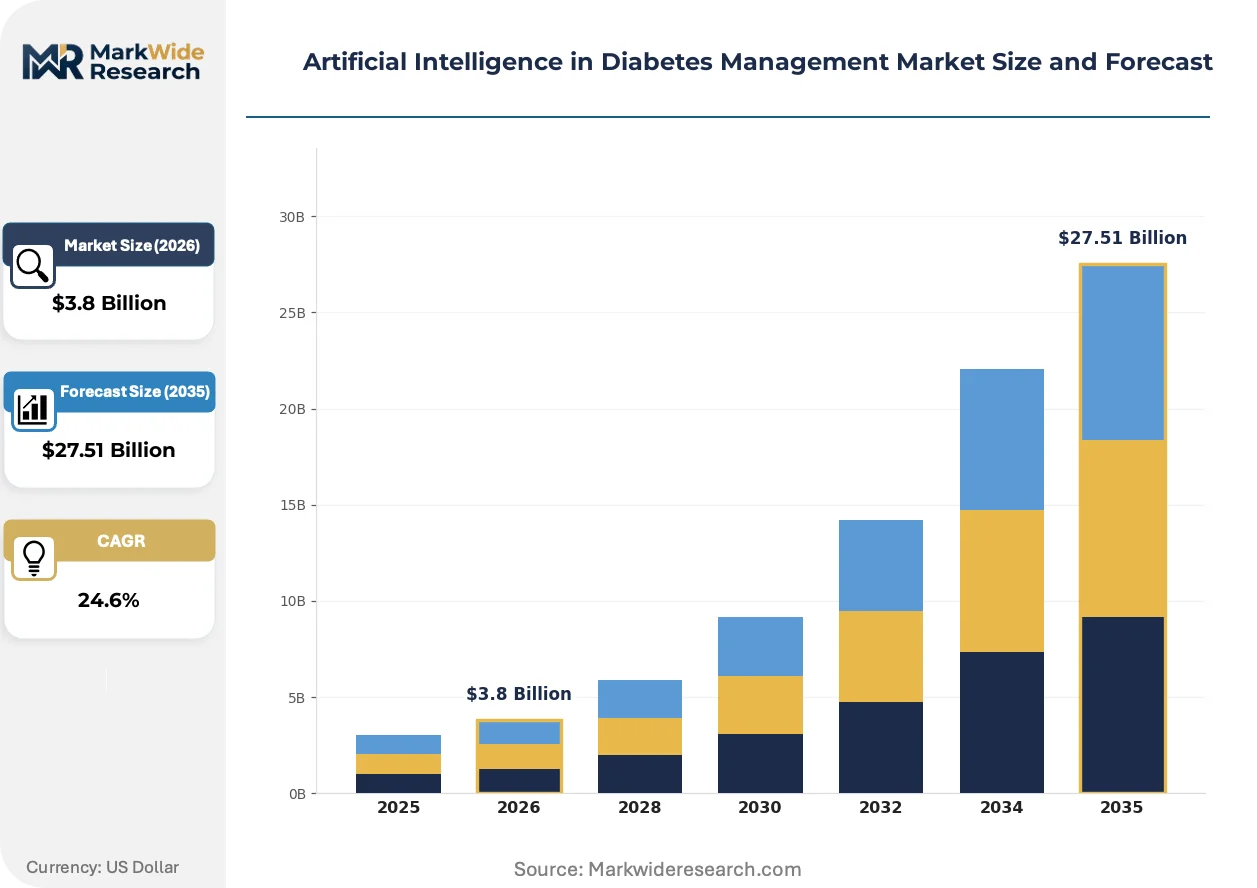
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Continuous Glucose Monitors, Insulin Delivery Systems Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Computer Vision Application: Remote Monitoring, Data Management, Personalized Therapy, Patient Education End User: Healthcare Providers, Patients, Research Institutions, Pharmacies |
| Companies Covered | Medtronic plc, Dexcom Inc, Abbott Laboratories, F. Hoffmann-La Roche Ltd, Insulet Corporation, Tandem Diabetes Care Inc, IBM Corporation, Alphabet Inc, Glooko Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Diabetes Management Market Emerging Trajectories
Continuous glucose monitor data architectures are displacing episodic blood glucose testing as the foundational input for therapeutic decision-making across diabetes care pathways.
Edge computing deployment on wearable glucose sensors is electrifying real-time insulin dosing automation by enabling on-device algorithm execution without cloud latency. Pediatric endocrinology clinics are adopting these systems fastest due to hypoglycemia risk sensitivity. This distributed processing architecture is compressing the competitive relevance of smartphone-tethered glucose applications.
EU AI Act risk classification for clinical decision-support systems is mandating conformity assessment procedures that extend market access timelines for algorithm-based diabetes tools. European notified bodies are prioritizing high-risk medical device AI evaluations over lower-risk wellness applications. Closed-loop insulin delivery systems face the most stringent documentation requirements, prompting manufacturers to front-load clinical validation investments.
Subscription-based remote patient monitoring contracts are displacing per-device procurement models among integrated delivery networks. Endocrinology practices are unbundling hardware acquisition from algorithm access fees to align costs with patient enrollment scale. This shift is most visible in United States Medicare Advantage contracts where capitated reimbursement structures favor ongoing monitoring relationships over capital equipment purchases.
Artificial Intelligence in Diabetes Management Market Segmentation
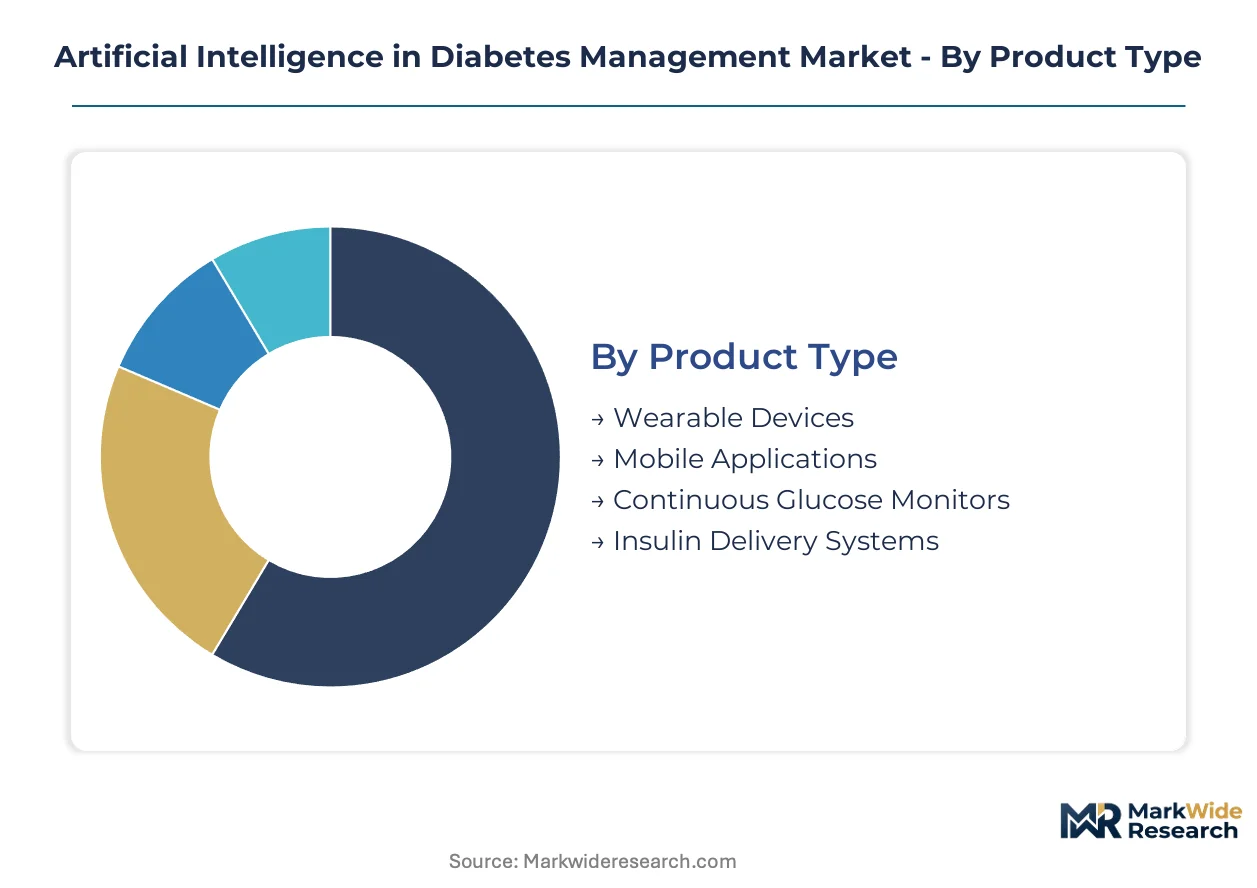
AI-enabled diabetes management segments around distinct technology maturity curves and procurement pathways. Product type determines hardware investment thresholds, while technology selection shapes algorithm validation requirements and regulatory clearance complexity.
Product Type:
Procurement patterns split between capital-intensive hospital systems and direct-to-consumer channels, with connectivity architecture now outweighing standalone device specifications in buyer evaluation.
- Continuous Glucose Monitors:Sensor-to-cloud data streams form the foundational input layer for automated insulin dosing algorithms. Hospital-based endocrinology departments in the United States and Germany concentrate demand as closed-loop integration becomes standard of care.
- Insulin Delivery Systems:Closed-loop pumps with embedded machine learning execute real-time dosing adjustments based on predictive glucose trajectories. FDA Software as a Medical Device guidance shapes clearance timelines for algorithm-automated delivery mechanisms.
- Wearable Devices:Multi-sensor wristbands and patches capture auxiliary biometric signals beyond glucose.
- Mobile Applications:Direct-to-consumer algorithm access bypasses traditional clinical procurement with lower deployment barriers.
Continuous Glucose Monitors lead on scale; Mobile Applications lead on momentum.
Technology:
Development investment concentrates where regulatory pathways are clearest and clinical validation datasets are deepest.
- Machine Learning:Supervised learning models trained on longitudinal CGM datasets enable hypoglycemia prediction with therapeutic precision. Research institutions in Japan and the United States drive algorithm refinement through multi-site clinical trials.
- Predictive Analytics:Time-series forecasting on glucose trajectories supports automated dosing decisions with quantified uncertainty bounds. Healthcare providers prioritize these tools for reducing severe hypoglycemic events in pediatric populations.
- Natural Language Processing:Patient-facing chatbots and coaching interfaces remain nascent in clinical deployment.
- Computer Vision:Image recognition for meal logging and insulin pen dosing verification sees limited integration.
Machine Learning commands the deepest investment; Predictive Analytics shows the steepest clinical adoption curve.
Application:
End-user workflow integration determines algorithm deployment priority, with reimbursement codes favoring continuous monitoring over episodic interventions.
- Remote Monitoring:Cloud-based glucose analytics platforms enable endocrinologists to intervene on deteriorating trends between office visits. Medicare Advantage capitated contracts in the United States accelerate subscription-based monitoring adoption.
- Personalized Therapy:Patient-specific insulin sensitivity models adjust dosing algorithms to individual metabolic patterns. Pharmacies in Germany leverage these tools to support medication adherence programs.
- Data Management:Interoperable glucose data repositories face HIPAA governance constraints on cross-border architectures.
- Patient Education:Automated coaching interfaces occupy underdeveloped white space with limited payer recognition.
Remote Monitoring dominates reimbursement capture; Personalized Therapy expands most quickly through pharmacy channel partnerships.
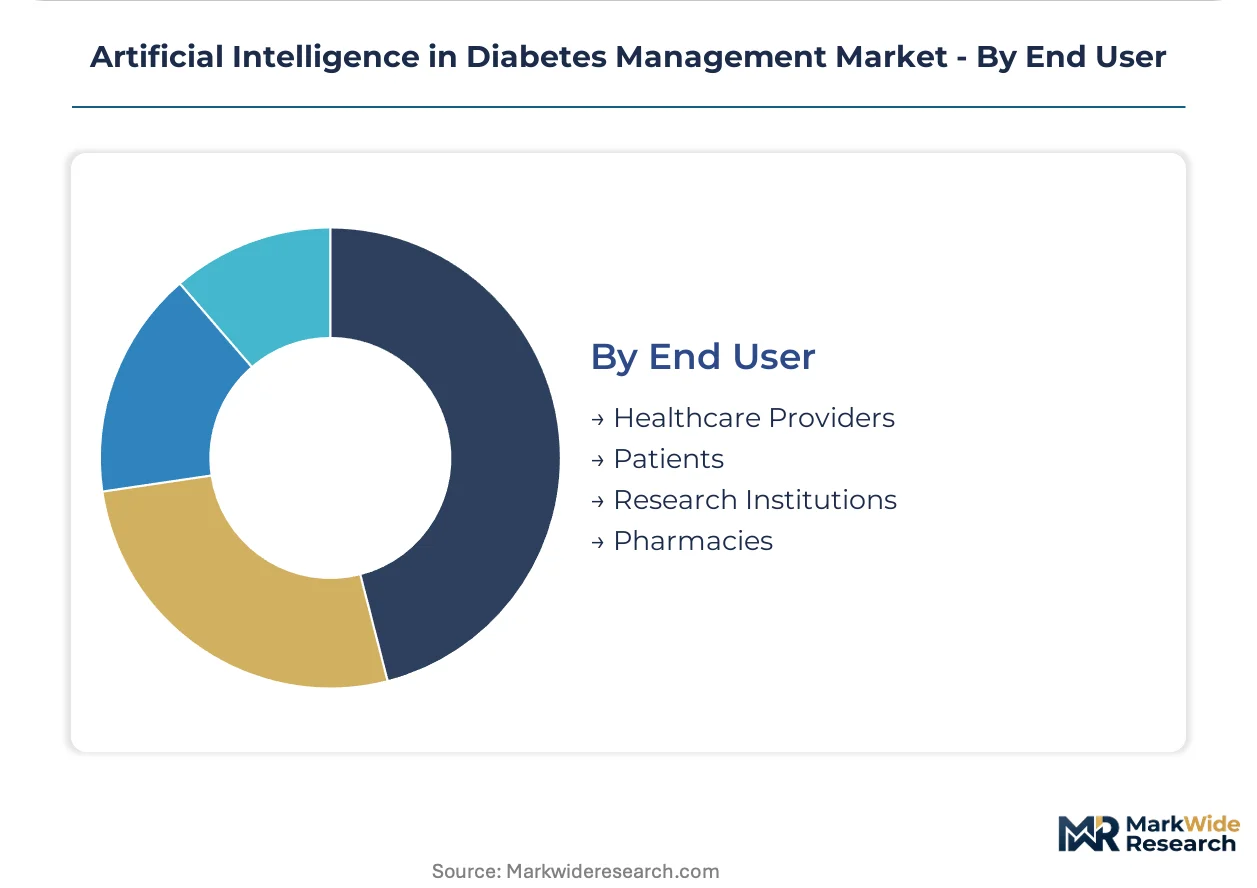
End User:
Budget authority and risk tolerance vary sharply across stakeholder types, shaping algorithm pricing and validation requirements.
- Healthcare Providers:Hospital endocrinology departments demand FDA-cleared decision-support tools with documented outcome improvements. Tertiary care networks in the United States and Japan prioritize closed-loop system integration.
- Patients:Direct purchasing of algorithm-enabled applications bypasses institutional procurement cycles. EU AI Act risk classification creates compliance uncertainty for consumer-facing diabetes tools in European markets.
- Research Institutions:Academic medical centers generate training datasets for algorithm development.
- Pharmacies:Retail health settings deploy glucose management tools for chronic care program differentiation.
Healthcare Providers anchor revenue concentration; Patients gain share fastest through direct-to-consumer algorithm access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Continuous glucose monitoring technology achieved commercial scale in the United States during the early 2000s, with subsequent algorithmic innovation spreading to Germany and Japan through academic medical center partnerships and regulatory harmonization efforts.
United States
Hospital-based endocrinology departments in Boston and the San Francisco Bay Area drive clinical validation of machine learning insulin dosing algorithms. FDA Software as a Medical Device guidance provides clearer clearance pathways for predictive glucose monitoring systems than comparable jurisdictions. Medicare Advantage capitated contracts in California and Florida accelerate subscription-based remote patient monitoring adoption over per-device procurement.
Germany
Pharmacy channel partnerships in Bavaria and North Rhine-Westphalia expand personalized therapy algorithm deployment for medication adherence programs. EU MDR certification requirements extend conformity assessment timelines for closed-loop insulin delivery systems. The Heidelberg and Munich medical technology clusters concentrate sensor-to-cloud connectivity development for integrated glucose management platforms.
Japan
Pediatric endocrinology clinics in Tokyo and Osaka adopt edge computing glucose sensors fastest due to hypoglycemia risk sensitivity. METI funding programs support multi-site clinical trials for algorithm refinement on longitudinal CGM datasets. The Kansai region anchors manufacturing partnerships between medical device producers and semiconductor foundries for on-device processing architectures.
United Kingdom
NHS integrated care systems in London and Manchester pilot AI-augmented decision support for tertiary diabetes care networks. MHRA alignment with FDA Software as a Medical Device frameworks accelerates algorithm-based product launches following US clearance. The Oxford-Cambridge arc concentrates academic medical center research generating training datasets for hypoglycemia prediction models.
Switzerland
Swissmedic certification procedures attract algorithm vendors seeking streamlined European market access for clinical decision-support systems. Basel and Zurich host pharmaceutical-diagnostic partnerships integrating glucose analytics into chronic care program differentiation. The country's data governance standards facilitate cross-border cloud architectures for remote monitoring platforms serving EU patient populations.
Artificial Intelligence in Diabetes Management Market Vendor Landscape
Premium-margin players sit above commodity-margin players across algorithm validation depth and regulatory clearance breadth. The vendor base stratifies into three tiers: integrated closed-loop system manufacturers, sensor-to-cloud connectivity specialists, and direct-to-consumer algorithm developers. Three archetypes dominate strategic positioning: medical device incumbents leveraging hardware installed bases, technology platform entrants exploiting cloud infrastructure scale, and digital health startups capturing direct-patient relationships. Competitive moves concentrate on strategic partnerships for interoperability certification and portfolio diversification into adjacent metabolic conditions.
Within the integrated system tier, Medtronic plc and Dexcom Inc exemplify divergent approaches to sensor-to-cloud architecture. Medtronic anchors the insulin delivery automation segment through closed-loop algorithm investments. Dexcom occupies a position emphasizing continuous data stream connectivity over hardware tethering. Among technology platform entrants, Alphabet Inc represents the cloud-scale archetype applying machine learning infrastructure to glucose prediction challenges. These three companies collectively illustrate how competitive positioning separates hardware-captive from platform-agnostic strategies.
| Leading Market Players |
|---|
| Medtronic plc |
| Dexcom Inc |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Insulet Corporation |
| Tandem Diabetes Care Inc |
| IBM Corporation |
| Alphabet Inc |
| Glooko Inc |
| Others |
Supply Flow & Price Mechanics
Edge computing migration toward on-device glucose algorithm execution is simultaneously compressing cloud infrastructure costs and concentrating semiconductor procurement around specialized foundry partnerships in Japan and Taiwan. This hardware transition rewards manufacturers with captive sensor production while squeezing margins for smartphone-tethered application developers lacking vertical control over MEMS fabrication.
Pricing Analysis
Subscription-based algorithm access layered over hardware leasing dominates procurement contracts among United States integrated delivery networks. Price differentiation separates FDA-cleared closed-loop systems with documented outcome improvements from direct-to-consumer wellness applications lacking payer reimbursement codes. Cost compression in the mobile application tier is intensifying as algorithm commoditization erodes first-mover premiums. Hospital endocrinology departments demonstrate lowest price sensitivity due to bundled reimbursement structures, while uninsured direct-pay patients face highest cost barriers to continuous monitoring adoption.
Supply Chain Analysis
Glucose oxidase membrane supply rests on German and Japanese specialty chemical producers with concentrated enzymatic coating expertise. Raw material dependencies span platinum electrode substrates, biocompatible adhesives, and CMOS image sensors for optical glucose detection. Single-source vulnerability in MEMS foundry capacity for sub-micron sensor fabrication creates procurement bottlenecks during demand surges. Distribution runs through hospital GPO contracts in the United States, pharmacy chain central purchasing in Germany, and direct-to-consumer channels for mobile algorithm subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Artificial Intelligence in Diabetes Management Market compounds steadily as algorithm-augmented glucose monitoring becomes standard of care in tertiary diabetes centers across developed healthcare systems.
For Market Incumbents: Lock in interoperability certification with legacy insulin pump installed bases to forestall displacement by closed-loop challengers. Deepen backward integration into glucose oxidase membrane production to insulate margins from specialty chemical supply shocks. Prioritize FDA breakthrough device designation for predictive hypoglycemia algorithms to extend clearance moats against software-only entrants lacking clinical validation infrastructure. For New Entrants and Emerging Players: Capture natural language processing interfaces for automated diabetes coaching, the most penetrable white space with limited incumbent algorithm investment. Target direct-to-consumer pharmacy distribution partnerships in Germany where medication adherence programs seek differentiated chronic care tools. Pursue EU AI Act conformity pre-certification to establish first-mover positioning ahead of larger platform vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among sensor-to-cloud connectivity specialists lacking closed-loop insulin delivery integration. Long-term viability favors algorithm developers with locked hospital system partnerships and documented outcome improvements in pediatric populations. Watch Medicare Advantage capitated contract expansion rates as the signal for subscription revenue durability across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Clearer clearance pathways accelerate predictive glucose monitoring launches ahead of EU MDR timelines. |
| Hospital System Partnership | Integrated delivery network contracts in California and Florida anchor subscription revenue visibility. |
| Sensor-to-Cloud Platform Integration | Dexcom and Abbott connectivity architectures force modular ecosystem participation from insulin pump rivals. |
| EU AI Act Conformity Pathway | Swissmedic and German notified body prioritization creates certified vendor advantages in European markets. |
| Reimbursement Strategy | Medicare remote patient monitoring codes determine algorithm accessibility outside self-pay populations. |
Methodological Framework
Multiple input streams — structured interviews with hospital endocrinology department heads, biomedical engineers at CGM manufacturers, and pharmacy chain chronic care program directors — were reconciled against FDA 510(k) clearance databases, CMS reimbursement code filings, and EU MDR notified body registration records. Secondary validation drew from hospital procurement database extracts, GPO contract terms, and METI-funded clinical trial registries in Japan. Bottom-up patient enrollment projections and top-down healthcare expenditure allocations were triangulated to anchor volume estimates.
Data-stream reconciliation across product type, technology maturity, application workflow integration, and end-user budget authority shaped the analytical framework over the projection horizon. CAGRs were derived from algorithm adoption curves segmented by regulatory clearance status and payer recognition tier. Forecast inputs incorporated FDA guidance evolution timelines, EU AI Act implementation pacing, and sensor manufacturing capacity expansion announcements from Kansai region semiconductor partnerships.
Regulatory clearance delays, reimbursement code retraction, and glucose sensor component supply disruptions are the dominant revision risks to modeled adoption trajectories. Forecasts embed assumptions around sustained Medicare Advantage capitation growth and stable EU MDR conformity assessment capacity. A small set of named triggers — FDA breakthrough device designation velocity, German pharmacy algorithm formulary placement rates, and Japanese pediatric clinic edge computing deployment pace — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
India Insulin Infusion Pump Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Diabetic Foot Ulcer Treatment Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
Digital Diabetes Management Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market