
 Digital Diabetes Care Market | 2026-2036
Digital Diabetes Care Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Diabetes Care Market Insights
Market Context
The shift from single-source glucose meter contracts to multi-source digital platform procurement is recalibrating how health systems evaluate vendors. Abbott Laboratories leverages its FreeStyle Libre ecosystem to anchor hospital formulary decisions across integrated delivery networks. Dexcom Inc. competes through direct-to-consumer subscription channels that bypass traditional durable medical equipment distributors. Medtronic Plc differentiates by extending its insulin pump data streams into third-party analytics dashboards, reducing patient platform switching.
Technical Definition and Structural Segments
Digital diabetes care encompasses software-enabled systems that capture, transmit, and analyze glycemic data to inform therapeutic decisions, typically integrating continuous glucose monitor sensors transmitting glucose readings every one to five minutes via Bluetooth to cloud-based algorithms. These systems serve commercial and clinical purposes by reducing hypoglycemic events, enabling remote titration of insulin doses, and generating longitudinal datasets for population health management. Continuous glucose monitors command the dominant revenue share within product type segmentation due to hardware-software bundling and recurring sensor replacement cycles. AI algorithms within technology segmentation represent the fastest-expanding margin pool as payers increasingly require predictive hypoglycemia alerts to justify reimbursement. Telemedicine solutions show mature growth trajectories in markets where virtual care parity laws have existed since the pandemic period.
Regulatory Frame and Outlook
FDA software-as-a-medical-device pathways, EU MDR Class IIa requirements for glucose monitoring apps, and HIPAA security rule enforcement collectively elevate compliance costs for new entrants while advantaging incumbents with established quality management systems. The EU AI Act's risk classification for medical decision-support algorithms will force additional conformity assessments on machine-learning-enabled insulin dosing recommendations. Stakeholders must monitor whether CMS national coverage determinations for continuous glucose monitoring in non-insulin-using Type 2 populations expand addressable demand or entrench existing beneficiary criteria.
Market Dynamics
The transition from episodic glucose monitoring to continuous data streaming is restructuring procurement economics around subscription-based sensor replacement rather than capital equipment acquisition.
Growth Catalysts
- EU MDR Class IIa pathway:Streamlined software-as-a-medical-device clearances accelerate time-to-market for glucose monitoring algorithms, reducing regulatory friction for algorithm developers.
- Hospital-at-home expansion:US health systems deploy remote glycemic monitoring for post-acute transitions, creating institutional demand for integrated sensor-platform bundles.
- Statutory reimbursement frameworks:Germany's DiGA pathway establishes predictable procurement volumes for digital therapeutics, anchoring European demand visibility.
Market Restraints
- Sensor manufacturing concentration:Polymer substrate and enzyme electrode supply chains cluster in East Asian contract manufacturers, exposing hardware vendors to single-source risk.
- HIPAA security rule enforcement:Cloud-based glucose data platforms face escalating compliance audit costs that disproportionately burden sub-scale software developers.
- Calibration-free optical substitutes:Non-invasive spectroscopic glucose measurement technologies threaten to compress the addressable market for invasive continuous monitors if clinical validation succeeds.
Strategic Opportunities
- Type 2 non-insulin populations:CMS national coverage determination expansion into this beneficiary category would unlock Medicare reimbursement for lifestyle-intervention glucose monitoring.
- AI-integrated insulin dosing:Machine learning algorithms that recommend basal rate adjustments represent convergence territory between continuous glucose monitors and automated insulin delivery systems.
- Pharmacy channel direct distribution:Retail pharmacy chains in the United States are building specialty diabetes care clinics that bypass traditional durable medical equipment intermediaries.
Industry Challenges
- Interoperability certification backlog:FDA 510(k) submissions for third-party data integration face extended review timelines as the agency scales software evaluation capacity.
- Legacy electronic health record integration:Hospital IT departments struggle with HL7 FHIR implementation for real-time glucose data ingestion into existing clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Diabetes Care Market |
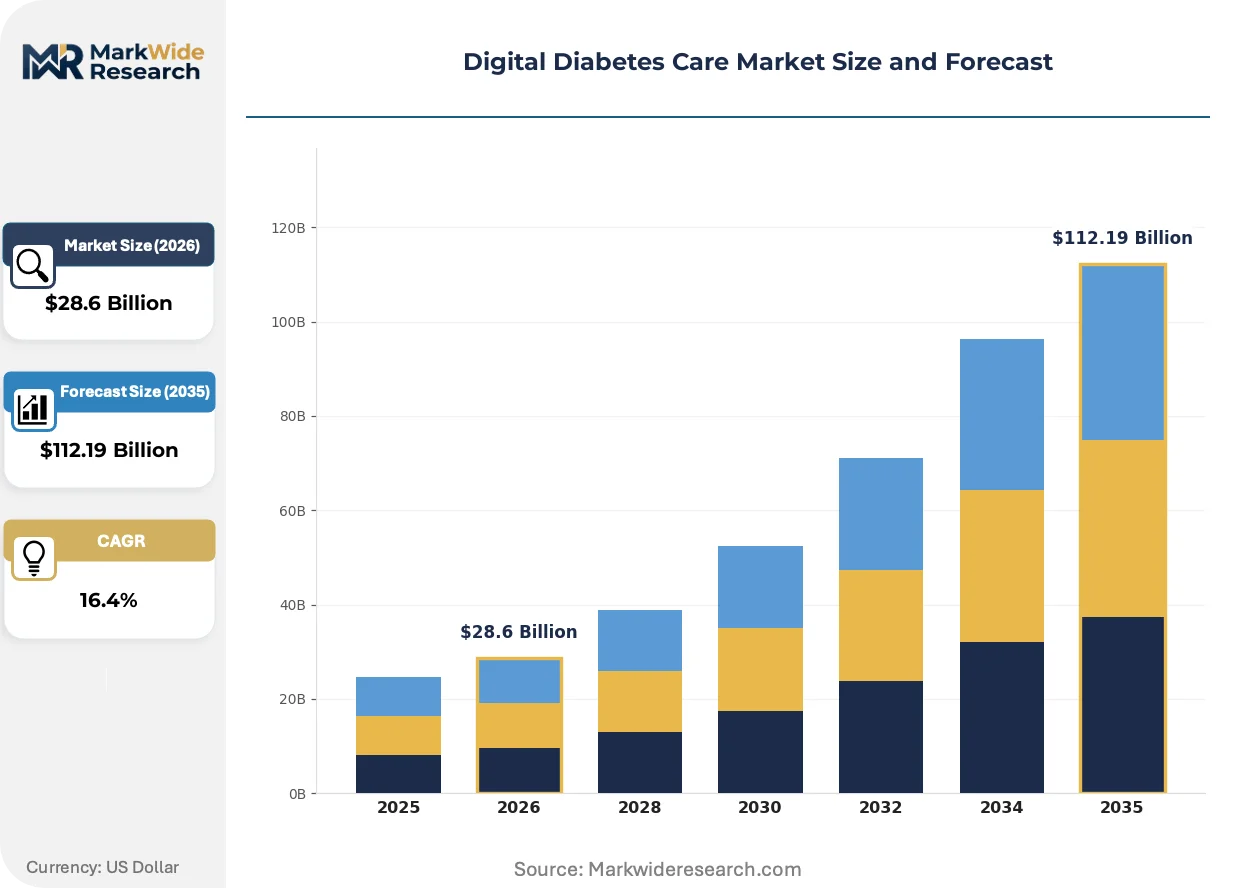
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Continuous Glucose Monitors, Telemedicine Solutions, Wearable Devices Technology: Cloud Computing, AI Algorithms, Data Analytics, Bluetooth Connectivity End User: Patients, Healthcare Providers, Caregivers, Insurance Companies Delivery Mode: Software as a Service, On-premises Software, Mobile Platforms, Web-based Solutions |
| Companies Covered | Abbott Laboratories, Medtronic Plc, F. Hoffmann-La Roche Ltd, Dexcom Inc., Insulet Corporation, Bayer AG, Ascensia Diabetes Care Holdings AG, Tandem Diabetes Care Inc., LifeScan Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Diabetes Care Market Trends and Innovations
Algorithmic prediction of hypoglycemic events is displacing reactive alert systems as the primary software differentiator in competitive platform evaluations.
Multi-day wear adhesive systems with extended glucose oxidase stability are electrifying sensor economics by reducing per-patient annual consumable costs. Integrated delivery networks in the United States are adopting these platforms at accelerating pace for inpatient-to-outpatient transition programs. The technology is electrifying margin structures for manufacturers who can maintain enzymatic accuracy across 14-day wear periods.
The EU AI Act's risk classification for medical decision-support algorithms imposes additional conformity assessments on machine-learning-enabled insulin dosing recommendations. European notified bodies are expanding technical review capacity to address Class IIa software certification backlogs. Glucose prediction modules with autonomous dose suggestion capabilities face the steepest compliance cost escalation.
Self-funded employers in the United States are contracting directly with continuous glucose monitor manufacturers for workforce diabetes management programs, disintermediating traditional pharmacy benefit managers. This channel compression concentrates purchasing power among large employers with actuarial capacity to measure medical cost reduction. The shift is most visible in technology and financial services sectors with self-insured health plans exceeding 50,000 covered lives.
Digital Diabetes Care Market Segmentation
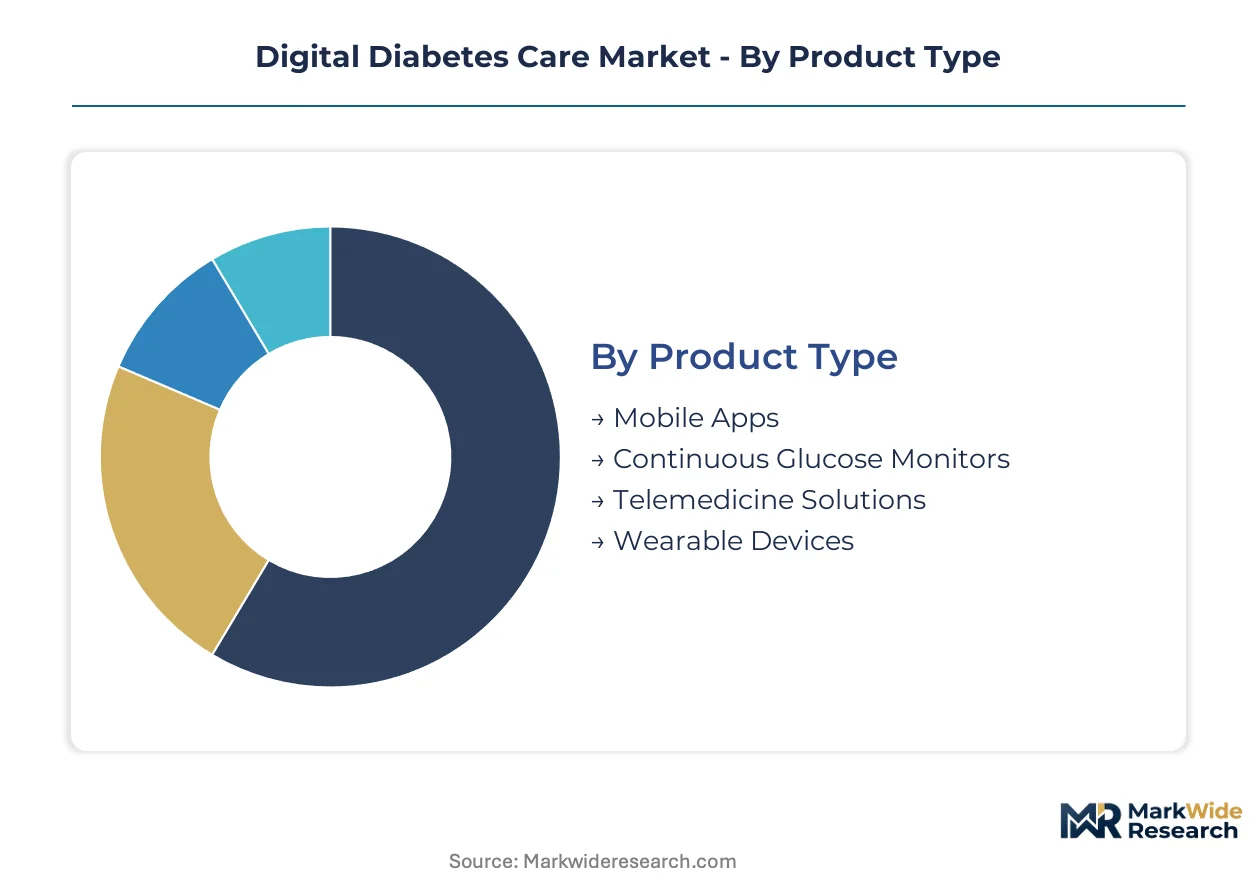
Procurement decisions in digital diabetes care diverge sharply by segment, with hardware-software bundles demanding long-term capital commitments while pure software plays require minimal fixed assets. Understanding where capital concentrates helps vendors align R&D investment with buyer budget cycles.
Product Type:
Continuous glucose monitors and wearable hardware demand the heaviest upfront manufacturing investment, while software-only segments scale with marginal engineering costs.
- Continuous Glucose Monitors:These systems integrate electrochemical sensors with polymer substrates and enzyme electrodes, transmitting readings every one to five minutes via Bluetooth. Hospital systems in the United States anchor procurement volumes through integrated delivery network formulary contracts, though sensor replacement economics dominate lifetime value calculations. Continuous glucose monitors absorb the bulk of installed capacity; AI Algorithms is expanding most quickly.
- Telemedicine Solutions:Virtual care platforms enabling remote insulin titration and clinician consultations leverage existing video infrastructure. Germany's statutory DiGA reimbursement pathway concentrates European demand visibility, creating predictable procurement volumes for platform vendors.
- Mobile Apps:Smartphone applications for glucose logging and dietary tracking require minimal hardware integration.
- Wearable Devices:Smartwatches and fitness trackers with glucose monitoring capabilities extend consumer electronics supply chains into medical-grade validation.
Hardware segments lock in recurring sensor revenues; software segments compete on algorithm accuracy and regulatory clearance speed.
Technology:
Cloud infrastructure and machine learning models attract venture funding at premium valuations, while connectivity standards commoditize.
- AI Algorithms:Machine learning modules predicting hypoglycemic events and recommending basal rate adjustments process continuous glucose data streams in real time. FDA software-as-a-medical-device pathways and EU AI Act risk classifications impose escalating compliance costs on autonomous dosing recommendations.
- Cloud Computing:HIPAA-compliant data lakes aggregate longitudinal glucose datasets for population health management. United States health systems drive institutional demand through hospital-at-home expansion programs.
- Data Analytics:Dashboards visualizing glycemic trends and generating clinician reports.
- Bluetooth Connectivity:Low-energy wireless protocols linking sensors to smartphones and insulin pumps.
Cloud Computing carries the steepest infrastructure burn rate; AI Algorithms commands the highest R&D talent premiums.
End User:
Patient-facing applications prioritize usability and direct-to-consumer marketing, while provider tools emphasize EHR integration and liability protection.
- Healthcare Providers:Clinical decision support tools integrate continuous glucose data into electronic health record workflows, requiring HL7 FHIR interoperability certification. United States hospital IT departments struggle with real-time ingestion implementation, creating vendor consolidation pressure.
- Patients:Direct-to-consumer continuous glucose monitor subscriptions bypass traditional durable medical equipment distributors. Self-funded employers in technology and financial services sectors contract directly with manufacturers for workforce diabetes management.
- Caregivers:Remote monitoring dashboards for family members of pediatric or elderly patients.
- Insurance Companies:Risk stratification tools leveraging aggregated glucose datasets for premium pricing.
Healthcare Providers absorb the bulk of enterprise software licensing; Patients is expanding most quickly through direct-to-consumer channels.
Delivery Mode:
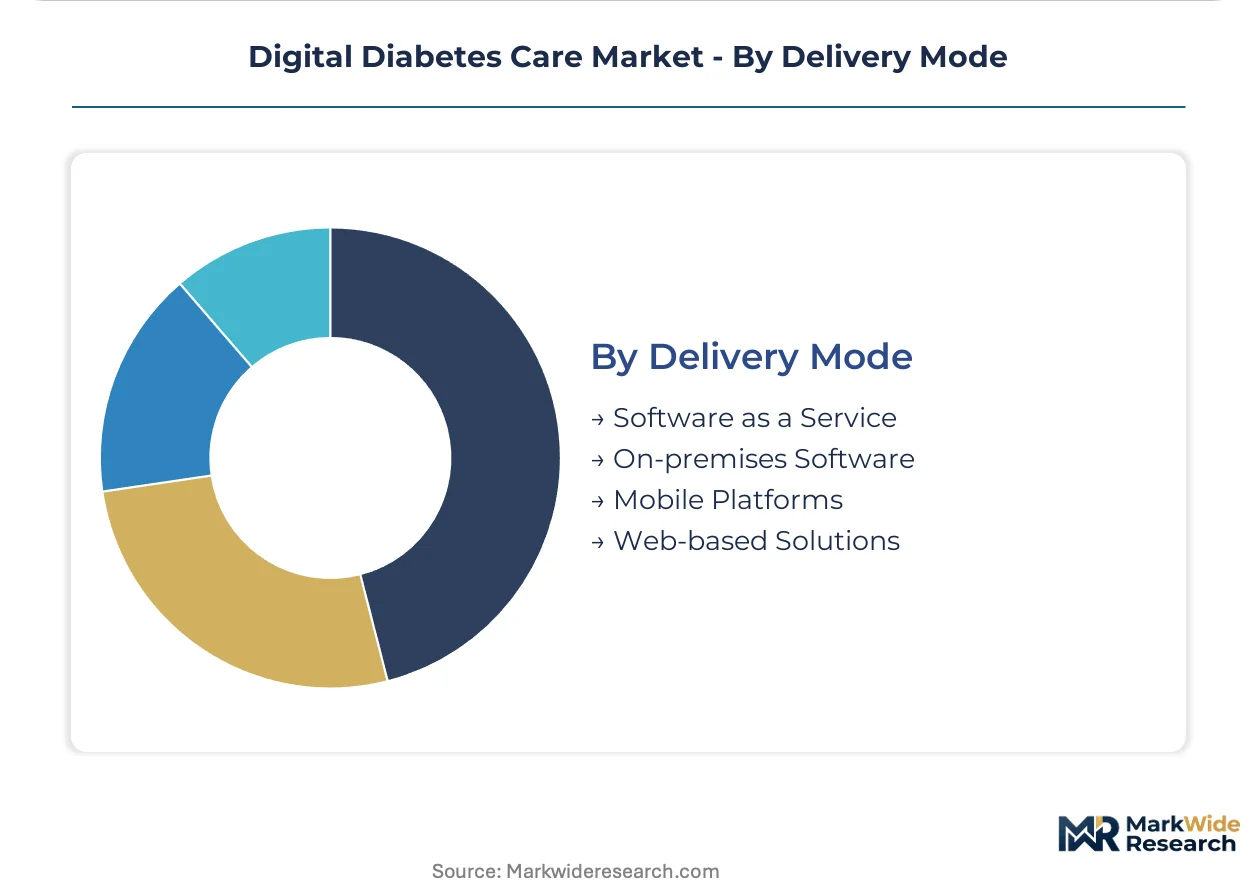
Subscription economics dominate SaaS and mobile platforms, while on-premises deployments persist in security-sensitive health system environments.
- Software as a Service:Cloud-hosted glucose monitoring platforms with recurring subscription revenue models. EU MDR Class IIa requirements and FDA 510(k) software-as-a-medical-device pathways accelerate clearance timelines for algorithm developers.
- Mobile Platforms:Native iOS and Android applications distributing continuous glucose data to patient smartphones. Retail pharmacy chains in the United States build specialty diabetes care clinics that bypass traditional durable medical equipment intermediaries.
- On-premises Software:Installed hospital systems for health systems with strict data residency requirements.
- Web-based Solutions:Browser-accessible clinician portals requiring minimal local installation.
Software as a Service captures the bulk of new vendor investment; Mobile Platforms is expanding most quickly through pharmacy channel direct distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme electrode manufacturing clusters in South Korea and Taiwan supply the electrochemical substrates powering continuous glucose monitor production worldwide. Hospital procurement networks in the United States, Germany, and Japan absorb the bulk of institutional demand, while retail pharmacy expansion reshapes patient-facing distribution channels.
United States
Integrated delivery networks in Texas and California anchor hospital formulary procurement for sensor-platform bundles. FDA software-as-a-medical-device pathways accelerate 510(k) clearances for glucose prediction algorithms. The Greater Boston corridor concentrates digital health venture funding and AI-enabled insulin dosing development.
Germany
Statutory health insurance funds drive predictable procurement volumes through the DiGA reimbursement pathway for digital therapeutics. EU MDR Class IIa requirements for glucose monitoring apps streamline software certification timelines. The Baden-Württemberg medical technology cluster around Stuttgart hosts sensor manufacturing and algorithm development operations.
Japan
Aging demographics and government-mandated diabetes screening expand the addressable patient population for remote monitoring solutions. PMDA regulatory harmonization with FDA standards reduces time-to-market for continuous glucose monitor submissions. The Kansai region around Osaka concentrates precision polymer substrate manufacturing for enzymatic sensors.
United Kingdom
NHS England's Diabetes Prevention Programme creates institutional demand for population-scale glucose monitoring platforms. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for software-as-a-medical-device products. The Cambridge-Oxford-London biotech corridor anchors machine learning development for predictive hypoglycemia alerts.
China
Domestic continuous glucose monitor manufacturers scale production for the world's largest Type 2 diabetes patient population. NMPA regulatory reforms align medical device software classifications with international standards. The Yangtze River Delta around Shanghai concentrates contract manufacturing for polymer substrate and enzyme electrode components.
Digital Diabetes Care Market Competitive Landscape
Platform ecosystem expansion dominates the current competitive landscape, with integrated sensor-software bundles displacing standalone hardware contracts. The vendor base concentrates around three strategic tiers: diversified medical technology conglomerates with hospital system relationships, specialized continuous glucose monitor developers with direct-to-consumer channels, and automated insulin delivery system manufacturers with pump-sensor convergence capabilities. M&A activity targets algorithm developers with FDA clearance momentum, while strategic partnerships between sensor manufacturers and pharmacy chains compress distribution margins.
Within the diversified conglomerate tier, Abbott Laboratories and Medtronic Plc exemplify platform bundling strategies that lock hospital formulary decisions through integrated delivery network contracts. Dexcom Inc. occupies a position in the specialized continuous glucose monitor segment, representing the direct-to-consumer subscription model that bypasses traditional durable medical equipment distributors. These three companies anchor the competitive structure, with their divergent channel strategies—institutional procurement versus consumer subscription—defining the primary competitive vectors in digital diabetes care.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic Plc |
| F. Hoffmann-La Roche Ltd |
| Dexcom Inc. |
| Insulet Corporation |
| Bayer AG |
| Ascensia Diabetes Care Holdings AG |
| Tandem Diabetes Care Inc. |
| LifeScan Inc. |
| Others |
Pricing and Supply Chain Analysis
Integrated delivery network procurement committees in the United States anchor pricing power through multi-year formulary contracts that bundle sensors with algorithmic platforms. This buyer concentration forces vendors toward subscription-based sensor replacement models rather than capital equipment sales, compressing upfront revenue recognition while extending lifetime value capture.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier continuous glucose monitor contracts from unbundled economy offerings where patients bear replacement risk. Three-tier pricing structure across premium, standard, and economy levels reflects FDA software-as-a-medical-device clearance tier and enzymatic accuracy specifications. Cost compression in the economy tier is intensifying because retail pharmacy chains negotiate direct distribution agreements that bypass durable medical equipment markups. Self-funded employers with actuarial teams demonstrate the lowest price sensitivity, while uninsured direct-to-consumer subscribers face the highest cost burden.
Supply Chain Analysis
EU MDR Class IIa and FDA 510(k) quality system certifications gate entry for polymer substrate and enzyme electrode suppliers, concentrating qualified vendors in South Korea, Taiwan, and Japan. Electrochemical sensor manufacturing draws from glucose oxidase biocatalysts, medical-grade platinum electrodes, and hydrophilic adhesive films. Single-source vulnerability persists in East Asian contract manufacturers where polymer substrate fabrication clusters. Distribution runs through integrated delivery network procurement offices for institutional volumes and retail pharmacy chains for direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
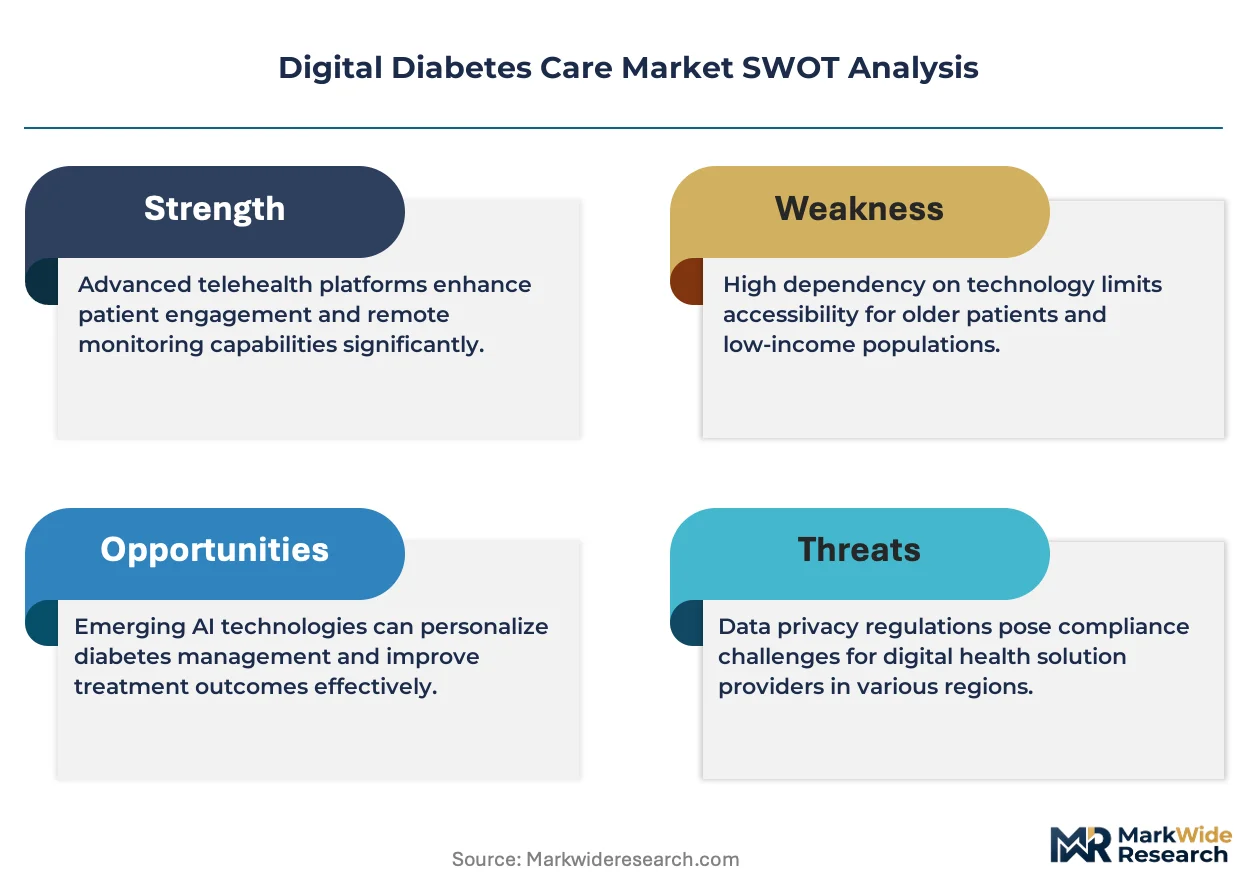
This market functions as a consolidation play where EU AI Act compliance costs and HIPAA security rule enforcement will force sub-scale algorithm developers toward acquisition or exit. Regulatory burden escalation advantages incumbents with established quality management systems.
For Market Incumbents: Anticipate non-invasive spectroscopic glucose measurement technologies threatening to compress demand for invasive sensors if clinical validation succeeds. Lock hospital formulary positions through backward integration into multi-day wear adhesive systems with extended enzymatic stability. Deepen platform ecosystem control by extending insulin pump data streams into third-party analytics dashboards to reduce patient switching. For New Entrants and Emerging Players: AI-integrated insulin dosing algorithms represent the most penetrable white-space segment, as machine learning modules predicting hypoglycemic events face less entrenched vendor relationships than hardware-sensor markets. Target Type 2 non-insulin populations where CMS national coverage determination expansion would unlock Medicare reimbursement. Pursue pharmacy channel direct distribution partnerships that bypass traditional durable medical equipment intermediaries. For Investors and Strategic Acquirers: The window for entry favors algorithm developers with FDA software-as-a-medical-device clearance momentum and established hospital system pilot contracts. Long-term viability hinges on convergence capabilities between continuous glucose monitors and automated insulin delivery systems. Watch CMS national coverage determinations for continuous glucose monitoring in non-insulin-using Type 2 populations as the primary inflection signal for addressable demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Accelerates 510(k) clearance timelines for glucose prediction algorithms under FDA digital health guidance. |
| Hospital System Partnership | Locks integrated delivery network formulary decisions through multi-year sensor-platform bundle contracts. |
| CE Marking Pathway | Streamlines EU MDR Class IIa certification for glucose monitoring apps in German statutory reimbursement markets. |
| Software Companion Development | Enables real-time HL7 FHIR interoperability with electronic health record workflows in United States hospitals. |
| Reimbursement Strategy | Secures DiGA pathway inclusion for digital therapeutics procurement in German statutory health insurance funds. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare coverage determinations, complemented by interviews with continuous glucose monitor product managers, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from SEC filings, DiGA registry data, and clinical validation studies in peer-reviewed endocrinology journals. Bottom-up sensor shipment estimates and top-down healthcare expenditure allocation were cross-referenced for triangulation.
Historical pricing trajectories for sensor replacement cycles were cross-referenced against panel input from procurement directors at integrated delivery networks to calibrate subscription revenue models. Segmentation dimensions modeled include product type, technology tier, end user archetype, and delivery mode across the analysis window. CAGRs were derived from slope analysis of installed base expansion and per-patient annual consumable spend. Forecast inputs incorporated regulatory clearance timelines, reimbursement pathway expansions, and enzymatic sensor wear period extensions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement intensity and non-invasive glucose measurement clinical validation success. Forecasts reflect documented assumptions regarding CMS coverage expansion timing and polymer substrate supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Implantable Insulin Pump Market
Diabetes Care
Gestational Diabetes Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
India Continuous Glucose Monitoring (CGM) Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
Middle-East and Africa Blood Glucose Monitoring Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Hyperinsulinemia Hypoglycaemia Treatment Market