
 Antidiabetics Market | 2026-2036
Antidiabetics Market Size, Share, and Industry Trends Forecast 2026-2036
Antidiabetics Market Analysis
Peptide-based active ingredients are decoupling antidiabetic formulations from traditional small-molecule economics, expanding manufacturing complexity and cost structures. Novo Nordisk A/S dominates the injectable GLP-1 segment through captive fermentation capacity and vertical control over peptide supply chains. Eli Lilly and Company differentiates via dual-hormone agonist pipelines that target both glycemic control and weight management. Sanofi anchors European manufacturing with established insulin biosimilar infrastructure and cold-chain distribution networks.
Antidiabetics comprise pharmacological agents that modulate glucose metabolism through insulin supplementation, pancreatic stimulation, or renal glucose excretion inhibition, with peptide therapeutics requiring recombinant DNA production in microbial or mammalian cell cultures followed by chromatographic purification. The primary commercial purpose centers on normalizing blood glucose levels to prevent microvascular and macrovascular complications in diabetic patients. SGLT2 Inhibitors represent the fastest-expanding product category as cardiorenal outcome data expands prescriber adoption beyond glycemic endpoints alone. Injectable delivery modes command premium positioning due to the biological instability of peptide drugs, while oral formulations in the DPP-4 Inhibitor class occupy mature, price-competitive segments with abbreviated regulatory pathways.
FDA review standards for diabetes therapies now incorporate cardiovascular outcome trial requirements that extend development timelines and raise capital barriers for new entrants. EMA's MDR framework and the EU's F-Gas Regulation constrain inhalation-based delivery device approvals and refrigerant choices in cold-chain logistics. India's CDSCO and PLI scheme are reshaping regional supply by incentivizing domestic insulin analog production. Stakeholders must monitor how evolving GLP-1 label expansions into obesity and cardiovascular prevention will fragment traditional diabetes-focused commercial models and reimbursement structures.
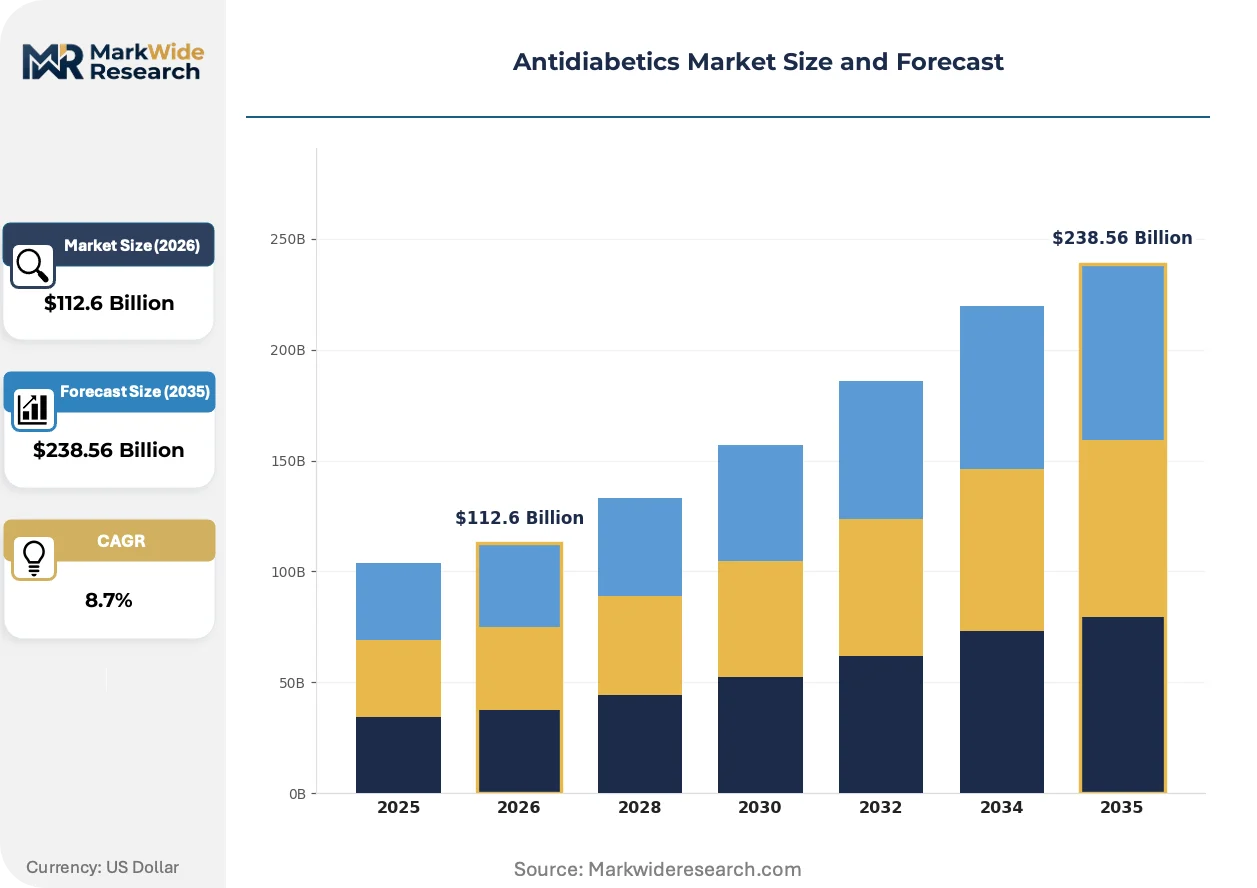
Market Dynamics
GLP-1 receptor agonists are fragmenting traditional antidiabetic commercial models as cardiorenal outcome data expands prescriber adoption beyond glycemic control into obesity and cardiovascular prevention, forcing reimbursement structures to adapt to multi-indication pricing.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed development timelines for novel peptide therapeutics reduce capital barriers and compress time-to-market for biologic diabetes treatments.
- Homecare Delivery Expansion:Patient migration from institutional settings to self-administration drives demand for patient-friendly injection devices and cold-chain direct-to-patient logistics.
- Peptide Manufacturing Scale-Up:Advances in recombinant DNA production and chromatographic purification enable cost-efficient expansion of biologic antidiabetic supply.
Market Restraints
- Cold-Chain Infrastructure Concentration:Biologic peptide instability requires refrigerated distribution networks concentrated in developed markets, limiting geographic reach.
- Cardiovascular Outcome Trial Mandates:FDA requirements for heart safety data extend development timelines and raise capital barriers for new therapeutic entrants.
- Fermentation Capacity Scarcity:Captive microbial and mammalian cell culture facilities concentrate among established manufacturers, constraining supply expansion.
Strategic Opportunities
- Oral GLP-1 Formulation Development:Non-injectable delivery technologies targeting patient adherence barriers in United States and European markets.
- India's PLI Scheme Incentives:Domestic production subsidies for insulin analog manufacturing reshape regional supply chains and export potential.
- Dual-Hormone Agonist Pipelines:Convergence of GLP-1 and GIP receptor targeting creates new therapeutic categories addressing glycemic control and weight management simultaneously.
Industry Challenges
- Peptide Synthesis Expertise Gap:Shortage of specialized biochemists and fermentation engineers constrains manufacturing workforce expansion.
- EMA MDR Compliance Complexity:Medical device regulation framework creates friction for delivery system approvals and post-market surveillance obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antidiabetics Market |
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $238.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors Delivery Mode: Injectable, Oral, Pen Devices, Infusion Pumps End User: Hospitals, Clinics, Homecare, Pharmaceutical Companies Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes |
| Companies Covered | Novo Nordisk A/S, Sanofi, Eli Lilly and Company, AstraZeneca, Merck & Co., Inc., Boehringer Ingelheim, Takeda Pharmaceutical Company, Novartis AG, Janssen Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antidiabetics Market Emerging Trajectories
Peptide therapeutics are decoupling antidiabetic economics from small-molecule commoditization, while regulatory frameworks increasingly weight cardiorenal outcomes and environmental compliance in approval and logistics decisions.
Continuous glucose monitoring integration with automated insulin delivery is modularizing diabetes management into closed-loop systems. Endocrinology practices and tech-enabled pharmacies in the United States are adopting these platforms fastest. The technology is modularizing patient data streams, device control, and therapeutic dosing into unified ecosystems that compress clinical decision cycles and reduce hypoglycemic events.
EMA's F-Gas Regulation constrains refrigerant choices in cold-chain logistics for temperature-sensitive biologics. Manufacturers must retrofit distribution networks with compliant cooling systems or absorb carbon credit costs. European insulin and GLP-1 supply chains are responding by consolidating warehousing in climate-controlled hubs and negotiating long-term refrigerant supply contracts.
Patients are demanding unbundled pharmacy services that separate drug dispensing from clinical counseling and device training. Retail pharmacy chains in the United States are displacing traditional bundled models with standalone injection training clinics and subscription-based device support. This shift is most visible in Medicare Advantage populations where supplemental benefits cover non-dispensing diabetes care services.
Antidiabetics Market Segmentation
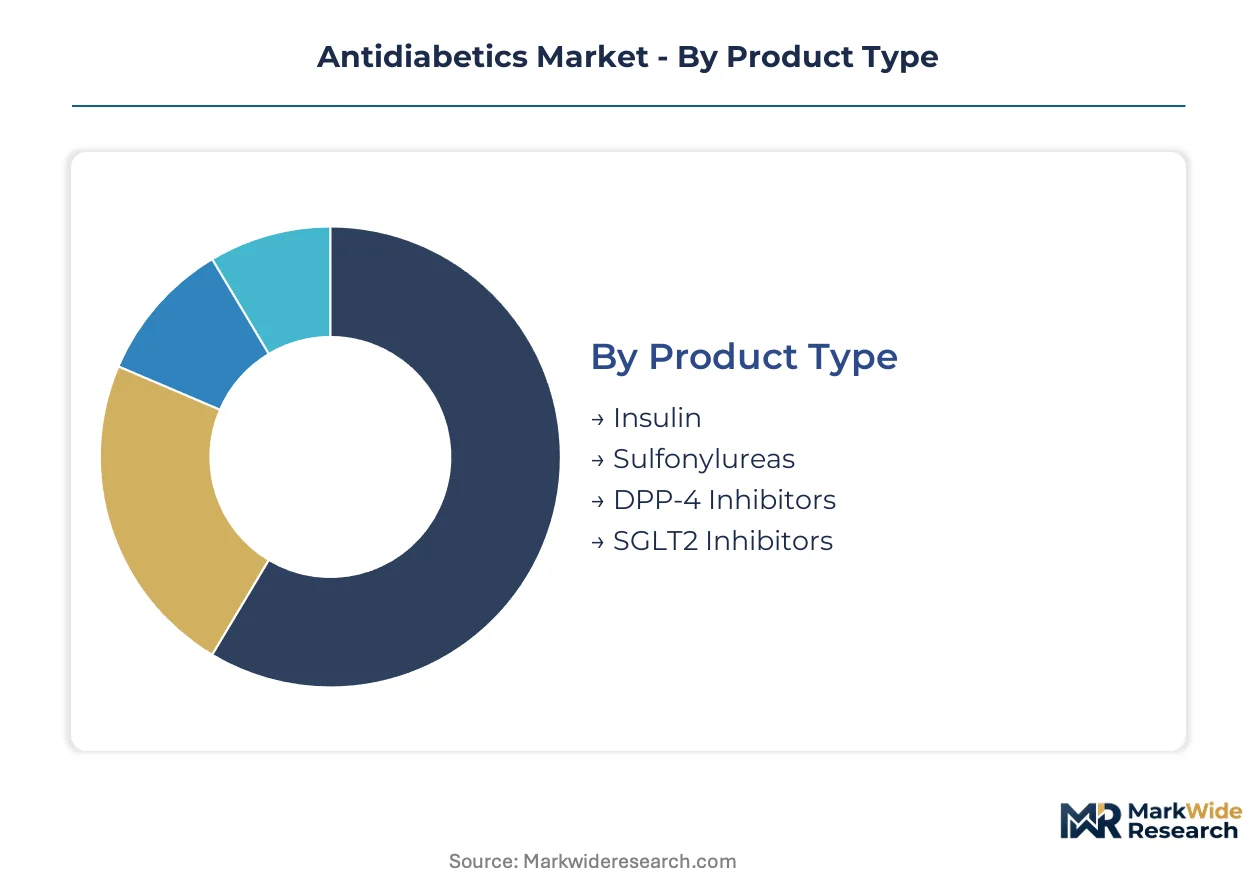
Antidiabetic market segmentation reflects divergent economics between mature small-molecule categories and rapidly expanding biologic peptide therapies. Understanding these segment boundaries clarifies where manufacturing complexity, reimbursement density, and prescriber behavior concentrate commercial value.
Product Type:
Volume concentration sits with established insulin analogs, while premium expansion is accelerating in outcome-driven SGLT2 and GLP-1 categories.
- Insulin:Recombinant human and analog formulations produced via microbial fermentation or mammalian cell culture. Demand concentrates in the United States and Europe where cold-chain infrastructure supports distribution, though manufacturing capacity scarcity constrains supply expansion among established producers.
- SGLT2 Inhibitors:Small-molecule agents that inhibit renal glucose reabsorption. Prescriber adoption is climbing fastest in the United States as cardiorenal outcome data expands reimbursement beyond glycemic endpoints into heart failure and chronic kidney disease prevention.
- DPP-4 Inhibitors:Oral incretin enhancers with mature, price-competitive positioning.
- Sulfonylureas:Pancreatic beta-cell stimulators occupying economy-tier pricing in emerging markets.
Mature deployment sits with Insulin. Newer deployment is concentrated in SGLT2 Inhibitors.
Delivery Mode:
Injectable systems command premium positioning due to biological instability of peptide drugs, while oral formulations serve adherence-sensitive patient populations.
- Injectable:Vial and syringe systems for insulin and GLP-1 receptor agonists. Homecare demand in the United States is displacing institutional administration as patients self-manage with disposable pen devices and automated injection training support.
- Pen Devices:Pre-filled, multi-dose delivery systems with dose-counting and needle-concealment features. European adoption is accelerating under EMA's MDR framework as manufacturers retrofit designs for enhanced post-market surveillance compliance.
- Oral:Tablet and capsule formulations for small-molecule antidiabetics.
- Infusion Pumps:Continuous subcutaneous insulin delivery systems with closed-loop glucose monitoring integration.
Cost-tier separation is sharpest between Injectable (premium biologics) and Oral (commoditized small-molecules).
End User:
Patient migration from facilities to home settings is fragmenting traditional channel structures and creating unbundled service opportunities.
- Homecare:Self-administered therapy with direct-to-patient logistics. United States Medicare Advantage populations are expanding supplemental benefits to cover device training and remote monitoring services separate from drug dispensing.
- Hospitals:Acute care settings managing diabetic ketoacidosis and perioperative glycemic control. India's CDSCO is tightening institutional procurement standards as domestic insulin analog production scales under PLI scheme incentives.
- Clinics:Outpatient endocrinology and primary care prescribing.
- Pharmaceutical Companies:Contract manufacturing and research outsourcing demand.
Volume concentration is shifting toward Homecare as reimbursement adapts to remote care models.
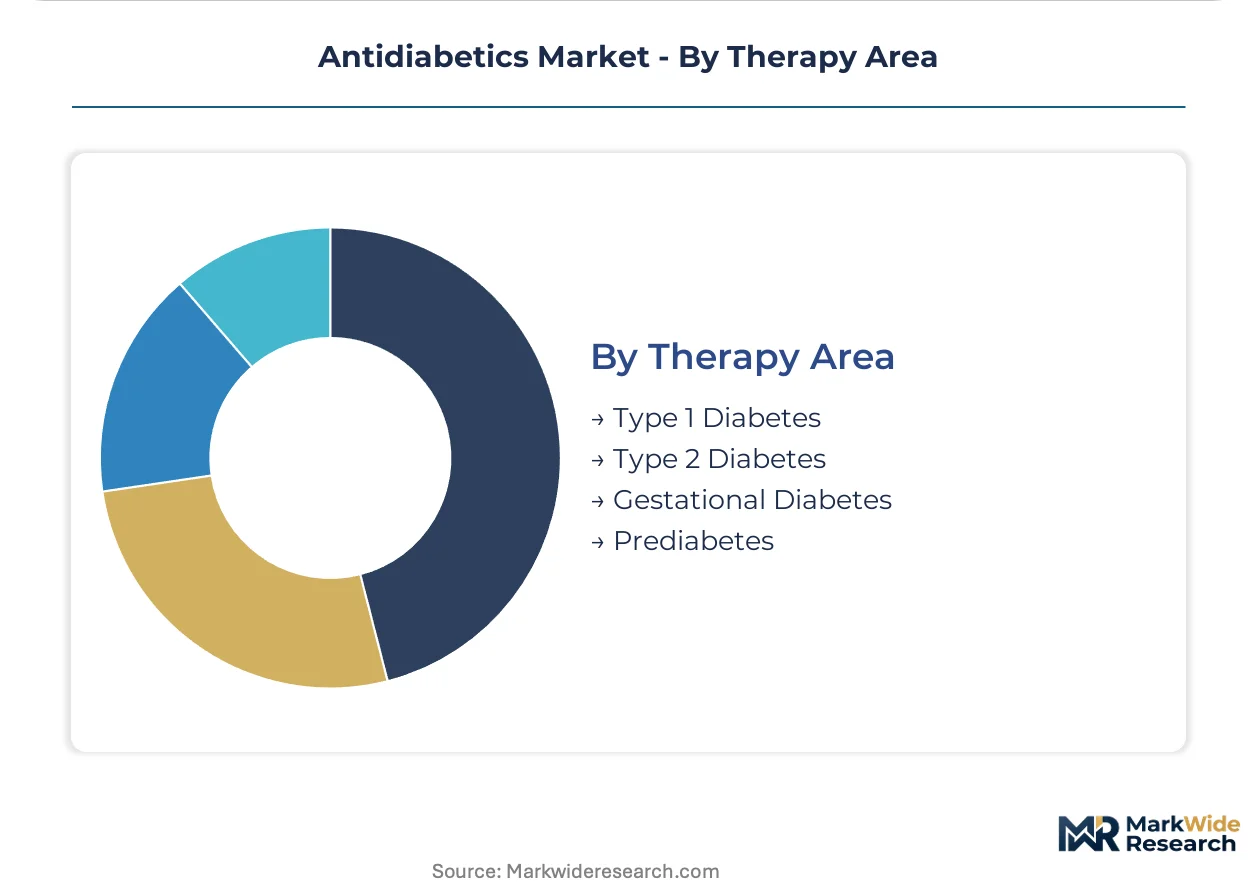
Therapy Area:
Type 2 diabetes dominates prescription volume, while Type 1 drives premium device and analog insulin demand.
- Type 2 Diabetes:Progressive insulin resistance and beta-cell dysfunction requiring escalating pharmacological intervention. United States prevalence linked to obesity is expanding prescriber adoption of dual-hormone agonist therapies that address glycemic control and weight management simultaneously.
- Type 1 Diabetes:Autoimmune beta-cell destruction requiring exogenous insulin replacement. Continuous glucose monitoring integration with automated insulin delivery is modularizing management into closed-loop systems fastest in United States endocrinology practices.
- Gestational Diabetes:Glucose intolerance during pregnancy with strict glycemic targets.
- Prediabetes:Impaired glucose tolerance with lifestyle and early pharmacological intervention.
Commercial investment concentrates in Type 2 Diabetes. Technology innovation is concentrated in Type 1 Diabetes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Ireland and Singapore concentrate bulk peptide fermentation for European and Asian supply chains. Tax incentives for biopharmaceutical manufacturing anchor capacity expansion decisions. FDA, EMA, and CDSCO regulations fragment approval pathways across major demand centers.
United States
Medicare Advantage supplemental benefits for device training and remote monitoring expand homecare delivery beyond traditional dispensing. FDA cardiovascular outcome trial mandates extend development timelines for novel therapies. The Greater Boston corridor anchors GLP-1 clinical trial infrastructure and specialized endocrinology practices adopting closed-loop systems.
Germany
EMA's MDR framework and F-Gas Regulation constrain delivery device approvals and cold-chain refrigerant choices. EMA post-market surveillance obligations require manufacturers to retrofit pen device designs for enhanced compliance. The Rhine-Ruhr region consolidates climate-controlled warehousing for insulin and GLP-1 distribution across continental Europe.
India
CDSCO institutional procurement standards tighten as domestic insulin analog production scales. The PLI scheme incentivizes manufacturing capacity for export markets. Gujarat's pharmaceutical special economic zones attract fermentation infrastructure investments targeting regional supply chain repositioning.
Japan
PMDA review standards incorporate long-term cardiovascular safety data requirements for diabetes therapy approvals. METI supports domestic manufacturing of continuous glucose monitoring components. The Kansai region around Osaka maintains specialized cold-chain logistics for temperature-sensitive biologic distribution.
Switzerland
Swissmedic maintains stringent stability testing requirements for peptide therapeutics that filter market entrants. The country's central European location supports multi-modal distribution into German, French, and Italian markets. Basel's pharmaceutical cluster concentrates formulation expertise and regulatory consulting for EMA centralized procedures.
Antidiabetics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive fermentation capacity concentrating among established peptide producers. The injectable GLP-1 segment shows tight supply-side consolidation around vertical control over microbial and mammalian cell culture facilities. Three archetypes dominate: fermentation-integrated incumbents, dual-hormone pipeline developers, and insulin biosimilar specialists. Capacity expansion and strategic partnerships represent the primary competitive moves as manufacturers secure peptide supply chains and expand cardiorenal outcome trial collaborations.
Among fermentation-integrated incumbents, Novo Nordisk A/S exemplifies vertical control over peptide supply chains through captive production infrastructure. Eli Lilly and Company occupies a position within the dual-hormone agonist development tier, targeting convergent therapeutic endpoints. Sanofi anchors the insulin biosimilar specialist archetype with established European manufacturing and distribution networks.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi |
| Eli Lilly and Company |
| AstraZeneca |
| Merck & Co., Inc. |
| Boehringer Ingelheim |
| Takeda Pharmaceutical Company |
| Novartis AG |
| Janssen Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Medicare Advantage plan concentration in the United States anchors value-based pricing for antidiabetic biologics, where reimbursement density and supplemental benefit coverage determine patient out-of-pocket exposure and manufacturer net realization. Peptide therapeutic complexity creates cost-tier separation between captive fermentation producers and contract-dependent competitors, with supply security translating directly into pricing power.
Pricing Analysis
Short lead-time premiums apply to GLP-1 receptor agonists and insulin analogs where fermentation capacity scarcity concentrates supply among established manufacturers. Three-tier pricing structure across premium biologics, standard biosimilars, and economy-tier small molecules reflects manufacturing complexity and cold-chain requirements. Cost compression in oral DPP-4 inhibitors intensifies due to abbreviated regulatory pathways and multi-source competition. Price sensitivity concentrates among uninsured and high-deductible plan populations in the United States, while least sensitivity sits with Medicare beneficiaries accessing supplemental benefits.
Supply Chain Analysis
Single-source vulnerability sits with microbial and mammalian cell culture capacity concentrated in Denmark, the United States, and France among vertically integrated incumbents. Peptide active pharmaceutical ingredients draw from recombinant DNA production, chromatographic purification resins, and specialized fermentation media. Tariff exposure runs through European cold-chain equipment imports subject to EMA's F-Gas Regulation compliance costs. Distribution runs through climate-controlled warehousing hubs in the Rhine-Ruhr region, Singapore's pharmaceutical special economic zones, and direct-to-patient logistics networks in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antidiabetics market functions as a vertical-integration race where control over microbial fermentation capacity and peptide purification infrastructure determines competitive sustainability. Manufacturers securing captive supply chains and cardiorenal outcome trial data capture disproportionate pricing power.
For Market Incumbents: Cement fermentation capacity advantages through facility expansion in Ireland and Singapore's tax-incentivized zones. Defend against oral GLP-1 formulation threats by accelerating dual-hormone agonist pipeline progression and locking in long-term pen device supply contracts under EMA MDR compliance frameworks. For New Entrants and Emerging Players: Capture India's PLI scheme subsidies for domestic insulin analog manufacturing targeting export markets in Southeast Asia and Africa. Penetrate the economy-tier sulfonylurea replacement segment with biosimilar positioning. Deploy hospital system partnerships in India's CDSCO-regulated institutional procurement channels as primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract peptide manufacturers with EMA MDR-compliant device capabilities in Eastern European geographies. Long-term viability hinges on fermentation expertise scarcity and cardiorenal outcome trial infrastructure ownership. Watch FDA label expansion decisions into obesity and cardiovascular prevention as inflection signals for revenue model fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive microbial cell culture facilities in Ireland and Singapore reduce single-source dependency for GLP-1 supply. |
| Cardiorenal Outcome Trial Collaboration | FDA-mandated heart safety data partnerships accelerate prescriber adoption beyond glycemic endpoints. |
| Oral GLP-1 Formulation Development | Non-injectable delivery technologies address patient adherence barriers in United States Medicare populations. |
| EMA MDR Device Compliance Retrofit | Pen device redesigns satisfy post-market surveillance obligations under European Medical Device Regulation. |
| India PLI Scheme Manufacturing Entry | Domestic insulin analog production under CDSCO incentives reshapes regional supply chains for export markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this antidiabetics market analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare data. Bottom-up prescription volume modeling and top-down revenue reconciliation triangulated market sizing across the analysis window.
Data-stream reconciliation integrated patient population epidemiology, treatment algorithm evolution, and reimbursement policy shifts across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, therapy area, end user, and regional regulatory cluster. CAGRs derived from historical volume trajectories and forward-looking patent expiry impacts, with specific inputs from continuous glucose monitoring adoption curves and GLP-1 label expansion probabilities.
The model holds under stable FDA and EMA regulatory frameworks; deviation in accelerated approval pathway modifications or F-Gas Regulation enforcement intensity would shift supply capacity and pricing trajectories. Forecasts reflect assumptions regarding cardiorenal outcome trial completion rates and India's PLI scheme disbursement continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
SGLT2 Inhibitors Treatment Market