
 Tenosynovial Giant Cell Tumor Treatment Market | 2026-2036
Tenosynovial Giant Cell Tumor Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Tenosynovial Giant Cell Tumor Treatment Market Intelligence
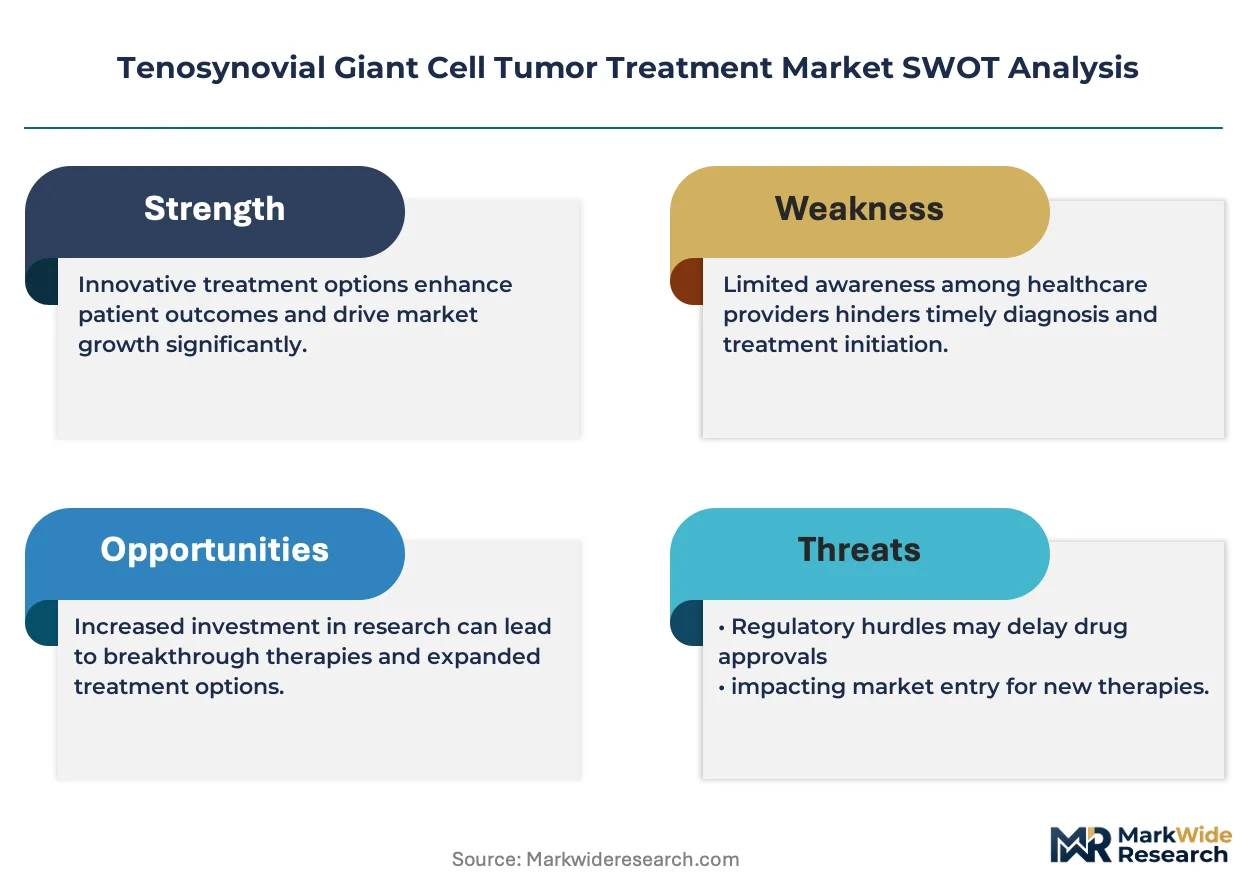
Project finance structures for late-stage clinical trials are reshaping competitive entry in tenosynovial giant cell tumor therapeutics. Novartis AG leverages its established oncology infrastructure to sustain investigator-initiated studies across multiple continents. Daiichi Sankyo Company Limited anchors its position through deep specialization in kinase inhibitor platforms. AmMax Bio, Inc. differentiates by concentrating resources on macrophage-targeting mechanisms for this CSF1R-driven indication.
Tenosynovial giant cell tumor treatment encompasses surgical, radiological, and pharmacological interventions directed at neoplastic proliferation of synovial-origin macrophages, with CSF1/CSF1R signaling pathway inhibition representing the dominant targeted mechanism. Local excision remains the foundational intervention for localized disease, while targeted therapy captures the fastest-expanding margin pool as systemic options displace repeat surgical morbidity. Among delivery modes, intralesional injection occupies a narrow but technically demanding niche for recurrent unresectable lesions, whereas oral administration extends addressable patient populations beyond major academic centers.
The FDA orphan drug program and EMA's parallel designation framework for rare neoplasms shape both development incentives and commercial exclusivity timelines for entrants in this space. Health technology assessment bodies in Germany and France impose distinct evidence thresholds for reimbursement of novel systemic therapies against surgical comparators. Stakeholders must monitor how real-world evidence requirements from these regulators evolve for drugs approved on accelerated pathways.
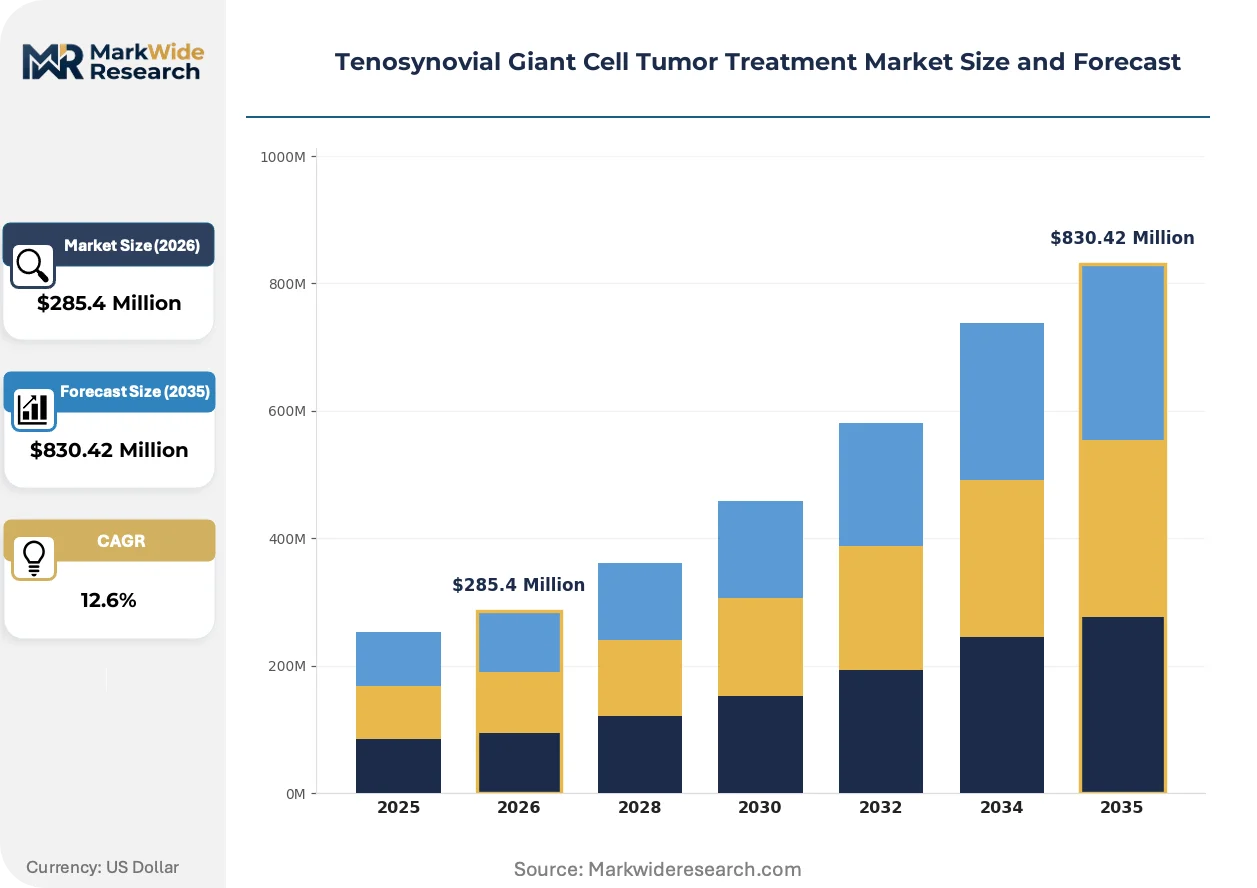
Market Dynamics
CSF1R inhibitor development pipelines are compressing surgical recurrence rates and redrawing reimbursement boundaries between pharmacological and interventional oncology in tenosynovial giant cell tumor management.
Growth Catalysts
- FDA Orphan Drug Designation:The pathway accelerates clinical trial protocols and extends market exclusivity for rare soft tissue neoplasm indications, incentivizing biopharma investment in this patient population.
- CSF1/CSF1R Signaling Inhibition:Targeted kinase platforms are displacing repeat surgical morbidity in diffuse-type disease, expanding addressable cases beyond localized resectable lesions.
- Specialty Center Concentration:Academic sarcoma programs in the United States are consolidating referral networks, creating concentrated prescriber bases for novel systemic therapies.
Market Restraints
- Biologic Manufacturing Complexity:Monoclonal antibody production requires single-use bioreactor capacity that concentrates among contract manufacturers in Switzerland and Singapore.
- Health Technology Assessment Friction:Germany's IQWiG and France's HAS impose distinct cost-effectiveness thresholds against surgical comparators, delaying reimbursement for accelerated-approval therapies.
- Pathology Diagnostic Variability:Inter-observer disagreement between pigmented villonodular synovitis and giant cell tumor of tendon sheath classifications complicates clinical trial enrollment.
Strategic Opportunities
- Intralesional Delivery Innovation:Depot formulations for recurrent unresectable lesions in the hand and foot could capture technically demanding cases currently managed with repeated debulking.
- Real-World Evidence Pathways:EMA's adaptive licensing framework and FDA's Project Orbis create parallel submission opportunities for post-marketing confirmatory data collection.
- Japan's Sakigake Designation:PMDA's priority review system for innovative pharmaceuticals offers accelerated access for CSF1R inhibitors in this rare indication.
Industry Challenges
- Sarcoma Pathology Fellowship Scarcity:The limited pipeline of specialized soft tissue pathologists constrains diagnostic throughput at community hospitals, delaying appropriate referral.
- Cross-Border Trial Coordination:Divergent informed consent requirements between the United States and European Union sites prolongs site activation timelines for multinational studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tenosynovial Giant Cell Tumor Treatment Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $830.42 Million |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Local Excision, Radiation Therapy, Targeted Therapy, Chemotherapy Delivery Mode: Intralesional Injection, Oral Administration, Systemic Treatment, Injectable Solution End User: Hospitals, Outpatient Clinics, Specialty Treatment Centers, Research Laboratories Product Type: Biologics, Small Molecules, Surgical Instruments, Diagnostic Tools |
| Companies Covered | Merck, AmMax Bio, Inc., Daiichi Sankyo Company Limited, Novartis AG, SynOx Therapeutics, Deciphera Pharmaceuticals Inc., Abbisko Therapeutics Co., Ltd., HUTCHMED, Ono Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tenosynovial Giant Cell Tumor Treatment Market Strategic Shifts & Innovations
Oral small-molecule CSF1R inhibitors are collapsing the historical boundary between surgical and medical oncology in tenosynovial giant cell tumor care, while regulatory frameworks adapt to accelerated evidence generation for rare neoplasms.
Peptide-drug conjugates targeting the CSF1 receptor are collapsing the therapeutic index limitations of first-generation kinase inhibitors. Sarcoma centers at Memorial Sloan Kettering and MD Anderson are integrating these agents into neoadjuvant protocols for diffuse-type disease. The compression of repeat surgical episodes is reshaping value-based care metrics in orthopedic oncology.
EMA's parallel scientific advice procedure with FDA is harmonizing oncology development programs across the Atlantic. The framework reduces regulatory duplication for orphan indications with limited patient pools. European reference pricing systems are responding with indication-specific value assessments rather than cross-therapeutic class benchmarking.
Patient advocacy networks are consolidating procurement influence in rare disease therapeutics. The TGCT Community Alliance and similar organizations in Germany and France are negotiating early access protocols directly with manufacturers. This channel disintermediation is most visible in the United States, where specialty pharmacy distribution is yielding to hospital-outpatient buy-and-bill arrangements for infused therapies.
Tenosynovial Giant Cell Tumor Treatment Market Segmentation
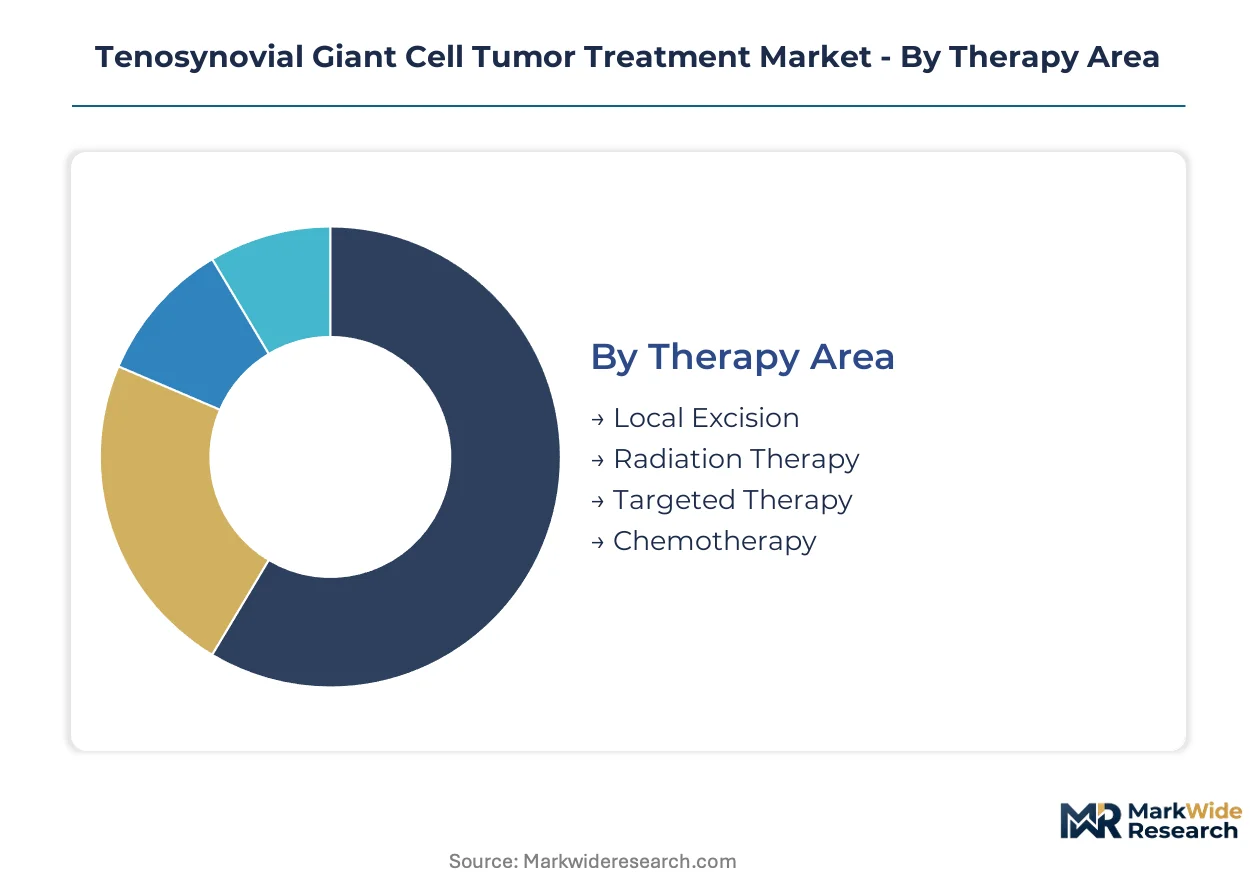
Tenosynovial giant cell tumor treatment modalities fragment across intervention intensity, delivery complexity, and care setting economics. Understanding these segment boundaries clarifies where CSF1R inhibitor revenues concentrate versus where surgical and radiological services retain margin.
Therapy Area:
Cost tier separates definitive surgical management from chronic pharmacological suppression in this indication.
- Targeted Therapy:CSF1R kinase inhibitors and monoclonal antibodies interrupt macrophage proliferation signaling. Academic sarcoma centers in the United States absorb the majority of prescriber volume as diffuse-type disease drives systemic treatment candidacy.
- Local Excision:Marginal or wide resection of localized tendon sheath lesions remains the foundational intervention. Community orthopedic practices in Germany and France handle high case volumes where joint preservation is technically achievable.
- Radiation Therapy:Adjuvant external beam or intraoperative delivery addresses microscopic residual disease. Post-operative protocols concentrate at radiation oncology departments within tertiary hospital networks.
- Chemotherapy:Cytotoxic regimens occupy a narrow role for rare malignant transformation or refractory diffuse-type presentations. Enrollment into sarcoma chemotherapy trials occurs predominantly at MD Anderson and Memorial Sloan Kettering.
Targeted therapy holds installed capacity. Local excision is rotating up the share rankings as diagnostic referral pathways mature.
Delivery Mode:
Application context determines whether administration requires interventional radiology expertise or extends to community prescribers.
- Oral Administration:Small-molecule CSF1R inhibitors enable outpatient management without infusion infrastructure. Patient access expands beyond major academic centers into community oncology practices across the United States and Western Europe.
- Intralesional Injection:Depot formulations or direct agent instillation into recurrent unresectable hand and foot lesions demands specialized interventional technique. Sarcoma centers at specialized hand surgery units in Switzerland and the Netherlands pioneered these protocols.
- Systemic Treatment:Intravenous monoclonal antibody delivery requires infusion center capacity and nursing support. Hospital outpatient departments capture this volume through buy-and-bill reimbursement arrangements.
- Injectable Solution:Parenteral formulations for perioperative or neoadjuvant protocols bridge surgical and medical oncology. Pre-operative shrinking of diffuse-type masses is gaining adoption at orthopedic oncology services in Japan under PMDA guidance.
Oral administration holds installed capacity. Intralesional injection is climbing the fastest as depot technologies mature.
End User:
Customer type maps directly to case complexity and reimbursement intensity for this rare neoplasm.
- Specialty Treatment Centers:Dedicated sarcoma and orthopedic oncology programs consolidate multidisciplinary care for diffuse-type and recurrent disease. The United States maintains the densest network, with centers at Duke, Mayo Clinic, and UCSF commanding regional referral basins.
- Hospitals:General acute care facilities handle localized resectable lesions through orthopedic surgery departments. German hospital networks integrate pathology and radiology for intraoperative margin assessment.
- Outpatient Clinics:Ambulatory surgery centers perform limited local excisions for small tendon sheath presentations. French clinique arrangements optimize same-day discharge for eligible cases.
- Research Laboratories:Companion diagnostic development and CSF1R expression profiling occur at contract research organizations and academic pathology cores. Biomarker validation partnerships link these sites to pharmaceutical sponsors.
Specialty treatment centers hold installed capacity. Hospitals are gaining share fastest as diagnostic referral protocols standardize.
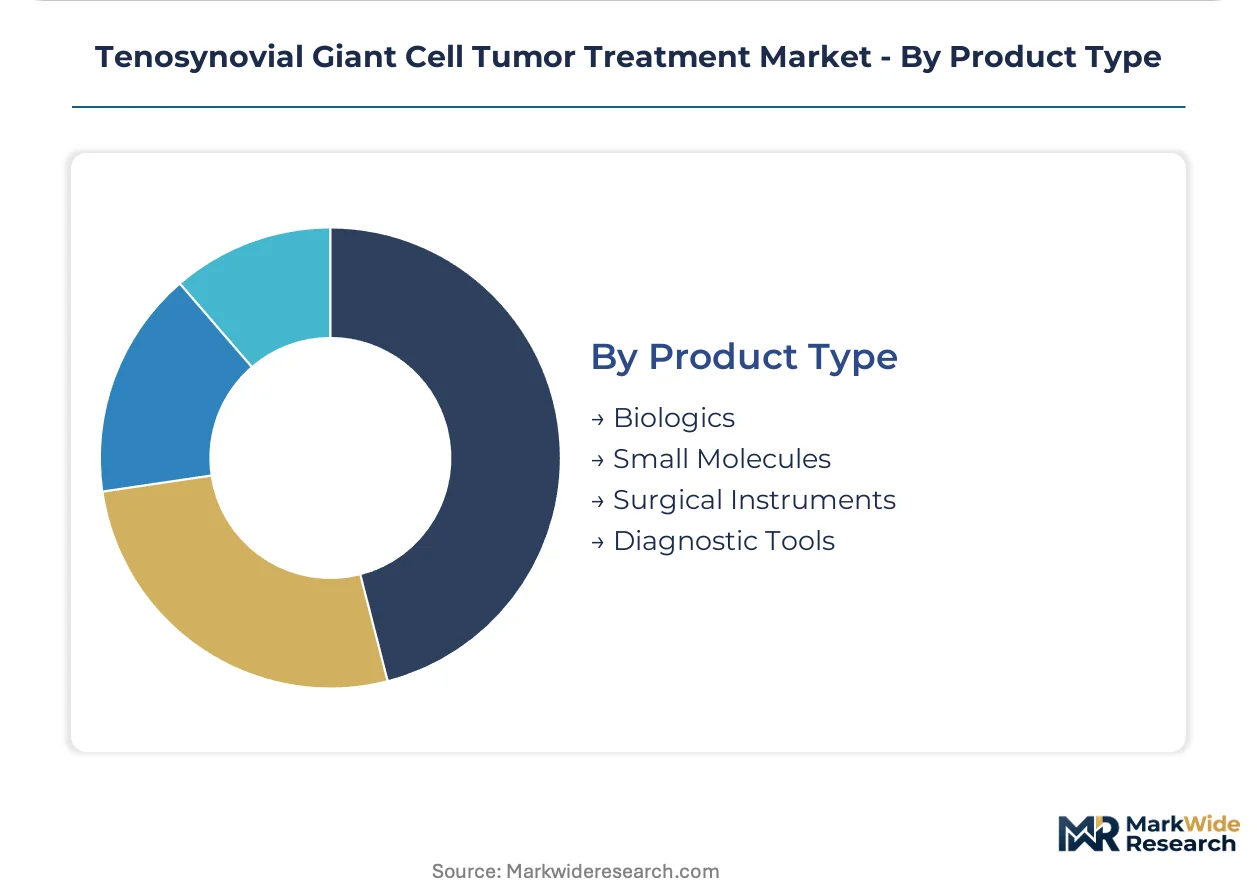
Product Type:
Supply concentration varies sharply between biologic manufacturing scale and surgical instrument commoditization.
- Biologics:CSF1R-targeting monoclonal antibodies require mammalian cell culture production in single-use bioreactor facilities. Contract manufacturers in Switzerland and Singapore hold captive capacity for clinical and commercial supply.
- Small Molecules:Kinase inhibitor active pharmaceutical ingredients are synthesized through multi-step chemical routes. Indian and Chinese API suppliers compete on cost for generic pexidartinib following patent expiry.
- Surgical Instruments:Arthroscopic shavers, curettes, and margin assessment tools for tenosynovectomy are sourced through orthopedic device distributors. German and Japanese precision instrument manufacturers dominate premium segments.
- Diagnostic Tools:CSF1R immunohistochemistry assays and fluorescence in situ hybridization kits enable molecular confirmation. Reference laboratories in the United States and United Kingdom validate these for clinical trial enrollment.
Biologics hold installed capacity. Small molecules are rotating up the share rankings as oral formulations displace infusion dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net therapeutic imports concentrate in Western Europe and Japan, where domestic biomanufacturing capacity lags behind CSF1R inhibitor demand from diffuse-type patient populations. The United States runs a substantial surplus in clinical trial services and specialty oncology care, exporting protocol expertise to Asia-Pacific sites.
United States
Memorial Sloan Kettering and MD Anderson anchor the densest network of sarcoma referral pathways globally, capturing complex diffuse-type cases from community hospitals. FDA orphan drug designation accelerates development timelines for CSF1R-targeting candidates. Boston's biotech corridor houses contract research organizations validating companion diagnostics for clinical trial enrollment.
Germany
IQWiG cost-effectiveness assessments create reimbursement friction for accelerated-approval systemic therapies against surgical comparators. University hospital networks in Heidelberg and Essen integrate orthopedic oncology with specialized soft tissue pathology services. Bavarian precision instrument manufacturers supply arthroscopic shavers for tenosynovectomy procedures across Central Europe.
Japan
PMDA's Sakigake priority review system compresses approval timelines for innovative CSF1R inhibitors in this rare indication. Osaka-based orthopedic oncology units pioneered neoadjuvant systemic protocols for diffuse-type disease. The Kanto region's clinical trial infrastructure absorbs substantial protocol volume from US sponsors seeking Asian patient diversity.
Switzerland
Contract manufacturers in Basel and Zurich hold captive single-use bioreactor capacity for monoclonal antibody production serving European demand. Swissmedic's streamlined orphan drug pathway attracts sponsor companies seeking parallel EMA submissions. The country's reference pricing negotiations influence reimbursement across German-speaking markets.
United Kingdom
NICE technology appraisals impose distinct evidence thresholds for novel systemic therapies against established surgical management. London's sarcoma centers at the Royal National Orthopaedic Hospital consolidate multidisciplinary care for recurrent unresectable lesions. The MHRA's post-Brexit recognition framework maintains access to EMA-approved CSF1R inhibitors.
Tenosynovial Giant Cell Tumor Treatment Market Key Industry Players
On the supply side, the industry is consolidating around three strategic archetypes: diversified oncology majors with established kinase inhibitor infrastructure, macrophage-targeting biotech specialists, and contract manufacturing organizations with captive bioreactor capacity. Large-cap pharmaceutical companies leverage existing regulatory relationships to compress development timelines, while mid-cap specialists concentrate resources on CSF1R mechanism validation. Competitive moves center on investigator-initiated study sponsorship and companion diagnostic partnerships.
Within the diversified oncology tier, Novartis AG and Daiichi Sankyo Company Limited exemplify platform leverage strategies, applying established kinase inhibitor expertise to this rare indication. AmMax Bio, Inc. occupies a distinct position among macrophage-targeting specialists, concentrating development resources on CSF1R-driven mechanisms. These three companies represent contrasting archetypes for competitive entry: scale-driven portfolio extension versus focused mechanism validation.
| Leading Market Players |
|---|
| Merck |
| AmMax Bio, Inc. |
| Daiichi Sankyo Company Limited |
| Novartis AG |
| SynOx Therapeutics |
| Deciphera Pharmaceuticals Inc. |
| Abbisko Therapeutics Co., Ltd. |
| HUTCHMED |
| Ono Pharmaceutical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Trans-Atlantic air freight corridors connecting Basel and Boston absorb premium surcharges for temperature-controlled biologics, concentrating supply chain costs among Swiss contract manufacturers and forcing three-tier pricing stratification across academic medical centers, hospital outpatient departments, and specialty infusion clinics.
Pricing Analysis
Industrial OEM buyers anchor value-based contracting for CSF1R inhibitor procurement, with pricing stratifying across premium branded biologics, standard small-molecule formulations, and economy-tier post-patent generics. Quality grade and FDA orphan drug certification tier create primary differentiation. Cost compression in the economy tier is intensifying because Indian API suppliers are scaling kinase inhibitor production. Community oncology practices exhibit highest price sensitivity; academic sarcoma centers demonstrate lowest.
Supply Chain Analysis
Lonza and Boehringer Ingelheim hold captive single-use bioreactor capacity for monoclonal antibody production serving European and North American demand. Manufacturing concentrates in Switzerland, Singapore, and the United States. Active pharmaceutical ingredients for small-molecule CSF1R inhibitors draw from Indian and Chinese chemical synthesis facilities. Single-source vulnerability persists for mammalian cell culture media. Distribution runs through hospital-outpatient buy-and-bill arrangements for infused therapies and specialty pharmacy channels for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic and patient support services attach to pharmaceutical offerings at margins exceeding hardware-equivalent returns, with adherence monitoring and biomarker testing subscription layers expanding faster than drug product sales alone.
For Market Incumbents: Insulate market position through backward integration into diagnostic assay development and captive bioreactor capacity expansion in Singapore. Generic pexidartinib entry from Indian manufacturers threatens small-molecule pricing. FDA orphan drug exclusivity extension and EMA parallel scientific advice investment defend regulatory moats. For New Entrants and Emerging Players: Establish a beachhead in intralesional depot formulations for recurrent unresectable hand and foot lesions, the most technically underserved segment. Japan's PMDA Sakigake priority review offers fastest regulatory pathway. Go-to-market through orthopedic hand surgery units at Swiss and Dutch academic centers bypasses entrenched oncology prescriber relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical divestiture of rare disease assets lacking portfolio fit. Long-term viability centers on CSF1R mechanism validation breadth across macrophage-driven indications. Watch FDA breakthrough therapy designation velocity as inflection signal for platform value re-rating.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA orphan drug designation compresses clinical trial timelines for rare soft tissue neoplasms. |
| Companion Diagnostic Partnership | CSF1R immunohistochemistry assay validation locks in clinical trial enrollment control. |
| Manufacturing Scale-Up | Single-use bioreactor capacity expansion in Singapore secures monoclonal antibody supply. |
| Real-World Evidence Collection | EMA adaptive licensing framework enables post-approval confirmatory data generation. |
| Geographic Expansion | PMDA Sakigake designation accelerates Japanese market access for innovative CSF1R inhibitors. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation cross-checked segmentation outputs.
Forecast inputs span treatment line, dosage form, administration route, and regional regulatory cluster across the projection horizon. CAGRs derive from patient incidence extrapolation, therapy penetration curves, and pricing trajectory assumptions. Modeled variables include diffuse-type disease prevalence, CSF1R inhibitor adoption rates, and surgical recurrence rate compression.
Macroeconomic conditions sit as an overlay; deviation in biopharma R&D tax credit policy or reference pricing stringency would shift the trajectory. Forecasts reflect documented assumptions on regulatory pathway success rates and reimbursement negotiation outcomes. Quarterly review of FDA approval velocity and IQWiG assessment timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Autologous Matrix Induced Chondrogenesis Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market
Regenerative Medicine
Global Cartilage Repair-Cartilage Regeneration Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
Atrophic Scar Treatment Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
Europe Regenerative Medicines Market