
 US Healthcare IT Market | 2026-2036
US Healthcare IT Market Size, Share, and Industry Trends Forecast 2026-2036
US Healthcare IT Market Insights
Multi-source procurement of clinical software is consolidating around fewer enterprise-grade vendors capable of end-to-end integration. Epic Systems Corporation anchors inpatient EHR dominance through deep specialty module development. Cerner Corporation competes aggressively in revenue cycle and population health extensions. Oracle leverages cloud infrastructure investments to reposition acquired assets across ambulatory and payer segments.
Healthcare IT encompasses the hardware, software, and networking infrastructure used to acquire, store, retrieve, and share healthcare data, with systems typically requiring HL7 FHIR compliance for data exchange and uptime thresholds exceeding 99.9% for critical care applications. Electronic Health Records occupy the largest installed base but generate thinner margins as replacement cycles lengthen. Cloud-based deployment represents the fastest-expanding architecture as hospital CIOs prioritize scalable infrastructure over capital-intensive on-premises data centers. AI-driven Analytics commands premium pricing where predictive models demonstrably reduce readmission penalties.
FDA oversight of clinical decision support software, HIPAA security rule enforcement by HHS Office for Civil Rights, and ONC certification requirements under the 21st Century Cures Act collectively elevate compliance costs for new market entrants. CMS quality reporting programs tie reimbursement to validated health IT functionality, creating structural demand for certified platforms. Stakeholders must weigh interoperability mandates against the switching costs of legacy system migration when evaluating platform commitments.
Market Dynamics
The 21st Century Cures Act mandates interoperability standards that force hospital systems to replace fragmented point solutions with integrated platforms, compressing vendor margins while elevating compliance costs for new entrants.
Growth Catalysts
- CMS Quality Reporting Programs:Reimbursement ties to validated health IT functionality create structural demand for certified EHR platforms across Medicare-participating hospitals.
- Texas Health System Consolidation:Large integrated delivery networks in Dallas and Houston drive enterprise-scale implementations that favor vendors with deep specialty modules.
- Cloud Infrastructure Migration:Hospital CIOs prioritize scalable architecture over capital-intensive on-premises data centers, accelerating SaaS procurement cycles.
Market Restraints
- Legacy System Switching Costs:Data migration complexity and workflow retraining create vendor lock-in that slows replacement cycles in mid-tier hospital systems.
- ONC Certification Burden:New market entrants face elevated compliance costs from 21st Century Cures Act requirements that favor established platform vendors.
- Cybersecurity Insurance Escalation:HIPAA security rule enforcement by HHS Office for Civil Rights drives premium increases that strain rural hospital operating budgets.
Strategic Opportunities
- Rural Health Network Gaps:Critical access hospitals in Mississippi and Alabama remain underpenetrated by enterprise EHR vendors due to implementation cost barriers.
- AI-Driven Readmission Prediction:Predictive analytics that demonstrably reduce CMS penalty exposure command premium pricing in value-based care arrangements.
- FHIR-Enabled Data Monetization:Standardized APIs create new revenue streams for health systems selling de-identified clinical data to life sciences researchers.
Industry Challenges
- Interoperability Talent Scarcity:Health systems compete for HL7 FHIR engineers and integration architects who can bridge legacy HL7 v2 interfaces with modern APIs.
- Multi-Vendor Integration Complexity:Best-of-breed strategies require expensive middleware layers that fragment clinical workflows and elevate total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Healthcare IT Market |
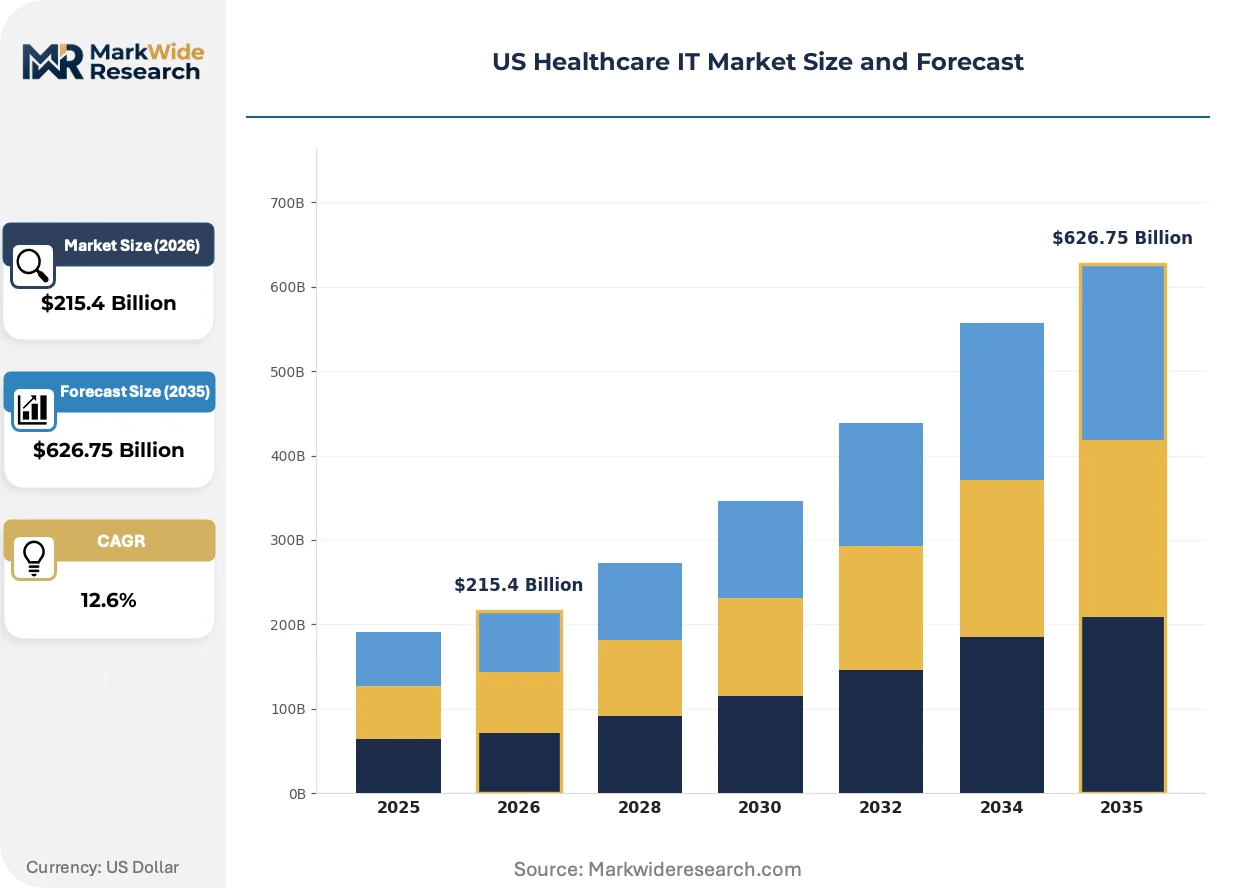
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $626.75 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Health Records, Practice Management Software, Telemedicine Solutions, Health Information Exchange End User: Hospitals, Ambulatory Care Centers, Physician Practices, Diagnostic Labs Deployment: Cloud-based, On-premises, Hybrid, Managed Services Technology: AI-driven Analytics, Interoperability Solutions, Cybersecurity Tools, Mobile Health Applications |
| Companies Covered | Epic Systems Corporation, Cerner Corporation, McKesson Corporation, GE Healthcare, Oracle, Optum, Inc., Philips Healthcare, Athenahealth, Inc., Veradigm Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Healthcare IT Market Trends and Innovations
Healthcare IT architecture is pivoting from monolithic enterprise systems toward modular, API-first platforms that enable selective component replacement without full-stack migration.
Cloud-native EHR deployment is decentralizing infrastructure ownership across hospital systems. Regional health networks in Florida and Arizona are adopting multi-tenant SaaS configurations that eliminate data center capital expenditures. This shift compresses implementation timelines from 18 months to 6 months while forcing on-premises vendors to reposition around hybrid connectivity services.
FDA oversight of clinical decision support software is expanding beyond traditional device pathways. Algorithm-based diagnostic aids now face premarket review requirements that extend development cycles by 12-18 months. Software vendors are responding by segregating CDS modules into distinct legal entities to isolate regulatory liability from core platform operations.
Hospital procurement committees are unbundling EHR contracts from long-term professional services agreements. Texas Medical Center affiliates now negotiate separate statements of work for implementation, optimization, and ongoing support. This disaggregation exposes vendor margin structures to competitive pressure while creating openings for specialized health IT consultancies in Houston and Dallas markets.
US Healthcare IT Market Segmentation
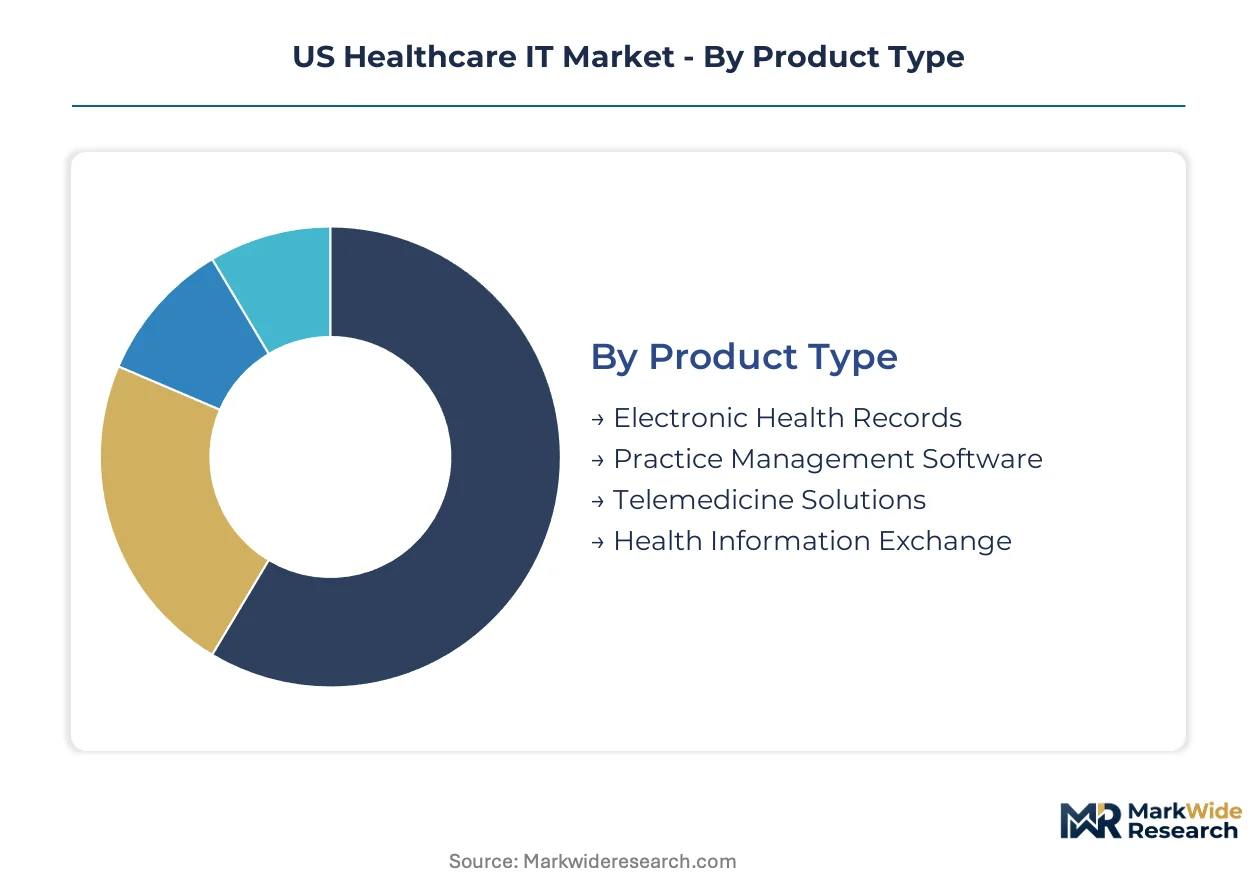
Segmentation reveals how procurement patterns concentrate around specific architectural choices and compliance requirements. Hospital systems in Texas and Florida drive divergent demand profiles that reshape vendor product roadmaps.
Product Type:
Supply concentrates among vendors capable of modular integration with legacy infrastructure.
- Electronic Health Records:Core clinical data repositories requiring HL7 FHIR compliance and 99.9% uptime thresholds. Demand clusters in Dallas and Houston health systems replacing fragmented point solutions with enterprise platforms under 21st Century Cures Act pressure.
- Practice Management Software:Administrative workflow engines handling scheduling, billing, and revenue cycle operations. Physician practices in Florida prioritize cloud-native deployments that compress implementation timelines from 18 months to 6 months.
- Telemedicine Solutions:Remote care delivery platforms with integrated video, scheduling, and documentation modules.
- Health Information Exchange:Networked data sharing infrastructure enabling cross-organizational care coordination.
Today's leader: Electronic Health Records. Tomorrow's challenger: Telemedicine Solutions.
End User:
Cost tier differentiation separates enterprise implementations from constrained rural deployments.
- Hospitals:Acute care facilities requiring comprehensive inpatient, outpatient, and emergency department modules. Texas Medical Center affiliates drive unbundled procurement separating software licenses from professional services agreements.
- Ambulatory Care Centers:Outpatient surgical and specialty clinics needing streamlined documentation and referral management. Mississippi and Alabama critical access facilities face implementation cost barriers that favor SaaS configurations.
- Physician Practices:Small to mid-size primary and specialty care operations.
- Diagnostic Labs:Clinical and anatomic pathology operations with instrument integration requirements.
Hospital systems command vendor attention. Physician practices represent the steepest expansion trajectory.
Deployment:
Volume concentration is accelerating toward architectures that eliminate capital expenditure burdens.
- Cloud-based:Multi-tenant SaaS configurations with vendor-managed infrastructure and automatic updates. Regional health networks in Florida and Arizona adopt these to eliminate data center ownership costs entirely.
- On-premises:Client-owned server infrastructure with direct hardware control. Mid-tier hospital systems in Texas retain these for legacy HL7 v2 interface stability despite higher total cost of ownership.
- Hybrid:Split architectures with sensitive data on-premises and analytics workloads in cloud environments.
- Managed Services:Outsourced infrastructure operations with vendor-staffed technical support.
Cloud-based deployment dominates new procurement. Hybrid architectures serve transition-bound incumbents.
Technology:
Application focus determines where AI and security investments concentrate development resources.
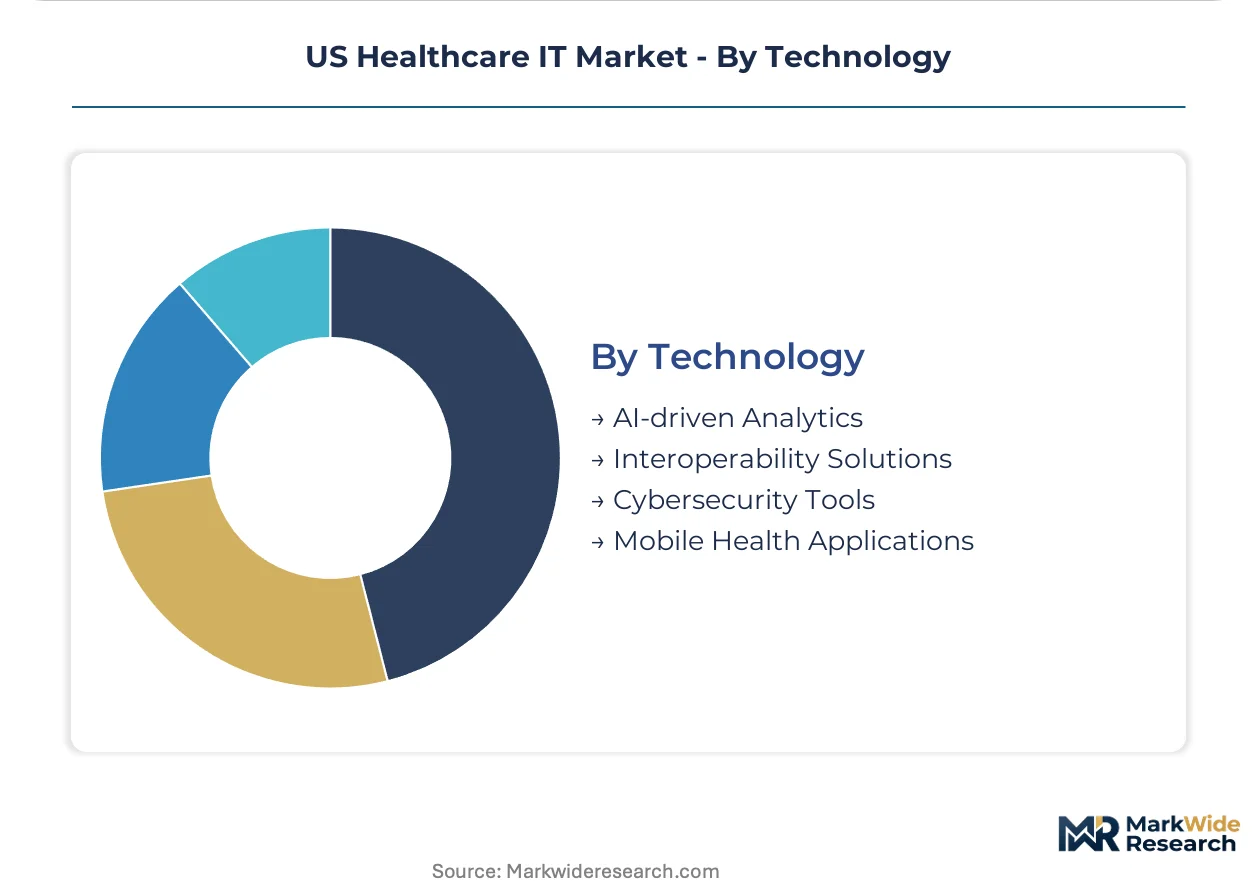
- AI-driven Analytics:Predictive models for readmission risk, sepsis detection, and length-of-stay optimization. These command premium pricing where demonstrable CMS penalty reduction justifies implementation costs.
- Interoperability Solutions:FHIR-enabled APIs and integration engines bridging legacy and modern data standards. Health systems compete for scarce HL7 FHIR engineers who can manage multi-vendor complexity.
- Cybersecurity Tools:Threat detection, encryption, and access control systems.
- Mobile Health Applications:Patient-facing and clinician-facing tools for remote engagement.
AI-driven Analytics captures margin premiums. Interoperability Solutions face talent scarcity constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost disparities across US states are reshaping where health systems concentrate IT procurement and where vendors establish implementation centers. Texas and Florida offer lower compliance cost structures compared to California and New York, drawing vendor investment toward Sun Belt health networks.
Texas
Texas Medical Center affiliates in Houston and Dallas drive enterprise-scale EHR replacements under 21st Century Cures Act pressure. HHS Office for Civil Rights enforcement of HIPAA security rules elevates cybersecurity spending across the state's 600+ hospitals. Austin's growing health tech corridor attracts FHIR engineering talent from coastal markets.
Florida
Regional health networks in Miami and Tampa adopt cloud-native SaaS configurations to eliminate data center capital expenditures. CMS quality reporting programs tie Medicare reimbursement to certified platform functionality, accelerating procurement cycles. Orlando's simulation and training cluster supports workflow retraining for mid-tier hospital systems.
California
Silicon Valley health systems pilot AI-driven analytics for CMS penalty reduction, commanding premium pricing for predictive readmission models. FDA oversight of clinical decision support software extends development cycles for algorithm-based diagnostic vendors. Los Angeles County's safety-net hospitals face implementation cost barriers that favor modular, API-first architectures.
Illinois
Chicago's integrated delivery networks unbundle EHR contracts from professional services agreements, exposing vendor margins to competitive pressure. ONC certification requirements under the 21st Century Cures Act favor established platform vendors with compliance infrastructure. The city's health IT consultancies capture implementation and optimization work separated from software licenses.
Massachusetts
Greater Boston's academic medical centers advance interoperability standards development through HL7 FHIR implementation guides. Cybersecurity insurance escalation strains rural hospital operating budgets in western Massachusetts, creating demand for managed security services. Cambridge's health data analytics cluster monetizes de-identified clinical data for life sciences researchers.
US Healthcare IT Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native and AI-augmented positioning. The vendor base concentrates around three maturity tiers: legacy enterprise platforms with deep specialty modules, cloud-first challengers with compressed implementation timelines, and niche analytics specialists commanding premium pricing for outcome-based contracts. Dominant competitive moves include M&A to capture interoperability talent and strategic partnerships to bridge legacy HL7 v2 infrastructure with modern FHIR APIs.
Within the enterprise platform tier, Epic Systems Corporation and Cerner Corporation exemplify contrasting architectural philosophies. Epic anchors inpatient dominance through integrated specialty module development, while Cerner competes aggressively in revenue cycle and population health extensions. Oracle occupies a distinct position leveraging cloud infrastructure investments to reposition acquired assets across ambulatory and payer segments.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Cerner Corporation |
| McKesson Corporation |
| GE Healthcare |
| Oracle |
| Optum, Inc. |
| Philips Healthcare |
| Athenahealth, Inc. |
| Veradigm Inc. |
| Others |
Pricing and Supply Chain Analysis
Enterprise-grade certification tiers separate ONC-certified platforms from uncertified point solutions, compressing margins at the lower tier while anchoring premium pricing for vendors with established compliance infrastructure and forcing supply chain choices toward established platform partners over niche specialists.
Pricing Analysis
Direct-to-hospital enterprise licensing dominates with subscription tiers scaled to bed count and module depth. Three-tier pricing structure across premium, standard, and economy levels reflects ONC certification status and specialty module availability. Cost compression in the mid-tier intensifies as Epic and Cerner bundle implementation services to defend share. Rural critical access hospitals exhibit highest price sensitivity, while Texas Medical Center affiliates negotiate unbundled contracts with separate professional services statements of work.
Supply Chain Analysis
Single-source vulnerability sits with cloud infrastructure providers AWS, Microsoft Azure, and Google Cloud, which host the majority of SaaS EHR deployments and analytics workloads. Software development draws from India, Ireland, and domestic US talent pools for FHIR engineering and integration architecture. Supply chain risk centers on cybersecurity insurance escalation that strains rural hospital operating budgets and forces vendor-managed security service adoption. Distribution runs through direct enterprise sales teams with regionally staffed implementation centers in Dallas, Houston, and Austin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US Healthcare IT represents a late-cycle quality story as hospital procurement committees prioritize ONC-certified platforms with proven interoperability over unproven point solutions, elevating compliance infrastructure to a primary selection criterion.
For Market Incumbents: Deploy backward integration into FHIR engineering talent pipelines to counter scarcity-driven wage inflation. Acquire specialized interoperability consultancies in Austin and Dallas to capture implementation work separated from software licenses. Oracle's cloud infrastructure investments demonstrate how infrastructure control defends margin position against SaaS-native challengers.
For New Entrants and Emerging Players: Capture rural health network gaps in Mississippi and Alabama where implementation cost barriers exclude enterprise vendors. Target critical access hospitals with modular, API-first architectures that compress deployment timelines. Lead with AI-driven readmission prediction modules that demonstrate measurable CMS penalty reduction to justify premium positioning.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier hospital systems face legacy system switching costs that slow replacement cycles and create stranded asset risk. Long-term viability favors vendors with cloud-native architectures and established ONC certification infrastructure. Watch FHIR-enabled data monetization revenue streams as the signal indicating platform stickiness and alternative revenue model maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| ONC Certification Investment | Establishes eligibility for CMS reimbursement-linked procurement and excludes uncertified competitors. |
| FHIR Engineering Talent Acquisition | Addresses interoperability talent scarcity that delays implementation timelines and elevates project risk. |
| Cloud Infrastructure Partnership | Enables multi-tenant SaaS configurations that eliminate hospital data center capital expenditures. |
| Rural Health Network Expansion | Captures underpenetrated critical access hospitals facing implementation cost barriers from enterprise vendors. |
| AI-Driven Analytics Module Development | Commands premium pricing where predictive models demonstrably reduce CMS readmission penalties. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged hospital CIOs, health system procurement committees, GPO contracts managers, and FHIR integration architects across Texas, Florida, California, Illinois, and Massachusetts. Secondary validation drew from CMS Medicare cost reports, ONC certification databases, hospital procurement disclosures, and HHS Office for Civil Rights enforcement actions. Bottom-up vendor revenue triangulation against top-down health system IT spending estimates anchored market sizing.
Historical reference periods established baseline adoption curves for cloud migration and AI module deployment across the modeling period. Segmentation modeling incorporated product type, end user tier, deployment architecture, and technology application dimensions. CAGRs derived from weighted average of vendor guidance, health system capital budget trajectories, and regulatory mandate implementation timelines. Forecast inputs included 21st Century Cures Act compliance deadlines and CMS quality reporting program expansion.
Regulatory enforcement intensity, cybersecurity incident frequency, and cloud infrastructure pricing volatility are the dominant revision risks to the projection framework. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Aged Care Software Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Wearable Biosensors Market
Healthcare IT
Secure Messaging in Healthcare Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Healthcare Credentialing Software Market