
 Diabetic Lancing Devices Market | 2026-2036
Diabetic Lancing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Lancing Devices Market Analysis
Multi-source procurement for precision-molded plastic housings and spring mechanisms is expanding as manufacturers diversify beyond captive Asian suppliers. Becton Dickinson anchors North American production capacity through vertically integrated polymer processing. Roche differentiates via electromechanical integration expertise that bridges lancing devices with connected glucose meters. HTL-STREFA competes on specialized lancet tip geometries that reduce penetration force variance.
A diabetic lancing device is a handheld instrument that punctures skin with a controlled-depth needle to extract capillary blood for glucose testing, typically employing a spring-loaded or cam-driven mechanism with penetration depths ranging from 0.8 mm to 3.0 mm. Its primary commercial purpose is to enable reliable, minimally traumatic blood sampling for diabetes self-management and clinical diagnostics. Adjustable lancet devices occupy the largest installed base among product types due to their compatibility with varying skin thickness across pediatric and geriatric populations. Automatic lancet devices represent the fastest-growing product category as integrated sensors and one-touch operation reduce user error in home care settings. Personal monitoring applications generate the dominant revenue stream within the application dimension, though clinical diagnostics sustains higher per-unit pricing through sterilization and traceability requirements.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for market access across the United States and Europe. ISO 15197 standards for blood glucose monitoring systems indirectly govern lancing device performance through system-level accuracy mandates. Japan's PMDA enforces additional biocompatibility testing that extends approval cycles for polymer materials contacting human tissue. Stakeholders must monitor evolving reimbursement codes for continuous glucose monitors versus traditional fingerstick protocols, as payer decisions will reshape volume allocation between standalone lancing devices and integrated diabetes management platforms.
Market Dynamics
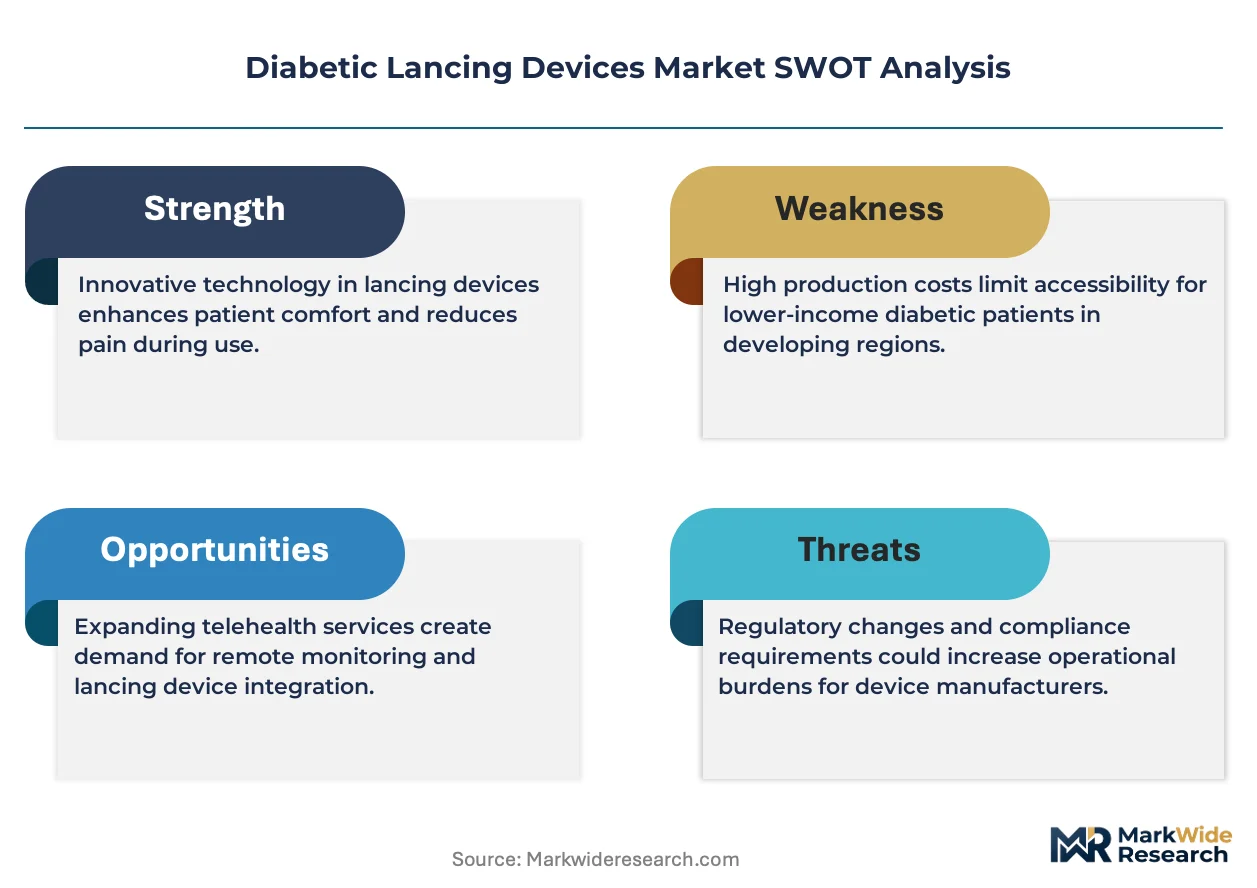
Continuous glucose monitor reimbursement expansion is compressing fingerstick protocol volumes, forcing lancing device manufacturers to pivot toward integrated diabetes management platforms and premium electromechanical features that preserve per-unit value in a contracting installed base.
Growth Catalysts
- EU Medical Device Regulation harmonization:MDR Article 117 requirements for device-drug combination products are elevating quality standards that favor established manufacturers with notified body relationships, filtering out low-cost competitors.
- Spring mechanism precision engineering:Advances in micro-coil manufacturing from Swiss and German precision metal suppliers are reducing penetration force variance below 15%, improving reproducibility for geriatric patients with compromised circulation.
- Home care protocol expansion:CMS reimbursement codes for remote patient monitoring in the United States are extending device replacement cycles and driving demand for durable, multi-use lancing platforms.
Market Restraints
- Medical-grade polymer cost volatility:Specialized acetal and polycarbonate resins for biocompatible housings face price pressure from automotive sector competition for injection-molding feedstock.
- Asian spring steel supply concentration:Cold-rolled stainless steel for precision cam mechanisms sources predominantly from Japanese and South Korean mills, creating vulnerability to regional trade friction.
- CGM substitution trajectory:Abbott and Dexcom factory-calibrated sensors are eliminating fingerstick verification requirements for Type 1 patients in reimbursement-eligible categories.
Strategic Opportunities
- India outpatient diabetes expansion:Ayushman Bharat health insurance coverage for glucometer distribution is creating first-time device access in tier-2 and tier-3 cities with limited CGM penetration.
- Lancet-sensor convergence:Integration of microfluidic channels with electrochemical detection is enabling single-step glucose measurement without separate test strips.
- Japan PMDA fast-track pathway:Sakigake designation for breakthrough medical devices is accelerating approval timelines for pain-minimizing lancet geometries targeting pediatric populations.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies for novel polymer formulations require 18-24 month timelines that delay product refresh cycles.
- Legacy meter compatibility maintenance:Proprietary lancet bayonet interfaces across Roche, LifeScan, and Ascensia device ecosystems fragment SKU portfolios and inflate inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Lancing Devices Market |
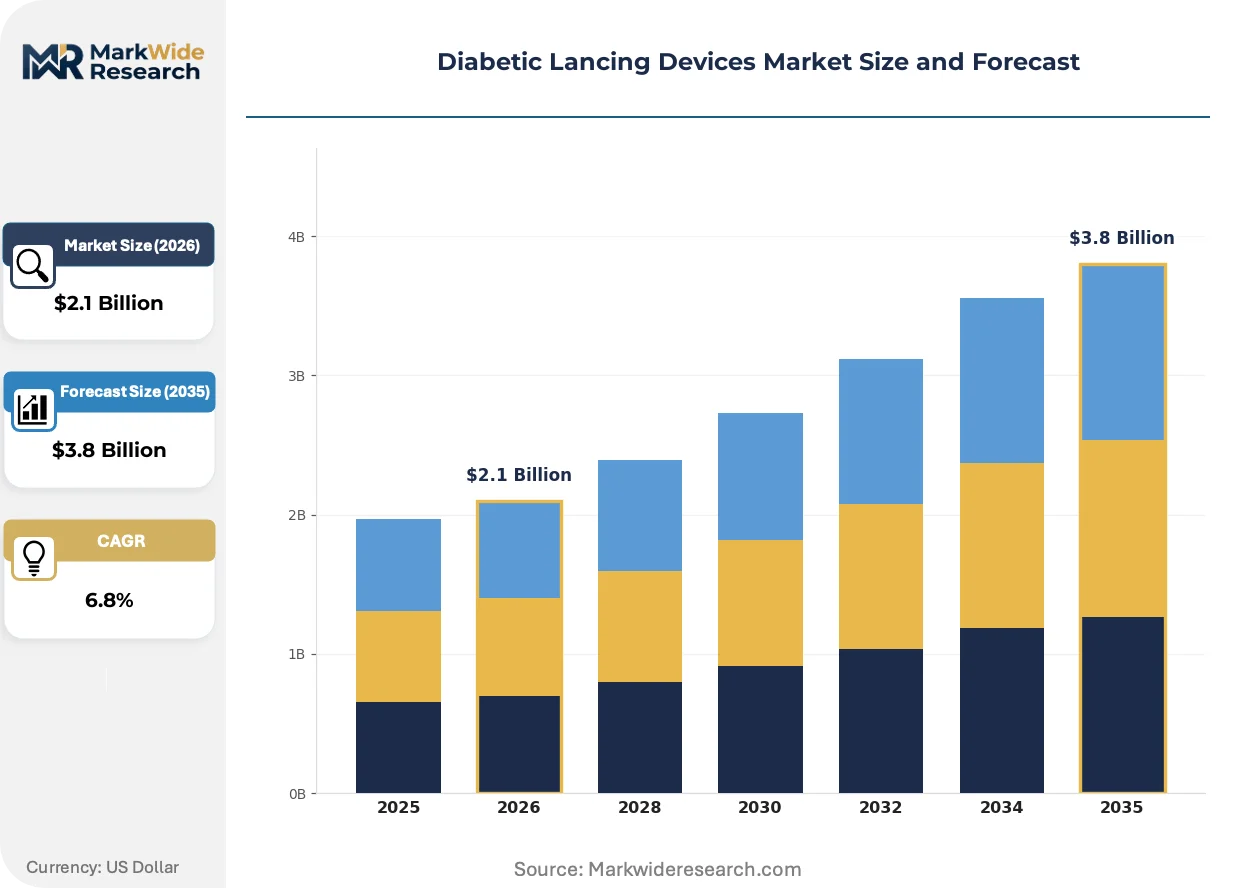
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Lancet Devices, Adjustable Lancet Devices, Automatic Lancet Devices, Thumb Lancet Devices, Spring-Loaded Devices Application: Personal Monitoring, Clinical Diagnostics, Home Care, Research Laboratories, Community Health Screening End User: Diabetes Clinics, Diagnostic Centers, Pharmacists, School Health Programs, Wellness Centers Distribution Channel: Pharmacies, Online Retailers, Medical Supply Distributors, Hospital Stores, Direct Patient Sales |
| Companies Covered | Terumo Corporation, Sanofi, Becton Dickinson, HTL-STREFA, Medtronic, Roche, B. Braun, Ypsomed Holding, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Lancing Devices Market Emerging Trajectories
Electromechanical miniaturization and connectivity integration are transforming lancing devices from mechanical commodities into data-capture nodes within closed-loop diabetes management systems.
Silicone microneedle arrays are rewriting blood extraction protocols by enabling sub-1 mm penetration depths with capillary action sampling. Pediatric endocrinology practices in Germany and the Netherlands are piloting these platforms for pain-sensitive populations. The technology is compressing the distinction between lancing devices and continuous monitoring inserts.
Japan's PMDA revised biocompatibility guidance for polymer-contacting devices now mandates extended leachable studies for materials with skin contact exceeding 24 hours. Manufacturers are reformulating acetal housings to meet revised extractables thresholds. This regulatory tightening is advantaging suppliers with in-house polymer compounding capabilities.
Hospital procurement consortia in the United States are consolidating glucose monitoring contracts under single-source agreements that bundle lancing devices, test strips, and data management software. IDN purchasing organizations are displacing fragmented GPO arrangements that previously allowed point-of-care autonomy. This concentration is most visible in the Southeast and Midwest health system alliances.
Diabetic Lancing Devices Market Segmentation
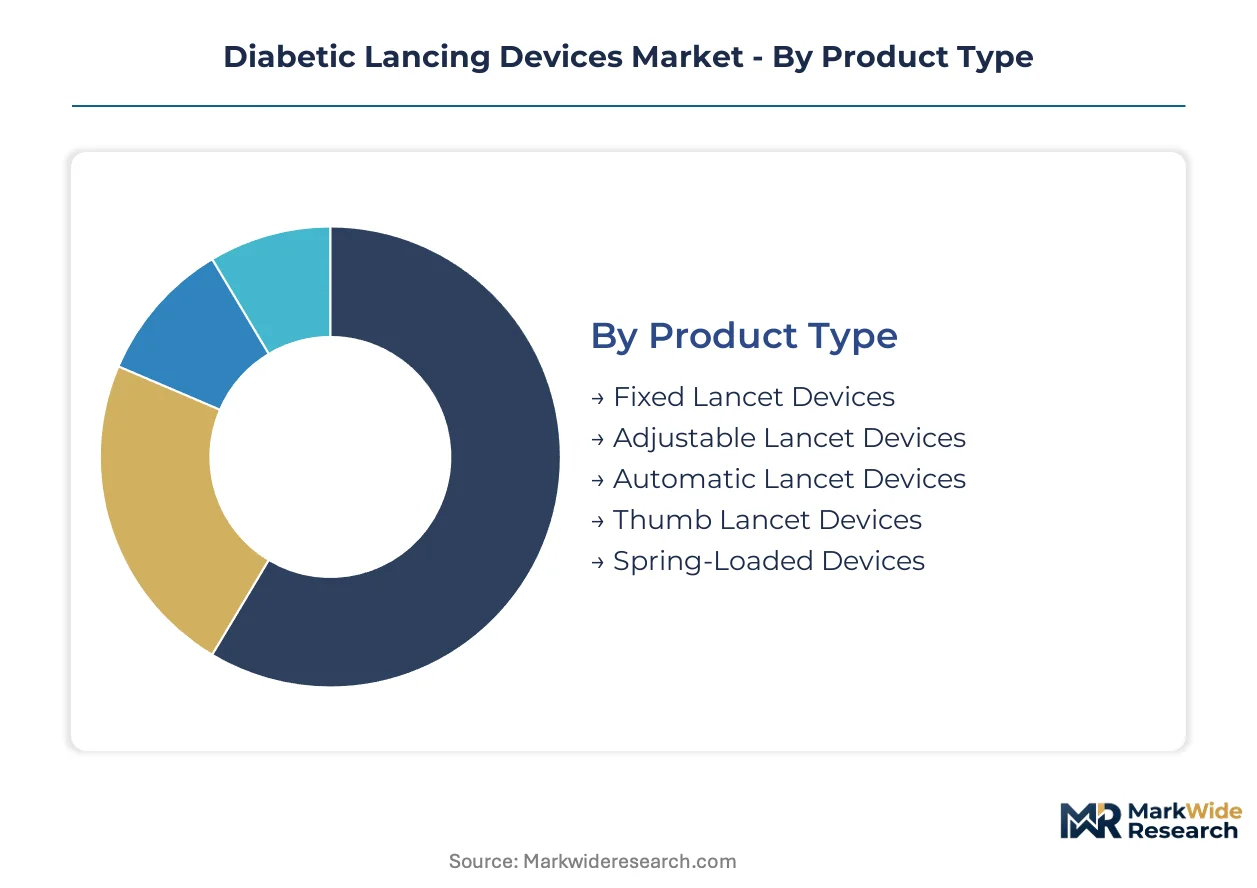
Segmentation in diabetic lancing devices reveals how mechanical design choices, care settings, and procurement pathways create distinct value pools. Manufacturers must align product specifications with reimbursement codes and user dexterity profiles across each slice.
Product Type:
Adjustable lancet devices command the largest installed base through compatibility with pediatric and geriatric skin thickness variance, while automatic lancet devices extract premium pricing via integrated sensor feedback.
- Fixed Lancet Devices:Single-depth penetration mechanisms with molded plastic housings and pre-calibrated spring constants. Demand concentrates in emerging market pharmacy channels where cost minimization overrides customization needs, though limited depth flexibility restricts use in pediatric populations.
- Adjustable Lancet Devices:Cam-driven depth selectors spanning 0.8 mm to 3.0 mm penetration settings with detented adjustment rings. Germany's statutory health insurance reimbursement framework favors these platforms for home care prescriptions, driving volume through retail pharmacy networks serving elderly diabetes patients.
- Automatic Lancet Devices:Electromechanical platforms with one-touch firing and penetration force sensors that reduce user error.
- Thumb Lancet Devices:Manual pressure-actuated designs without spring mechanisms, common in low-resource settings.
- Spring-Loaded Devices:Traditional coil-spring mechanisms with replaceable lancet carriers.
Today's leader: Adjustable Lancet Devices. Tomorrow's challenger: Automatic Lancet Devices.
Application:
Personal monitoring generates recurring revenue through device replacement cycles, whereas clinical diagnostics sustains higher per-unit margins via sterilization and traceability requirements.
- Personal Monitoring:Daily self-testing protocols in home environments with patient-purchased devices and third-party lancet compatibility. United States CMS remote patient monitoring reimbursement codes are extending replacement intervals for durable platforms, concentrating demand through mail-order pharmacy channels.
- Clinical Diagnostics:Point-of-care testing in controlled settings with single-use sterility mandates and lot-tracking requirements. Japan's PMDA biocompatibility testing for polymer-contacting devices elevates compliance costs, filtering out low-cost suppliers from hospital procurement tenders.
- Home Care:Nurse-administered testing in residential settings with documentation requirements.
- Research Laboratories:Precision-controlled sampling for glucose variability studies.
- Community Health Screening:Mass testing events with disposable device economics.
Personal Monitoring anchors current volume. Clinical Diagnostics offers the steepest expansion trajectory for premium-tier manufacturers.
End User:
Procurement authority fragments across prescribing physicians, procurement consortia, and direct patient purchases, creating divergent pricing and specification requirements.
- Diabetes Clinics:Specialized endocrinology practices with protocol standardization and volume purchasing agreements. United States IDN purchasing organizations in the Southeast and Midwest are consolidating glucose monitoring contracts under single-source bundles that include lancing devices, test strips, and data management software.
- Diagnostic Centers:High-throughput facilities with workflow automation and sterility validation. Germany's outpatient laboratory accreditation requirements mandate traceable lot records for all capillary sampling devices, favoring suppliers with integrated data systems.
- Pharmacists:Retail dispensing with over-the-counter and prescription fulfillment.
- School Health Programs:Pediatric-focused procurement with pain-minimization priorities.
- Wellness Centers:Preventive screening with consumer-oriented device aesthetics.
Diagnostic Centers dominate premium contract value. Diabetes Clinics are consolidating fastest into bundled purchasing.
Distribution Channel:
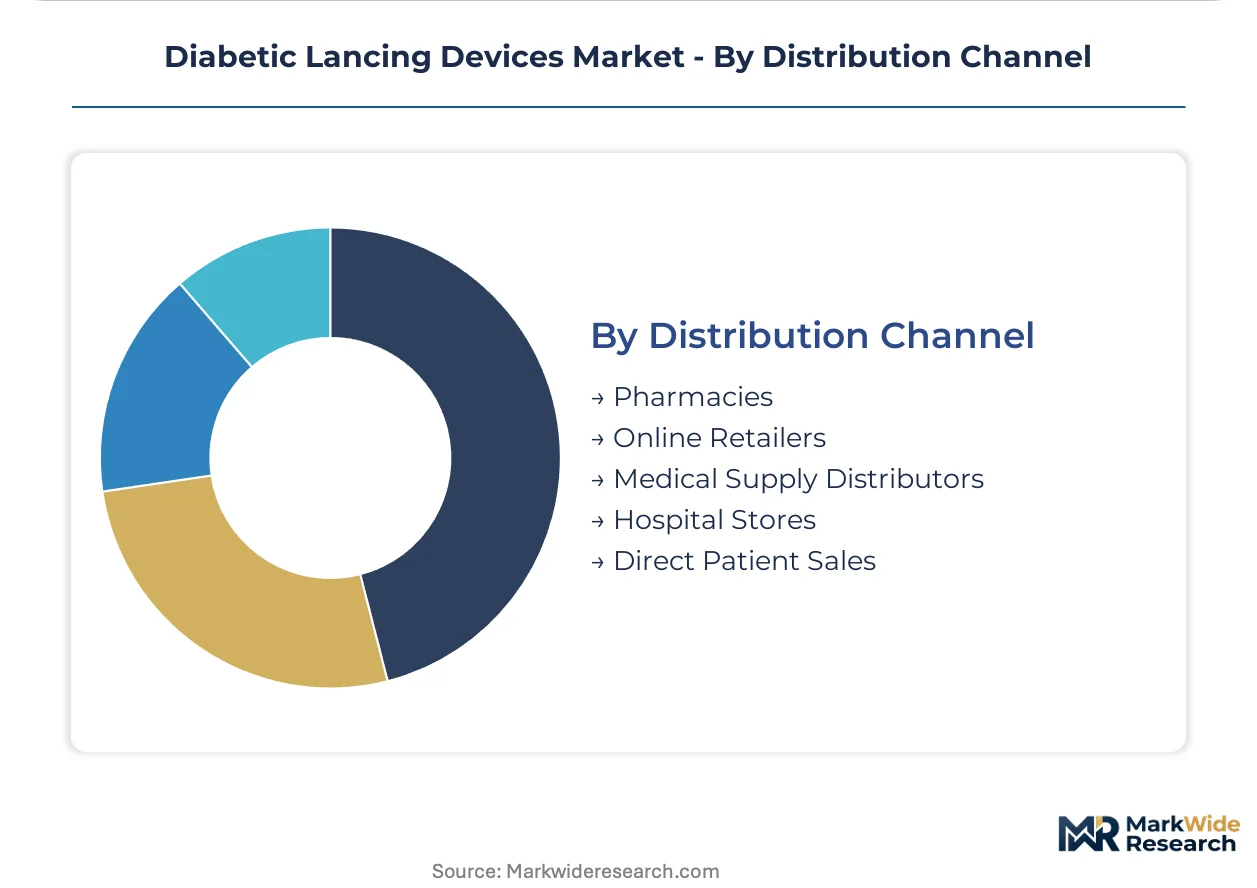
Channel selection determines margin structure and patient adherence support levels, with direct models capturing replacement revenue and pharmacy networks ensuring formulary placement.
- Pharmacies:Brick-and-mortar retail with pharmacist counseling and insurance adjudication. Japan's dispensing pharmacy separation policy concentrates lancing device sales through registered drug retailers with reimbursement code expertise, creating high barriers for direct-to-consumer entrants.
- Online Retailers:E-commerce platforms with subscription replenishment and price transparency. United States Amazon and specialized diabetes supply sites are displacing traditional medical supply distributors for replacement lancet purchases, compressing margins through comparison shopping.
- Medical Supply Distributors:B2B wholesale with inventory management and clinic servicing.
- Hospital Stores:Captive retail within acute care facilities.
- Direct Patient Sales:Manufacturer-owned channels with loyalty programs and data integration.
Pharmacies retain the dominant share. Online Retailers are gaining share fastest among replacement purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision polymer processing clusters in the United States anchor production capacity for electromechanical lancing platforms, while reimbursement pathways in Germany and Japan concentrate demand for premium adjustable devices among aging diabetes populations.
United States
CMS remote patient monitoring codes extend device replacement cycles for durable home care platforms. FDA 510(k) clearance pathways shape clinical evidence requirements for spring-loaded mechanisms. Southeast and Midwest health system alliances consolidate glucose monitoring contracts under bundled single-source agreements.
Germany
Statutory health insurance reimbursement frameworks favor adjustable-depth lancet devices for elderly home care prescriptions. EU Medical Device Regulation Article 117 elevates quality standards for device-drug combination products. Precision metal suppliers in Baden-Württemberg reduce penetration force variance through micro-coil manufacturing advances.
Japan
PMDA biocompatibility testing mandates for polymer-contacting devices extend approval timelines for acetal housing formulations. Sakigake fast-track designation accelerates market access for pain-minimizing lancet geometries targeting pediatric endocrinology. Kanto region dispensing pharmacy separation concentrates sales through registered drug retailers.
India
Ayushman Bharat health insurance coverage creates first-time device access in tier-2 and tier-3 cities with limited continuous glucose monitor penetration. Central Drugs Standard Control Organization regulates import pathways for electromechanical platforms. Maharashtra and Gujarat manufacturing clusters assemble cost-optimized spring-loaded devices for pharmacy channels.
Diabetic Lancing Devices Market Vendor Landscape
Global majors compete with regional champions across polymer processing and precision metal fabrication capabilities. Market structure tilts toward consolidated electromechanical integration at the premium tier and fragmented mechanical assembly at the economy tier. Three archetypes dominate: vertically integrated polymer processors, specialized lancet geometry designers, and electromechanical system integrators. Capacity expansion in precision-molded housings and strategic partnerships for spring mechanism sourcing represent the dominant competitive moves.
Among Japanese precision fabricators, Terumo Corporation exemplifies the vertically integrated polymer processing archetype. Roche and Becton Dickinson occupy positions bridging lancing devices with connected glucose management platforms. HTL-STREFA represents specialized lancet tip geometry expertise.
| Leading Market Players |
|---|
| Terumo Corporation |
| Sanofi |
| Becton Dickinson |
| HTL-STREFA |
| Medtronic |
| Roche |
| B. Braun |
| Ypsomed Holding |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Family-owned precision metal fabricators in Baden-Württemberg and sovereign-backed polymer processors in Japan anchor tier-one supply capacity, translating captive spring mechanism expertise into pricing power that resists commoditization pressure from Asian mechanical assembly competitors.
Pricing Analysis
Medical-grade polymer cost pass-through from automotive sector competition for injection-molding feedstock is compressing margins at the economy tier while premium electromechanical platforms preserve value through sensor integration. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared automatic devices with connectivity features from adjustable mechanical units and fixed-depth pharmacy-channel alternatives. Pricing pressure stems from CGM substitution eliminating fingerstick protocols for Type 1 reimbursement categories. Hospital procurement consortia exhibit lowest price sensitivity due to bundled single-source contracts, while emerging market pharmacy channels face acute cost compression.
Supply Chain Analysis
Japan's PMDA biocompatibility testing requirements and India's phased manufacturing program for medical devices are reshaping sourcing patterns toward qualified domestic compounders and assembly partners. Precision spring mechanisms draw from Japanese and South Korean cold-rolled stainless steel mills, while biocompatible acetal and polycarbonate housings source from German and United States polymer processors. Single-source vulnerability concentrates in Swiss and German micro-coil suppliers serving penetration force variance specifications. Distribution runs through hospital procurement consortia in the United States, statutory health insurance pharmacy networks in Germany, and dispensing pharmacy separation channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where continuous glucose monitor reimbursement expansion is forcing demand toward premium electromechanical specifications that preserve per-unit value in a contracting fingerstick installed base.
For Market Incumbents: Deepen electromechanical integration capabilities that bridge lancing devices with connected glucose management platforms, defending against CGM substitution by embedding sensors and data capture. Fortify notified body relationships under EU MDR Article 117 to filter low-cost competitors from device-drug combination product tenders. Prioritize in-house polymer compounding to meet Japan's revised PMDA leachable thresholds without 18-24 month biocompatibility testing delays. For New Entrants and Emerging Players: The price-point gap between premium automatic devices and economy fixed-depth alternatives offers white-space entry through mid-tier adjustable platforms with depth customization. Target India's tier-2 and tier-3 cities under Ayushman Bharat coverage where CGM penetration remains minimal and first-time device access is expanding. Pursue pediatric pain-minimization positioning via Japan's Sakigake fast-track pathway for novel lancet geometries. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized lancet geometry designers with proprietary tip configurations but limited electromechanical integration scale. Long-term viability over the analysis window hinges on convergence toward closed-loop diabetes management systems where standalone mechanical devices face obsolescence. Watch CMS reimbursement code decisions for remote patient monitoring as the inflection signal for durable multi-use platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Integration Investment | Sensor-enabled automatic devices bridge the gap to connected glucose management ecosystems. |
| Notified Body Relationship Expansion | EU MDR Article 117 compliance filters low-cost competitors from device-drug combination tenders. |
| Pediatric Pain-Minimization Development | Japan's Sakigake designation accelerates approval for novel lancet geometries in sensitive populations. |
| India Distribution Partnership | Ayushman Bharat coverage in tier-2 and tier-3 cities creates first-time device access at scale. |
| In-House Polymer Compounding | PMDA biocompatibility tightening advantages suppliers with captive material formulation capabilities. |
Methodological Framework
Multiple input streams — structured interviews with diabetes device product managers, hospital GPO contracts managers, and regulatory affairs specialists; secondary validation through FDA 510(k) filings, EU MDR notified body documentation, and CMS reimbursement code databases; plus customs records for polymer and spring steel trade flows — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from procurement directors at United States IDNs and German statutory health insurance funds. The analytical framework models demand across product type, application setting, end-user procurement authority, and distribution channel dimensions throughout the forecast period. CAGRs were derived from penetration force variance reduction curves, CGM substitution elasticities, and reimbursement code expansion timelines for remote patient monitoring protocols.
Caveats apply where continuous glucose monitor factory-calibration advances or payer coverage decisions for non-fingerstick protocols could materially shift the outlook for standalone lancing device demand. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Insulin Patch Pumps Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Diabetic Ketoacidosis Treatment Market