
 Wearable Glucometers Market | 2026-2036
Wearable Glucometers Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Glucometers Market Analytics
The capital-intensity divergence between sensor substrate fabrication and software-only app developers is unwinding competitive boundaries across the wearable glucometer landscape. Abbott Laboratories leverages vertically integrated manufacturing of electrochemical sensors to sustain price discipline in pharmacy and direct-to-consumer channels. Dexcom, Inc. anchors its position through proprietary transmitter-receiver architectures that dominate clinician prescribing workflows in integrated health systems.
Wearable glucometers are electrochemical or optical biosensing devices affixed to the body surface, typically measuring interstitial glucose concentrations via enzyme-coated electrodes or near-infrared spectroscopy at 5–15 minute intervals for diabetes management and metabolic tracking. Continuous glucose monitors command the dominant installed base among product types, while non-invasive optical sensors represent the fastest-growing technology segment as manufacturers pursue needle-free alternatives. Microneedle technology occupies an emerging margin pool, bridging accuracy requirements with reduced skin trauma for fitness enthusiasts and pre-diabetic populations.
FDA premarket review under 21 CFR 862.1355 and CE marking under the EU MDR govern device accuracy thresholds and biocompatibility standards, directly shaping which sensor technologies achieve commercial scale in the United States and European markets. The FDA's breakthrough devices program accelerates pathways for non-invasive platforms, while ISO 15197 calibration requirements constrain market access for lower-accuracy health tracker entrants. Stakeholders must monitor reimbursement coding decisions by Medicare and Germany's G-BA, as these determinations will dictate whether optical and microneedle formats expand beyond self-pay diabetic segments into broader chronic disease management contracts.
Market Dynamics
Continuous glucose monitoring is displacing fingerstick blood glucose meters as the standard of care, compressing reimbursement timelines and forcing manufacturers to secure integrated health system contracts before pharmacy channel access.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage determinations for therapeutic CGM in Type 2 diabetes populations remove out-of-pocket barriers for elderly patients in the United States.
- Optical sensor maturation:Near-infrared spectroscopy advances reduce calibration requirements, enabling needle-free glucose tracking for fitness and pre-diabetic segments.
- Home care migration:Post-acute care models shift chronic disease management from clinics to residential settings, accelerating demand for connected monitoring devices.
Market Restraints
- Palladium electrode cost volatility:Electrochemical sensor fabrication depends on precious metal catalysts subject to commodity price swings and Russian supply concentration.
- ISO 15197 calibration barriers:Stringent accuracy thresholds for self-monitoring blood glucose systems block health tracker entrants from clinical-grade claims.
- Skin adhesion chemistry limitations:Extended wear periods require biocompatible adhesives that balance sweat resistance with reduced dermal irritation, constraining 14-day sensor durability.
Strategic Opportunities
- Pre-diabetic population penetration:Germany's DMP disease management programs create reimbursement pathways for metabolic tracking in at-risk cohorts before insulin dependence.
- Microneedle-hydrogel convergence:Dissolvable microneedle arrays paired with enzymatic hydrogels bridge accuracy and comfort gaps for athletic performance monitoring.
- Direct-to-consumer pharmacy channels:CVS and Walgreens shelf placement bypasses prescription workflows, capturing self-pay wellness segments outside traditional diabetes care.
Industry Challenges
- Biocompatibility certification timelines:FDA 510(k) review cycles for novel adhesive polymers extend 18-24 months, delaying product refresh cadences.
- RF transmitter integration complexity:Bluetooth Low Energy firmware must coexist with insulin pump communication protocols in closed-loop artificial pancreas systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Glucometers Market |
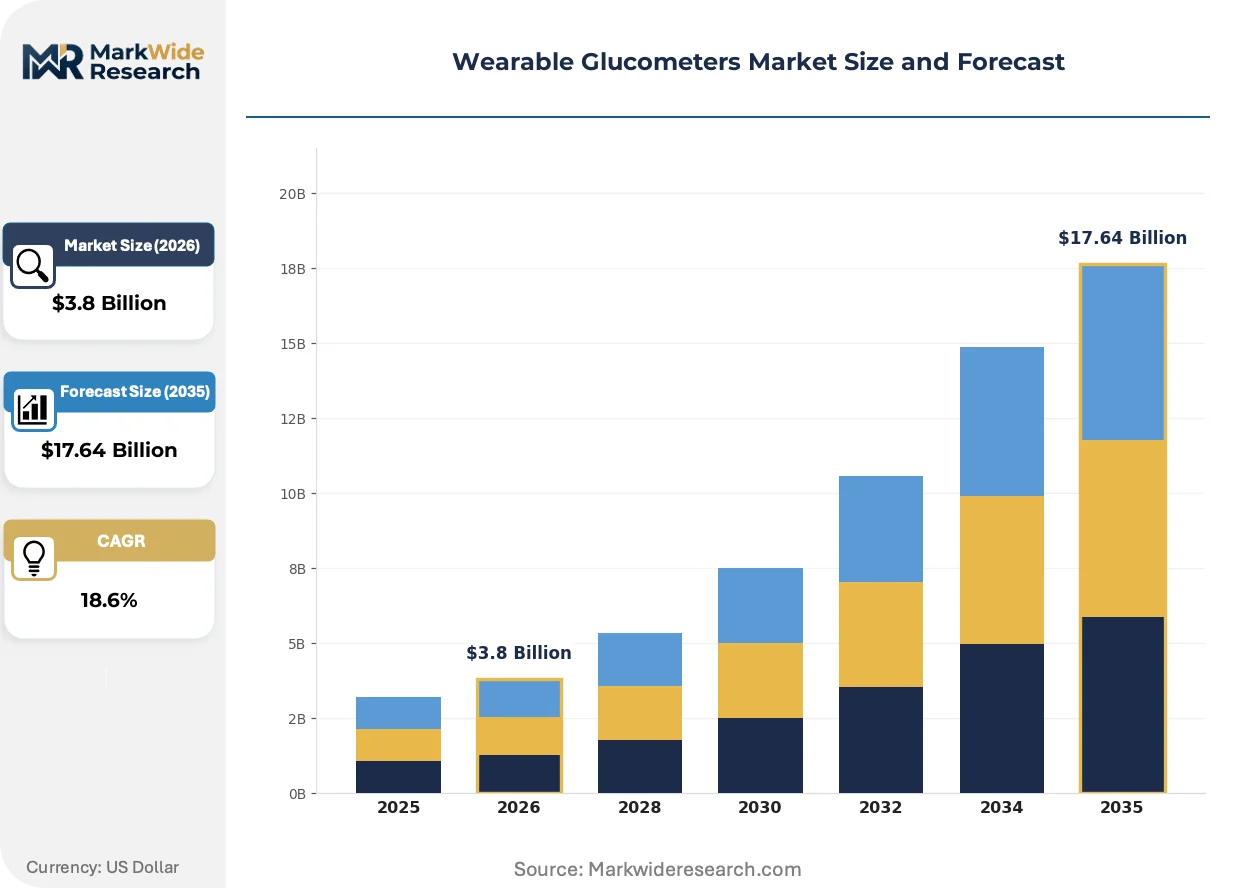
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Glucose Monitors, Flash Glucose Monitors, Smartwatches, Health Trackers Technology: Enzyme-Based Sensors, Non-Invasive Sensors, Optical Sensors, Microneedle Technology End User: Diabetic Patients, Healthcare Providers, Fitness Enthusiasts, Research Institutions Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Direct Sales |
| Companies Covered | Abbott Laboratories, Dexcom, Inc., Medtronic plc, Senseonics Holdings, Inc., F. Hoffmann-La Roche Ltd., Insulet Corporation, B. Braun Melsungen AG, Ascensia Diabetes Care Holdings AG, LifeScan, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Glucometers Market Evolving Landscape
Sensor form factors are collapsing toward imperceptible wearables while regulatory frameworks race to accommodate non-invasive platforms. Manufacturers now compete on data integration speed rather than standalone accuracy.
Microneedle array technology is miniaturizing glucose sensing into patch formats thinner than adhesive bandages. Fitness enthusiasts and gestational diabetes patients adopt these devices for discrete metabolic feedback during exercise and pregnancy. The shift is compressing differentiation between medical-grade and wellness-oriented hardware, forcing electrochemical incumbents to defend pharmacy formulary placement against optical challengers.
CE marking under the EU MDR now requires clinical evidence from intended-use populations, not just healthy volunteers. This elevates trial costs for non-invasive optical sensors targeting broader diabetic segments. German and French notified bodies are prioritizing reviews for needle-free alternatives, compressing time-to-market for spectroscopy-based platforms relative to traditional electrochemical submissions.
Employer-sponsored wellness programs are unbundling glucose monitoring from diabetes management contracts. Large self-insured corporations in the United States now subsidize CGM subscriptions for metabolic health optimization among non-diabetic workforces. This procurement pivot redirects vendor sales efforts from endocrinology clinics toward benefits administrators and occupational health departments.
Wearable Glucometers Market Segmentation
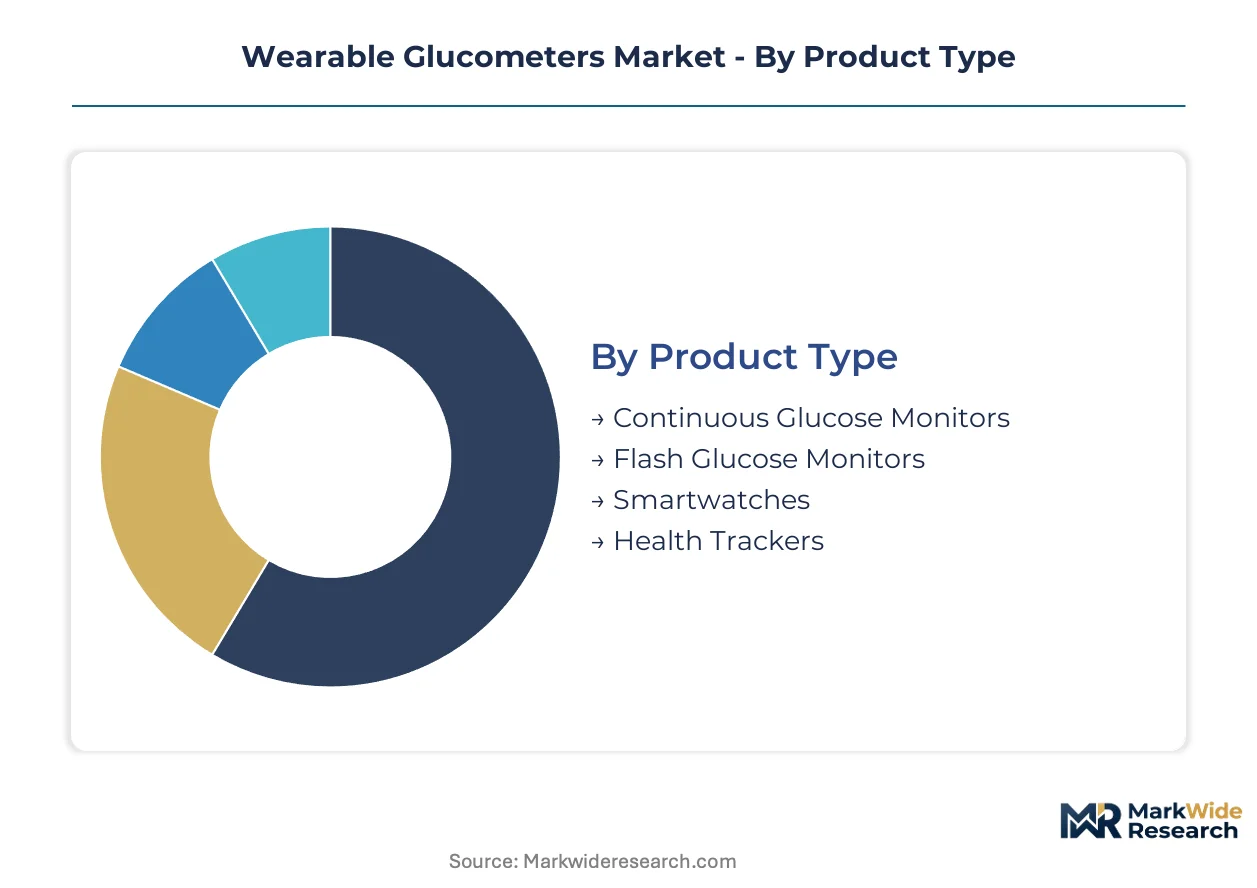
Wearable glucometer manufacturers route distinct product categories through divergent commercial channels. Channel economics and reimbursement access determine which segments achieve volume scale versus margin concentration.
Product Type:
Continuous glucose monitors flow through pharmacy and integrated health system procurement, while flash monitors and consumer wearables concentrate in direct-to-consumer and online channels.
- Continuous Glucose Monitors:Electrochemical sensor systems with subcutaneous filament insertion measure interstitial glucose at 5-minute intervals. Demand concentrates in Medicare-eligible Type 2 populations across the United States as CMS expands therapeutic CGM coverage, though pharmacy formulary placement remains contested.
- Flash Glucose Monitors:Factory-calibrated sensors eliminate fingerstick confirmation requirements through interstitial fluid scanning. Germany's G-BA reimbursement decisions for broader diabetic populations drive European adoption, compressing time-to-treatment for newly diagnosed patients.
- Smartwatches:Optical photoplethysmography modules enable non-invasive glucose estimation for wellness tracking. Apple and Samsung hardware partnerships channel these through consumer electronics retail.
- Health Trackers:Fitness-oriented bands with metabolic monitoring target pre-diabetic and athletic segments. Direct-to-consumer subscription models bypass prescription workflows entirely.
Continuous Glucose Monitors dominate installed base. Flash Glucose Monitors is where expansion concentrates.
Technology:
Cost tiers separate clinical-grade electrochemical platforms from emerging optical and microneedle alternatives targeting wellness price points.
- Enzyme-Based Sensors:Glucose oxidase-coated electrodes catalyze electron transfer for amperometric detection. Palladium catalyst cost volatility constrains margin stability for manufacturers dependent on Russian supply concentration.
- Non-Invasive Sensors:Near-infrared spectroscopy and impedance-based approaches eliminate dermal penetration. FDA breakthrough device designations accelerate review timelines for optical platforms targeting needle-averse populations.
- Optical Sensors:Raman spectroscopy and photonic crystal technologies measure glucose through skin transmittance. CE marking under EU MDR now requires diabetic population evidence rather than healthy volunteer data, elevating trial costs.
- Microneedle Technology:Dissolvable polymer arrays penetrate stratum corneum for interstitial fluid sampling without sustained implantation. Fitness enthusiasts and gestational diabetes patients in Japan and Germany adopt these for discrete metabolic feedback.
Enzyme-Based Sensors anchor clinical reimbursement. Optical Sensors are climbing the fastest toward commercial scale.
End User:
Customer type determines pricing power, with healthcare providers commanding volume discounts and fitness enthusiasts accepting premium self-pay positioning.
- Diabetic Patients:Insulin-dependent and non-insulin-dependent populations requiring glycemic control for complication prevention. Medicare coverage expansion in the United States removes out-of-pocket barriers for elderly cohorts.
- Healthcare Providers:Endocrinology clinics and integrated health systems prescribing CGM as standard of care. Prescribing workflow integration with electronic health records determines vendor selection.
- Fitness Enthusiasts:Athletic populations optimizing metabolic performance through real-time glucose visibility. Employer-sponsored wellness programs in self-insured US corporations now subsidize subscriptions.
- Research Institutions:Academic medical centers and pharmaceutical companies utilizing CGM for clinical trial endpoints and metabolic research. Data licensing agreements generate secondary revenue streams for device manufacturers.
Diabetic Patients represent the core revenue base. Fitness Enthusiasts is where customer acquisition costs are compressing fastest.
Distribution Channel:
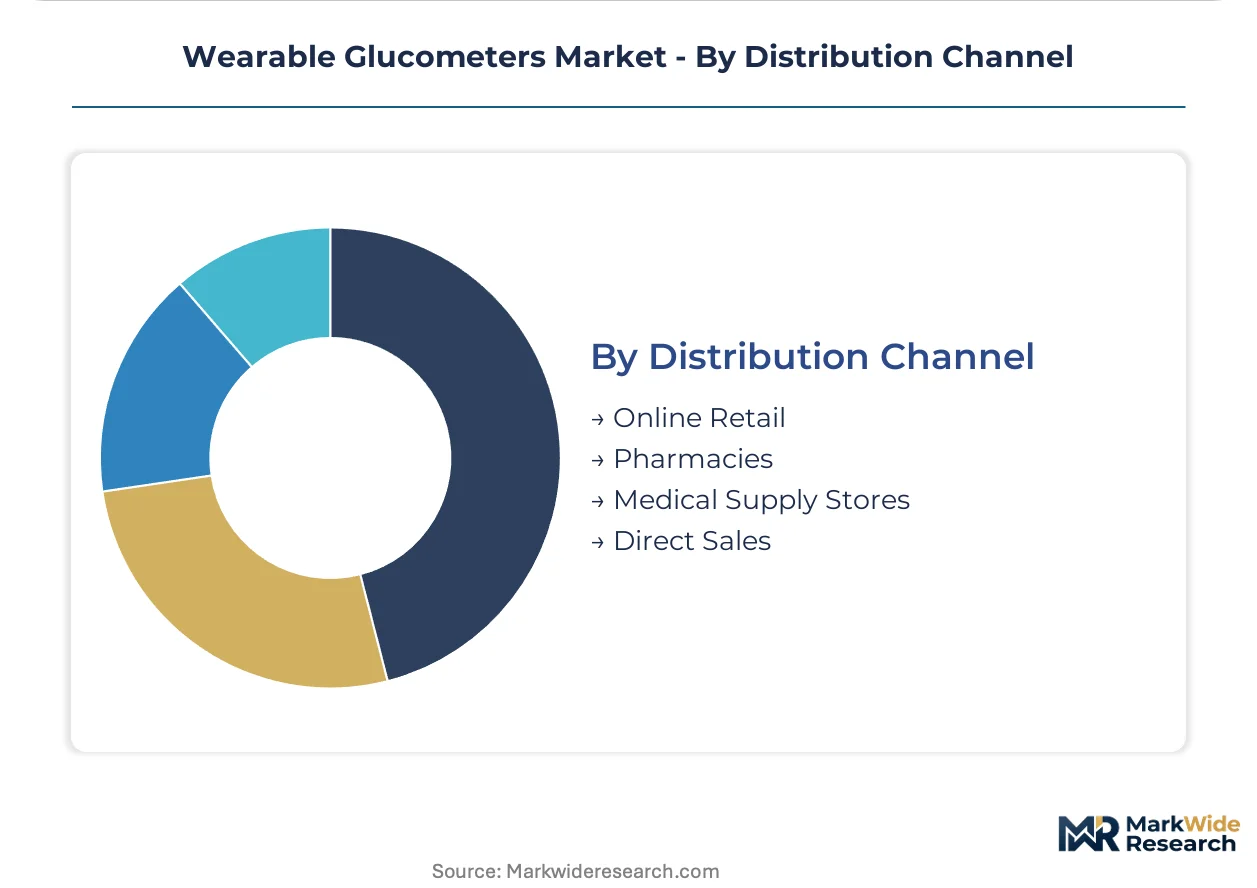
Supply concentration varies sharply, with pharmacy chains controlling clinical access and online platforms capturing wellness-oriented self-pay demand.
- Online Retail:Amazon and manufacturer-direct storefronts bypass prescription requirements for non-invasive and wellness-tier devices. Subscription auto-renewal models improve lifetime value metrics.
- Pharmacies:CVS, Walgreens, and independent pharmacy networks control Medicare Part B reimbursed CGM distribution. Formulary placement negotiations determine market access for electrochemical incumbents.
- Medical Supply Stores:Durable medical equipment suppliers serving home healthcare and long-term care facilities. Competitive bidding programs compress margins for Medicare-funded transactions.
- Direct Sales:Manufacturer field forces targeting integrated health systems and employer wellness programs. Account-based selling supports closed-loop artificial pancreas system integration.
Pharmacies dominate reimbursed volume. Online Retail is where self-pay expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in wearable glucometers tilt toward net import dependence in markets with concentrated manufacturing bases. The United States absorbs the largest absolute volume of CGM devices despite substantial domestic production capacity.
United States
Medicare coverage expansion for therapeutic CGM in Type 2 diabetes drives elderly patient adoption across Medicare Advantage networks. FDA breakthrough device designations accelerate premarket review timelines for optical sensor platforms. The Minneapolis-St. Paul corridor hosts Medtronic's operational headquarters and integrated health system pilot programs.
Germany
G-BA reimbursement decisions for flash glucose monitors compress patient out-of-pocket exposure in statutory health insurance. CE marking under EU MDR requires diabetic population clinical evidence rather than healthy volunteer data. The Mannheim-Heidelberg biotech cluster concentrates enzymatic sensor R&D and notified body consulting services.
Japan
PMDA fast-track reviews for microneedle-based glucose sensors target gestational diabetes and fitness tracking applications. METI funding programs support near-infrared spectroscopy development for needle-free alternatives. Tokyo-Osaka medical device corridors host manufacturing partnerships between domestic electronics firms and diabetes care specialists.
United Kingdom
NICE technology appraisals determine NHS England funding eligibility for CGM versus flash monitor prescriptions. MHRA post-Brexit regulatory autonomy permits accelerated approval pathways for CE-marked devices with European precedent. The Oxford-Cambridge arc concentrates optical biosensor university spinouts and clinical trial infrastructure.
India
CDSCO medical device rules classify wearable glucometers under risk-based licensing with mandatory BIS standards compliance. PLI scheme incentives attract electrochemical sensor component manufacturing for export markets. Hyderabad-Bengaluru medical technology corridors host contract research organizations serving multinational device trials.
Wearable Glucometers Market Competitive Landscape
Concentration sits with diversified medtech conglomerates controlling vertically integrated sensor fabrication and transmitter-receiver architectures. The vendor base spans three tiers: established diabetes care incumbents with pharmacy formulary dominance, emerging optical sensor specialists pursuing FDA breakthrough pathways, and consumer electronics entrants leveraging smartphone integration. Strategic moves center on securing integrated health system contracts before pharmacy channel access and compressing adhesive polymer certification timelines through pre-submission FDA engagement.
Within the diversified medtech tier, Abbott Laboratories and Dexcom exemplify contrasting defensive positions—Abbott through electrochemical sensor manufacturing scale and Dexcom through proprietary transmitter architectures embedded in clinician prescribing workflows. Medtronic occupies a hybrid position spanning insulin pump integration and standalone CGM distribution. These three anchors demonstrate how reimbursement coding capture and health system EHR integration determine competitive durability against optical challengers.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom, Inc. |
| Medtronic plc |
| Senseonics Holdings, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Insulet Corporation |
| B. Braun Melsungen AG |
| Ascensia Diabetes Care Holdings AG |
| LifeScan, Inc. |
| Others |
Value Network & Pricing Analysis
Optical sensor substrate migration from silicon to flexible polymer films simultaneously redraws manufacturing geography toward East Asian electronics corridors and compresses per-unit sensor economics for non-invasive platforms. This substrate substitution weakens palladium-dependent electrochemical incumbents while elevating contract manufacturers with roll-to-roll printing capabilities in Taiwan and South Korea.
Pricing Analysis
Healthcare provider procurement committees anchor pricing stratification across premium, standard, and economy tiers, with FDA breakthrough device certification commanding 40-60% premiums over CE-marked equivalents. Price differentiation hinges on calibration-free operation and Medicare reimbursement coding capture, with pharmacy formulary placement determining volume access. Pricing pressure stems from optical sensor challengers bypassing prescription workflows through direct-to-consumer channels, compressing margins for electrochemical systems dependent on clinician prescribing. Self-pay fitness enthusiasts exhibit lowest price sensitivity, while Medicare-eligible Type 2 populations in the United States face highest out-of-pocket cost barriers absent coverage determination.
Supply Chain Analysis
Container availability constraints on transpacific lanes from Shanghai and Busan elevate inbound logistics costs for enzyme-coated electrode substrates sourced from Japanese specialty chemical producers. Manufacturing concentration centers on the United States, Germany, and Japan for electrochemical sensor fabrication, with China and South Korea dominating optical component assembly. Raw material dependencies include palladium catalysts, glucose oxidase enzymes, and near-infrared photodetector arrays. Single-source vulnerability concentrates in Russian palladium supply for electrochemical platforms. Distribution runs through pharmacy chains for reimbursed clinical devices and online retail for wellness-tier optical alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-software bundling accelerates faster than standalone device sales, with data analytics subscriptions and insurer wellness program integrations expanding recurring revenue pools beyond sensor replacement cycles.
For Market Incumbents: Shield pharmacy formulary position by accelerating adhesive polymer biocompatibility certification through pre-submission FDA engagement, compressing 18-24 month review cycles. Deepen backward integration into glucose oxidase enzyme production to offset palladium cost volatility from Russian supply concentration. Prioritize closed-loop artificial pancreas system integration with insulin pump partners to lock in clinician prescribing workflows against optical challengers. For New Entrants and Emerging Players: Data interoperability gaps in employer wellness program administration create white-space targeting opportunities for subscription-native platforms with API-first architectures. Penetrate pre-diabetic metabolic tracking segments in Germany's DMP disease management programs before insulin dependence onset, where reimbursement pathways remain underdeveloped. Pursue direct-to-consumer pharmacy shelf placement at CVS and Walgreens to bypass prescription bottlenecks entirely. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors optical sensor specialists with FDA breakthrough designations and CE marking momentum over electrochemical incumbents facing commodity input pressure. Long-term viability across the analysis window favors platforms with software companion revenue attach rates exceeding hardware replacement cycles. Watch Medicare coverage determination timelines for non-invasive platforms as the critical inflection signal for optical sensor commercial scale.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates premarket review timelines for optical sensor platforms targeting needle-averse diabetic populations. |
| CE Marking Under EU MDR | Requires diabetic population clinical evidence, elevating trial costs but creating regulatory moats for compliant entrants. |
| Hospital System Partnership | Secures EHR integration and clinician prescribing workflow embedding before pharmacy channel access. |
| Software Companion Development | Enables subscription revenue models and insurer wellness program data licensing beyond hardware sales. |
| Reimbursement Strategy | Determines Medicare Part B and Germany G-BA coverage eligibility, removing out-of-pocket barriers for elderly cohorts. |
Research Methodology
The analysis maps continuous glucose monitors, flash glucose monitors, smartwatches, and health trackers, each validated through endocrinologists, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Primary interviews with device manufacturers and pharmacy procurement directors combined with secondary validation against FDA 510(k) filings, CE marking databases, CMS Medicare coverage determinations, and hospital procurement records. Bottom-up sensor shipment estimates triangulated against top-down reimbursement expenditure data across the projection horizon.
Consistency checks validated volume and value outputs against external benchmarks including Medicare CGM penetration statistics and statutory health insurance expenditure reports. The analytical framework models product type, technology platform, end user segment, and distribution channel dimensions throughout the forecast period. CAGRs derive from installed base growth curves, replacement cycle compression, and pricing trajectory assumptions. Industry-specific inputs include adhesive polymer certification timelines and optical sensor accuracy validation studies.
Underlying assumptions cover Medicare coverage expansion continuity, palladium supply stability, and EU MDR notified body capacity, with deviation risk concentrated in reimbursement coding decisions and biocompatibility certification delays. Forecasts reflect these conditions without explicit probability weighting. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
Europe Diabetes Care Devices Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
Digital Diabetes Care Market
Diabetes Care
Diabetic Footwear Market