
 Global Smart Diabetes Management Market | 2026-2036
Global Smart Diabetes Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Diabetes Management Market Foresight
Hospital end-user reliance is broadening toward home care and telehealth channels as payors push for remote patient monitoring. Abbott Laboratories leverages vertical integration across sensor manufacturing to control supply continuity. Dexcom, Inc. dominates continuous glucose monitoring through proprietary factory-calibrated algorithms. Medtronic plc anchors insulin pump connectivity via its smartphone-integrated ecosystem.
Smart diabetes management encompasses sensor-integrated devices, data platforms, and automated insulin delivery systems that measure interstitial glucose levels every one to five minutes and transmit readings wirelessly to receivers or cloud databases. The primary purpose centers on reducing glycemic variability and hypoglycemic events through real-time feedback loops. Continuous glucose monitors capture the dominant value pool due to recurring sensor replacement cycles and premium pricing durability. AI-based analytics represents the fastest-expanding technology segment as predictive algorithms advance toward closed-loop automation. Mobile health apps remain structurally fragmented with low switching costs and thin monetization.
FDA premarket review, EMA MDR compliance, and ISO 15197 standards collectively elevate barriers for glucose monitoring accuracy and cybersecurity. These frameworks compel manufacturers to maintain dual regulatory track files and invest in clinical validation beyond minimum performance thresholds. Stakeholders must monitor interoperability mandates from the Centers for Medicare and Medicaid Services and comparable European bodies as reimbursement increasingly ties to data-sharing capabilities.
Market Dynamics
Closed-loop insulin delivery systems are compressing competitive timelines as manufacturers race to integrate continuous glucose monitoring with automated dosing algorithms before reimbursement gates close.
Growth Catalysts
- CMS Remote Patient Monitoring Reimbursement:United States payors now cover connected diabetes devices under expanded RPM billing codes, accelerating provider deployment of cellular-enabled glucose sensors.
- Interoperability Mandates:FDA guidance requiring data portability between insulin pumps and third-party apps is dismantling proprietary walled gardens and opening accessory markets.
- Japan METI Digital Health Acceleration:Subsidies for home-based glucose monitoring systems are driving adoption among elderly diabetic populations in prefectures with physician shortages.
Market Restraints
- Platinum Electrode Supply Concentration:Sensor manufacturing depends on South African and Russian platinum group metal refiners, exposing production schedules to geopolitical supply shocks.
- EMA MDR Clinical Evidence Requirements:Stricter post-market surveillance obligations for Class III diabetes devices are extending recertification timelines and inflating regulatory compliance costs.
- Flash Glucose Monitoring Substitution:Factory-calibrated sensors requiring no fingerstick calibration are displacing traditional continuous glucose monitors in price-sensitive European markets.
Strategic Opportunities
- Brazil ANVISA Fast-Track Pathway:Expedited approval for software-as-medical-device glucose analytics creates first-mover advantage in Latin America's largest diabetes population.
- AI-Enabled Hypoglycemia Prediction:Machine learning models analyzing CGM trend data are converging with automated insulin suspension protocols to reduce nocturnal events.
- Pharmacy Channel Direct Distribution:Bypassing durable medical equipment suppliers through retail pharmacy partnerships is capturing patients seeking same-day sensor replacement.
Industry Challenges
- Biocompatibility Engineering Talent Scarcity:Sensor manufacturers face acute shortages of materials scientists capable of optimizing enzymatic glucose oxidase stability for 14-day wear durations.
- Legacy EHR Integration Complexity:Hospital systems running decade-old electronic health record architectures struggle to ingest real-time CGM data streams without expensive middleware development.
- ISO 15197 Accuracy Validation Bottlenecks:Third-party clinical research organizations face 6-9 month backlogs for glucose meter equivalence studies, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Diabetes Management Market |
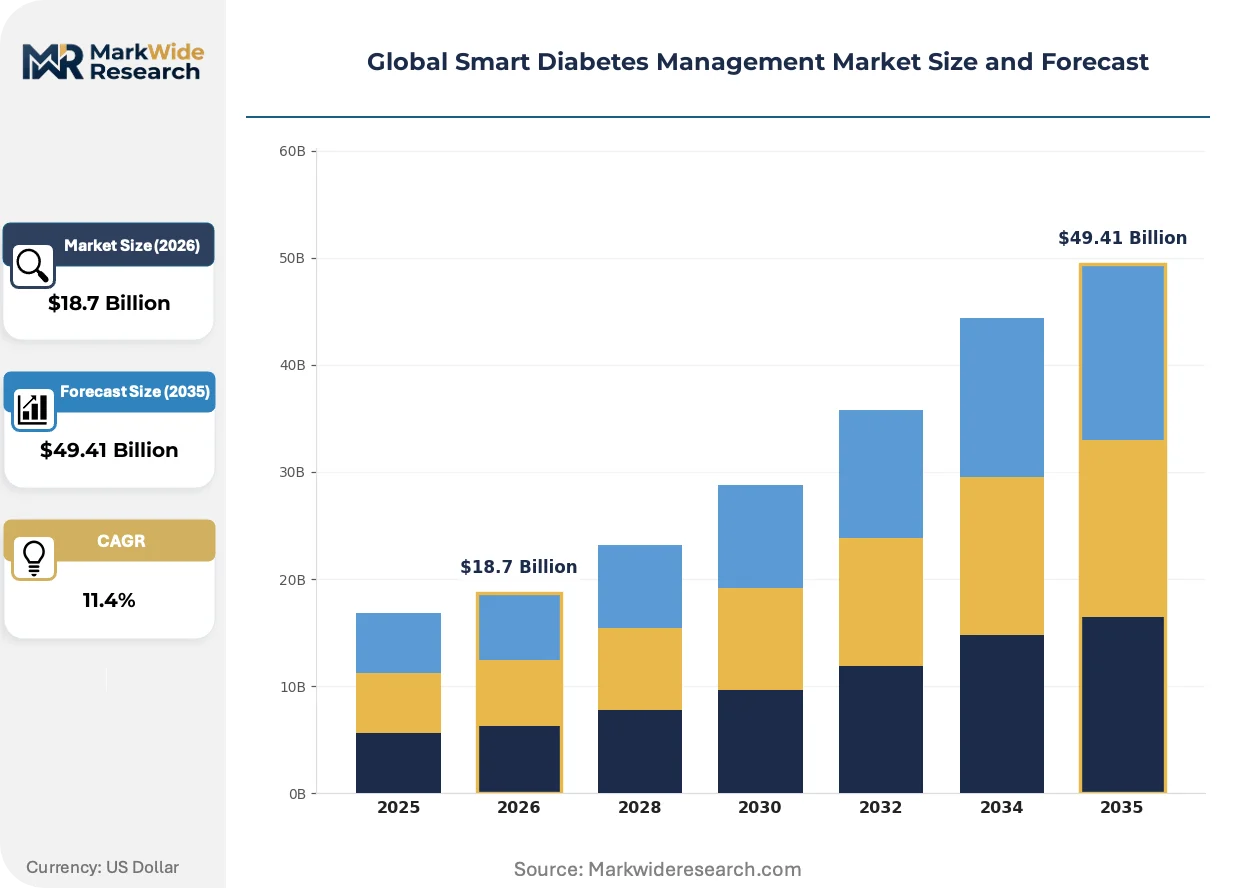
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Glucose Monitors, Insulin Pumps, Blood Glucose Meters, Mobile Health Apps, Smart Insulin Pens Technology: Bluetooth, Zigbee, NFC, Cloud Computing, AI-based Analytics Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes, Postprandial Monitoring End User: Home Care, Specialty Clinics, Diabetes Care Centers, Telehealth Services |
| Companies Covered | Abbott Laboratories, Medtronic plc, Dexcom, Inc., F. Hoffmann-La Roche Ltd, Insulet Corporation, Lifescan, Inc., Bayer AG, Ascensia Diabetes Care Holdings AG, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Diabetes Management Market Shifts & Advancements
Artificial intelligence is displacing threshold-based alerts with predictive glycemic forecasting, while regulatory pressure on data interoperability is forcing open-architecture redesigns across the device ecosystem.
Multisensor fusion technology is converging with non-invasive optical glucose sensing to enable calibration-free monitoring. Academic medical centers in Germany and Switzerland are piloting combined near-infrared spectroscopy and thermal gradient sensors for patients with adhesive allergies. This convergence is compressing the addressable market for invasive fingerstick alternatives.
EMA MDR Article 10 post-market clinical follow-up requirements are mandating real-world evidence collection for all new glucose monitoring submissions. Manufacturers must now embed automated data transmission infrastructure into devices sold in EU member states. Small-to-mid sized developers without existing cloud platforms face acquisition or partnership pressure.
Self-insured employers are unbundling diabetes management from traditional health plan contracts and contracting directly with device-integrated remote monitoring platforms. Fortune 500 companies in the United States are negotiating per-member-per-month fees that bypass pharmacy benefit managers entirely. This channel disintermediation is most visible in Texas and California where large employer concentration enables direct purchasing leverage.
Global Smart Diabetes Management Market Segmentation
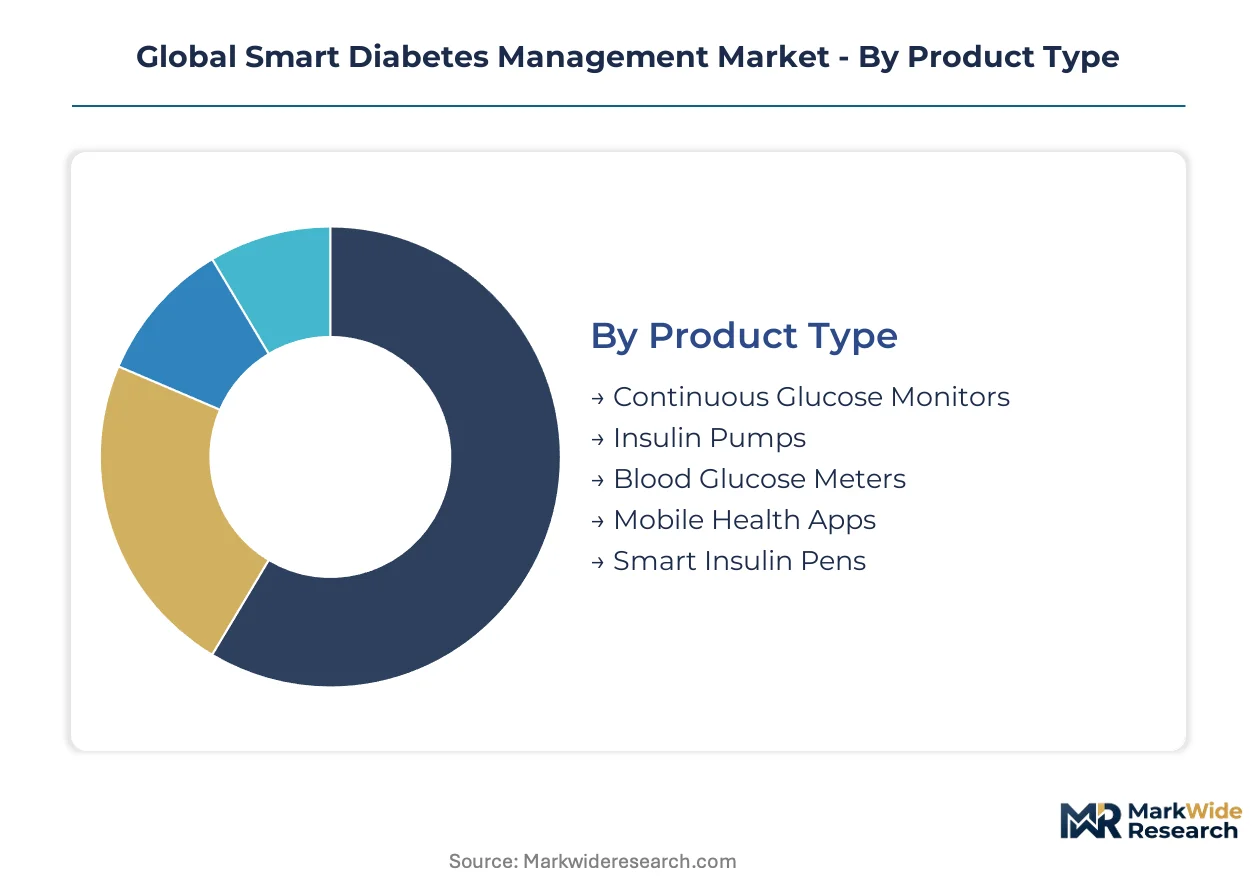
Smart diabetes management markets fragment across multiple technical and usage dimensions. Product architecture, connectivity protocols, disease severity, and care setting each create distinct value pools with divergent margin profiles and competitive dynamics.
Product Type:
Purchase decisions center on therapy intensity and reimbursement tier alignment.
- Continuous Glucose Monitors:Factory-calibrated sensors with 10-14 day wear durations transmit interstitial glucose readings every 1-5 minutes to receivers or smartphones. United States home care settings drive volume as CMS RPM billing codes expand coverage for cellular-enabled devices.
- Insulin Pumps:Motor-driven delivery systems with basal-bolus programming integrate with CGM data for hybrid closed-loop automation. Germany and Japan concentrate demand where statutory health insurance funds reimburse smartphone-integrated pump ecosystems.
- Blood Glucose Meters:Electrochemical strip-based devices for capillary glucose measurement remain prevalent in price-sensitive markets and backup scenarios.
- Mobile Health Apps:Software platforms for glucose logging, meal tracking, and insulin dose calculation face thin monetization and high user churn.
- Smart Insulin Pens:Bluetooth-enabled dose capture devices address injection therapy patients seeking digital adherence tracking without pump adoption.
Continuous Glucose Monitors lead on scale; Smart Insulin Pens lead on momentum.
Technology:
Connectivity infrastructure determines data latency, battery life, and ecosystem lock-in potential.
- Bluetooth:Low-energy 2.4 GHz protocol dominates CGM-to-smartphone transmission with sub-10mW power draw enabling 14-day sensor longevity. FDA interoperability guidance is mandating open Bluetooth APIs that dismantle proprietary receiver requirements.
- AI-based Analytics:Machine learning models trained on CGM trend vectors predict hypoglycemic events 30-60 minutes pre-onset. Cloud Computing infrastructure enables real-time model updates and population-level glycemic pattern analysis.
- Zigbee:Mesh networking protocol finds niche deployment in institutional settings requiring multi-device coordination.
- NFC:Near-field communication supports one-touch data transfer for flash glucose monitoring systems in European pharmacy channels.
- Cloud Computing:Distributed data architecture underpins remote patient monitoring platforms and EMA MDR-mandated post-market surveillance.
Bluetooth dominates installed base; AI-based Analytics climbs the fastest.
Application:
Disease progression stage dictates monitoring frequency and therapeutic intervention intensity.
- Type 1 Diabetes:Absolute insulin deficiency requires intensive glucose monitoring with 6-10 daily checks or continuous sensing. United States pediatric endocrinology centers drive CGM adoption through early intervention protocols.
- Type 2 Diabetes:Insulin resistance and progressive beta-cell failure creates the largest addressable population with heterogeneous monitoring needs. Japan's elderly diabetic population in rural prefectures is expanding flash monitoring for medication adherence.
- Gestational Diabetes:Glucose intolerance during pregnancy demands short-duration intensive monitoring with postpartum discontinuation.
- Prediabetes:Elevated fasting glucose without diagnostic threshold drives wellness-oriented monitoring with limited reimbursement.
- Postprandial Monitoring:Meal-triggered glucose excursion tracking supports dietary optimization in non-insulin-treated patients.
Type 2 Diabetes leads on scale; Type 1 Diabetes leads on revenue intensity.
End User:
Care setting migration from institutional to distributed models is restructuring procurement authority.
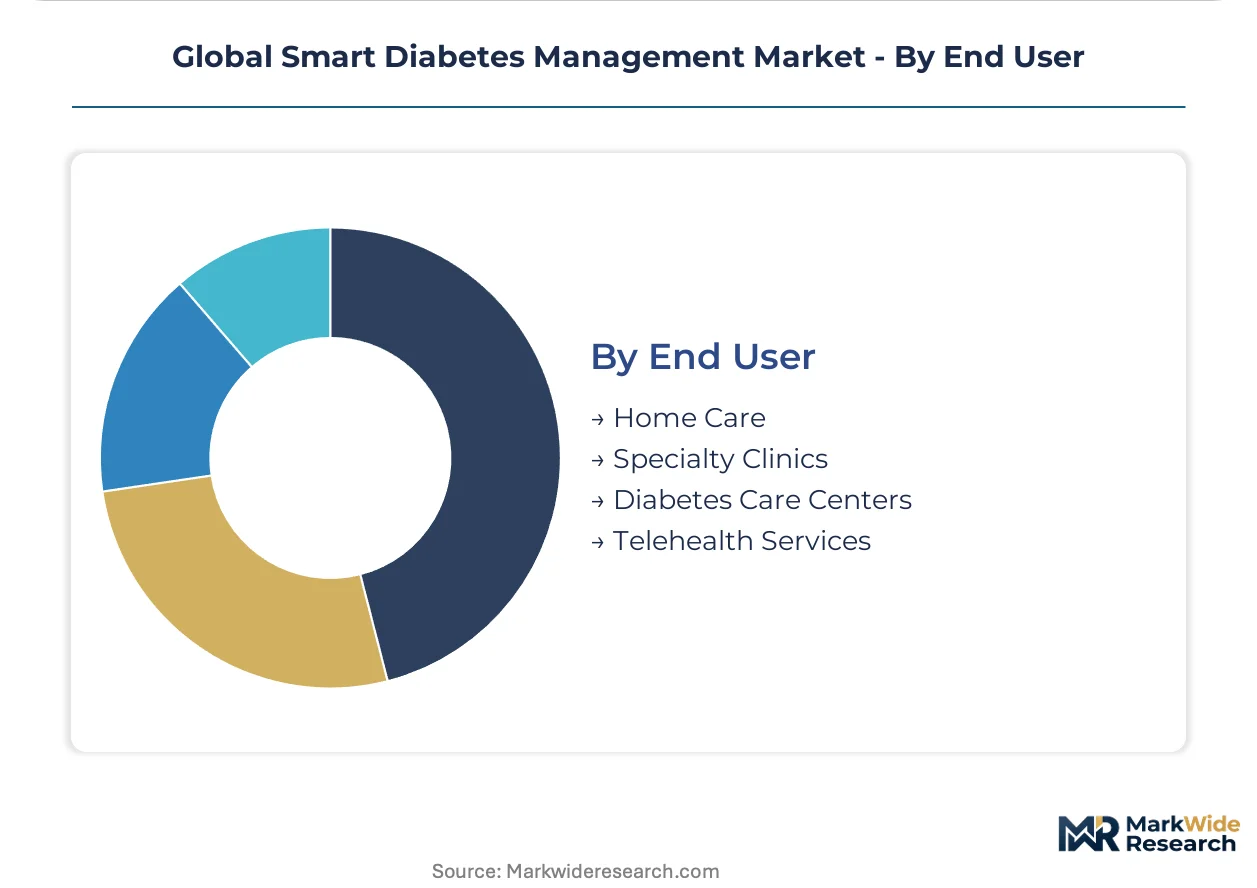
- Home Care:Patient-managed monitoring with remote clinician oversight captures the dominant volume as telehealth reimbursement matures. Germany's statutory insurance system now funds CGM supplies for home-dwelling patients with physician-signed therapy plans.
- Telehealth Services:Virtual-first diabetes platforms integrate device data with video consultations for rural and mobility-limited populations. United States self-insured employers in Texas and California are contracting direct per-member-per-month arrangements.
- Specialty Clinics:Endocrinology-focused practices concentrate complex case management and pump initiation training.
- Diabetes Care Centers:Hospital-affiliated multidisciplinary programs coordinate acute complication response with longitudinal device optimization.
Home Care leads on scale; Telehealth Services leads on expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EMA MDR compliance costs in Europe diverge from FDA premarket pathways in the United States, prompting sensor producers to optimize clinical trial placement and post-market surveillance infrastructure across jurisdictions.
United States
CMS Remote Patient Monitoring reimbursement codes now cover cellular-enabled glucose sensors, accelerating home care deployment. FDA interoperability guidance mandates open Bluetooth APIs, dismantling proprietary receiver requirements. The Minneapolis-San Diego corridor concentrates pump and CGM engineering talent.
Germany
Statutory health insurance funds reimburse smartphone-integrated insulin pump ecosystems, anchoring European demand. EMA MDR Article 10 post-market clinical follow-up requirements mandate real-world evidence collection infrastructure. Baden-Württemberg hosts precision sensor manufacturing clusters serving both diagnostic and therapeutic device makers.
Japan
METI digital health subsidies target elderly diabetic populations in rural prefectures with physician shortages. PMDA streamlined approval pathways for software-as-medical-device glucose analytics compress time-to-market. The Kansai region anchors flash glucose monitoring distribution through pharmacy channel partnerships.
China
NMPA innovation approval channels for AI-enabled glucose prediction algorithms attract multinational clinical trial investment. Domestic sensor manufacturers exploit cost advantages in enzymatic electrode production. The Yangtze River Delta concentrates contract research organizations conducting ISO 15197 accuracy validation studies.
Brazil
ANVISA fast-track pathways for software-as-medical-device glucose analytics create first-mover positioning in Latin America's largest diabetic population. Federal pharmacy reimbursement for continuous monitoring expands beyond hospital procurement. São Paulo anchors regional distribution infrastructure for sensor imports.
Global Smart Diabetes Management Market Competitive Landscape
Vertical integration dominates the current landscape as sensor manufacturers secure captive supply of platinum group metals and enzymatic reagents. The market structures around three tiers: diversified medtech conglomerates with full-stack diabetes portfolios, CGM-focused specialists with algorithmic moats, and emerging software-as-medical-device platforms. Strategic archetypes include backward-integrated supply chain controllers, algorithm-centric predictive analytics developers, and pharmacy-channel direct distributors. M&A activity and open-architecture partnerships represent the dominant competitive vectors as interoperability mandates dismantle proprietary ecosystems.
Among diversified medtech conglomerates, Abbott Laboratories and Medtronic plc occupy positions spanning sensor manufacturing through automated insulin delivery, while Dexcom, Inc. exemplifies the CGM-specialist archetype with factory-calibrated algorithmic differentiation. Insulet Corporation and F. Hoffmann-La Roche Ltd represent alternative positioning vectors in tubeless pump delivery and diagnostic-integrated care platforms respectively.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic plc |
| Dexcom, Inc. |
| F. Hoffmann-La Roche Ltd |
| Insulet Corporation |
| Lifescan, Inc. |
| Bayer AG |
| Ascensia Diabetes Care Holdings AG |
| Sanofi |
| Others |
Supply & Pricing Matrix
Platinum group metal electrode costs cascade from South African and Russian refiners through sensor bill-of-materials into three-tier pricing structures across premium, standard, and economy levels. Manufacturers with captive enzymatic reagent production command 15-20 point margin advantages over contract-dependent competitors.
Pricing Analysis
Distributor margin compression in the durable medical equipment channel is forcing manufacturers toward direct-to-pharmacy arrangements that bypass 25-35 point markups. Pricing stratifies across premium, standard, and economy tiers based on factory-calibration certification and real-time cloud connectivity bundling. Cost compression in the standard tier is intensifying because flash glucose monitoring substitutes are displacing traditional continuous glucose monitors in European markets. Price sensitivity concentrates among Type 2 diabetes patients in statutory insurance systems, while Type 1 intensive insulin users demonstrate inelastic demand for closed-loop automation.
Supply Chain Analysis
Single-source vulnerability sits with South African platinum group metal refiners that feed enzymatic electrode production for 14-day wear sensors. Manufacturing capacity draws from the United States, Germany, and China, with sensor assembly concentrated in Baden-Württemberg and the Yangtze River Delta. Raw material dependencies rest on glucose oxidase enzymes, medical-grade adhesives, and platinum-iridium electrode substrates. Tariff exposure on Chinese-sourced electronics components threatens cost structures for Bluetooth-enabled transmitters. Distribution runs through pharmacy channel partnerships in Japan and Brazil, bypassing traditional durable medical equipment suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in algorithmic differentiation and cloud infrastructure ownership as sensor hardware commoditizes. Premium-tier shift toward closed-loop automation commands reimbursement premiums that offset platinum input volatility.
For Market Incumbents: Acquire cloud-based analytics platforms to capture recurring software revenue streams and lock in ecosystem switching costs. Backward integration into enzymatic reagent production defends against platinum price volatility and biocompatibility engineering talent scarcity. Secure FDA premarket notification pathways for interoperable device submissions before EMA MDR compliance costs escalate.
For New Entrants and Emerging Players: Launch via direct-to-pharmacy distribution in Brazil and Japan where ANVISA fast-track and PMDA streamlined pathways compress time-to-market. Target software-as-medical-device glucose analytics in Latin America where hospital system EHR integration complexity creates white-space for middleware solutions. Pursue per-member-per-month contracting with self-insured employers in Texas and California to bypass pharmacy benefit manager gatekeeping.
For Investors and Strategic Acquirers: Consolidation pressure builds where small-to-mid sized developers lack embedded cloud platforms for EMA MDR Article 10 post-market surveillance compliance. Long-term viability favors algorithm-centric predictive analytics developers with FDA-cleared machine learning models over hardware-dependent sensor manufacturers. Monitor CMS Remote Patient Monitoring reimbursement code expansions as inflection indicators for home care setting volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Interoperability Compliance | Open Bluetooth API mandates from FDA dismantle proprietary receiver requirements and enable accessory market entry. |
| EMA MDR Cloud Infrastructure | Embedded data transmission architecture satisfies Article 10 post-market clinical follow-up obligations for EU market access. |
| Pharmacy Channel Partnership | Direct retail distribution in Japan and Brazil captures same-day sensor replacement demand outside DME supplier networks. |
| AI Hypoglycemia Prediction | Machine learning models analyzing CGM trend vectors converge with automated insulin suspension protocols for nocturnal event reduction. |
| Platinum Supply Security | Captive refining relationships or alternative electrode chemistries hedge geopolitical exposure to South African and Russian supply concentration. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and Brazil, with primary inputs from each market informing demand calibration and regulatory pathway assessment. The research combines structured interviews with endocrinologists, hospital purchasing committees, biomedical engineers, GPO contracts managers, and pharmacy procurement leads with secondary validation against FDA 510(k) filings, EMA MDR submissions, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up sensor unit economics and top-down addressable population estimates undergo iterative triangulation to resolve variance.
Granularity-level modeling disaggregates volume and value across product type, connectivity protocol, disease severity application, and care setting end user throughout the forecast period. CAGRs derive from segment-specific adoption curves calibrated to reimbursement policy shifts and regulatory approval timelines. Industry-specific forecast inputs include CMS Remote Patient Monitoring billing code expansion trajectories and EMA MDR recertification backlog projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under platinum supply disruption scenarios and interoperability mandate implementation delays. Outcomes reflect documented assumptions regarding reimbursement parity between continuous and flash glucose monitoring systems. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Global Non-Invasive Glucose Meter Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
Global Diabetic Retinopathy Market