
 Europe Commercial Telematics Market | 2026-2036
Europe Commercial Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Telematics Market Intelligence
Advanced fleet-grade connectivity is bifurcating the competitive landscape between premium integrated platforms and modular point solutions. Webfleet Solutions B.V. leverages its TomTom heritage to dominate embedded navigation and real-time traffic intelligence across European road networks. MiX Telematics sustains technology leadership in heavy-duty truck telematics through specialized driver behavior analytics and compliance dashboards. AddSecure anchors its position in secure IoT communications, extending encrypted data transmission capabilities that differentiate its offerings in regulated transport sectors.
Europe commercial telematics encompasses GPS, GPRS, and satellite-enabled vehicle monitoring systems that collect engine diagnostics, location telemetry, and driver performance data through onboard hardware and cloud-based software platforms. These systems primarily enable fleet operators to optimize asset utilization, enforce regulatory compliance, and reduce operational expenditures across distributed vehicle networks. Fleet management services command the largest service type category due to recurring subscription revenue models and deep integration with enterprise resource planning systems. Insurance telematics represents the fastest-expanding segment as European underwriters increasingly tie premium pricing to verified driving behavior data. GPS technology occupies the dominant technology position, though satellite-based solutions are gaining traction in remote Nordic and Alpine corridors where cellular coverage fragments.
The EU Green Deal and F-Gas Regulation shape product standards by mandating emissions transparency and refrigerant leak monitoring in transport refrigeration units, directly expanding sensor integration requirements. ECHA's REACH compliance frameworks and GDPR data governance rules constrain how telematics providers collect, process, and retain driver biometric and location information across member states. Stakeholders must monitor evolving EU AI Act provisions governing automated decision-making in driver scoring algorithms, as these classifications will determine market access requirements and liability structures for predictive analytics platforms.
Market Dynamics
The EU Green Deal's emissions transparency mandates are compressing deployment timelines for connected vehicle platforms across European freight corridors. Fleet operators must integrate real-time monitoring systems to avoid penalties under tightening CO2 performance standards for heavy-duty vehicles.
Growth Catalysts
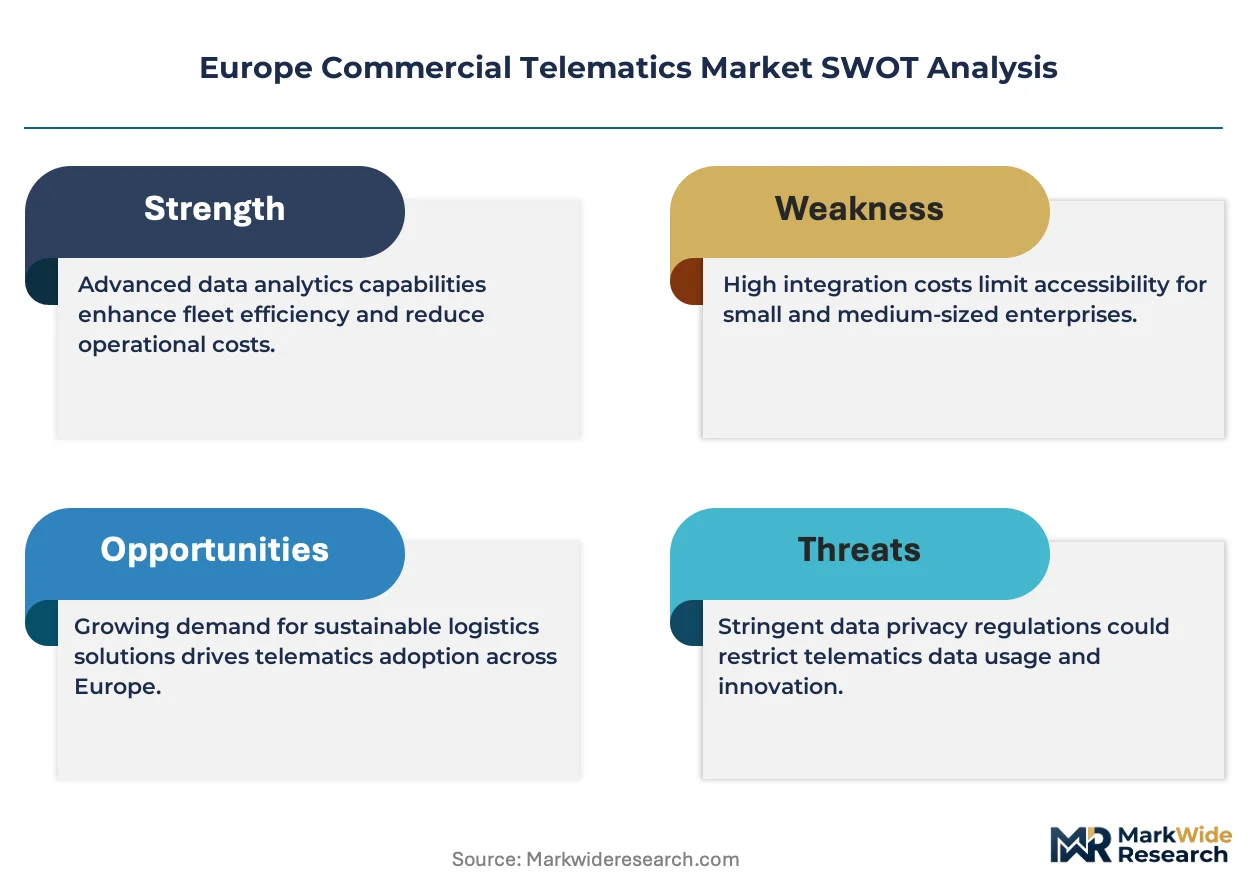
- F-Gas Regulation:Transport refrigeration units now require continuous refrigerant leak monitoring, forcing cold-chain operators to install sensor-integrated telematics hardware across their fleets.
- Logistics sector consolidation:Large fleet operators in Germany and the Netherlands are mandating unified telematics platforms to coordinate multi-modal freight movements across dense corridor networks.
- GPRS-to-LTE migration:Cellular network sunsetting is compelling hardware refreshes, accelerating replacement cycles for aging onboard diagnostic units.
Market Restraints
- Semiconductor supply concentration:Specialized vehicle-grade chipsets depend on concentrated Asian foundry capacity, creating input volatility for European hardware manufacturers.
- GDPR compliance friction:Cross-border driver data transfers face divergent member-state interpretations, complicating pan-European platform architectures.
- Satellite connectivity cost premium:Remote Nordic and Alpine operations require expensive dual-mode cellular-satellite hardware that prices out smaller fleet operators.
Strategic Opportunities
- Poland and Romania freight growth:Underpenetrated Eastern European logistics markets present first-mover advantages for modular, lower-cost telematics solutions.
- EU AI Act compliance services:Automated driver scoring algorithms will require algorithmic audit capabilities, creating new service revenue streams for analytics providers.
- Insurance telematics convergence:Usage-based premium pricing mandates from European underwriters are opening fleet-data monetization partnerships.
Industry Challenges
- Embedded systems engineering scarcity:Shortages of firmware developers with automotive cybersecurity expertise are delaying product certification timelines.
- Legacy fleet integration complexity:Retrofitting CAN bus protocols into pre-2010 commercial vehicles requires costly custom engineering that erodes hardware margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Telematics Market |
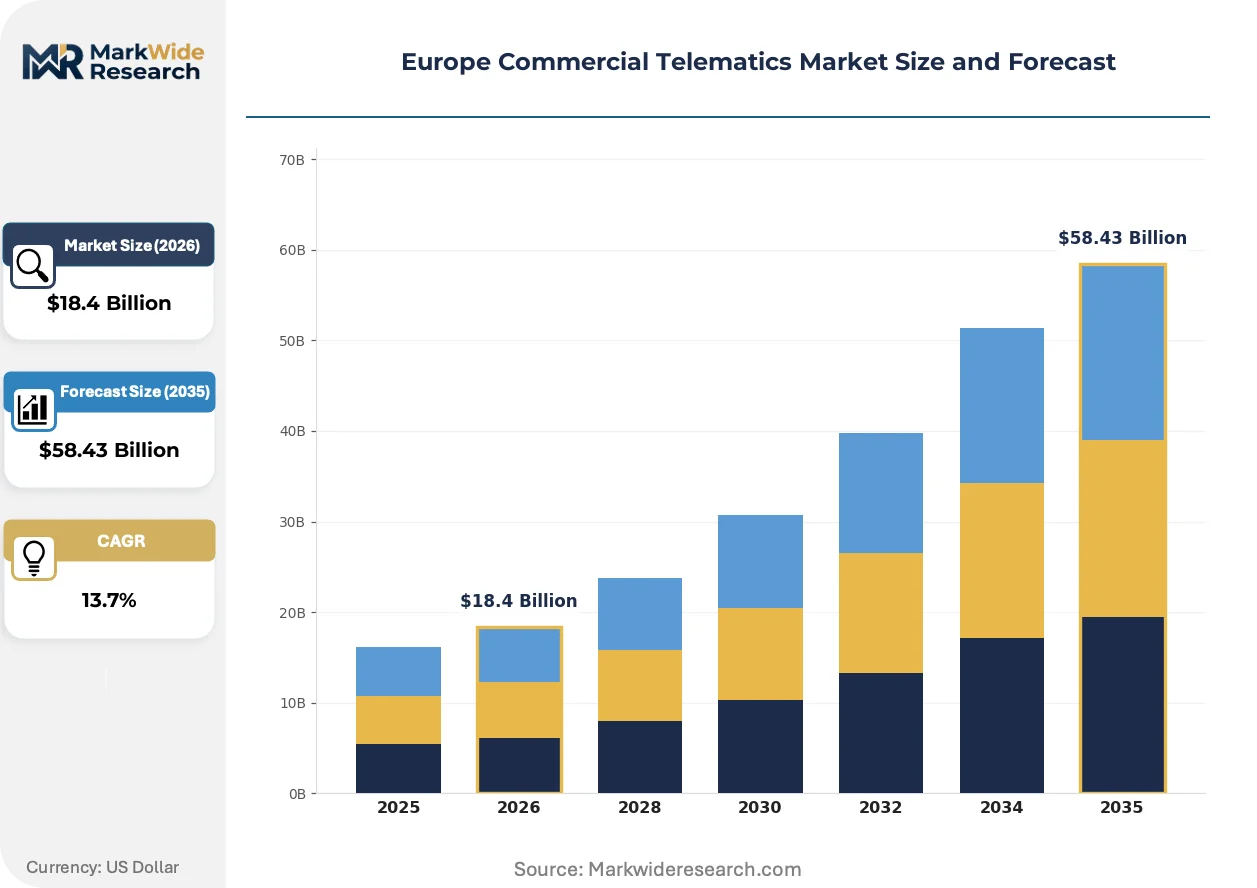
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $58.43 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, GPRS, RFID, Satellite Vehicle Type: Trucks, Vans, Buses, Trailers Service Type: Fleet Management, Insurance Telematics, Remote Diagnostics, Vehicle Tracking End User: Logistics, Construction, Public Sector, Delivery Services |
| Companies Covered | Webfleet Solutions B.V., Verizon Connect, Masternaut Limited, ABAX UK Ltd, Targa Telematics S.p.A, AddSecure, Gurtam Inc., MiX Telematics, Transpoco, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Telematics Market Strategic Shifts & Innovations
Edge computing architectures are redistributing data processing loads across European commercial vehicle networks. This shift is compressing latency for critical safety applications while reducing cellular data transmission costs.
AI-enabled predictive maintenance algorithms are supplanting scheduled service intervals in heavy-duty truck fleets. German logistics operators are deploying these systems across their tractor-trailer networks to anticipate component failures before roadside breakdowns occur. The technology is compressing total cost of ownership advantages for early adopters while pressuring traditional aftermarket service providers.
The EU AI Act's risk classification framework is reshaping liability structures for automated driver monitoring systems. Fleet management platforms using biometric scoring now face mandatory conformity assessments before market deployment. Insurance telematics providers are most affected, restructuring their algorithmic transparency documentation to satisfy notified body requirements.
Subscription-based hardware procurement is displacing capital expenditure models among mid-sized European fleet operators. Leasing companies are bundling telematics devices with vehicle finance packages, shifting technology refresh cycles onto lessors. This pattern is most visible in the Benelux region, where fleet-as-a-service providers have captured significant share of new commercial vehicle registrations.
Europe Commercial Telematics Market Segmentation
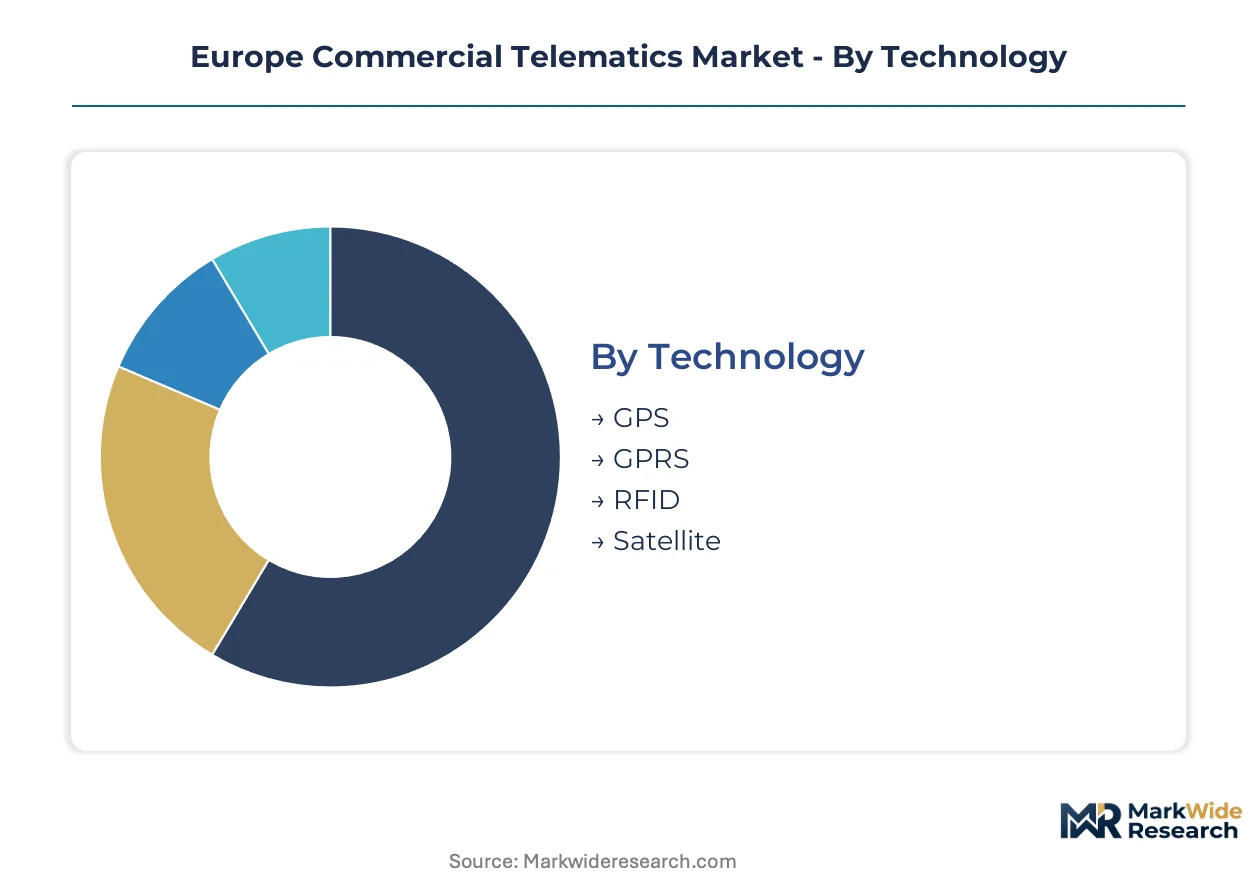
Telematics providers structure product portfolios around distinct technology stacks and vehicle categories to match deployment economics with customer operational profiles. Channel strategies diverge sharply between integrated fleet platforms sold direct to enterprise operators and modular hardware distributed through vehicle OEMs and leasing networks.
Technology:
GPS and cellular modules flow primarily through direct fleet management channels, while satellite and RFID components concentrate in specialized distributor networks serving remote operations and asset-heavy sectors.
- GPS:Constellation-based positioning systems deliver meter-level accuracy for route optimization and geofencing across European road networks. German logistics corridors and Dutch freight hubs generate concentrated demand as operators pursue fuel efficiency gains and delivery-time compliance.
- GPRS:Cellular data transmission enables real-time telemetry streaming at lower hardware cost than satellite alternatives. Network sunsetting timelines are compressing replacement cycles as operators migrate aging 2G/3G units to LTE-capable hardware before coverage discontinuation.
- RFID:Short-range identification tags automate yard management and trailer tracking without continuous power draw. Cold-chain operators in France and Italy deploy passive RFID for refrigerated asset monitoring where battery maintenance proves impractical.
- Satellite:Orbital connectivity ensures telemetry continuity across Nordic tundra, Alpine passes, and maritime freight routes where terrestrial networks fragment. Dual-mode cellular-satellite hardware commands premium pricing that limits adoption to heavy-haul operators with remote route obligations.
GPS dominates installed base. Satellite is where expansion concentrates among operators serving remote corridors.
Vehicle Type:
Hardware form factors and sensor configurations vary substantially by vehicle class, with trucks and vans driving volume through standardized OBD-II and J1939 integrations while buses and trailers require specialized mounting and power solutions.
- Trucks:Heavy-duty platforms integrate engine control module access, driver behavior cameras, and refrigerated unit monitoring through standardized CAN bus protocols. German and Polish long-haul fleets represent the primary demand concentration as emissions regulations tighten and cross-border freight volumes climb.
- Vans:Light commercial vehicles deploy compact plug-and-play devices optimized for rapid installation across dispersed last-mile delivery fleets. Benelux urban logistics operators and UK courier services are saturating this segment with subscription-based procurement models.
- Buses:Passenger transport mandates require integrated passenger counting, schedule adherence, and accessibility compliance monitoring. Municipal operators in Spain and Italy are retrofitting aging fleets with connected platforms to satisfy public service contract requirements.
- Trailers:Unpowered assets demand battery-optimized tracking with extended dormancy periods and cargo sensor integration. Container chassis and refrigerated trailers in Rotterdam-Antwerp-Hamburg corridor networks are driving adoption as operators seek to reduce unlocated equipment losses.
Trucks anchor revenue concentration. Vans are climbing the fastest as e-commerce delivery networks expand.
Service Type:
Revenue models stratify between recurring subscription platforms and transactional data services, with fleet management commanding enterprise budgets while insurance telematics penetrates through underwriter partnerships and policyholder incentives.
- Fleet Management:Integrated platforms combine real-time tracking, route optimization, fuel monitoring, and maintenance scheduling through cloud-based dashboards. Large German and Dutch logistics operators are mandating unified systems across multi-modal networks to coordinate tractor-trailer movements and warehouse synchronization.
- Insurance Telematics:Usage-based pricing models tie premium calculations to verified driving behavior data collected through onboard devices. European underwriters in the UK, Italy, and France are accelerating deployment as risk differentiation becomes competitive necessity in commercial auto lines.
- Remote Diagnostics:Predictive maintenance algorithms analyze engine telemetry to anticipate component failures before roadside breakdowns occur. Heavy-duty truck operators are adopting these services to compress total cost of ownership and protect delivery schedule reliability.
- Vehicle Tracking:Location-centric services provide asset recovery and unauthorized movement alerts without full operational management suites. Small fleet operators and construction contractors in Eastern Europe prioritize this lower-cost entry point for basic visibility.
Fleet management commands revenue concentration. Insurance telematics is gaining share fastest as regulatory pressure on underwriting practices intensifies.
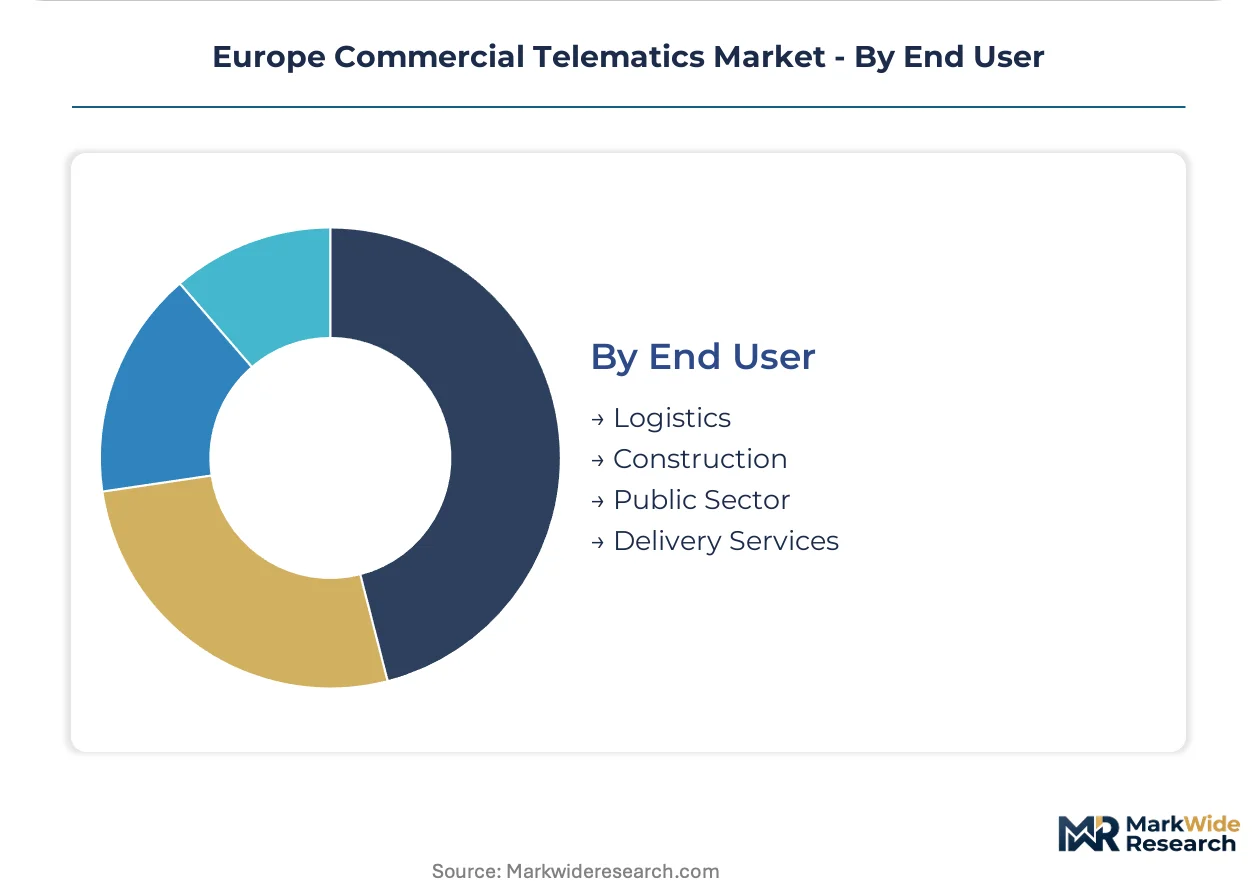
End User:
Procurement authority and technical requirements diverge sharply between centralized logistics enterprises with dedicated fleet managers and fragmented construction or public sector operators with dispersed decision-making.
- Logistics:Third-party transport operators and dedicated fleet owners pursue end-to-end supply chain visibility through ERP-integrated telematics platforms. German freight forwarders and Dutch distribution specialists are consolidating vendor relationships to achieve multi-modal coordination across road, rail, and short-sea networks.
- Construction:Heavy equipment and commercial vehicle fleets require ruggedized hardware with extended temperature tolerance and dust ingress protection. French and Spanish infrastructure contractors are deploying connected platforms to monitor equipment utilization and prevent unauthorized after-hours operation.
- Public Sector:Municipal and national government fleets face procurement transparency mandates and service-level agreements demanding documented operational performance. Waste collection, snow removal, and emergency vehicle operators in Scandinavian municipalities are standardizing on open-data-compatible systems.
- Delivery Services:Parcel and food delivery networks prioritize real-time customer communication interfaces and proof-of-delivery verification. Rapid courier growth in Polish and Romanian urban centers is driving demand for compact, rapidly deployable tracking hardware.
Logistics dominates installed base. Delivery services are where expansion concentrates as e-commerce penetration deepens across Eastern Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's commercial telematics trade flows reflect a continental production hub serving intra-regional logistics networks. Germany exports embedded fleet hardware to Benelux and Scandinavian markets while importing satellite connectivity modules from specialized UK vendors. Cross-border data service arrangements dominate the value chain.
Germany
Dense freight corridors along the Rhine-Alpine axis generate concentrated demand for heavy-duty truck telematics. The KBA enforces stringent commercial vehicle type-approval standards that mandate onboard diagnostic integration. The Ruhr industrial basin and Hamburg port cluster host major logistics operators deploying unified fleet management platforms.
United Kingdom
Insurance telematics penetration exceeds continental averages as underwriters tie commercial premiums to verified driving behavior. The Financial Conduct Authority supervises usage-based insurance data governance practices. London's last-mile delivery networks and Midlands distribution hubs drive compact van telematics adoption.
Netherlands
Rotterdam-Antwerp port logistics create Europe's densest trailer tracking deployment corridor. National regulators align with EU Green Deal emissions transparency mandates for maritime-road intermodal chains. Eindhoven's technology ecosystem spawns specialized IoT hardware developers serving cold-chain operators.
France
ANSM and CNIL jointly oversee health-transport and data privacy compliance for pharmaceutical cold-chain telematics. Transport refrigeration units face F-Gas Regulation leak monitoring requirements. Lyon and Marseille freight clusters prioritize sensor-integrated platforms for temperature-sensitive cargo.
Poland
Rapid logistics sector expansion outpaces legacy fleet connectivity penetration, creating modular solution opportunities. National transport authorities implement EU CO2 performance standards for heavy-duty vehicles with accelerated timelines. Warsaw and Silesian industrial zones attract first-mover telematics providers targeting underpenetrated operator segments.
Europe Commercial Telematics Market Key Industry Players
Concentration sits with integrated platform providers that bundle hardware, connectivity, and analytics through subscription models. The vendor landscape stratifies across three tiers: multinational fleet management suites, specialized compliance-focused modules, and regional hardware distributors. Strategic moves center on API ecosystem expansion and insurance partnership networks.
Within the integrated platform tier, Webfleet Solutions B.V. and Verizon Connect occupy positions exemplifying navigation-heritage and telecom-backed delivery models respectively. MiX Telematics represents specialized heavy-duty expertise, while AddSecure anchors secure IoT communications positioning. These entities illustrate how European market access depends on GDPR-compliant data architectures and EU Green Deal certification pathways.
| Leading Market Players |
|---|
| Webfleet Solutions B.V. |
| Verizon Connect |
| Masternaut Limited |
| ABAX UK Ltd |
| Targa Telematics S.p.A |
| AddSecure |
| Gurtam Inc. |
| MiX Telematics |
| Transpoco |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day lead times for vehicle-grade cellular modems concentrate pricing power among German and Dutch hardware integrators serving enterprise fleet operators, while subscription-based procurement models shift cost absorption onto leasing networks across the Benelux corridor.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Europe's commercial telematics market. Premium tiers command positioning through EU Green Deal certification and GDPR-compliant data architectures, while standard offerings compete on LTE connectivity bundling and economy tiers target price-sensitive Eastern European operators with stripped-down GPS tracking. Cost compression in the economy tier intensifies because GPRS-to-LTE migration cycles force accelerated hardware refresh spending. Small fleet operators in Poland and Romania exhibit highest price sensitivity, whereas German logistics enterprises prioritize compliance-grade platforms over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor semiconductor fabrication for specialized vehicle-grade chipsets that European telematics hardware manufacturers draw from for onboard diagnostic units. German and Dutch assembly operations rest on concentrated Asian foundry capacity for cellular modems, GPS receivers, and edge-computing processors. Single-source vulnerability in 4G/5G modem supply creates exposure for hardware vendors serving EU emissions compliance deadlines. Distribution runs through direct enterprise sales for integrated platforms and vehicle OEM leasing networks for modular plug-and-play devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework for automated driver scoring algorithms introduces a regulatory inflection that will compress certification timelines and reshape competitive viability for predictive analytics platforms across European freight networks.
For Market Incumbents: Consolidate API ecosystem control and insurance partnership networks to defend against modular point-solution entrants attacking the mid-market. Deepen vertical integration into secure IoT communications capabilities to satisfy GDPR cross-border data transfer requirements as member-state interpretations diverge. Prioritize firmware development capacity in automotive cybersecurity to address embedded systems engineering scarcity delaying product certifications. For New Entrants and Emerging Players: Differentiate on EU AI Act algorithmic audit services as a standalone revenue stream separate from core telematics hardware. Target underpenetrated cold-chain operators in France and Italy facing F-Gas Regulation refrigerant leak monitoring mandates with sensor-integrated modular platforms. Pursue white-label partnerships with Eastern European leasing networks to bypass direct enterprise sales friction in Poland and Romania. For Investors and Strategic Acquirers: Carve-out targets emerge from telecom-backed fleet management divisions seeking to monetize non-core telematics assets amid parent-level restructuring. Long-term viability hinges on sustained regulatory pressure from EU emissions transparency mandates and insurance telematics convergence across the analysis window. Monitor notified body backlog lengths for EU AI Act conformity assessments as an inflection indicator for platform deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified fleet management dashboards compress vendor consolidation timelines for German logistics operators. |
| Strategic Partnership | Insurance telematics data-sharing agreements with UK underwriters unlock usage-based premium monetization. |
| Acquisition of Specialist Firm | Edge-computing hardware targets accelerate latency reduction for AI-enabled predictive maintenance algorithms. |
| Geographic Expansion | Modular low-cost platform deployment captures first-mover position in Polish and Romanian freight growth corridors. |
| Product Launch | GDPR-compliant biometric scoring platforms satisfy EU AI Act risk classification requirements for driver monitoring. |
Research Approach
Initial hypotheses were tested against primary input from fleet operations directors, telematics platform engineers, insurance underwriter risk officers, and EU regulatory compliance consultants, and refined through secondary validation against KBA type-approval filings, ECHA REACH substance registrations, EU Green Deal implementation guidance, and cellular network operator coverage discontinuation schedules. Bottom-up hardware shipment estimates triangulated against top-down fleet operator subscription spend analysis.
Variance decomposition across technology, vehicle type, service tier, and end-user industry dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by EU regulatory enforcement timelines and cellular network migration schedules. Modeled inputs incorporated satellite connectivity cost premiums for Nordic-Alpine corridor penetration and insurance telematics partnership formation rates across UK, Italian, and French underwriters.
Material uncertainties — semiconductor supply volatility, divergent GDPR member-state enforcement patterns, and EU AI Act notified body capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and fleet operator replacement cycle synchronization. Recalibration cycles align with material shifts in EU emissions performance standard enforcement and cellular network sunsetting announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Automotive Rear Seat Infotainment Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Global Taxi-Sharing Software Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
India Fleet Management Software Market
Telematics and Infotainment
Telematics-Linked Fleet Battery Health Management Systems Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market