
 LAMEA Last Mile Delivery Market | 2026-2036
LAMEA Last Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Last Mile Delivery Market Insights
Asset-light fleet leasing and pay-per-use vehicle financing is reconfiguring competitive entry barriers across the LAMEA region. Aramex leverages its established Middle Eastern hub network to anchor cross-border last-mile corridors into Africa. FedEx Corporation sustains premium express positioning through controlled cold-chain capabilities for pharmaceutical and perishable segments. BEST Inc. specializes in high-frequency urban parcel routing through dense Chinese-origin trade lanes that terminate in LAMEA ports.
Last mile delivery denotes the final transportation leg from distribution hub to end recipient, typically spanning distances under 50 kilometers and requiring real-time tracking protocols with sub-hour delivery windows for express classifications. Its primary commercial purpose centers on converting digital purchase intent into physical fulfillment completion at the lowest cost per successful drop. Express delivery commands disproportionate margin pools across Latin American corridors where consumers demonstrate willingness to pay premium tariffs for speed certainty. Scheduled delivery is gaining structural traction among appliance and furniture retailers seeking to reduce failed-attempt costs through precise time-window commitments. Autonomous delivery remains nascent in LAMEA markets but attracts concentrated pilot investment in Dubai and Riyadh where regulatory sandboxes permit drone corridor testing.
Brazil's national environmental regulator enforces escalating emissions thresholds for commercial van fleets operating in São Paulo and Rio de Janeiro metropolitan zones, compelling operators toward electric vehicle transition timelines. Mexico's federal consumer protection agency mandates transparent delivery tracking disclosure and refund protocols for e-commerce transactions, reshaping platform liability structures. South Africa's competition authority scrutinizes logistics consolidation patterns to preserve independent courier market access. Stakeholders must monitor how divergent national enforcement intensities across LAMEA jurisdictions fragment compliance cost structures and influence regional network architecture decisions.
Market Dynamics
Electric vehicle mandates across São Paulo and Mexico City are forcing fleet operators to accelerate capital deployment toward zero-emission van procurement, compressing traditional diesel-powered logistics economics.
Growth Catalysts
- E-commerce Fulfillment Density:Digital retail platforms are expanding same-day delivery coverage into secondary Brazilian and Mexican metropolitan zones, pulling parcel volume concentration into dense urban corridors.
- ANVISA Cold-Chain Standards:Brazil's national pharmaceutical regulator mandates temperature-verified last-mile protocols for biologics and vaccines, creating specialized logistics demand with premium tariff structures.
- Drone Corridor Sandboxes:Dubai and Riyadh regulatory authorities permit beyond-visual-line-of-sight testing for autonomous aerial delivery, attracting concentrated pilot investment from cross-border operators.
Market Restraints
- Electric Vehicle Capex Burden:Battery-powered commercial van procurement costs remain elevated versus internal combustion equivalents, straining operator balance sheets during mandated transition timelines.
- Charging Infrastructure Gaps:Grid-connected depot capacity concentrates in São Paulo and Mexico City metropolitan cores, leaving secondary corridors dependent on fossil fuel fleets.
- Cross-Border Customs Friction:Divergent documentation requirements between Mercosur and Middle Eastern trade blocs extend transit times for international parcel flows.
Strategic Opportunities
- Secondary City Penetration:Underdeveloped logistics infrastructure in Colombian and Chilean provincial capitals presents first-mover positioning for asset-light platform models.
- Reverse Logistics Integration:E-commerce return volume growth enables bundled pickup-delivery routing economics that pure-play forward distributors cannot replicate.
- Renewable Energy Subsidies:Brazilian federal tax incentives for solar-powered depot operations reduce facility energy costs and support emissions compliance documentation.
Industry Challenges
- Route Optimization Talent Scarcity:Shortage of data scientists capable of deploying real-time dynamic routing algorithms limits operational efficiency gains from telematics investments.
- Legacy Warehouse Management Integration:Proprietary order management systems at established retailers resist API connectivity with third-party delivery platforms, fragmenting visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Last Mile Delivery Market |
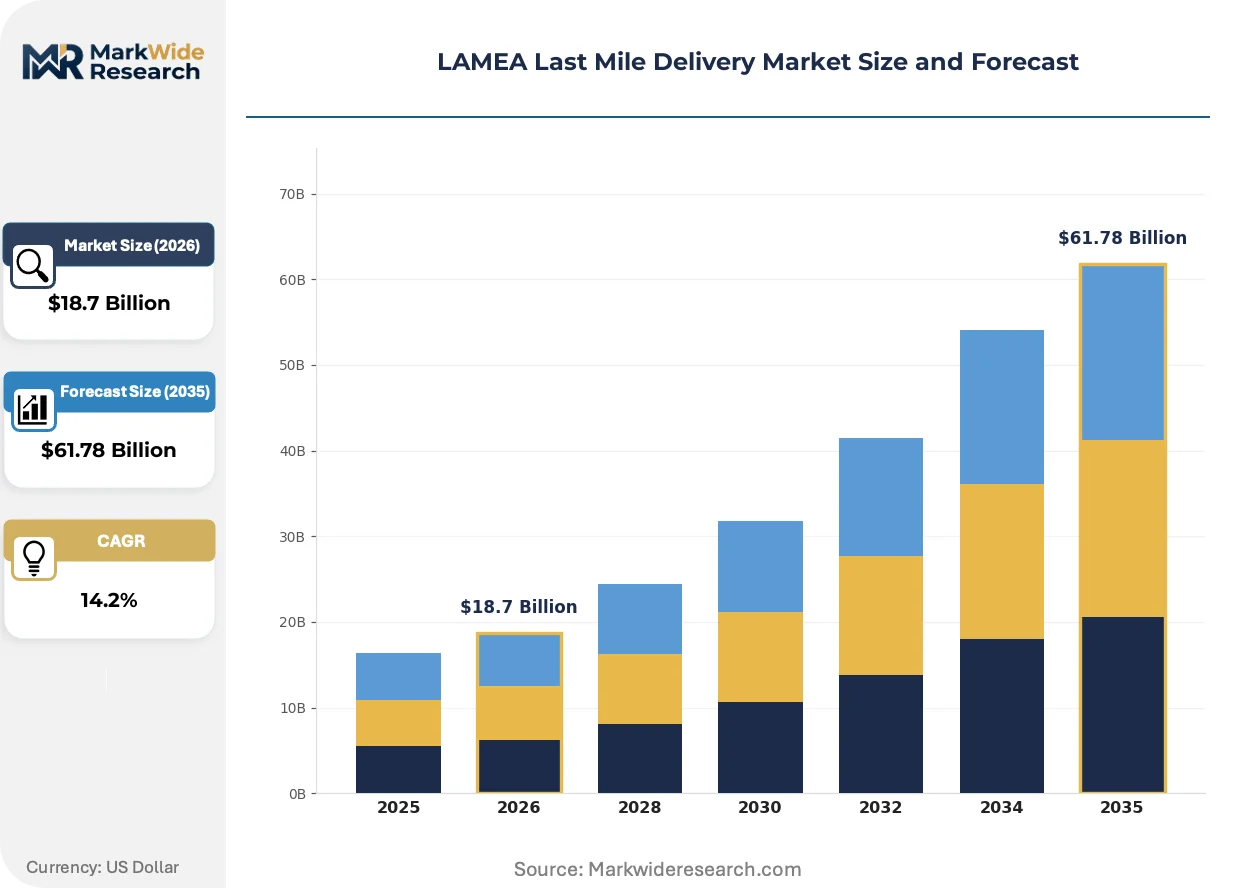
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Express Delivery, Same-Day Delivery, Scheduled Delivery End User: Retailers, E-commerce Platforms, Third-Party Logistics, Restaurants Technology: GPS Tracking, Route Optimization, Mobile Applications, Autonomous Delivery Fleet Type: Bicycles, Motorbikes, Vans, Drones |
| Companies Covered | Amazon.com, FedEx Corporation, United Parcel Service, DHL International, Aramex, SF Express, XPO Logistics, Kerry Logistics Network Limited, BEST Inc., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Last Mile Delivery Market Trends and Innovations
Real-time visibility infrastructure is compressing delivery window commitments across Latin American corridors, while regulatory pressure and buyer behavior shifts simultaneously reshape fleet composition and service tiering.
Dynamic route optimization software is digitizing dispatch decisions that previously relied on static territory assignments. Mid-market e-commerce platforms in São Paulo and Mexico City are deploying these systems within eighteen-month implementation cycles. The technology is digitizing cost structures by reducing miles-per-stop and enabling sub-hour delivery guarantees that command premium pricing.
Brazil's escalating commercial van emissions thresholds, enforced by the national environmental regulator in metropolitan São Paulo and Rio de Janeiro zones, mandate progressive fleet electrification. Operators face compressed transition timelines with penalties for non-compliance. Pharmaceutical and perishable segments, where cold-chain reliability justifies higher vehicle investment, are responding fastest with dedicated electric fleet procurement.
Scheduled delivery windows are displacing ambiguous arrival estimates for appliance and furniture categories. Major Brazilian home goods retailers now require precise two-hour commitments to reduce failed-attempt costs and customer service burden. This behavioral shift is most visible in São Paulo's dense residential districts where building access coordination complexity demands appointment-based logistics.
LAMEA Last Mile Delivery Market Segmentation
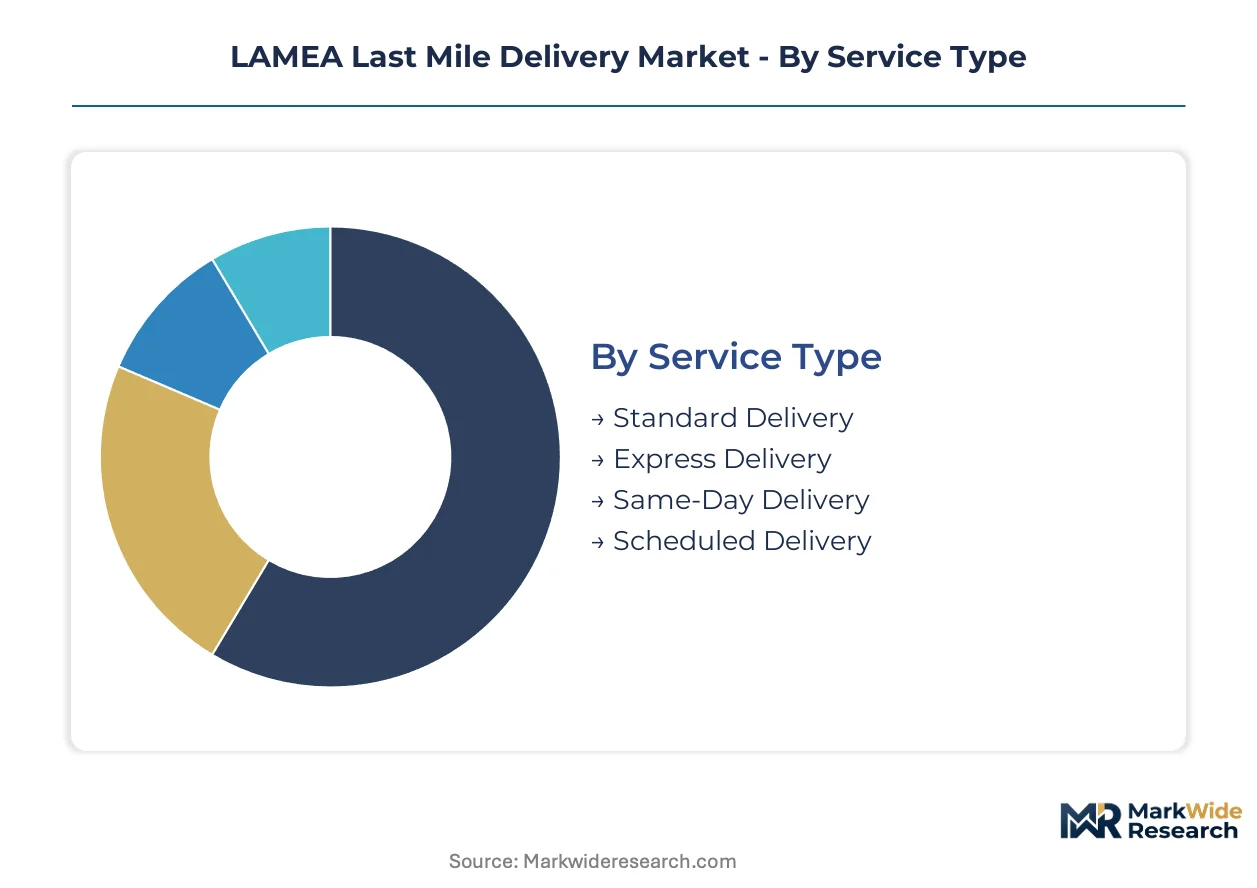
Segmentation in LAMEA last-mile delivery reveals how service tiers, fleet composition, and technology investments align with divergent urban density patterns and regulatory pressures across the region. Understanding these partitions enables operators to match capital deployment with margin profiles and compliance timelines.
Service Type:
Use-case spectrum spans urgent fulfillment to planned logistics, with each tier commanding distinct pricing power and operational complexity.
- Standard Delivery:Multi-day fulfillment windows with consolidated routing economics dominate cost-sensitive corridors. Demand concentrates in Brazilian secondary cities where e-commerce penetration is deepening but premium tolerance remains constrained by purchasing power.
- Express Delivery:Sub-24-hour commitments with dedicated vehicle allocation command tariff premiums of 40-60% above standard tiers. São Paulo and Mexico City metropolitan zones generate concentrated volume as corporate procurement and affluent consumer segments prioritize speed certainty over cost minimization.
- Same-Day Delivery:Ultra-rapid fulfillment requiring micro-fulfillment node proximity and dynamic dispatch systems.
- Scheduled Delivery:Precision time-window commitments reduce failed-attempt costs for bulky goods categories.
Established volume favors Standard Delivery; emerging adoption favors Express Delivery.
End User:
Customer-type concentration determines contract structure stability and volume predictability across the fulfillment ecosystem.
- E-commerce Platforms:Digital retail marketplaces with integrated logistics arms or platform-mediated courier networks drive parcel volume concentration. Mercado Libre and Amazon Brazil are expanding captive fleet capacity in São Paulo to secure service-level guarantees during peak demand windows.
- Third-Party Logistics:Asset-light operators with multi-client aggregation models capture economies of scope through shared routing infrastructure. These providers are gaining traction among mid-market retailers lacking capital for dedicated fleet deployment.
- Retailers:Traditional brick-and-mortar chains with omnichannel fulfillment obligations.
- Restaurants:Food service operators with sub-hour delivery mandates and high cancellation sensitivity.
Contract reliability favors Third-Party Logistics; margin expansion favors E-commerce Platforms.
Technology:
Technology maturity stratifies between proven tracking infrastructure and experimental autonomous systems.
- GPS Tracking:Real-time location telemetry with geofenced arrival notifications constitutes baseline operational infrastructure. Deployment is near-universal across São Paulo and Mexico City fleets, with ANVISA and Mexico's consumer protection agency mandating disclosure transparency for pharmaceutical and e-commerce shipments.
- Route Optimization:Algorithmic dispatch systems reduce miles-per-stop and enable dynamic rerouting based on traffic and demand surges.
- Mobile Applications:Driver-facing interfaces with proof-of-delivery capture and customer communication tools.
- Autonomous Delivery:Drone and ground-robot pilots operating in Dubai and Riyadh regulatory sandboxes.
Operational necessity favors GPS Tracking; capability differentiation favors Route Optimization.
Fleet Type:
Vehicle selection reflects payload requirements, emissions compliance timelines, and infrastructure availability across metropolitan zones.
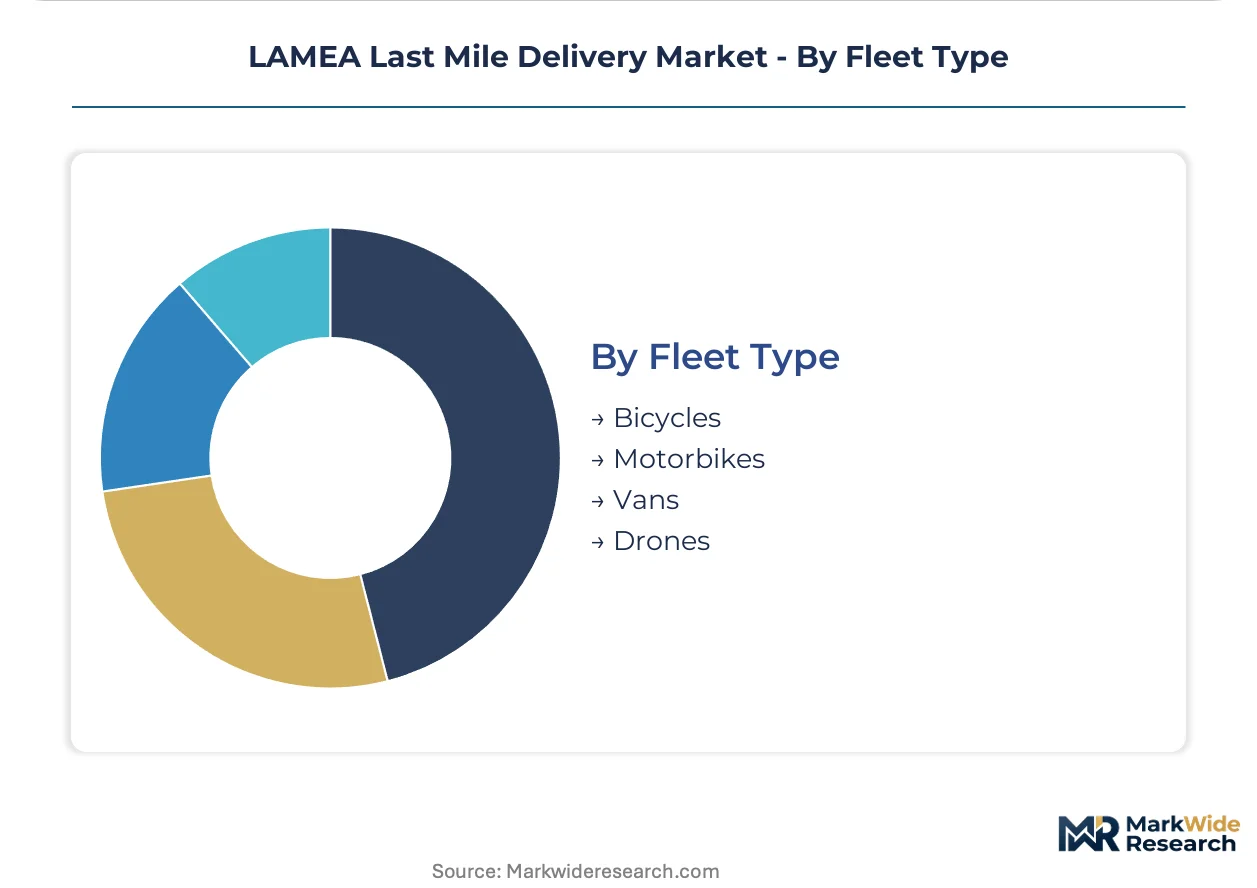
- Vans:Commercial cargo vehicles with 500-1500kg capacity dominate bulky goods and B2B fulfillment segments. Brazil's environmental regulator is enforcing escalating emissions thresholds in São Paulo and Rio de Janeiro, compelling accelerated electric van procurement despite elevated capital costs.
- Motorbikes:Two-wheelers with 50-150kg payload capacity enable rapid penetration of dense urban corridors with parking constraints. Mexico City operators rely heavily on motorbike fleets for express document and small parcel delivery where traffic congestion paralyzes larger vehicles.
- Bicycles:Human-powered or electric-assisted cycles for ultra-short-radius fulfillment in pedestrianized districts.
- Drones:Aerial systems for beyond-visual-line-of-sight testing in Dubai and Riyadh corridors.
Regulatory pressure favors Vans; operational flexibility favors Motorbikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's federal tax incentives for solar-powered depot operations are reducing facility energy costs and accelerating emissions compliance timelines across the LAMEA corridor. Mexico's consumer protection mandates are reshaping platform liability structures for transparent tracking disclosure. Regulatory sandboxes in Gulf Cooperation Council jurisdictions are permitting beyond-visual-line-of-sight drone testing.
Brazil
Mercado Libre and Amazon Brazil are expanding captive fleet capacity in São Paulo to secure service-level guarantees during peak demand windows. ANVISA mandates temperature-verified last-mile protocols for biologics and vaccines, creating specialized logistics demand with premium tariff structures. São Paulo and Rio de Janeiro metropolitan zones concentrate electric van procurement as Brazil's environmental regulator enforces escalating commercial fleet emissions thresholds.
Mexico
Mid-market e-commerce platforms in Mexico City are deploying dynamic route optimization systems within eighteen-month implementation cycles. The federal consumer protection agency mandates transparent delivery tracking disclosure and refund protocols for e-commerce transactions. Mexico City operators rely heavily on motorbike fleets for express document and small parcel delivery where traffic congestion paralyzes larger vehicles.
United Arab Emirates
Dubai's regulatory authorities permit beyond-visual-line-of-sight testing for autonomous aerial delivery, attracting concentrated pilot investment from cross-border operators. MOHAP pharmaceutical distribution standards are elevating cold-chain infrastructure requirements for biologics transit through Gulf hubs. Dubai and Riyadh corridors are emerging as testbeds for drone corridor commercialization before broader LAMEA rollout.
Saudi Arabia
SFDA pharmaceutical logistics standards are driving investment in temperature-controlled last-mile infrastructure for biologics distribution across the Kingdom. The national logistics privatization program is opening state-owned distribution assets to private operator partnerships. Riyadh's regulatory sandbox environment is enabling ground-robot and aerial autonomous delivery pilots with accelerated commercial licensing pathways.
South Africa
The competition authority scrutinizes logistics consolidation patterns to preserve independent courier market access across metropolitan freight networks. National treasury renewable energy procurement programs are subsidizing solar depot installations for fleet operators seeking operational cost reduction. Cape Town and Johannesburg logistics clusters are integrating reverse logistics capabilities to capture bundled pickup-delivery routing economics from e-commerce return volume growth.
LAMEA Last Mile Delivery Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct operational archetypes that reflect divergent capital intensity and geographic anchoring strategies. Integrated platform operators with captive fulfillment networks compete against asset-light aggregators and specialized cold-chain specialists. Strategic moves concentrate on fleet electrification partnerships and micro-fulfillment node densification in metropolitan cores.
Within the cross-border corridor specialist tier, Aramex anchors Middle Eastern hub networks into African last-mile markets. BEST Inc. occupies a position exemplifying high-frequency urban parcel routing through dense Chinese-origin trade lanes terminating in LAMEA ports. FedEx Corporation represents the premium express archetype through controlled cold-chain capabilities for pharmaceutical and perishable segments.
| Leading Market Players |
|---|
| Amazon.com |
| FedEx Corporation |
| United Parcel Service |
| DHL International |
| Aramex |
| SF Express |
| XPO Logistics |
| Kerry Logistics Network Limited |
| BEST Inc. |
| Others |
Pricing and Supply Chain Analysis
São Paulo's electric van procurement clusters concentrate manufacturer bargaining power with BYD, Renault, and local assembly partners, translating into tiered fleet financing costs that downstream operators pass through as delivery surcharges. This geographic supply anchoring shapes margin structures across Brazilian metropolitan corridors where emissions compliance timelines compress capital deployment decisions.
Pricing Analysis
Speed-certification tier creates the primary spread between express, same-day, and standard delivery tariffs. Three-tier pricing structure across premium, standard, and economy levels reflects ANVISA cold-chain compliance costs and real-time tracking infrastructure investments. Cost compression in standard tiers is intensifying because e-commerce platforms internalize logistics arms and eliminate third-party margins. Mid-market retailers show highest price sensitivity; pharmaceutical distributors demonstrate lowest sensitivity due to temperature-verified protocol requirements.
Supply Chain Analysis
Extended payment terms from Chinese EV manufacturers and supply-chain finance facilities from Brazilian development banks are easing fleet procurement burdens for mid-scale operators. Vehicle assembly concentrates in China, Brazil, and Mexico; battery cell production rests on South Korean and Chinese suppliers. Lithium-ion cell supply faces single-source vulnerability from concentrated cathode material processing. Distribution runs through São Paulo and Mexico City metropolitan depot networks before final-mile motorbike or van deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Last-mile delivery in LAMEA reads as a service-attach opportunity where reverse logistics and subscription-based fleet leasing expand faster than pure parcel volume. Recurring-revenue layers from return pickups and pay-per-use vehicle financing now outpace hardware-driven growth in captive fleet deployment.
For Market Incumbents: Build switching-cost moats through integrated warehouse-management API connectivity that locks mid-market retailers into proprietary order-visibility platforms. Deepen backward integration into solar-powered depot operations to capture Brazilian federal tax incentives and shield against grid-dependency risks. Consolidate route-optimization talent pools in São Paulo and Mexico City before specialist data-science scarcity intensifies competitive bidding. For New Entrants and Emerging Players: Build out asset-light platform models in Colombian and Chilean provincial capitals where underdeveloped logistics infrastructure offers first-mover positioning without incumbent density advantages. Target scheduled delivery windows for appliance and furniture categories where precise time-commitments reduce failed-attempt costs and build retailer dependency. Pursue partnership-based entry with regional e-commerce marketplaces lacking captive fleet capital. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among third-party logistics operators with multi-client aggregation models that capture economies of scope through shared routing infrastructure. Long-term viability across the analysis window favors asset-light platforms with reverse logistics capabilities over pure-play forward distributors. Monitor electric van procurement subsidy announcements from Brazilian federal and São Paulo state authorities as inflection indicators for accelerated fleet transition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | BYD and Renault alliances with Brazilian operators lock in zero-emission van supply ahead of ANVISA enforcement timelines. |
| Micro-Fulfillment Node Densification | Urban warehouse proximity in São Paulo and Mexico City enables sub-hour delivery guarantees that command tariff premiums. |
| Reverse Logistics Integration | Bundled pickup-delivery routing captures e-commerce return volume economics that pure-play forward distributors cannot replicate. |
| Cold-Chain Certification Investment | ANVISA-compliant temperature-verified protocols open specialized biologics segments with premium margin structures. |
| Regulatory Sandbox Participation | Dubai and Riyadh drone corridor testing positions operators for autonomous delivery licensing before broader LAMEA rollout. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, e-commerce logistics executives, regulatory affairs specialists at ANVISA and Mexico's consumer protection agency, and third-party logistics platform managers, then refined through secondary validation. Trade data from Brazilian customs authorities, ANVISA pharmaceutical distribution filings, SEC disclosures from listed logistics operators, and IEA electric vehicle adoption databases provided demand-side calibration. Bottom-up route-density modeling and top-down metropolitan GDP correlation were triangulated to ground volume assumptions.
Demand-supply balance across the projection horizon was assessed through parcel volume per capita against fleet capacity deployment in São Paulo, Mexico City, Dubai, and Johannesburg metropolitan zones. Segmentation dimensions modeled include service tier, fleet type, technology maturity, and end-user contract structure alongside cold-chain compliance tier. CAGRs were derived from logistic diffusion curves fitted to e-commerce penetration rates and emissions mandate phase-in schedules. Forecast inputs incorporated ANVISA regulatory timeline certainty and Gulf Cooperation Council autonomous delivery licensing velocity.
Stress conditions across lithium cell price volatility, Brazilian real exchange rate fluctuation, and Mercosur customs friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about electrification subsidy continuity and drone regulatory pathway clarity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
Global Drone Logistics and Transportation Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
Freight Brokerage Market
Logistics and Shipping
Asia Pacific Domestic Courier Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market