
 Telematics-Linked Fleet Battery Health Management Systems Market | 2026-2036
Telematics-Linked Fleet Battery Health Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Telematics-Linked Fleet Battery Health Management Systems Market Insights
China's battery manufacturing corridor is reconfiguring supply dynamics for telematics-linked fleet systems. Continental leverages its automotive sensor heritage to anchor hardware integration for commercial vehicle OEMs. Geotab competes through open-platform architecture that extends third-party battery analytics compatibility. Bosch sustains R&D intensity in edge computing modules purpose-built for fleet energy diagnostics.
Telematics-linked fleet battery health management systems combine wireless sensor networks, cloud-based analytics, and predictive algorithms to monitor state-of-charge, state-of-health, and thermal runaway risk across distributed vehicle assets. These systems enable fleet operators to prevent unplanned downtime, optimize charging schedules, and extend battery cycle life through real-time degradation modeling. Predictive analytics platforms command premium positioning due to AI-driven failure forecasting that reduces total cost of ownership for logistics providers. IoT connectivity infrastructure occupies the largest installed base but faces margin compression as hardware commoditizes. Heavy-duty truck fleets represent the fastest-growing application segment as electrification penetrates long-haul routes previously resistant to battery-electric powertrains.
The EPA's commercial vehicle greenhouse gas standards and the EU's F-Gas Regulation shape product compliance requirements for thermal management components in battery health systems. China's MIIT mandates GB-standard telematics interoperability that conditions market access for foreign platform providers. Fleet management companies must monitor evolving cybersecurity frameworks for connected vehicle data streams as regulatory scrutiny intensifies across jurisdictions.
Market Dynamics
The EU Green Deal's commercial vehicle electrification mandates are compressing fleet operator procurement cycles for predictive battery analytics infrastructure, forcing rapid technology deployment across heavy-duty logistics corridors.
Growth Catalysts
- EU F-Gas Regulation:Thermal management component compliance requirements are accelerating replacement of legacy fleet monitoring hardware with integrated health management systems across German and Dutch logistics hubs.
- Heavy-duty truck electrification:Long-haul route operators are deploying predictive analytics platforms to mitigate range anxiety and unplanned downtime risks on battery-electric corridors.
- GB-standard telematics:China's MIIT interoperability mandates are conditioning market access and driving foreign platform providers to adapt connectivity architectures for cross-border fleet operations.
Market Restraints
- Lithium-ion cell supply concentration:Dependence on East Asian cathode material suppliers creates input cost volatility and procurement risk for integrated battery health system manufacturers.
- Edge computing hardware commoditization:IoT connectivity infrastructure faces sustained margin compression as sensor module production scales and differentiation erodes.
- Cybersecurity framework fragmentation:Divergent connected vehicle data protection requirements across EPA, EU AI Act, and MIIT jurisdictions inflate compliance engineering costs for multi-market platform deployments.
Strategic Opportunities
- India PLI scheme:Domestic commercial vehicle electrification incentives are creating procurement pull for telematics-linked health monitoring systems in emerging logistics markets.
- AI-driven failure forecasting:Convergence of machine learning algorithms with real-time thermal runaway detection is opening premium service tiers for total cost of ownership optimization.
- Last-mile delivery electrification:Underpenetrated urban van fleets in Southeast Asian megacities present whitespace for predictive battery analytics deployment at lower hardware price points.
Industry Challenges
- Battery electrochemistry expertise scarcity:Fleet operators lack in-house capacity to interpret degradation modeling outputs, creating implementation bottlenecks for predictive maintenance platforms.
- Legacy telematics integration complexity:Retrofitting health management layers onto existing fleet management software architectures requires costly middleware development and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telematics-Linked Fleet Battery Health Management Systems Market |
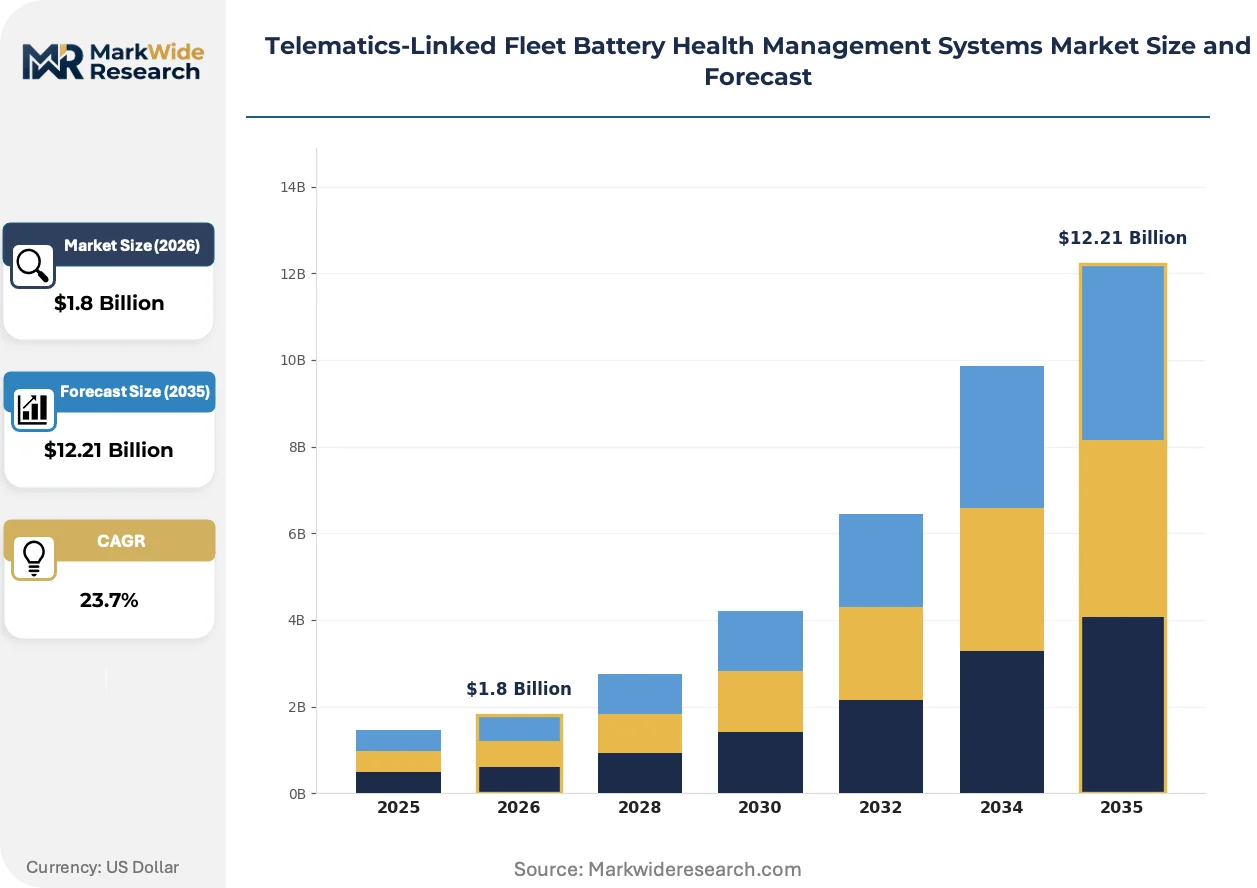
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Monitoring Devices, Diagnostic Software, Predictive Analytics Platforms, Battery Replacement Services, Energy Management Systems Technology: IoT Connectivity, Cloud-Based Analytics, AI-Driven Predictive Maintenance, Wireless Sensor Networks, Edge Computing Application: Heavy-Duty Truck Fleets, Delivery Van Operations, Public Transportation Services, Construction Equipment Fleets, Mining Vehicle Management End User: Logistics Providers, Fleet Management Companies, Public Transit Authorities, Mining Corporations, Construction Contractors |
| Companies Covered | Geotab, Samsara, Verizon Connect, Trimble, Teletrac Navman, Webfleet, Continental, Bosch, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telematics-Linked Fleet Battery Health Management Systems Market Trends and Innovations
Digital twin architectures are virtualizing physical battery asset monitoring, compressing the traditional hardware-software boundary in fleet energy diagnostics and enabling new service delivery models.
Edge-native AI inference engines are virtualizing cloud-dependent analytics workflows for state-of-health estimation. Commercial vehicle OEMs are embedding these modules directly into battery management systems to reduce latency and connectivity costs. This virtualization is compressing the addressable market for standalone telematics hardware providers while expanding software subscription revenue pools.
The EPA's commercial vehicle greenhouse gas standards are tightening thermal monitoring requirements for battery-electric powertrains. Fleet operators must demonstrate continuous cell-level temperature surveillance to maintain compliance certification. Heavy-duty truck segments operating cross-border routes between the US and Canada face the steepest compliance engineering investments.
Third-party battery analytics compatibility is displacing proprietary fleet management platforms. Logistics providers are unbundling health monitoring from incumbent telematics contracts and procuring best-of-breed predictive tools through open API architectures. This preference shift is most visible in German dense logistics corridors where operator technical sophistication supports multi-vendor integration.
Telematics-Linked Fleet Battery Health Management Systems Market Segmentation
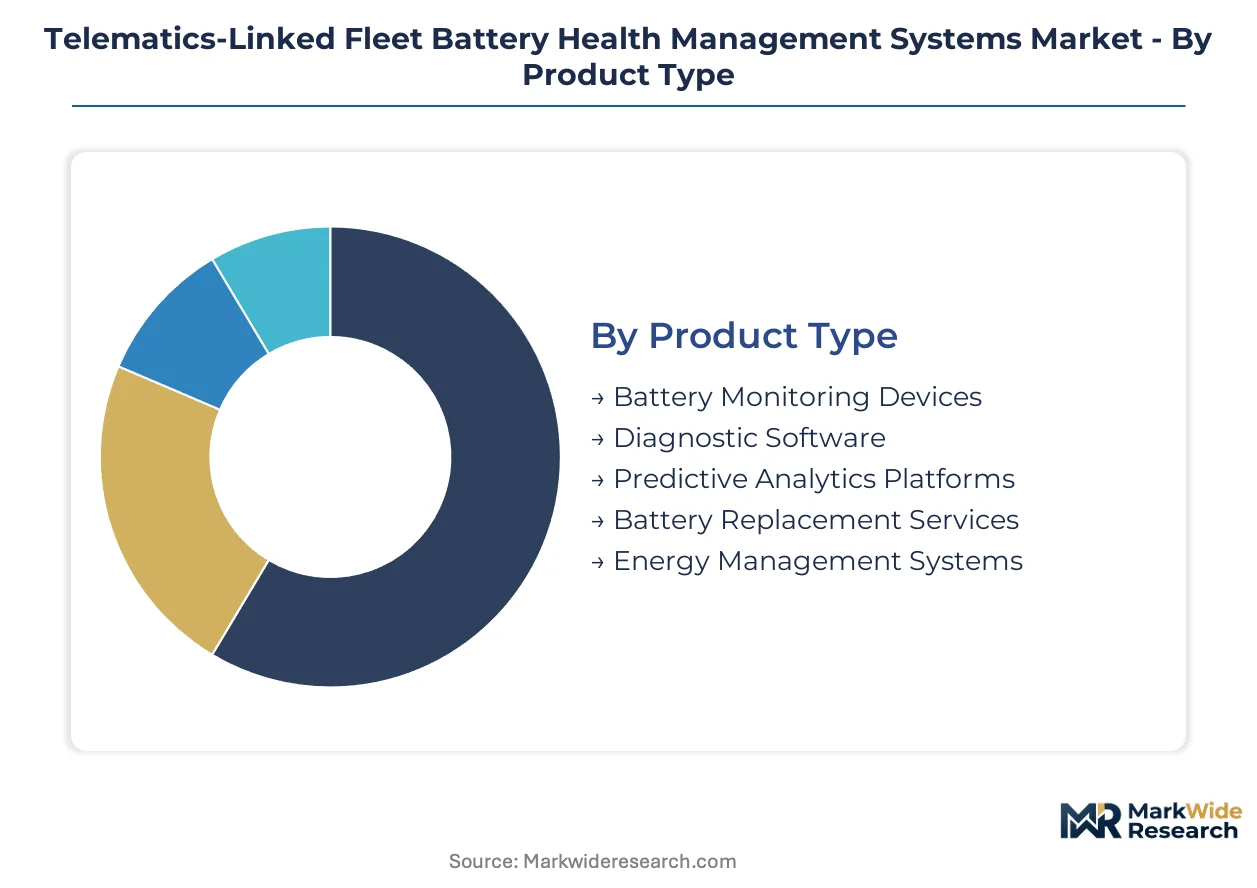
Telematics-linked fleet battery health management systems serve heterogeneous operational requirements across vehicle electrification stages. Segment boundaries reflect divergent technical sophistication thresholds, connectivity infrastructure maturity, and total cost of ownership optimization priorities among fleet operators.
Product Type:
Use-case spectrum spans hardware-centric monitoring through software-enabled predictive intervention, with procurement patterns tracking fleet digitalization maturity.
- Battery Monitoring Devices:Hardware modules measuring voltage, current, and temperature at cell and pack levels with CAN bus integration. German logistics corridors concentrate procurement as EU F-Gas Regulation mandates continuous thermal surveillance for commercial vehicle certification.
- Predictive Analytics Platforms:AI-driven degradation modeling and failure forecasting systems commanding premium positioning. Heavy-duty truck electrification across US-Canada cross-border routes drives steepest adoption curves as operators mitigate range anxiety through state-of-health estimation.
- Diagnostic Software:Real-time fault code interpretation and maintenance scheduling tools with fleet management system integration.
- Battery Replacement Services:End-of-life logistics and second-life repurposing coordination bundled with health data handoff.
- Energy Management Systems:Charging optimization and grid interaction modules for depot-based fleet operations.
The dominant share belongs to Battery Monitoring Devices, while Predictive Analytics Platforms is closing the gap fastest.
Technology:
Technology selection pivots on latency tolerance, connectivity cost structures, and data sovereignty requirements across fleet operational geographies.
- IoT Connectivity:Cellular and satellite telemetry infrastructure transmitting battery telemetry to centralized platforms. Dense logistics networks in the Netherlands and Belgium leverage existing 4G coverage for lowest-cost deployment.
- Edge Computing:On-vehicle inference engines processing state-of-health algorithms without cloud dependency. OEM embedding strategies in China follow MIIT GB-standard interoperability mandates for reduced connectivity cost in cross-border fleet operations.
- Cloud-Based Analytics:Centralized machine learning pipelines aggregating multi-asset degradation patterns.
- AI-Driven Predictive Maintenance:Failure forecasting models trained on historical fleet telemetry and electrochemical simulation.
- Wireless Sensor Networks:Bluetooth and ultra-wideband mesh architectures eliminating wired harness complexity in retrofit installations.
IoT Connectivity holds the largest installed base, though Edge Computing is expanding most quickly as OEMs embed intelligence directly into battery management systems.
Application:
Application segmentation tracks electrification penetration depth across commercial vehicle duty cycles and route predictability profiles.
- Heavy-Duty Truck Fleets:Long-haul battery-electric powertrains requiring predictive thermal runaway detection and charging corridor optimization. EPA greenhouse gas standards compress procurement cycles for integrated health monitoring on US interstate routes.
- Delivery Van Operations:Urban last-mile electrification with predictable duty cycles enabling simplified state-of-charge estimation. Southeast Asian megacities present whitespace for lower hardware price point deployment as postal and parcel operators electrify.
- Public Transportation Services:Fixed-route bus electrification with depot-based charging and standardized cycle profiling.
- Construction Equipment Fleets:Intermittent usage patterns and harsh operating environments demanding ruggedized sensor packaging.
- Mining Vehicle Management:Underground and remote site operations with limited connectivity driving edge-native analytics requirements.
Heavy-Duty Truck Fleets command the highest per-unit system values, while Delivery Van Operations is gaining share fastest on urban electrification momentum.
End User:
End user categories reflect organizational technical capacity to interpret health data and integrate predictive outputs into maintenance workflows.
- Logistics Providers:Third-party freight operators optimizing asset utilization through unplanned downtime prevention. Technical sophistication in German dense corridors supports multi-vendor platform integration and unbundling from incumbent telematics contracts.
- Fleet Management Companies:Leasing and full-service providers using health data to residual value forecasting and contract structuring.
- Public Transit Authorities:Municipal operators with regulatory reporting obligations and budget-constrained replacement cycles.
- Mining Corporations:Resource extraction operators prioritizing asset availability in remote locations with limited service infrastructure.
- Construction Contractors:Project-based equipment owners with fragmented fleet composition and variable maintenance discipline.
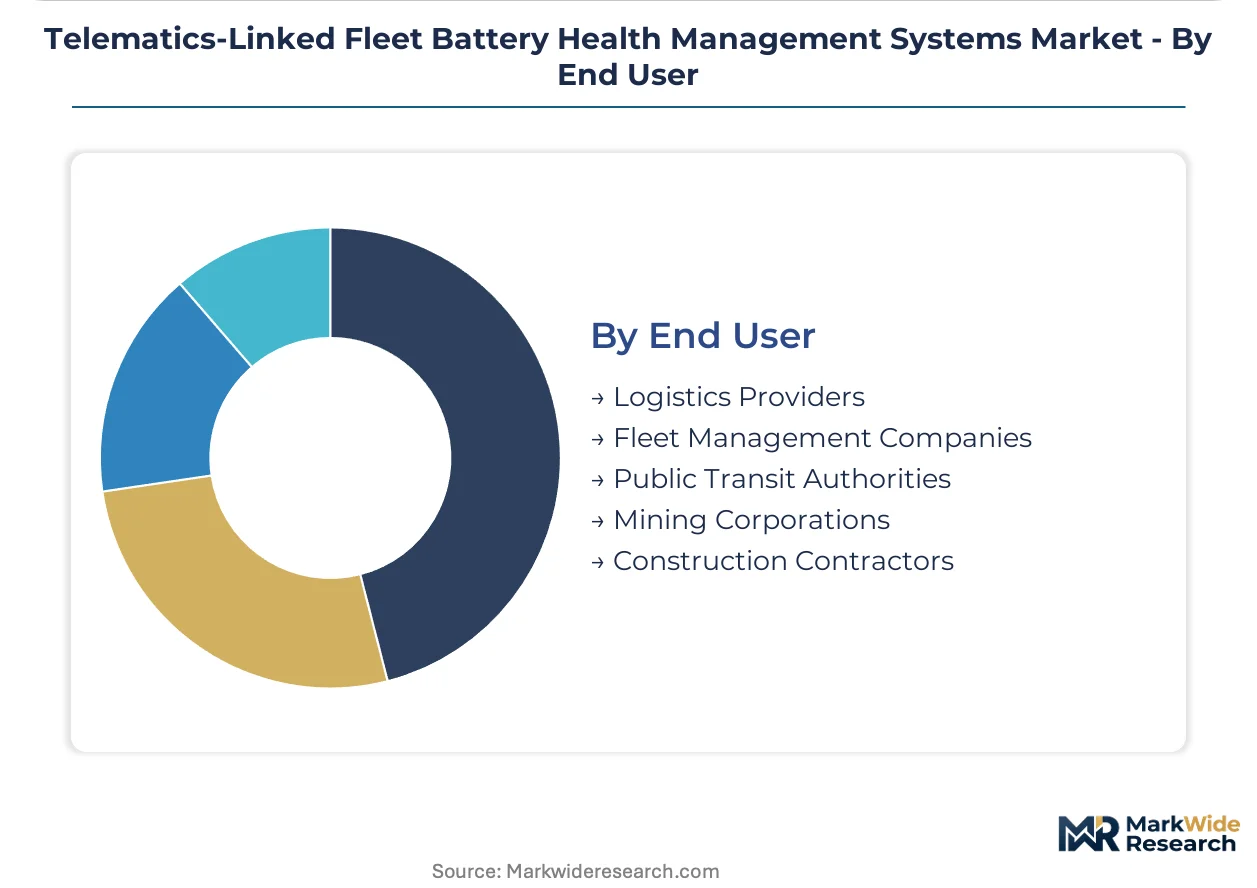
Logistics Providers anchor procurement volume, while Fleet Management Companies is climbing the fastest as residual value optimization becomes central to electrified asset financing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian battery manufacturing dominance and European regulatory stringency are reconfiguring procurement geography for telematics-linked fleet systems. Dense logistics corridors in Germany and the Netherlands concentrate demand for predictive analytics infrastructure.
Germany
Heavy-duty truck fleet operators along the Rhine-Alpine corridor are deploying integrated health monitoring systems to comply with EU F-Gas Regulation thermal surveillance mandates. The KBA enforces continuous cell-level temperature certification for commercial vehicle electrification. Dense logistics hubs in North Rhine-Westphalia anchor procurement volume for predictive battery analytics platforms.
United States
Long-haul electrification across interstate freight corridors is compressing deployment timelines for predictive maintenance infrastructure. EPA commercial vehicle greenhouse gas standards mandate thermal monitoring documentation for battery-electric powertrain certification. Cross-border routes between Michigan and Ontario concentrate pilot deployments for integrated health management systems.
China
Domestic commercial vehicle OEMs are embedding edge-native analytics modules to satisfy MIIT GB-standard telematics interoperability requirements. The country's dual carbon goals accelerate fleet electrification procurement cycles for health monitoring hardware. Manufacturing clusters in Shenzhen and Shanghai supply wireless sensor networks for cross-border logistics operations.
Netherlands
Existing 4G infrastructure coverage enables lowest-cost IoT connectivity deployment for urban delivery van electrification. EU Green Deal commercial vehicle mandates force rapid technology adoption across Rotterdam-Antwerp logistics corridors. Dense freight networks in the Randstad metropolitan region concentrate demand for cloud-based battery telemetry platforms.
India
Domestic logistics providers are piloting predictive analytics platforms under the PLI scheme commercial vehicle electrification incentives. The CEA mandates grid-interactive charging infrastructure standards that condition health system interoperability. Emerging freight corridors in Maharashtra and Gujarat present procurement pull for telematics-linked monitoring at lower hardware price points.
Telematics-Linked Fleet Battery Health Management Systems Market Competitive Landscape
Automotive heritage conglomerates and open-platform software specialists split the market between hardware-integrated and API-extensible deployment models. The vendor base concentrates around three strategic archetypes: sensor-integrated automotive suppliers, cloud-native fleet telematics platforms, and edge-computing module specialists. Incumbent players defend position through backward integration into battery management system firmware, while challengers pursue geographic expansion via regional telematics partnerships.
Within the automotive heritage tier, Continental and Bosch exemplify sensor-integrated positioning through automotive supplier lineage. Geotab occupies a distinct position representing open-platform architecture approaches that extend third-party analytics compatibility. These three anchors illustrate the competitive tension between proprietary hardware integration and extensible software ecosystems that defines procurement segmentation across German logistics corridors and North American long-haul routes.
| Leading Market Players |
|---|
| Geotab |
| Samsara |
| Verizon Connect |
| Trimble |
| Teletrac Navman |
| Webfleet |
| Continental |
| Bosch |
| LG Electronics |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's wireless sensor manufacturing clusters anchor global capacity for telematics-linked fleet battery health systems, translating concentrated component supply into asymmetric pricing power for integrated platform providers serving German logistics corridors.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure for thermal management hardware, separating CE-certified continuous monitoring systems from uncertified legacy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and after-sales service bundling. Cost compression in economy-tier IoT connectivity modules is intensifying because sensor production scales erode hardware margins. Fleet management companies exhibit highest price sensitivity, while heavy-duty truck operators absorbing total cost of ownership optimization premiums show lowest.
Supply Chain Analysis
Foxconn, Jabil, and Luxshare hold contract manufacturing capacity for edge computing modules and wireless sensor assemblies. Supply concentrates in China, South Korea, and Vietnam, drawing from lithium-ion cathode materials, semiconductor foundry output, and cellular modem chipsets. Single-source vulnerability in East Asian battery management system firmware creates structural exposure. Distribution runs through Tier 1 automotive suppliers and direct OEM embedding contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
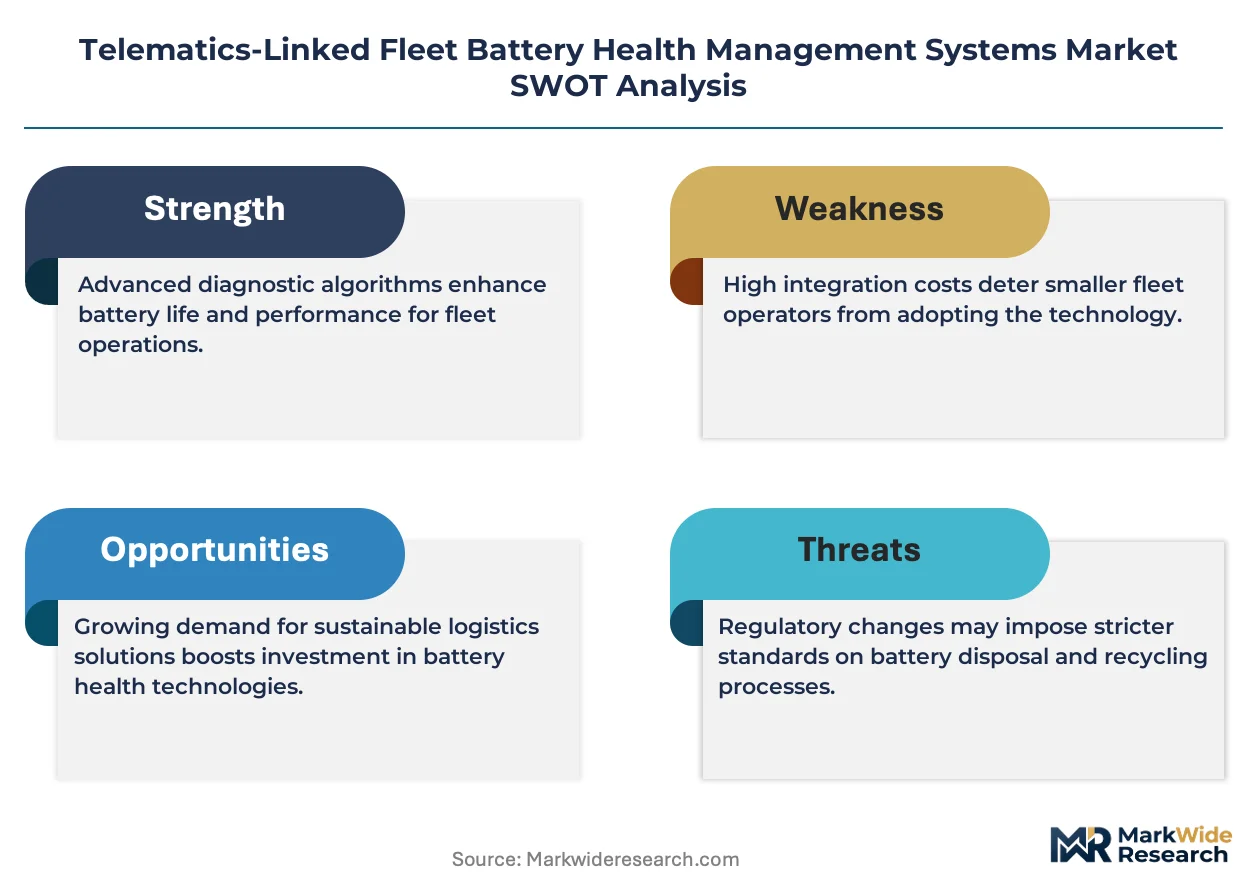
Battery electrochemistry expertise scarcity constrains fleet operator implementation capacity, creating a bottleneck where predictive analytics platforms outpace customer readiness to interpret degradation modeling outputs.
For Market Incumbents: Harden firmware control over battery management system integration to block challenger API unbundling. Deepen backward integration into thermal sensor manufacturing to capture margin from EPA greenhouse gas compliance hardware. Expand certification engineering teams for EU AI Act connected vehicle data governance.
For New Entrants and Emerging Players: Southeast Asian last-mile delivery van fleets present whitespace for lower hardware price point deployment. Target India PLI scheme procurement pull with simplified diagnostic software avoiding legacy telematics retrofit complexity. Pursue regional telematics partnership routes rather than direct OEM sales.
For Investors and Strategic Acquirers: Long-term, this sits as a data-asset play because predictive maintenance platforms accumulate irreplaceable fleet degradation pattern libraries. Target edge-native AI inference engine specialists with automotive OEM validation. Monitor MIIT GB-standard interoperability mandate enforcement as market access inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Open API architectures enable unbundling from incumbent telematics contracts in German logistics corridors. |
| Acquisition of Specialist Firm | Battery electrochemistry modeling expertise addresses fleet operator implementation bottlenecks. |
| Geographic Expansion | India PLI scheme incentives create procurement pull for health monitoring infrastructure deployment. |
| Product Launch | Edge-native AI inference engines reduce cloud dependency for cross-border fleet operations. |
| Strategic Partnership | Charging infrastructure partnerships optimize depot-based energy management system coordination. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory databases, automotive production statistics, and customs trade records. Interviews with fleet operations directors, OEM platform engineers, battery management system firmware developers, and telematics procurement officers inform demand-side validation. Bottom-up unit economics modeling triangulates against top-down market sizing from vehicle electrification forecasts and regulatory mandate timelines.
Forecast inputs incorporate vehicle class electrification penetration, propulsion architecture content per vehicle, OEM tier supplier sourcing patterns, and regional regulatory cluster adoption curves. Segmentation dimensions span product type maturity, technology deployment model, application duty cycle predictability, and end-user technical sophistication. CAGRs derive from fitted adoption curves against historical fleet management software transitions and battery-electric powertrain warranty cost data.
Practitioners should monitor lithium-ion cell supply concentration shifts, cybersecurity framework harmonization progress, and edge computing hardware commoditization velocity for early signals of forecast revision. Quarterly review of MIIT GB-standard enforcement intensity and EPA greenhouse gas certification timeline adherence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
Mobility on Demand (Mod) Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Next Generation in-Vehicle Networking (IVN) Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Global in Dash Navigation System Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
Smart Telematics Gateway Market
Telematics and Infotainment
C-V2X OBU Market