
 Netherlands Last Mile Delivery Market | 2026-2036
Netherlands Last Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Last Mile Delivery Market Insights
Parcel locker networks and micro-fulfillment nodes in Dutch city centers is narrowing the physical gap between inventory and consumer doorsteps. PostNL leverages its nationwide postal infrastructure to sustain last-mile density across suburban and rural postcodes. DHL competes through automated sorting hubs positioned near Rotterdam's port complex. DPD anchors its Dutch operations with electric van fleets serving Amsterdam's ring road corridors.
Last mile delivery denotes the final transportation leg from distribution hub to end recipient, typically spanning distances under 50 kilometers and requiring real-time tracking, dynamic routing, and proof-of-delivery confirmation. GPS tracking and route optimization software coordinate vehicle dispatch against traffic patterns and delivery windows. Same-day service commands premium positioning among time-sensitive e-commerce buyers, while scheduled delivery retains cost advantages for non-urgent retail replenishment. Van-based transport still occupies the volume core, though cycling and walking segments gain ground in Amsterdam and Utrecht's dense historic cores where vehicle access faces restriction.
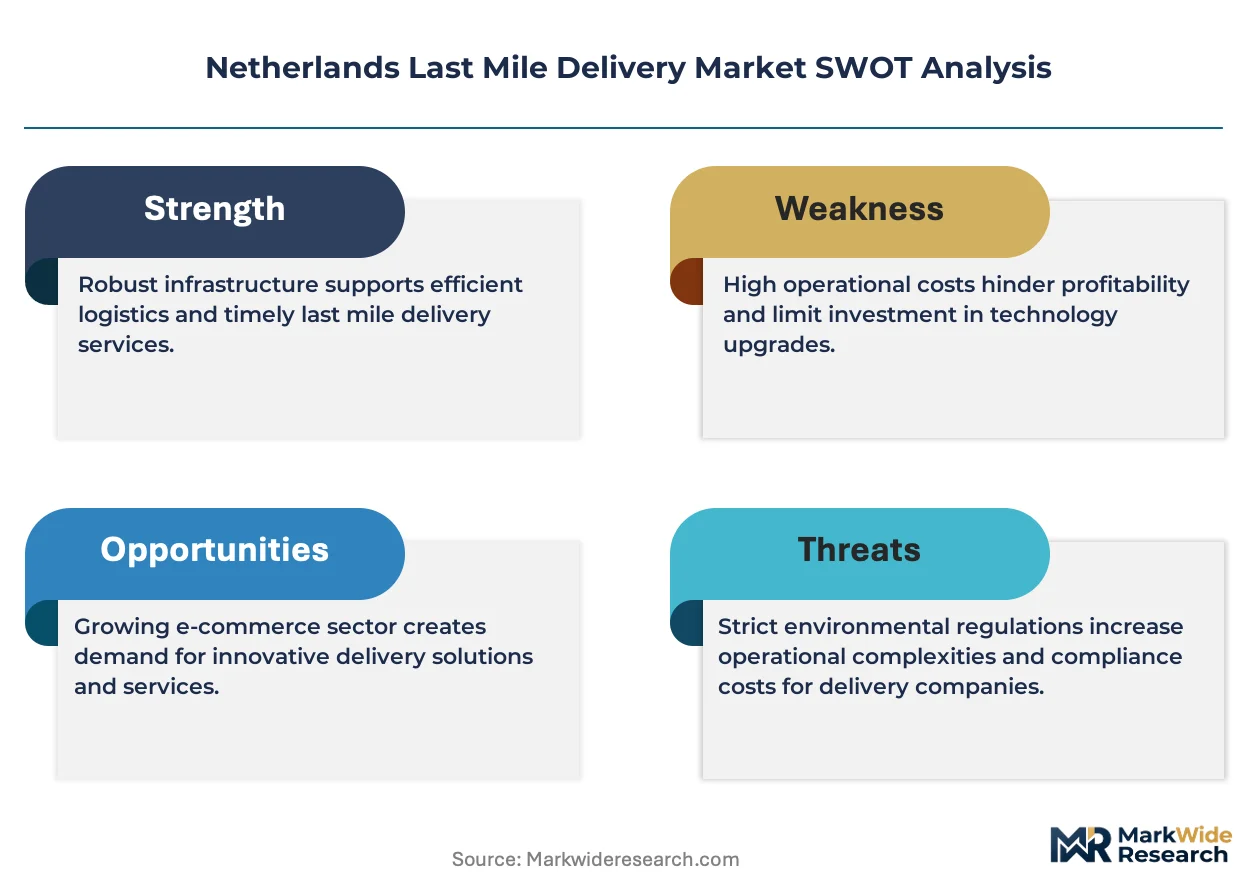
The Dutch Environmental Management Act and municipal zero-emission zones enforced by city regulators are mandating electric vehicle transition and restricting diesel van access in central business districts. The Netherlands Authority for Consumers and Markets monitors carrier pricing transparency and platform competition under national competition law. Stakeholders must weigh fleet electrification timelines against micro-hub real estate costs as regulatory pressure tightens operational constraints.
Market Dynamics
Amsterdam's zero-emission zones under the Dutch Environmental Management Act are forcing carriers to compress electrification timelines against micro-hub real estate scarcity. This regulatory pressure is restructuring fleet economics and urban logistics footprints simultaneously.
Growth Catalysts
- Online grocery parcel volumes:Dutch supermarket chains are scaling same-day fulfillment networks, pulling refrigerated van demand and cold-chain micro-fulfillment investment into dense Randstad postcodes.
- Municipal zero-emission mandates:Rotterdam, Utrecht and The Hague have replicated Amsterdam's diesel van restrictions, expanding the addressable market for electric light commercial vehicles and cargo bike infrastructure.
- GPS tracking and route optimization software:Real-time dispatch coordination against traffic patterns is compressing cost-per-delivery and enabling tighter delivery windows for time-sensitive e-commerce buyers.
Market Restraints
- Micro-hub real estate costs:Central Amsterdam and Rotterdam waterfront industrial land commands premium pricing that erodes last-mile unit economics for independent carriers.
- Grid infrastructure lag:Suburban and rural postcodes outside Randstad corridors lack sufficient charging point density to support full fleet electrification timelines mandated by municipal regulators.
- Cargo bike payload limitations:Dense historic cores in Utrecht and Leiden restrict vehicle access, yet refrigerated parcels and bulky furniture exceed bicycle trailer capacity thresholds.
Strategic Opportunities
- Underpenetrated Limburg and Groningen provinces:Peripheral Dutch regions beyond Randstad density offer first-mover positioning for parcel locker networks and automated sorting hubs.
- EU Green Deal fleet subsidies:National incentive schemes for electric commercial vehicle procurement reduce capex barriers for mid-size carriers transitioning diesel van fleets.
- Convergence of parcel lockers and micro-fulfillment:Shared urban real estate combining automated pickup points with dark store inventory is narrowing inventory-to-doorstep distance in Dutch city centers.
Industry Challenges
- Electric vehicle technician scarcity:Maintenance networks for electric van fleets require specialized battery and drivetrain expertise that outpaces current vocational training output.
- Legacy warehouse management system integration:Automated sorting hubs and dynamic routing platforms must interface with incumbent ERP architectures, creating data synchronization friction during deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Last Mile Delivery Market |
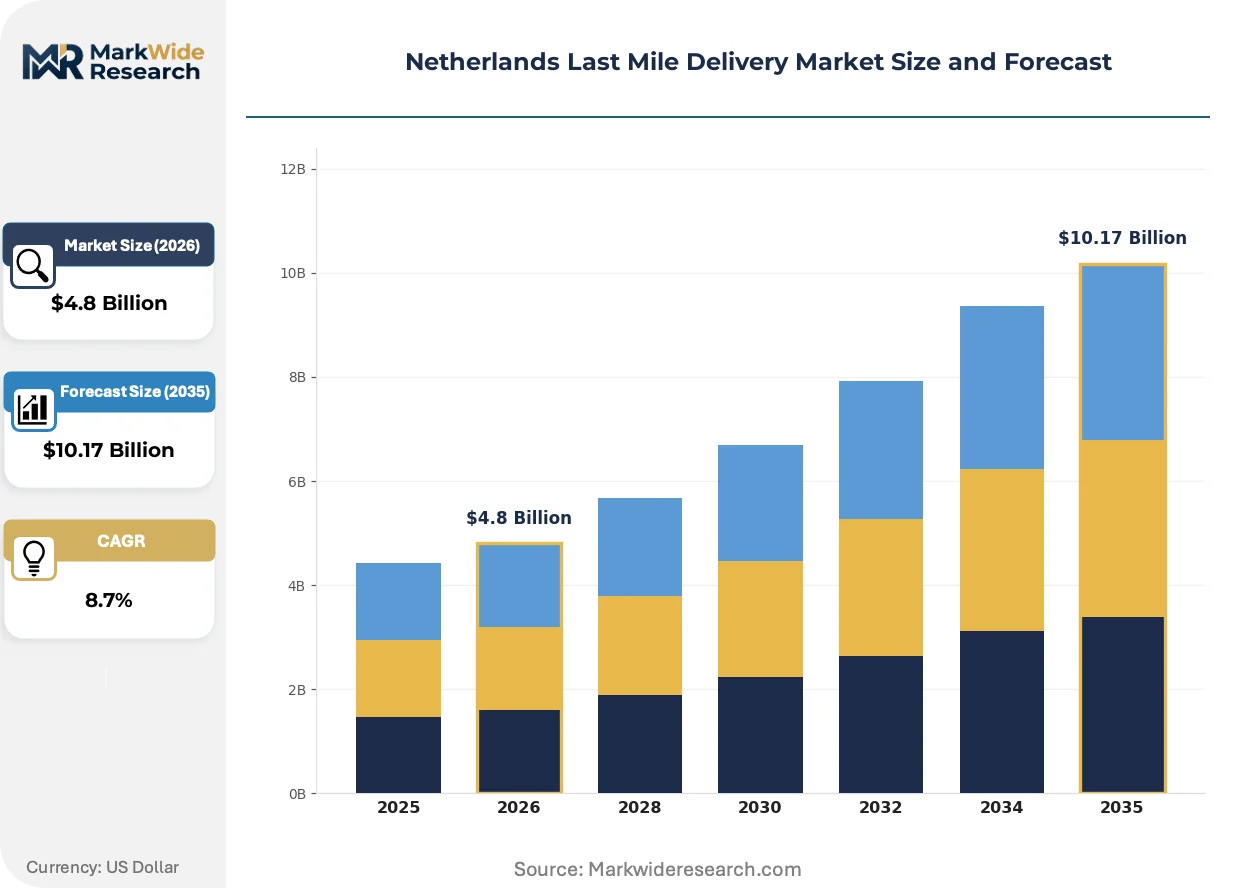
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Method: Cycling, Walking, Van, Drone Service Type: Same-Day, Next-Day, Scheduled, On-Demand End User: Retailers, E-Commerce, Wholesalers, Service Providers Technology: GPS Tracking, Route Optimization, Mobile Apps, Automation |
| Companies Covered | PostNL, DHL, DPD, UPS, DSV, Geodis, DB Schenker, Kuehne + Nagel, CEVA Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Last Mile Delivery Market Trends and Innovations
Logistics infrastructure is compressing physical distance between inventory and consumer through automated micro-nodes and electrified fleet coordination. Three forces are restructuring competitive positioning.
Dynamic route optimization algorithms are migrating from static daily planning to real-time dispatch against traffic, weather and delivery window constraints. E-commerce carriers serving Amsterdam's ring road corridors are adopting these platforms at accelerating pace. This capability compression is enabling same-day service premiums while reducing kilometers-per-parcel inefficiency.
The Dutch Environmental Management Act's zero-emission zone enforcement is mandating diesel van phase-out timelines that outpace natural fleet replacement cycles. Municipal regulators in Rotterdam and The Hague have extended Amsterdam's central business district restrictions, forcing carrier capital reallocation toward electric light commercial vehicles and cargo bike infrastructure. Suburban and rural postcodes face grid infrastructure bottlenecks that delay full compliance.
Buyer procurement of delivery services is fragmenting across scheduled economy, standard next-day and premium same-day tiers. Large Dutch retailers are unbundling logistics contracts, awarding separate lanes to specialized carriers rather than consolidated national providers. This pattern concentrates in Randstad corridors where consumer density supports service-level segmentation.
Netherlands Last Mile Delivery Market Segmentation
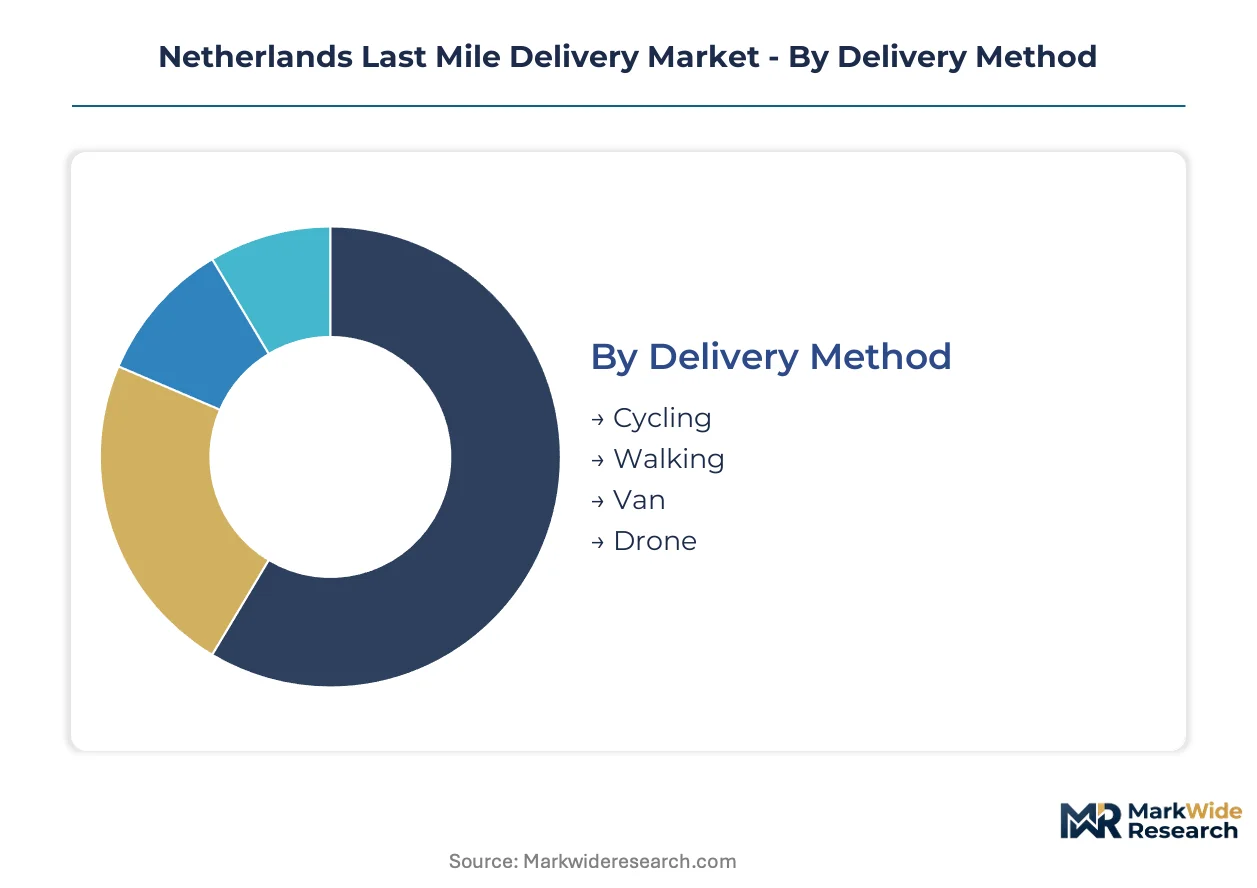
Segmentation in Dutch last-mile delivery reveals how carriers allocate capital across modal choices and service tiers. Each dimension exposes distinct margin structures, electrification requirements, and real estate dependencies that shape competitive positioning in Randstad corridors.
Delivery Method:
After-sales service intensity varies sharply across modalities, with electric vans requiring technician networks and cargo bikes demanding rapid-response maintenance in dense urban cores.
- Van:Electric light commercial vehicles dominate parcel volume in Amsterdam's ring road corridors and Rotterdam's port-adjacent distribution zones. Municipal zero-emission mandates under the Dutch Environmental Management Act are compressing diesel-to-electric transition timelines for carriers serving central business districts.
- Cycling:Cargo bikes and electric-assisted bicycles handle final-50-meter delivery in Utrecht and Leiden historic cores where vehicle access faces restriction. Payload ceilings limit application to parcels under 30 kilograms, excluding refrigerated groceries and bulky furniture from this modal option.
- Walking:Pedestrian couriers operate in Amsterdam's canal district and The Hague's Binnenhof quarter, covering micro-zones under 500 meters from urban micro-hubs. This method sustains lowest per-delivery carbon intensity but restricts throughput to lightweight, non-urgent parcels.
- Drone:Autonomous aerial systems remain in pilot phase across rural Friesland and Zeeland island communities, bridging waterway barriers that extend van routes. Regulatory frameworks from the country's aviation authority limit commercial deployment to beyond-visual-line-of-sight corridors.
By volume, Van leads. By growth pace, Cycling is ahead.
Service Type:
Cost tier stratification separates premium same-day positioning from economy scheduled delivery, with each tier commanding distinct fleet utilization patterns and labor cost structures.
- Same-Day:Time-definite delivery within 4-6 hours commands premium pricing from Dutch supermarket chains scaling fresh grocery fulfillment. Refrigerated van pools and dynamic routing software coordinate temperature-controlled handoffs against narrow delivery windows in dense Randstad postcodes.
- Next-Day:Standard 24-hour service retains volume core for non-urgent e-commerce replenishment, leveraging automated sorting hubs near Rotterdam's port complex for line-haul efficiency. This tier balances unit economics against consumer expectations for predictable arrival windows.
- Scheduled:Appointment-based delivery serves furniture retailers and appliance wholesalers requiring recipient presence for bulky item handoff. Carriers optimize route density by clustering scheduled slots within 2-hour windows across suburban North Holland and South Holland provinces.
- On-Demand:Instant fulfillment within 1-2 hours targets foodservice and pharmaceutical segments in Amsterdam and The Hague urban cores. Micro-fulfillment nodes positioned within 3 kilometers of recipient addresses enable this service tier's compressed inventory-to-doorstep distance.
Next-Day captures the volume base. Same-Day is climbing the fastest.
End User:
Application-specific requirements drive divergent fleet specifications, with refrigerated capacity for grocery retail contrasting parcel-locker integration for pure-play e-commerce.
- E-Commerce:Pure-play online retailers generate parcel volume concentration in Randstad corridors, with demand for flexible delivery windows and locker-based pickup alternatives. GPS tracking integration and mobile app proof-of-delivery confirmation are baseline requirements.
- Retailers:Omnichannel Dutch supermarket chains are scaling same-day fulfillment networks, pulling cold-chain micro-fulfillment investment into dense urban postcodes. Click-and-collect convergence with home delivery strains fleet flexibility.
- Wholesalers:B2B replenishment of stock-keeping units to independent retailers operates on scheduled lanes with palletized consolidation, distinct from consumer parcel dynamics.
- Service Providers:Third-party logistics contractors handle overflow capacity for peak e-commerce periods, requiring rapid fleet scaling without fixed asset ownership.
E-Commerce leads by parcel count. Retailers are gaining share fastest.
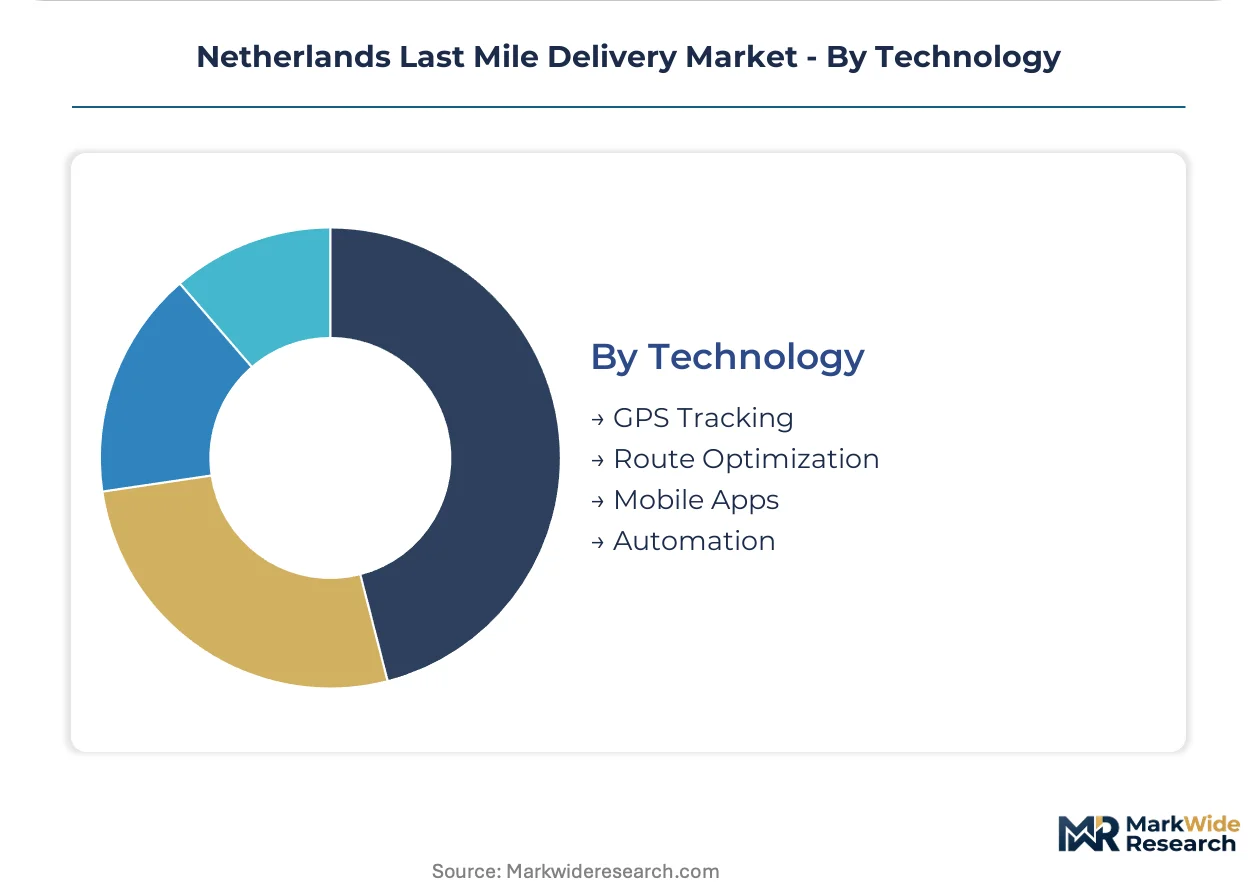
Technology:
Maturity gradients separate established GPS infrastructure from emerging automation layers, with integration costs and data synchronization requirements determining adoption pace.
- GPS Tracking:Real-time vehicle location monitoring enables dynamic dispatch against traffic patterns and delivery window constraints. This capability underpins customer-facing arrival time predictions and proof-of-delivery verification.
- Route Optimization:Algorithmic planning against traffic, weather, and delivery density compresses kilometers-per-parcel inefficiency. Migration from static daily planning to real-time adjustment is accelerating among carriers serving Amsterdam's ring road corridors.
- Mobile Apps:Driver-facing interfaces coordinate handoff confirmation, recipient communication, and exception management. Consumer-facing apps enable delivery window selection and locker code retrieval.
- Automation:Automated sorting hubs and robotic micro-fulfillment nodes reduce labor dependency in high-volume Rotterdam and Amsterdam distribution centers. Legacy warehouse management system integration creates deployment friction.
GPS Tracking holds the installed base. Automation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's port complex anchors the Netherlands' logistics throughput, with deep-water container terminals feeding distribution corridors radiating toward the Randstad agglomeration. This maritime infrastructure underwrites the country's role as a European gateway for e-commerce fulfillment networks.
North Holland
Amsterdam's canal district and Schiphol Logistics Park concentrate premium same-day fulfillment demand from fashion and electronics retailers. The Dutch Environmental Management Act's zero-emission zone enforcement restricts diesel van access within the A10 ring road, compelling carriers to deploy electric light commercial vehicles and cargo bike pools. Parcel locker networks and micro-fulfillment nodes cluster along Haarlemmerweg and Zuidas business corridor.
South Holland
Rotterdam's port-adjacent distribution zones and The Hague's government quarter generate divergent logistics requirements. Municipal regulators have replicated Amsterdam's diesel restrictions across Rotterdam's central business district, expanding electric fleet mandates. Automated sorting hubs position near Waalhaven container terminals to compress line-haul distances for parcels entering European distribution networks.
Utrecht
The province's central rail junction status attracts inventory positioning for national distribution networks. Historic core restrictions in Utrecht city center limit vehicle access to electric-assisted cargo bikes and pedestrian couriers. Leidsche Rijn development zone offers peripheral real estate for micro-hubs serving the dense urban core without premium central land costs.
North Brabant
Eindhoven's high-tech manufacturing cluster and Tilburg's furniture retail concentration pull scheduled delivery capacity for bulky goods handoff. The region lies outside Randstad density corridors, offering lower last-mile unit economics for independent carriers. Grid infrastructure limitations delay full fleet electrification timelines compared to Amsterdam and Rotterdam compliance schedules.
Netherlands Last Mile Delivery Market Competitive Landscape
On the supply side, the industry is consolidating around integrated postal operators and global express carriers with dedicated Dutch infrastructure. National postal density competes against international hub-and-spoke networks. Two strategic archetypes dominate: legacy postal operators leveraging nationwide address databases, and global integrators deploying automated sorting technology. Competitive moves center on micro-hub real estate acquisition and electric fleet procurement acceleration against regulatory deadlines.
Among established Dutch operators, PostNL anchors the national postal infrastructure tier, while DHL and DPD occupy positions within the international express carrier segment. These three exemplify divergent responses to municipal zero-emission mandates—PostNL through nationwide electrification sequencing, DHL through Rotterdam port-proximate automation investment, and DPD through ring road electric van corridor specialization.
| Leading Market Players |
|---|
| PostNL |
| DHL |
| DPD |
| UPS |
| DSV |
| Geodis |
| DB Schenker |
| Kuehne + Nagel |
| CEVA Logistics |
| Others |
Pricing and Supply Chain Analysis
Rotterdam's port-adjacent distribution zones concentrate automated sorting capacity and electric fleet procurement, anchoring margin pools with carriers serving Amsterdam's zero-emission corridors while compressing unit economics for independent operators lacking scale.
Pricing Analysis
Volume-discount tiering structures separate national postal operators from mid-size carriers lacking route density. Three-tier pricing stratification across premium same-day, standard next-day, and economy scheduled tiers reflects service-level differentiation. Price differentiation hinges on delivery window precision and refrigerated capacity for grocery retail. Cost compression in economy tiers intensifies as municipal zero-emission mandates accelerate fleet replacement cycles. Small e-commerce merchants exhibit highest price sensitivity; omnichannel supermarket chains prioritize reliability over rate negotiation.
Supply Chain Analysis
Tariff exposure between German electric van manufacturers and Dutch fleet operators dominates procurement risk as EU Green Deal subsidies compress import cost advantages. Supply concentration rests on German and Chinese battery cell production, Belgian charging infrastructure components, and domestic micro-hub real estate. Raw material dependencies span lithium-ion cells, aluminum chassis, and thermal insulation for refrigerated compartments. Single-source vulnerability concentrates in specialized electric drivetrain assemblies. Distribution feeds from Rotterdam port terminals through automated sorting hubs into Randstad micro-fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal zero-emission enforcement under the Dutch Environmental Management Act constitutes a regulatory inflection accelerating fleet electrification timelines and restructuring competitive economics across last-mile delivery.
For Market Incumbents: Entrench position through accelerated micro-hub real estate acquisition in constrained Amsterdam and Rotterdam central districts before premium industrial land scarcity worsens. Secure exclusive parcel locker placements at Dutch railway stations and supermarket chains to lock out emerging competitors. Prioritize backward integration into electric vehicle maintenance networks to offset technician scarcity.
For New Entrants and Emerging Players: Establish a beachhead in Limburg and Groningen provinces where parcel locker penetration remains underdeveloped and incumbent density is lowest. Target scheduled delivery for bulky furniture retail in North Brabant, where lower real estate costs improve unit economics. Deploy cargo bike pools in Utrecht and Leiden historic cores as a low-capex entry wedge.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional carriers holding suburban route density but lacking electrification capital. Long-term viability favors operators with secured micro-hub footprints and technician training pipelines. Monitor Amsterdam municipal regulator announcements for zero-emission zone expansion timing as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Hub Real Estate Acquisition | Parcel locker placement at Dutch railway stations locks in consumer pickup convenience. |
| Electric Fleet Procurement Acceleration | EU Green Deal subsidies reduce capex barriers for Rotterdam port-adjacent carriers. |
| Cargo Bike Infrastructure Deployment | Amsterdam's historic core restrictions mandate bicycle-based final-50-meter delivery. |
| Automated Sorting Hub Investment | Rotterdam Waalhaven positioning compresses line-haul distances for European distribution. |
| Refrigerated Capacity Expansion | Same-day grocery fulfillment pulls cold-chain investment into dense Randstad postcodes. |
Research Methodology
Operator-level perspectives from fleet managers, municipal logistics planners, electric vehicle procurement officers, and micro-hub real estate developers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against Dutch Environmental Management Act enforcement schedules, EU Green Deal subsidy documentation, and municipal zero-emission zone regulatory filings. Bottom-up parcel volume modeling triangulated with top-down carrier capacity assessments.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning delivery modality, service tier, end-use application, and technology layer. CAGRs derived from trend extrapolation against electrification timelines and micro-fulfillment penetration curves. Forecast inputs incorporated charging infrastructure build-out pace and parcel locker network expansion.
Sensitivities concentrate around municipal regulator enforcement timing, grid infrastructure lag in peripheral provinces, and electric vehicle technician training output. Forecasts reflect documented assumptions on fleet replacement cycles and real estate availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Russia Third-Party Logistics (3PL) Market
Logistics and Shipping
Tank Container Shipping Market
Logistics and Shipping
Air Cargo Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
US International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
Spain Freight and Logistics Market
Logistics and Shipping
Turkey Courier Express and Parcel (CEP) Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market