
 In Car Infotainment System Market | 2026-2036
In Car Infotainment System Market Size, Share, and Industry Trends Forecast 2026-2036
In Car Infotainment System Market Insights
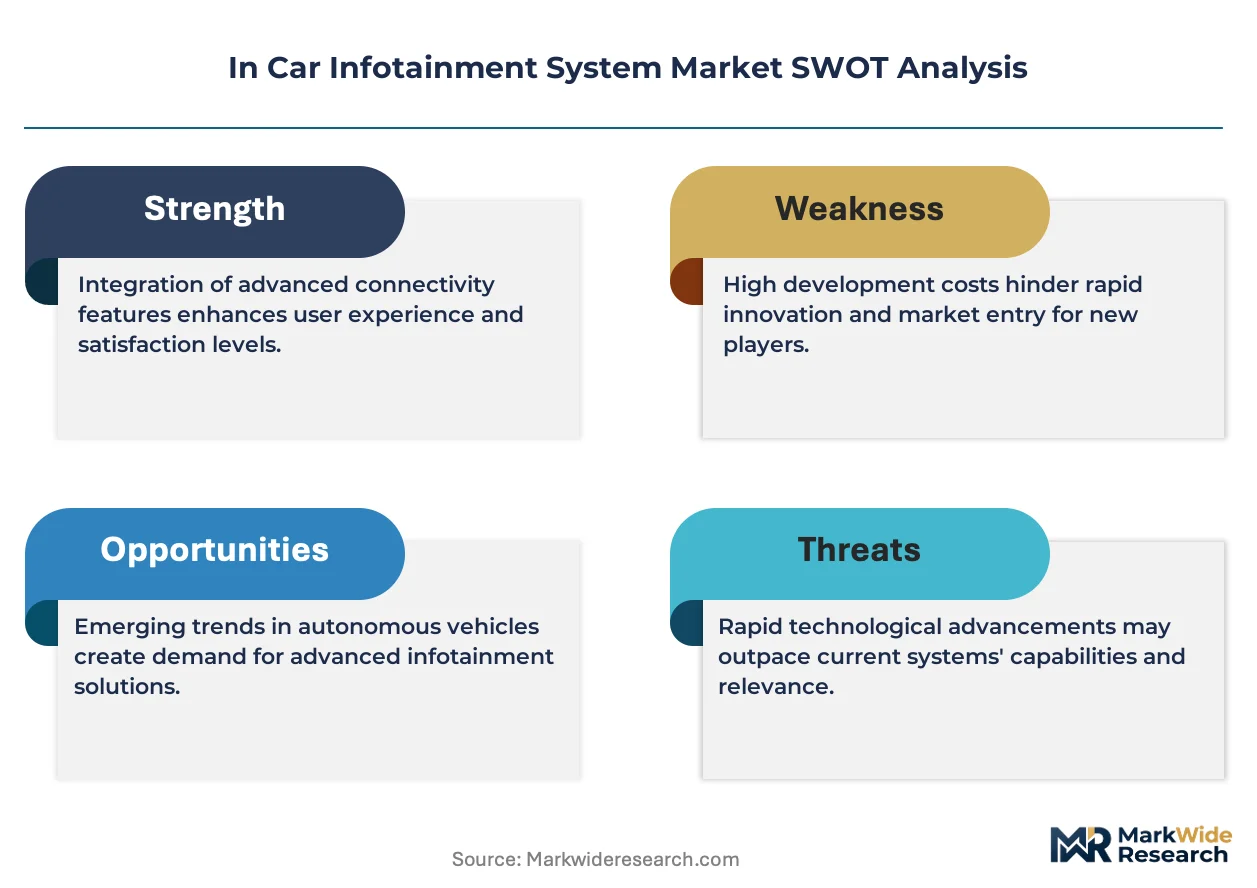
EU cybersecurity certification for connected vehicles is repositioning the cost-of-entry calculus for cockpit electronics suppliers. Harman International leverages its Samsung-backed semiconductor sourcing to sustain vertical integration in premium audio and display modules. Panasonic Corporation anchors its competitive stance through manufacturing scale across multiple Japanese and North American assembly plants. Robert Bosch GmbH differentiates via embedded software stacks that navigate functional safety requirements for Level 2+ autonomous driving interfaces.
An in-car infotainment system integrates hardware and software components including touchscreens, processors, audio amplifiers, and wireless connectivity modules to deliver navigation, entertainment, telematics, and human-machine interface functions within the vehicle cabin. These systems typically operate on automotive-grade computing platforms with temperature tolerances spanning minus 40 to 85 degrees Celsius and incorporate over-the-air update capabilities to maintain software relevance across vehicle lifecycles. Factory-installed integrated systems command the dominant share of value capture due to OEM control over electrical architecture design and long-term service revenue streams. Voice recognition technology represents the fastest-expanding interface category as automakers compete to reduce driver distraction metrics and differentiate premium trim levels. Aftermarket add-on solutions face margin compression from declining installation complexity and compressed replacement cycles in aging vehicle parcs.
The European Union's Cyber Resilience Act and the UN ECE R155 regulation on cybersecurity management systems are mandating formal threat assessment protocols for all networked cockpit electronics, effectively filtering non-compliant component vendors from OEM supply rosters. The U.S. NHTSA maintains advisory guidelines on driver distraction that directly influence display placement, menu depth, and voice command latency requirements across all vehicles sold in the American market. China's MIIT enforces domestic data localization standards for connected vehicle platforms, creating divergent architecture requirements for global suppliers serving multiple geographies. Stakeholders must monitor how fragmentation in software certification regimes affects platform development costs and supplier consolidation trajectories.
Market Dynamics
Automotive OEMs are consolidating cockpit electronics architectures around centralized computing platforms, compressing tier-two component suppliers while elevating software-defined vehicle stacks as the primary value capture layer.
Growth Catalysts
- EU AI Act compliance mandates:European vehicle manufacturers must certify algorithmic transparency in voice recognition and driver monitoring systems, creating certified supplier demand for explainable AI middleware.
- Over-the-air update proliferation:Automotive-grade Linux and Android Automotive OS distributions now support decade-long software lifecycles, enabling recurring revenue streams from feature subscriptions and security patches.
- German engineering cluster density:Stuttgart and Munich host co-located R&D centers for Harman, Bosch, and Continental, accelerating prototype-to-production cycles for Level 2+ autonomous interfaces.
Market Restraints
- Automotive semiconductor allocation constraints:Foundry capacity for 7nm and 5nm automotive SoCs remains captive to consumer electronics demand cycles, creating 26-52 week lead time volatility for cockpit domain controllers.
- UN ECE R155 certification costs:Threat assessment and security management system documentation requirements add fixed compliance overhead that filters sub-scale component vendors from OEM supply rosters.
- Smartphone mirroring substitution:Apple CarPlay and Android Auto continue displacing embedded navigation revenue pools as consumers prefer familiar mobile app ecosystems over proprietary OEM software.
Strategic Opportunities
- India domestic manufacturing incentives:PLI scheme allocations for automotive electronics and semiconductor packaging attract tier-one suppliers to Chennai and Pune assembly corridors.
- AR-HUD convergence with ADAS:Augmented reality head-up displays integrating real-time navigation and hazard alerts command premium positioning in luxury and electric vehicle segments.
- Japan METI data trust framework:Cross-industry data sharing protocols for connected vehicles enable mobility service providers to monetize aggregated driver behavior analytics.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates at Bosch, Continental, and Denso, constraining expansion capacity for emerging cockpit software vendors.
- Legacy CAN bus integration friction:New zonal E/E architectures must maintain backward compatibility with 1990s-era powertrain networks, complicating wiring harness rationalization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Car Infotainment System Market |
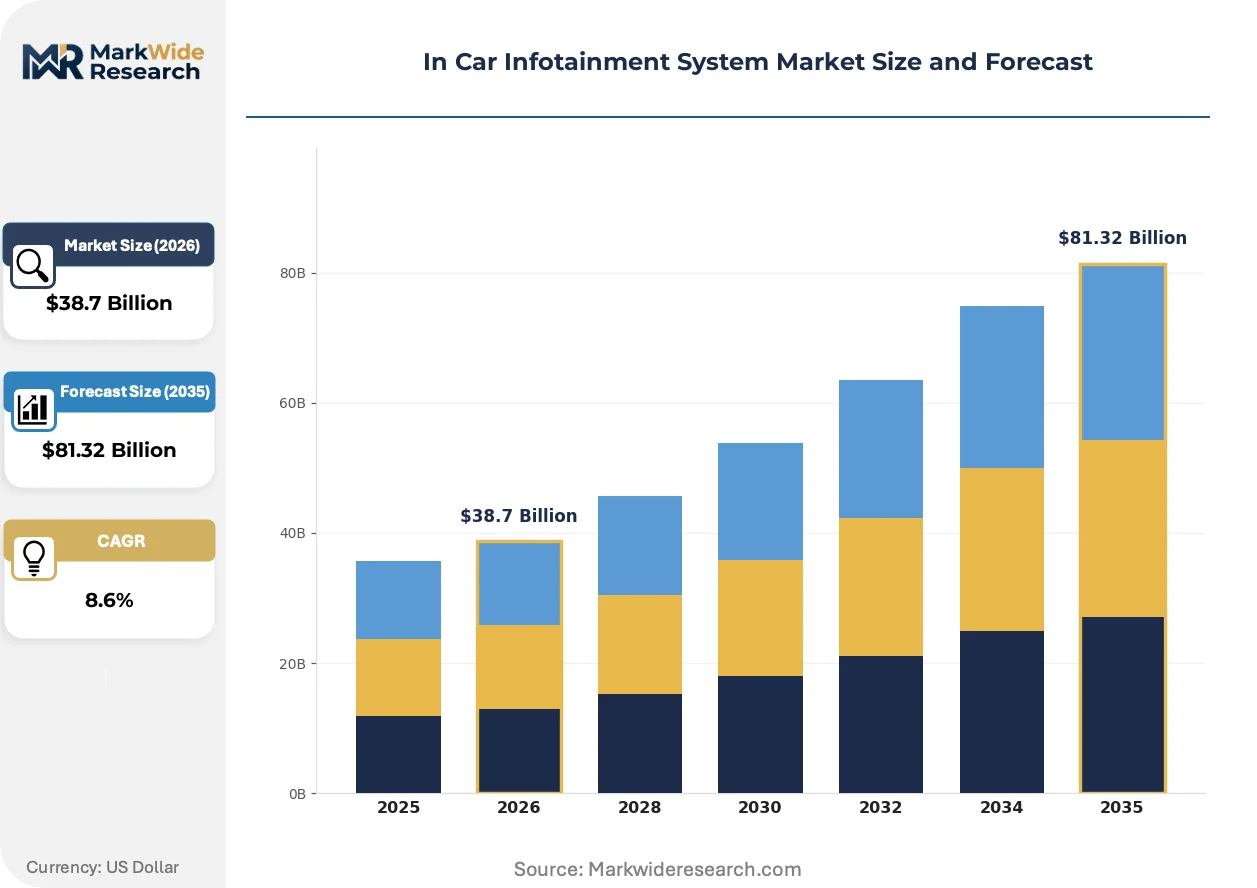
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Systems, Add-On Solutions, Display Audio, Head-Up Display Technology: Android Auto, Apple CarPlay, Bluetooth, Voice Recognition End User: OEMs, Aftermarket Providers, Fleet Management, Individual Consumers Installation: Factory Installed, Dealer Installed, DIY, Retrofitting |
| Companies Covered | Harman International, Panasonic Corporation, Robert Bosch GmbH, Continental AG, Denso Corporation, Alpine Electronics, Pioneer Corporation, Visteon Corporation, Aptiv PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Car Infotainment System Market Trends and Innovations
Voice-first human-machine interfaces and generative AI assistants are displacing touch-centric control paradigms as automakers compete on driver distraction metrics and premium cabin differentiation.
Generative AI copilots are converging with natural language processing engines to enable contextual dialogue about vehicle systems, navigation, and media selection. Luxury OEMs in Germany and Japan deploy these systems as trim-level differentiators. The technology is compressing traditional voice recognition licensing models toward consolidated platform providers.
REACH substance restrictions and RoHS amendments are tightening material compliance for display backlights and solder alloys in cockpit electronics. Component suppliers must document full material declarations through supply chain tiers. European OEMs are accelerating supplier consolidation to reduce audit burden exposure.
Fleet procurement of standardized infotainment configurations is displacing retail consumer choice as mobility-as-a-service operators specify durable, serviceable hardware over feature-rich premium systems. Rental and subscription vehicle providers in the United States now specify 10-year service life targets. This rotation compresses aftermarket accessory markets while elevating telematics integration requirements.
In Car Infotainment System Market Segmentation
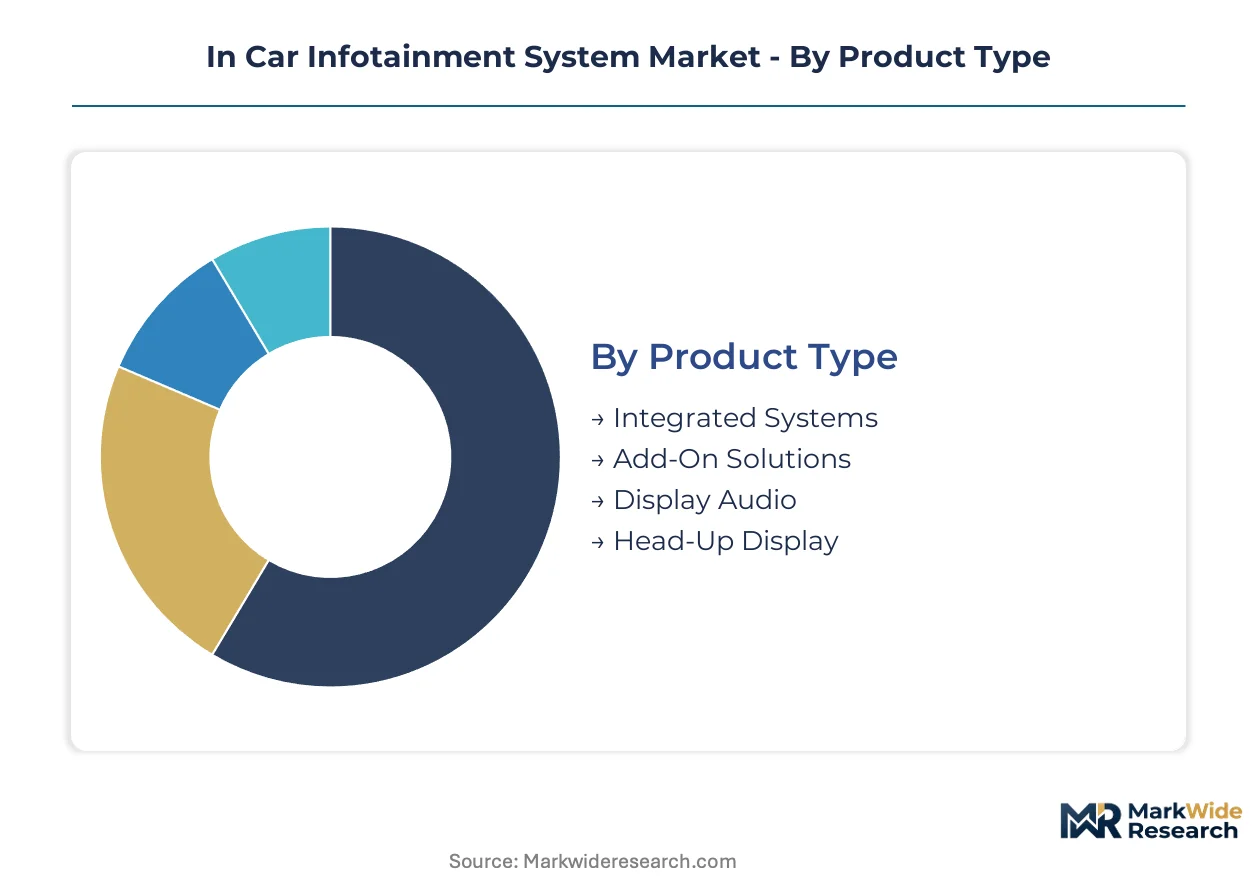
Segmentation in the in-car infotainment market reveals how hardware-software integration depth, installation authority, and connectivity standards reshape procurement patterns across vehicle lifecycles. Upgrade cycles vary dramatically between factory-embedded platforms with decade-long service horizons and aftermarket solutions facing compressed replacement intervals.
Product Type:
Replacement-cycle economics favor embedded platforms for new vehicle production while add-on solutions capture aging parc refresh demand.
- Integrated Systems:Factory-embedded hardware-software stacks with centralized domain controllers and automotive-grade Linux distributions. German and Japanese OEMs concentrate procurement here to secure long-term subscription revenue and OTA update control.
- Display Audio:Modular touchscreen units bridging embedded and aftermarket categories, typically 7-12 inch panels with smartphone mirroring as primary connectivity. Fleet operators in the United States specify these for standardized vehicle configurations across rental and subscription pools.
- Add-On Solutions:Portable or semi-integrated units for vehicle parc extension.
- Head-Up Display:Windshield-projection systems integrating navigation and ADAS alerts.
Volume placements concentrate in Integrated Systems; the faster expansion belongs to Display Audio.
Technology:
Connectivity standard adoption tracks smartphone ecosystem loyalty and voice interface maturation across premium and mass-market vehicle tiers.
- Voice Recognition:Natural language processing engines with contextual dialogue capabilities and driver distraction compliance. EU AI Act algorithmic transparency mandates are accelerating certified supplier consolidation for German luxury OEM deployments.
- Apple CarPlay:Proprietary smartphone mirroring protocol with iOS ecosystem integration. Consumer preference for familiar mobile interfaces is displacing embedded navigation revenue pools across North American and European markets.
- Android Auto:Google-developed mirroring standard with Android Automotive OS convergence.
- Bluetooth:Legacy wireless audio and telephony pairing protocol.
Deployment breadth favors Apple CarPlay; Voice Recognition climbs the fastest as automakers compete on cabin differentiation metrics.
End User:
Procurement authority determines specification complexity, with centralized fleet purchasing displacing individual consumer choice in mobility service segments.
- OEMs:Original equipment manufacturers controlling electrical architecture design and software lifecycle management. Stuttgart and Munich engineering clusters co-locate tier-one supplier R&D to accelerate prototype-to-production cycles for Level 2+ autonomous interfaces.
- Fleet Management:Mobility-as-a-service operators specifying durable, serviceable hardware over feature-rich premium systems. United States rental and subscription vehicle providers now mandate 10-year service life targets and standardized telematics integration.
- Aftermarket Providers:Independent installation channels for vehicle parc extension.
- Individual Consumers:Retail purchasers with preference for smartphone ecosystem continuity.
Revenue capture concentrates with OEMs; Fleet Management is gaining share fastest as mobility services expand vehicle procurement scale.
Installation:
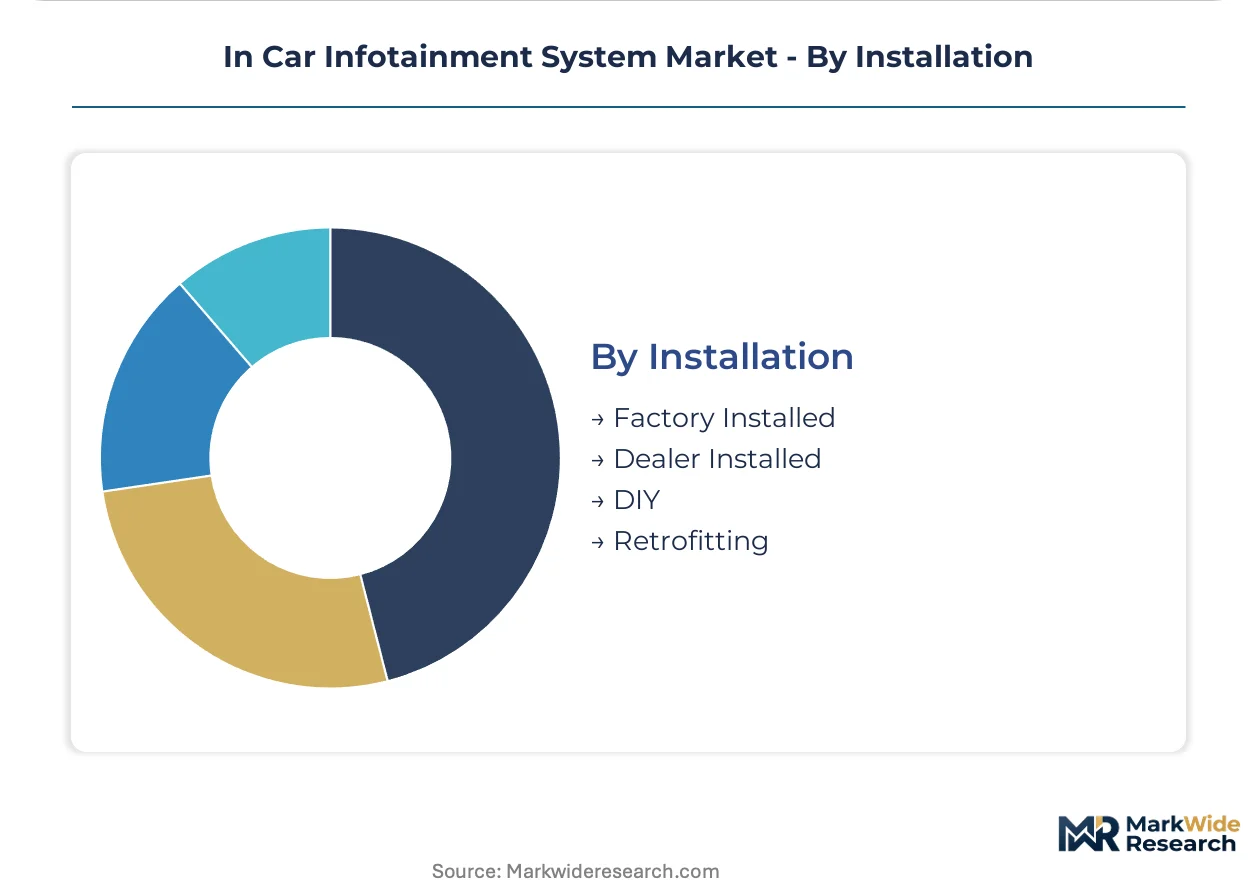
Installation channel selection reflects warranty preservation priorities and electrical architecture access constraints across vehicle age classes.
- Factory Installed:Assembly-line integration with OEM electrical architecture and thermal management validation. Temperature tolerances spanning minus 40 to 85 degrees Celsius require automotive-grade component qualification that filters non-compliant vendors from supply rosters.
- Retrofitting:Post-production hardware upgrades for zonal E/E architecture transitions. Legacy CAN bus compatibility requirements complicate wiring harness rationalization programs for 1990s-era powertrain network integration.
- Dealer Installed:Authorized channel installation preserving warranty coverage.
- DIY:Consumer self-installation with compressed margin profiles.
Volume concentration sits with Factory Installed; Retrofitting expands most quickly as zonal architecture transitions accelerate vehicle refresh demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, Japan, and the United States where tier-one suppliers co-locate engineering centers with automaker headquarters. Passenger vehicle OEMs in these markets are expanding embedded software budgets as regulatory compliance thresholds rise for connected cockpit platforms.
Germany
Stuttgart and Munich host concentrated R&D clusters for Harman, Bosch, and Continental, accelerating prototype-to-production cycles for Level 2+ autonomous interfaces. The EU AI Act mandates algorithmic transparency certification for voice recognition and driver monitoring systems, filtering non-compliant vendors from OEM supply rosters. Bavaria's engineering corridor anchors premium audio and display module development for luxury German automakers.
Japan
Tokyo and Nagoya metropolitan areas concentrate Denso and Panasonic manufacturing scale across multiple assembly plants serving domestic and North American vehicle production. METI's data trust framework enables cross-industry data sharing protocols for connected vehicles, allowing mobility service providers to monetize aggregated driver behavior analytics. The Kanto region specializes in automotive-grade semiconductor packaging and thermal management validation.
United States
Michigan and California engineering centers focus on centralized computing platform development for software-defined vehicle architectures. NHTSA advisory guidelines on driver distraction directly influence display placement, menu depth, and voice command latency requirements across all vehicles sold in the American market. Detroit-area suppliers manage electrical architecture design for long-term subscription revenue and OTA update control.
China
Shanghai and Beijing corridors concentrate domestic cockpit electronics procurement for local OEMs expanding electric vehicle production. MIIT enforces data localization standards for connected vehicle platforms, creating divergent architecture requirements for global suppliers serving multiple geographies. Yangtze River Delta manufacturing hubs specialize in display audio modules and smartphone mirroring integration.
India
Chennai and Pune assembly corridors attract tier-one suppliers through PLI scheme allocations for automotive electronics and semiconductor packaging. Domestic manufacturing incentives reposition India as a cost-competitive sourcing base for cockpit domain controllers and connectivity modules. Tamil Nadu's automotive cluster concentrates on entry-level integrated systems for mass-market vehicle platforms.
In Car Infotainment System Market Competitive Landscape
German producers anchor one tier; Japanese specialists hold manufacturing scale advantages in display and thermal management components. The vendor structure concentrates around tier-one automotive electronics suppliers with captive semiconductor sourcing relationships and embedded software certification expertise. Three archetypes dominate: diversified industrial conglomerates with automotive divisions, dedicated cockpit electronics specialists, and consumer electronics firms with automotive-grade product lines. Competitive moves center on strategic partnerships for AI middleware development and geographic expansion into India through domestic manufacturing incentives.
Within the diversified conglomerate tier, Robert Bosch GmbH exemplifies embedded software stack differentiation through functional safety certification for autonomous driving interfaces. Panasonic Corporation occupies a position anchored by multi-plant manufacturing scale across Japanese and North American production corridors. Harman International sits within the premium-tier specialist category, leveraging Samsung-backed semiconductor sourcing to sustain in-house production of audio and display modules for luxury vehicle programs.
| Leading Market Players |
|---|
| Harman International |
| Panasonic Corporation |
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Alpine Electronics |
| Pioneer Corporation |
| Visteon Corporation |
| Aptiv PLC |
| Others |
Pricing and Supply Chain Analysis
Automotive-grade semiconductor wafer costs cascade through cockpit domain controller production into three-tier pricing structure across premium, standard, and economy levels, with EU AI Act certification tiers filtering non-compliant vendors from OEM supply rosters and compressing margin capture for unqualified component suppliers.
Pricing Analysis
Short lead-time premiums for 7nm automotive SoCs command substantial markups over standard allocation contracts, while spot inventory liquidation creates downward pressure in display audio modules. Pricing stratifies across premium, standard, and economy tiers based on ASIL-D functional safety certification and automotive Linux distribution licensing depth. Cost compression in entry-level integrated systems is intensifying because smartphone mirroring substitution erodes embedded navigation value pools. Fleet management buyers exhibit highest price sensitivity due to standardized 10-year service life mandates, while luxury German OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for cockpit domain controllers mandate multi-supplier qualification across Taiwanese foundries, South Korean memory fabricators, and Japanese automotive-grade packaging facilities. Raw material dependencies center on silicon wafers, rare-earth display phosphors, and RoHS-compliant solder alloys. Single-source vulnerability concentrates in 5nm automotive SoC foundry capacity captive to consumer electronics demand cycles. Distribution runs through tier-one supplier direct-OEM channels with co-located engineering centers in Stuttgart, Munich, and Detroit accelerating prototype-to-production cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The In Car Infotainment System Market operates as a cost-of-compliance arena where UN ECE R155 cybersecurity certification creates a barrier-to-entry moat filtering sub-scale component vendors from OEM supply rosters.
For Market Incumbents: Hedge against smartphone mirroring substitution by deepening embedded software subscription revenue streams and securing captive semiconductor sourcing relationships. Consolidate functional safety engineering talent pools through targeted acquisition of ISO 26262 ASIL-D certified development teams. Priority lever rests on backward integration into automotive-grade Linux distribution maintenance to sustain OTA update control across vehicle lifecycles. For New Entrants and Emerging Players: Launch via fleet management procurement channels targeting standardized display audio configurations for United States rental and subscription vehicle pools. White-space opportunity concentrates in India PLI scheme corridors where domestic manufacturing incentives attract tier-one supplier co-location. Most penetrable segment spans entry-level integrated systems for mass-market electric vehicle platforms with simplified electrical architecture requirements. For Investors and Strategic Acquirers: EU AI Act algorithmic transparency enforcement is the leading indicator that certified AI middleware suppliers will command sustained valuation premiums over generic voice recognition vendors. Long-term viability favors acquisition targets with embedded software certification expertise and automotive-grade thermal management validation capabilities. Signal to watch centers on OEM consolidation of cockpit electronics architectures around centralized computing platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Centralized computing platforms elevate subscription revenue capture for OEMs controlling electrical architecture design. |
| Battery Supply Agreement | Electric vehicle production scale in Germany and China drives cockpit electronics procurement for dedicated EV platforms. |
| Geographic Manufacturing Footprint | PLI scheme allocations in Chennai and Pune reposition India as cost-competitive sourcing base for domain controllers. |
| Platform Standardization | Fleet operators specify durable hardware configurations displacing retail consumer choice in mobility service segments. |
| Charging Infrastructure Partnership | Telematics integration requirements expand as charging network operators monetize aggregated driver behavior analytics. |
Research Methodology
Document review covered SEC 10-K filings from tier-one automotive electronics suppliers, EU regulatory filings for AI Act compliance, and vehicle production databases from IHS Markit, complemented by interviews with OEM platform engineers, tier-one supplier procurement leads, aftermarket distribution channel heads, and dealership operations managers. Secondary validation drew from automotive semiconductor customs data, NHTSA driver distraction guideline documentation, and MIIT connected vehicle platform filings. Bottom-up segment sizing triangulated against top-down market value reconstruction across the analysis window.
Unit shipment and revenue outputs derived from modeled projections across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions throughout the forecast period. CAGRs were computed from fitted growth curves incorporating OTA update penetration rates, voice recognition interface adoption trajectories, and fleet management procurement scale expansion. Industry-specific inputs included automotive-grade Linux distribution deployment timelines and UN ECE R155 certification completion schedules.
The model assumes a particular technology adoption path for generative AI copilot integration; alternative pathways for contextual dialogue engine deployment would alter the outlook for natural language processing licensing consolidation. Deviation in foundry capacity allocation for automotive SoCs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
GPS Tracker Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
Video Telematics Market
Telematics and Infotainment
APAC Internet of Cars Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Telematics Control Unit Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
North America Automotive Navigation System Market
Telematics and Infotainment
Global Automotive Remote Diagnostics Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
Automotive Wi-Fi Router Market