
 Europe Electric Light Commercial Vehicles Market | 2026-2036
Europe Electric Light Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Light Commercial Vehicles Market Foresight
The EU Green Deal's 90% transport emission reduction target for 2040 is expanding the addressable fleet base for electric light commercial vehicles across European Union member states. Renault Group leverages its historic dominance in compact van segments to anchor electrified offerings in French and Southern European markets. Stellantis N.V. sustains multi-brand manufacturing scale across Italian and Polish assembly plants. Mercedes-Benz Group AG differentiates through premium battery thermal management and extended-range configurations for German fleet operators.
Europe electric light commercial vehicles are battery-electric or fuel-cell-powered goods transport vehicles with gross vehicle weight ratings typically below 3.5 tonnes, engineered for urban duty cycles with frequent stop-start operation and regenerative braking energy recovery. Their primary commercial purpose centers on zero-emission last-mile logistics, tradespeople transport, and municipal service fleets operating within expanding low-emission zones. Vans occupy the dominant volume position due to standardized cargo volumes matching parcel carrier specifications, while solid-state battery configurations represent the fastest-advancing technology segment as energy density improvements promise extended range without payload compromise. E-commerce end users command the most concentrated margin pool as platform-driven delivery density justifies dedicated fleet electrification investments.
EMA transport emission benchmarks, CE marking requirements for electromagnetic compatibility, and the EU AI Act's pending vehicle autonomy provisions collectively shape product certification timelines and software architecture obligations for manufacturers serving European markets. REACH chemical restrictions further constrain battery material sourcing and recycling pathway documentation. Fleet operators and OEM program managers must monitor battery passport implementation timelines and charging infrastructure interoperability standards as decisive variables for total cost of ownership calculations and resale value retention.
Market Dynamics
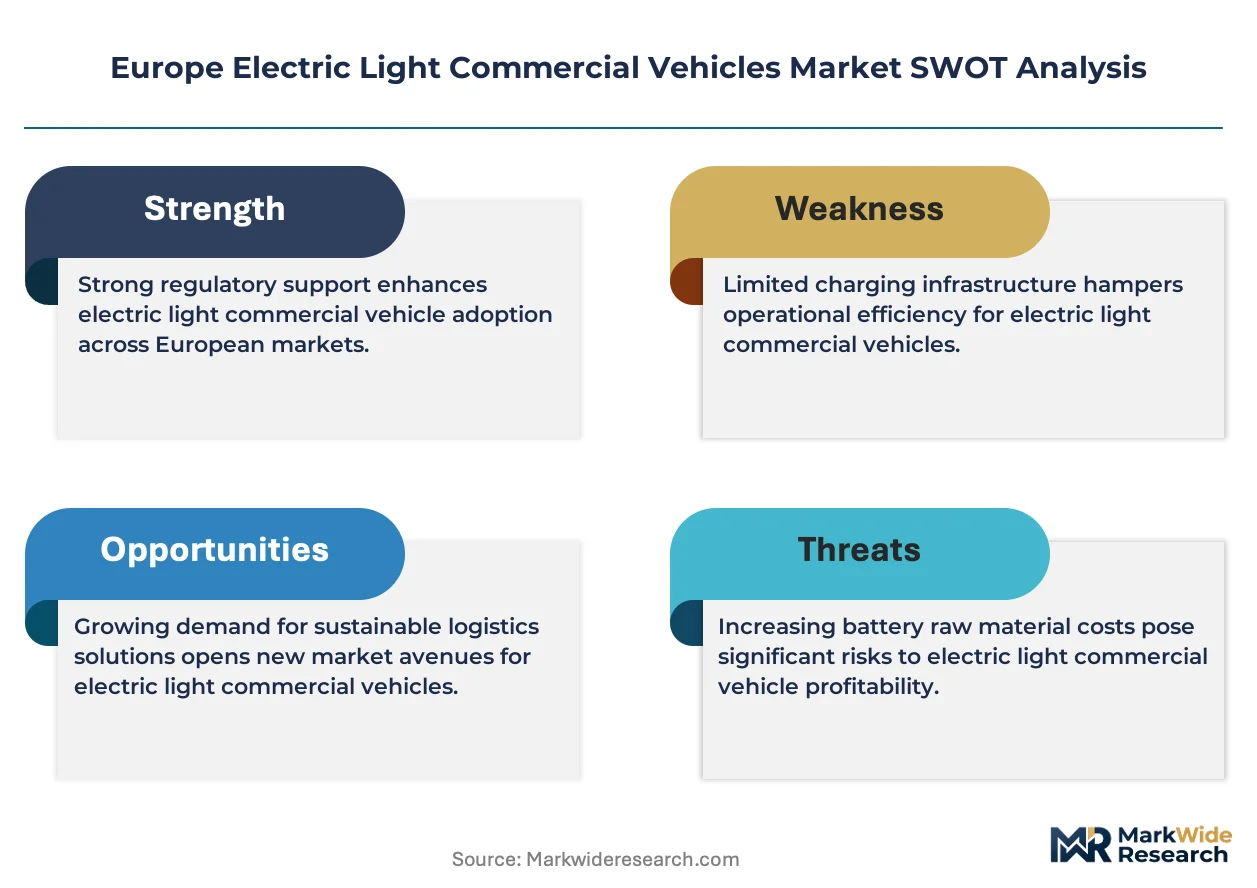
The EU Green Deal's transport emission reduction mandate is compressing fleet replacement timelines across European logistics operators, forcing accelerated electrification of urban delivery vehicles before total cost of ownership parity with diesel alternatives is achieved.
Growth Catalysts
- Urban Low-Emission Zones:Municipal LEZ expansions in London, Paris, and Amsterdam are prohibiting diesel van access to central business districts, compelling fleet operators to electrify or face route exclusions.
- Battery Passport Mandate:The EU Battery Regulation's traceability requirements are standardizing recycling infrastructure investments, reducing second-life battery uncertainty and improving residual value calculations for fleet financiers.
- Last-Mile Density:Parcel carrier hub consolidation around Rhine-Ruhr and Randstad distribution centers is concentrating electrified fleet deployment where charging infrastructure economics prove most favorable.
Market Restraints
- Lithium Supply Concentration:European cell manufacturers remain dependent on processed lithium hydroxide from Chilean and Australian refining operations, exposing production schedules to maritime logistics volatility.
- Thermal Management Cost Structure:The F-Gas Regulation's phase-down of hydrofluorocarbon refrigerants is forcing redesign of battery cooling systems with alternative heat transfer fluids at 15-25% cost premiums.
- Grid Connection Queues:Distribution network operators in Germany and the Netherlands are extending commercial charging installation timelines to 18-24 months due to transformer capacity constraints in industrial zones.
Strategic Opportunities
- Solid-State Battery Convergence:Sulfide-based electrolyte architectures promise 40% energy density improvements over lithium-ion, enabling 400km range in compact van form factors without payload sacrifice.
- Vehicle-to-Grid Integration:Bidirectional charging protocols are creating new revenue streams for fleet operators through frequency regulation services in Nordic and Benelux electricity markets.
- Polish Manufacturing Scale:Stellantis and emerging OEMs are expanding Silesian assembly capacity to serve Central European markets where electrification penetration currently lags Western benchmarks by 3-5 years.
Industry Challenges
- High-Voltage Technician Scarcity:Fleet maintenance departments face acute shortages of IMI Level 3 certified technicians capable of servicing 400V+ battery systems and power electronics.
- CE Marking Complexity:Electromagnetic compatibility testing for vehicle autonomy sensors under pending EU AI Act provisions is extending homologation timelines by 6-9 months for Level 2+ ADAS configurations.
- Depreciation Modeling Uncertainty:Residual value forecasting for battery-electric vans lacks standardized methodology, complicating lease rate-setting and fleet remarketing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Light Commercial Vehicles Market |
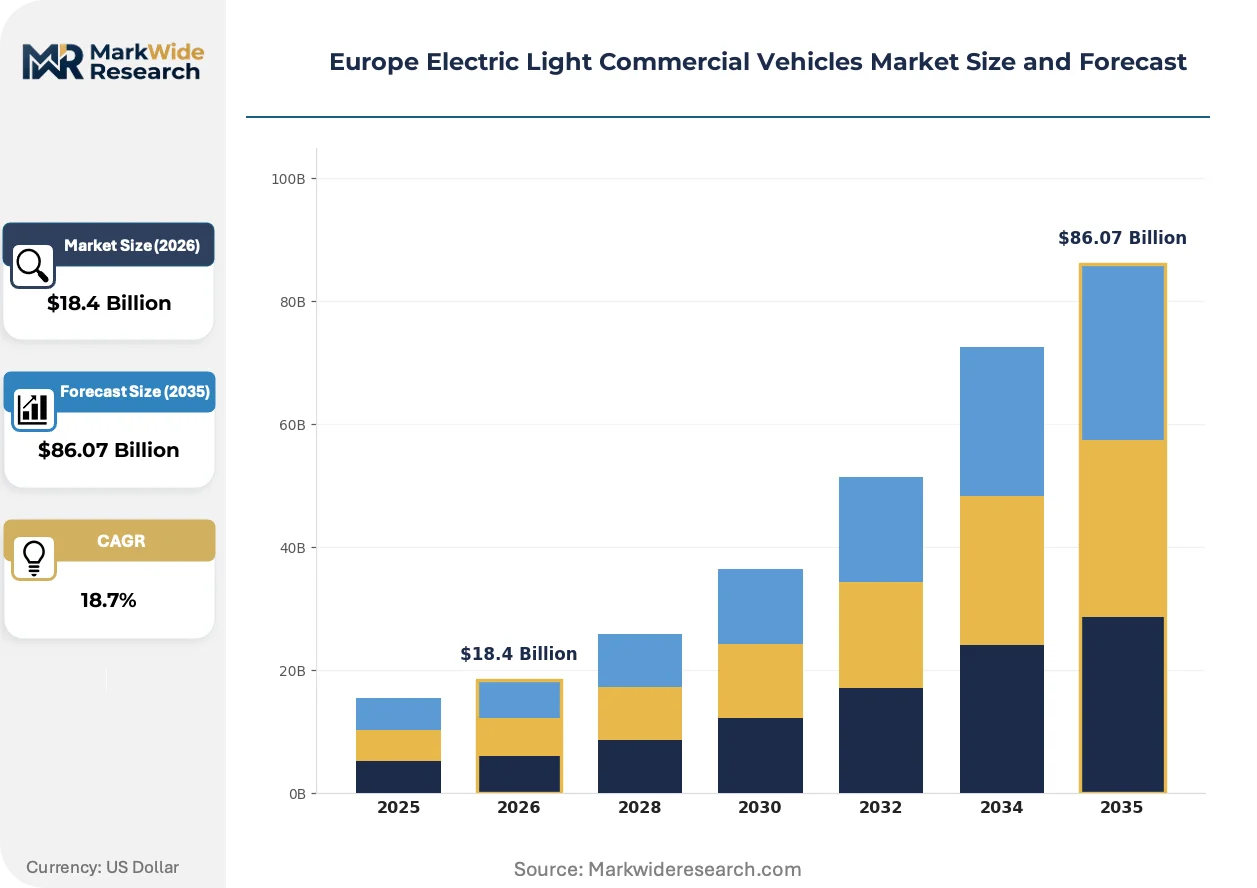
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $86.07 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Vans, Pickups, Chassis Cabs, Micro Vehicles Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Solid-State Charging Infrastructure: Fast Charging, Standard Charging, Wireless Charging, Battery Swap End User: E-Commerce, Logistics, Public Transport, Delivery Services |
| Companies Covered | Volkswagen AG, Peugeot S.A., Stellantis N.V., Iveco Group N.V., Toyota Motor Corporation, Ford Motor Company, Mercedes-Benz Group AG, Volvo Trucks, Renault Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Light Commercial Vehicles Market Shifts & Advancements
Three interconnected developments are restructuring European electric van competitiveness: thermal management architecture, regulatory compliance automation, and procurement model transformation toward energy-as-a-service frameworks.
Integrated heat pump systems are automating cabin and battery thermal conditioning through single-circuit refrigerant architectures. Parcel carriers operating high-frequency stop-start routes in Copenhagen and Stockholm are specifying these systems to preserve winter range. The technology is automating fleet energy management by eliminating separate PTC heater components and reducing HVAC-related range degradation from 30% to under 15% in sub-zero conditions.
The EU AI Act's risk-based classification for autonomous vehicle functions is mandating algorithmic transparency documentation for lane-keeping and emergency braking systems. Tier-1 suppliers are restructuring software development workflows to accommodate conformity assessment body oversight. German van manufacturers face the most compressed compliance timelines as their Level 2+ offerings trigger the Act's "high-risk" system requirements before 2026 enforcement dates.
Fleet operators are unbundling vehicle acquisition from energy supply through charging-as-a-service contracts with infrastructure providers. This procurement evolution transfers capex burden to specialized operators while guaranteeing uptime through service-level agreements. The shift is most advanced in the Netherlands, where LeasePlan and Athlon have structured full-electric fleet packages incorporating home, depot, and public charging access under single per-kilometer rates.
Europe Electric Light Commercial Vehicles Market Segmentation
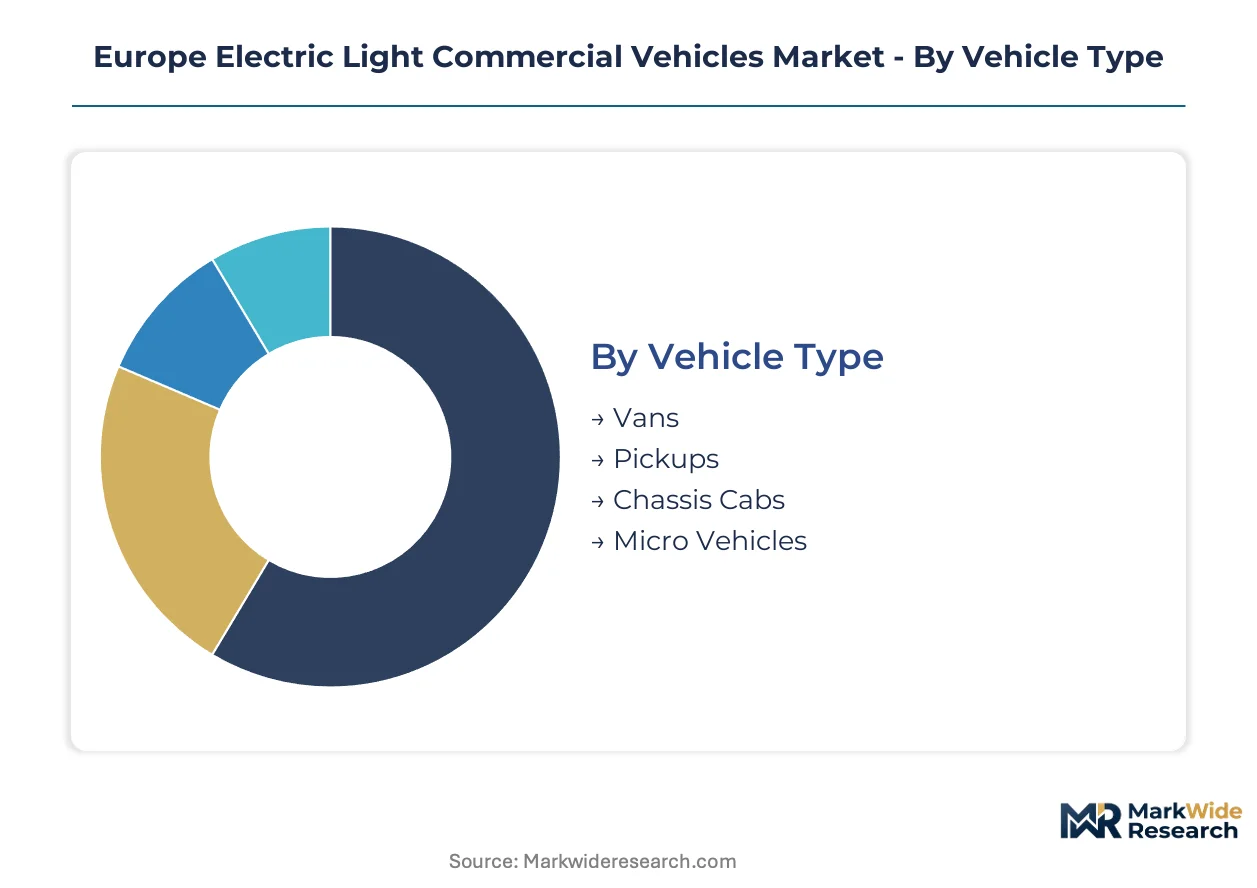
Segmentation in Europe's electric light commercial vehicle market exposes divergent total cost of ownership calculations across duty cycles. Fleet operators select configurations based on route density, dwell time access to charging, and payload preservation requirements.
Vehicle Type:
Procurement patterns split between standardized cargo volume requirements and specialized upfit applications.
- Vans:Enclosed cargo bodies with 6-15 cubic meter capacities dominate parcel carrier specifications across German and Dutch logistics corridors. Rhine-Ruhr distribution hubs specify these for standardized pallet loading and automated sortation compatibility.
- Pickups:Open-bed configurations serve tradespeople and municipal maintenance fleets requiring irregular cargo dimensions. French construction sectors favor these for tool transport flexibility.
- Chassis Cabs:Chassis Cabs: Cab-forward platforms accept custom bodywork for refrigerated transport and specialized municipal equipment. Belgian food distributors specify these for multi-temperature zone configurations.
- Micro Vehicles:Sub-3.5 tonne quadracycles and compact delivery vehicles navigate narrow historic city centers. Italian urban postal services deploy these in Florence and Siena restricted zones.
Volume sits with Vans; growth tilts toward Micro Vehicles.
Battery Type:
Energy density thresholds determine route feasibility and payload trade-offs for fleet planners.
- Lithium-Ion:NMC and LFP chemistries deliver 200-300km real-world range in compact van footprints. Polish assembly plants source these cells for Stellantis and emerging OEM production serving Central European markets.
- Solid-State:Sulfide electrolyte architectures promise 40% energy density gains over conventional lithium-ion. German premium manufacturers are accelerating validation programs for extended-range configurations.
- Lead-Acid:Lead-Acid: Mature chemistry persists in price-sensitive micro vehicle segments and secondary auxiliary power applications. Limited penetration in primary traction systems due to weight penalties.
- Nickel-Metal Hydride:Nickel-Metal Hydride: Legacy hybrid technology transitioning out of mainstream commercial applications. Remains in limited service for specific fleet retrofit programs.
Deployment concentrates in Lithium-Ion; technology investment flows toward Solid-State.
Charging Infrastructure:
Charging modality selection reflects real estate access, route predictability, and capital allocation preferences.
- Fast Charging:150kW+ DC infrastructure enables mid-route energy replenishment for time-critical delivery operations. Netherlands corridor deployments prioritize these for intercity logistics.
- Standard Charging:Standard Charging: AC overnight depot charging dominates predictable return-to-base fleet economics. German municipal operators standardize on 22kW three-phase installations.
- Wireless Charging:Wireless Charging: Inductive pad systems eliminate connector wear in high-frequency stop-start operations. Swedish parcel hubs pilot these for automated guided vehicle integration.
- Battery Swap:Battery Swap: Station-based exchange systems minimize vehicle downtime for continuous-shift operations. Limited European deployment compared to Asian markets.
Capital deployment favors Standard Charging; pilot activity concentrates in Fast Charging.
End User:
End-use economics vary sharply between platform-driven volume density and contracted service obligations.
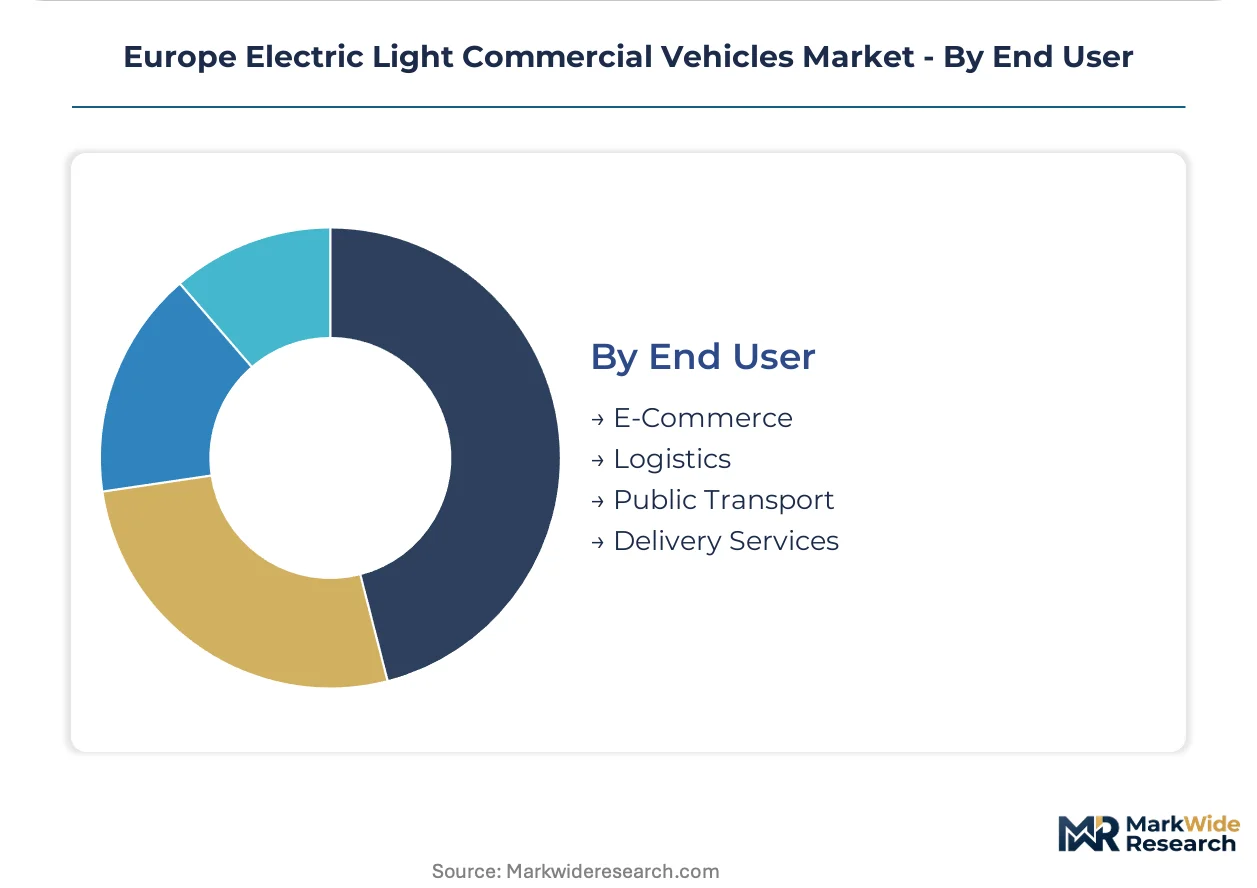
- E-Commerce:Platform logistics operators command dedicated fleet electrification budgets based on delivery density algorithms. Amazon and regional equivalents anchor procurement in Randstad and Paris basin corridors.
- Logistics:Logistics: Third-party freight operators balance asset utilization across mixed diesel-electric fleets. DHL and comparable integrators phase electrification through hub-and-spoke route optimization.
- Public Transport:Public Transport: Municipal authorities specify passenger-configured variants for paratransit and demand-responsive services. London and Amsterdam authorities mandate zero-emission fleet transitions.
- Delivery Services:Delivery Services: Food and express courier operators prioritize compact vehicle formats with rapid turnaround. Subscriptions and quick-commerce platforms drive urban micro vehicle demand.
Contract volume concentrates in Logistics; margin expansion tilts toward E-Commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan cluster anchors European electric van procurement intensity, with distribution hubs in Düsseldorf and Cologne commanding dedicated fleet electrification budgets from parcel carriers and third-party logistics operators.
Germany
Fleet operators in North Rhine-Westphalia and Bavaria are accelerating battery-electric van deployment ahead of the EU Green Deal's 2040 transport emission targets. The KBA enforces stringent type-approval protocols for 400V+ high-voltage systems. Stuttgart-based Mercedes-Benz Group AG and Munich-area manufacturing clusters are validating extended-range configurations for premium fleet segments.
France
Île-de-France logistics corridors and Lyon-Rhône distribution networks are mandating zero-emission vehicle access to expanding low-emission zones in Paris and regional centers. ANSM oversees chemical safety documentation for battery materials under REACH frameworks. Renault Group anchors compact van electrification from its historic dominance in French and Southern European markets.
Netherlands
Randstad metropolitan logistics density—spanning Amsterdam, Rotterdam, and Utrecht—is concentrating charging infrastructure investment where depot economics prove most favorable. The Dutch Authority for Consumers and Markets regulates charging interoperability standards. LeasePlan and Athlon have structured full-electric fleet packages incorporating home, depot, and public charging under single per-kilometer rates.
Italy
Lombardy and Piedmont manufacturing clusters are expanding Stellantis assembly capacity to serve Central European markets where electrification penetration lags Western benchmarks. The Ministry of Infrastructure and Transport coordinates with EU Battery Regulation implementation timelines. Turin-based engineering centers are optimizing thermal management architectures for Mediterranean climate duty cycles.
Poland
Silesian assembly plants are scaling production to capture demand from Central European fleet operators seeking cost-optimized electrification pathways. The Polish Office of Competition and Consumer Protection monitors state aid compliance for green transition investments. Emerging OEMs alongside Stellantis are establishing supply chain corridors linking Warsaw logistics hubs to Western European distribution networks.
Europe Electric Light Commercial Vehicles Market Competitive Landscape
The competitive structure tilts toward diversified automotive conglomerates with multi-brand manufacturing scale and historic van segment expertise. Consolidation around integrated powertrain and thermal management capabilities is compressing margins for standalone entrants. Two dominant archetypes occupy the landscape: legacy European OEMs with established fleet relationships, and diversified global automakers leveraging cross-segment electrification platforms. Capacity expansion across Polish and Italian assembly plants and strategic partnerships for solid-state battery sourcing represent the primary competitive moves reshaping positioning.
Among diversified European automotive groups, Stellantis N.V. and Renault Group exemplify the multi-brand scale archetype, while Mercedes-Benz Group AG occupies the premium-tier differentiation position. Volkswagen AG represents the cross-segment platform leverage model, applying battery-electric architectures across passenger and commercial vehicle divisions. These three entities anchor the competitive structure through distinct geographic and segment positioning strategies.
| Leading Market Players |
|---|
| Volkswagen AG |
| Peugeot S.A. |
| Stellantis N.V. |
| Iveco Group N.V. |
| Toyota Motor Corporation |
| Ford Motor Company |
| Mercedes-Benz Group AG |
| Volvo Trucks |
| Renault Group |
| Others |
Supply & Pricing Matrix
Sovereign-backed battery producers and private-equity-rolled-up charging infrastructure operators anchor supply-side ownership patterns, translating state subsidy access and consolidated depot-network scale into pricing discipline across fleet procurement negotiations.
Pricing Analysis
Outcome-based pricing tied to vehicle uptime and energy-per-kilometer guarantees anchors fleet procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates Mercedes-Benz thermal management configurations from Stellantis volume platforms and emerging Polish-assembled entrants. Cost compression in economy-tier lithium-ion configurations is intensifying because cell manufacturers are passing through refined lithium hydroxide volatility. Third-party logistics operators exhibit highest price sensitivity due to mixed-fleet asset utilization pressures, while e-commerce platform operators accept premium positioning for dedicated electrification budgets.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Düsseldorf coordinate hub-and-spoke patterns linking Polish assembly plants to Western European fleet operators. Cell manufacturing concentrates in Hungary, Poland, and Germany, drawing from processed lithium hydroxide anchored in Chilean and Australian refining operations. Nickel, cobalt, and rare earth permanent magnet dependencies create single-source vulnerability for power electronics and motor assemblies. Distribution runs through Rhine-Ruhr logistics corridors where parcel carrier hub consolidation optimizes charging infrastructure economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into battery cell production and captive charging infrastructure represents the decisive upstream lever reshaping competitive economics, as OEMs and fleet operators seek to capture margin pools currently absorbed by specialized suppliers.
For Market Incumbents: Acquire solid-state battery validation capabilities and certified high-voltage technician training networks. Stellantis and Renault must defend against emerging Polish-assembled entrants by securing sulfide electrolyte sourcing partnerships. Backward integration into thermal management component production preserves margin as F-Gas Regulation compliance costs escalate. For New Entrants and Emerging Players: The price-point gap between premium German thermal management configurations and economy-tier Polish volume production opens white-space in mid-range fleet specifications. Central European municipal operators present most penetrable demand, lagging Western electrification benchmarks. Direct fleet-as-a-service contracting bypasses established dealership channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed Polish component suppliers and stranded Italian thermal management engineering assets amid consolidation pressure. Five-to-ten-year viability hinges on battery passport compliance infrastructure and residual value modeling standardization. Watch for EU AI Act enforcement timelines as inflection indicator for autonomous vehicle software valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell sourcing contracts with Hungarian or Polish manufacturers secure capacity for Stellantis and emerging OEM ramp-ups. |
| Charging Infrastructure Partnership | Depot-network alliances with LeasePlan or Athlon transfer capex burden and guarantee uptime through service-level agreements. |
| Software-Defined Vehicle Investment | EU AI Act compliance for Level 2+ ADAS configurations requires algorithmic transparency documentation and conformity assessment body oversight. |
| Geographic Manufacturing Footprint | Silesian assembly expansion captures Central European demand where electrification penetration trails Western benchmarks. |
| Platform Standardization | Cross-segment battery-electric architectures across passenger and commercial divisions reduce Volkswagen AG development costs. |
Research Methodology
Vehicle production databases, EU regulatory filings, and charging infrastructure deployment records formed the secondary backbone. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations directors, and charging infrastructure providers were cross-referenced against customs data and IHS Markit registration statistics. Bottom-up fleet deployment modeling and top-down market sizing were triangulated to reconcile volume estimates.
Historical trendline analysis of van segment electrification rates informed projection frameworks across the analysis window. Segmentation dimensions included vehicle class, battery chemistry, charging modality, and end-use vertical. CAGRs were derived from logistic diffusion curves fitted to early-adopter fleet penetration patterns. Solid-state battery commercialization timelines and EU Battery Regulation implementation schedules served as scenario variables.
Inputs from KBA type-approval databases and ANSM chemical safety documentation were available through the study window; gaps in second-life battery residual value transaction data introduce uncertainty bands around total cost of ownership calculations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
France E-Bike Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
Lawn Mower Battery Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market
Electric Vehicles
Latin America Electric Bus Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
E-Bike Accessories Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market