
 Vehicle to Vehicle (V2V) Communication Market | 2026-2036
Vehicle to Vehicle (V2V) Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle to Vehicle (V2V) Communication Market Intelligence
Software-defined feature updates for safety and traffic management are shifting the V2V business model from a one-time hardware sale to recurring revenue streams. Qualcomm Technologies, Inc. leverages its leadership in cellular chipsets to dominate the C-V2X space. Autotalks Ltd. competes by offering hybrid DSRC and C-V2X solutions for deployment flexibility. Meanwhile, automakers like General Motors Company integrate these systems to enhance vehicle safety ratings and offer premium connectivity services.
Vehicle to Vehicle (V2V) communication enables the direct, wireless exchange of data between nearby vehicles. These systems operate using standards like IEEE 802.11p for DSRC or 3GPP specifications for C-V2X, facilitating low-latency transmission of information about speed, position, and braking. The technology landscape is transitioning, with Cellular V2X (C-V2X) gaining ground over the established Dedicated Short Range Communication (DSRC) due to its broader network compatibility. Within applications, safety notifications represent the foundational use case, while traffic management systems are emerging as a key growth area.
Regulatory mandates are critical for market development, with bodies like the US Federal Communications Commission (FCC) allocating spectrum for V2X services. In Europe, standards from the European Telecommunications Standards Institute (ETSI) and CE marking requirements govern interoperability. China's Ministry of Industry and Information Technology (MIIT) actively promotes C-V2X deployment as part of its national connected vehicle strategy. Stakeholders must now decide whether to commit to existing infrastructure or pivot entirely to the more versatile but network-dependent C-V2X standard.
Market Dynamics
The technological transition from Dedicated Short Range Communication (DSRC) to Cellular V2X (C-V2X) is the central force shaping the market. This shift dictates infrastructure investment, component design, and strategic partnerships across the automotive ecosystem, forcing stakeholders to choose between competing standards.
Growth Catalysts
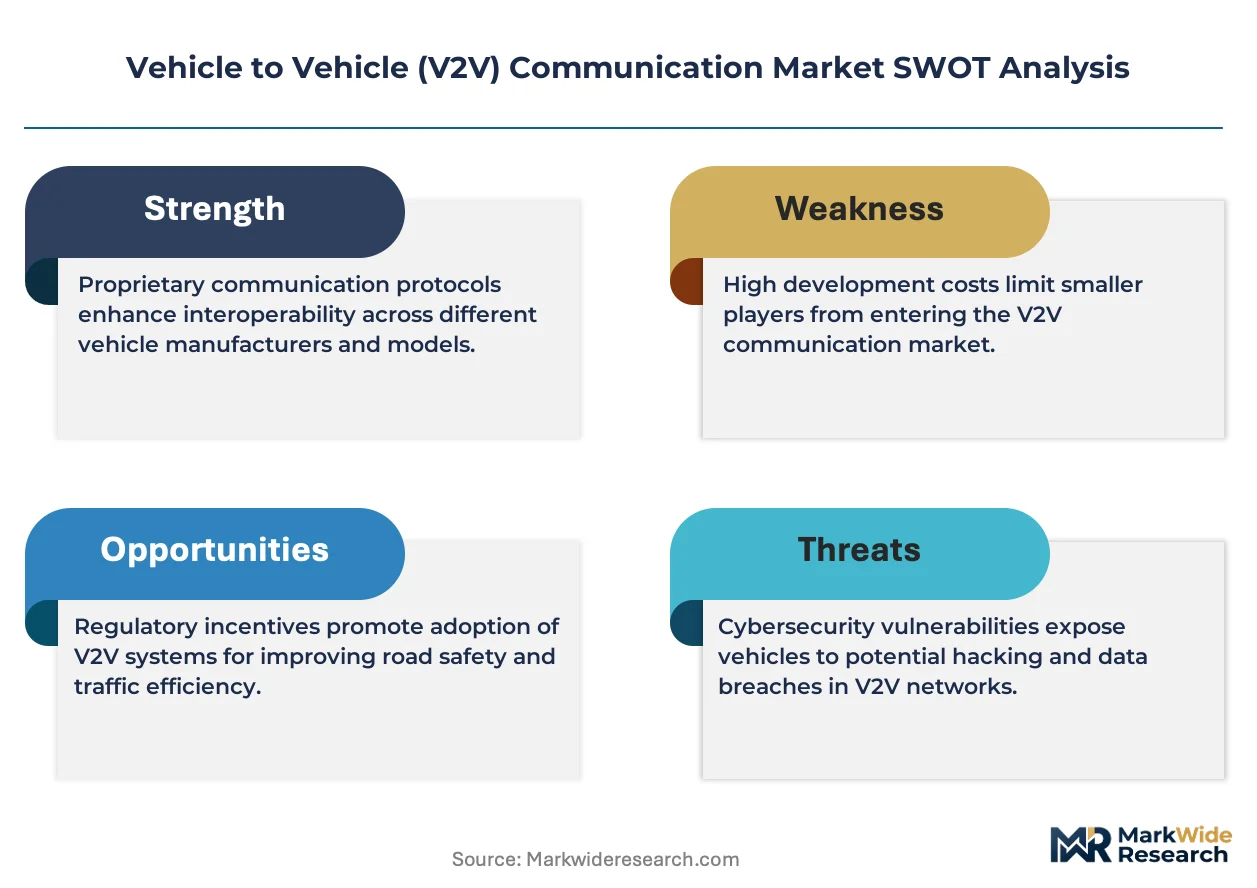
- Regulatory Mandates:Policies from China's MIIT and spectrum allocation by the US FCC are compelling automakers to integrate C-V2X technology, creating a stable demand floor.
- Commercial Fleet Economics:Fleet operators adopt V2V to reduce fuel costs through platooning and lower insurance rates via enhanced safety.
- 5G Network Expansion:The growing availability of 5G infrastructure enables advanced, low-latency C-V2X applications beyond basic safety messaging.
Market Restraints
- High Deployment Cost:Significant capital is needed to equip vehicles and build out the necessary roadside unit infrastructure, slowing mass adoption.
- Standards Conflict:The ongoing competition between DSRC and C-V2X technologies creates investment uncertainty, delaying large-scale infrastructure commitments.
- Interoperability Hurdles:A lack of uniform communication protocols across different automakers and regions limits the technology's network effect and overall utility.
Strategic Opportunities
- Data Monetization Services:Anonymized V2V data can be packaged for traffic analysis services, predictive maintenance, and usage-based insurance products.
- Smart City Integration:Expanding to a full V2X ecosystem allows for integration with traffic signals and public transit for urban mobility management.
- Emerging Market Leapfrogging:Developing economies can bypass legacy DSRC infrastructure, deploying C-V2X directly as part of new intelligent transport systems.
Industry Challenges
- Cybersecurity and Data Privacy:Securing vehicle networks against malicious attacks and ensuring the privacy of transmitted data are persistent operational hurdles requiring constant vigilance and software updates.
- Integration with Legacy Systems:The complexity of integrating advanced V2V units with the diverse and often outdated electronic architectures of vehicles already on the road slows down market penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle to Vehicle (V2V) Communication Market |
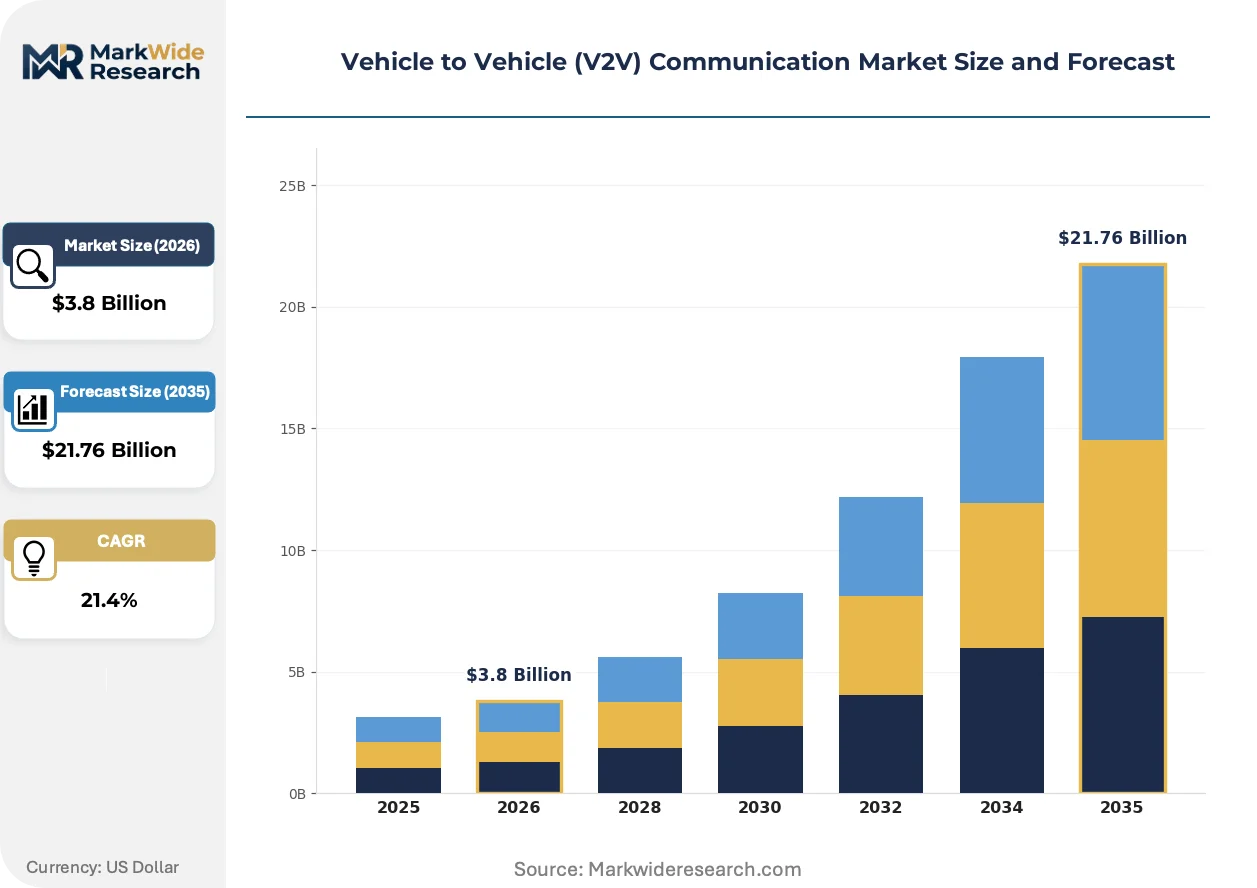
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $21.76 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Dedicated Short Range Communication, Cellular V2X, Wi-Fi Direct, Bluetooth Application: Driver Assistance, Traffic Management, Parking Assistance, Safety Notifications End User: OEMs, Fleet Operators, Public Transport, Insurance Companies Deployment: On-premise, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | Qualcomm Technologies, Inc., Autotalks Ltd., BMW Group, General Motors Company, Toyota Motor Corporation, Harman International Industries, Continental AG, Volkswagen Group, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle to Vehicle (V2V) Communication Market Strategic Shifts & Innovations
The V2V market's evolution is defined by the transition from a hardware-centric safety feature to a platform for software-defined services and data monetization. This shift redefines value creation and competitive dynamics for automakers and technology suppliers alike.
Cellular V2X (C-V2X) technology provides direct and network-based communication for vehicles using 5G and LTE standards. Automakers and road authorities are rapidly adopting C-V2X in new vehicle platforms and smart city infrastructure projects. This advanced system is absorbing the core safety functions of older DSRC technology while adding superior performance and a clear path to 5G integration.
China's Ministry of Industry and Information Technology (MIIT) has mandated C-V2X as the national standard for intelligent connected vehicles. This policy compels automakers operating in China to integrate the technology, accelerating the build-out of a nationwide C-V2X network. The mandate most affects global automakers, who must now align their product roadmaps with China's standards to maintain market access.
A significant shift is underway from one-time hardware sales towards recurring revenue models based on software and data services. This change disrupts the traditional Tier-1 supplier relationship, as automakers increasingly partner with software firms for subscription-based feature updates. This trend is most prominent among premium European and North American automotive brands using enhanced connectivity to differentiate their offerings.
Vehicle to Vehicle (V2V) Communication Market Segmentation
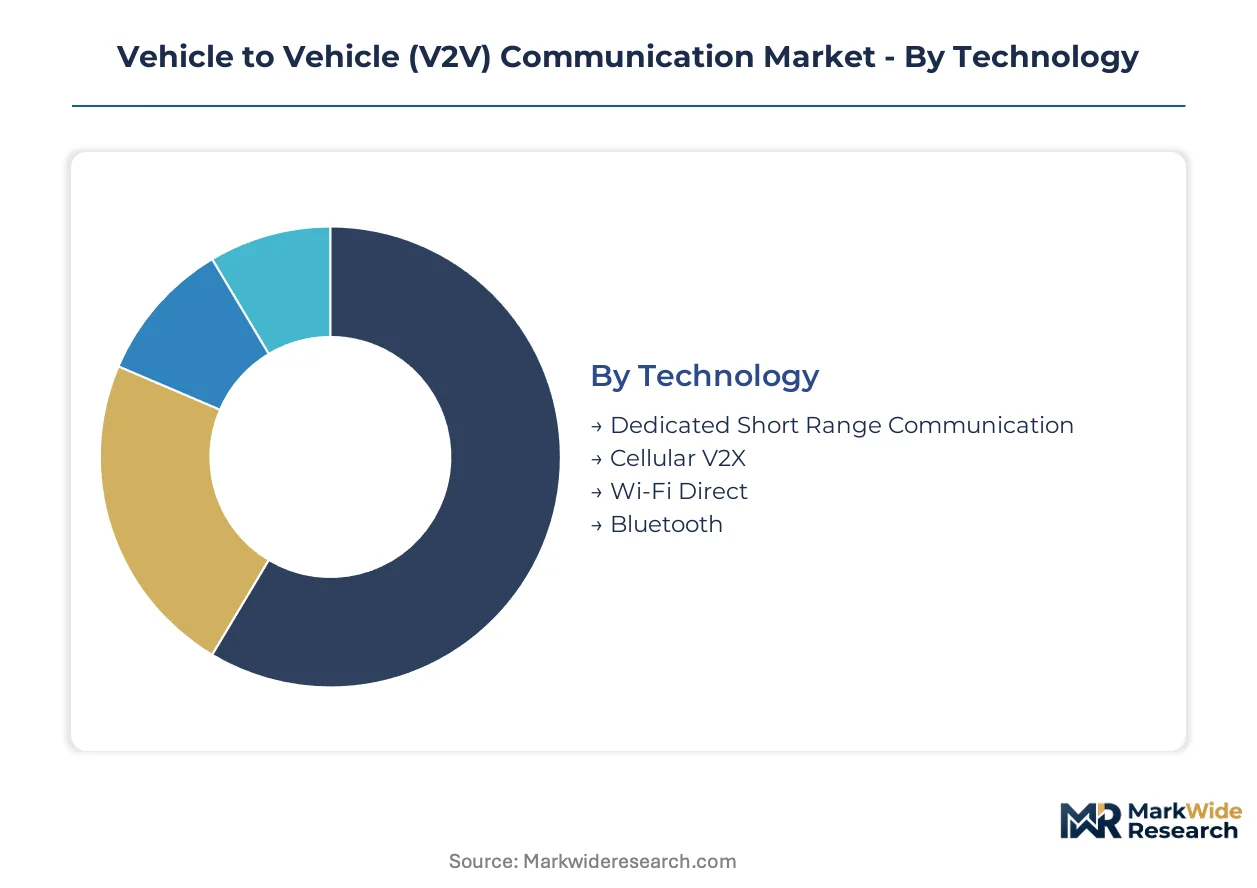
Segmentation analysis illuminates the diverse technological and operational facets driving the Vehicle to Vehicle (V2V) Communication Market. Understanding these distinct segments helps stakeholders identify specific growth vectors and allocate resources effectively. The market delineates functional applications, underlying technologies, and varied end-user adoption patterns.
Technology:
Supply concentration within V2V technology largely depends on the prevailing regulatory and infrastructure standards adopted by different regions.
- Cellular V2X:Cellular V2X (C-V2X) leverages 4G LTE and 5G cellular networks for direct and network-assisted communication between vehicles. Demand is concentrating in China, where the MIIT mandates its deployment for national intelligent transportation systems.
- Dedicated Short Range Communication:Dedicated Short Range Communication (DSRC) utilizes IEEE 802.11p for direct, short-range wireless data exchange between vehicles. Adoption is still present in some legacy systems, particularly in North America, driven by existing infrastructure investments.
- Wi-Fi Direct:Wi-Fi Direct offers peer-to-peer connectivity for short-range data exchange, suitable for localized V2V interactions.
- Bluetooth:Bluetooth provides ultra-short-range communication for specific in-vehicle or immediate proximity applications, often for pedestrian detection.
Today's leader: Cellular V2X. Tomorrow's challenger: Wi-Fi Direct.
Application:
V2V applications transform vehicle data into actionable intelligence, enhancing both individual vehicle safety and broader traffic efficiency.
- Safety Notifications:Safety Notifications involve immediate alerts for potential hazards like sudden braking, blind spot warnings, and collision avoidance. This foundational use case sees demand from automakers seeking improved NCAP safety ratings and premium service offerings.
- Traffic Management:Traffic Management applications optimize traffic flow, reduce congestion, and enable smart city initiatives through real-time data exchange. Demand is expanding fastest in urban areas globally, driven by infrastructure investments in intelligent transport systems.
- Driver Assistance:Driver Assistance systems use V2V data to augment advanced driver-assistance features, improving situational awareness.
- Parking Assistance:Parking Assistance leverages V2V to guide vehicles to available parking spots, reducing search time and urban congestion.
Safety Notifications hold the largest current share. Traffic Management applications are expanding most quickly.
End User:
End-user categories reflect the diverse stakeholders benefiting from V2V communication, from vehicle manufacturers to public service providers.
- OEMs:Original Equipment Manufacturers (OEMs) integrate V2V modules into new vehicles during production, offering embedded connectivity features. Demand for these integrated systems is driven by regulatory mandates and consumer expectations for advanced safety features.
- Fleet Operators:Fleet Operators deploy V2V systems to optimize logistics, enable platooning for fuel efficiency, and enhance driver safety. Adoption among commercial fleets is increasing in Europe and North America, aiming to reduce operational costs and insurance premiums.
- Public Transport:Public Transport entities use V2V for route optimization, emergency vehicle prioritization, and enhanced passenger safety.
- Insurance Companies:Insurance Companies explore V2V data for usage-based insurance models and accident reconstruction, influencing premium calculations.
OEMs represent the primary value driver. Fleet Operators are rapidly increasing their V2V deployments.
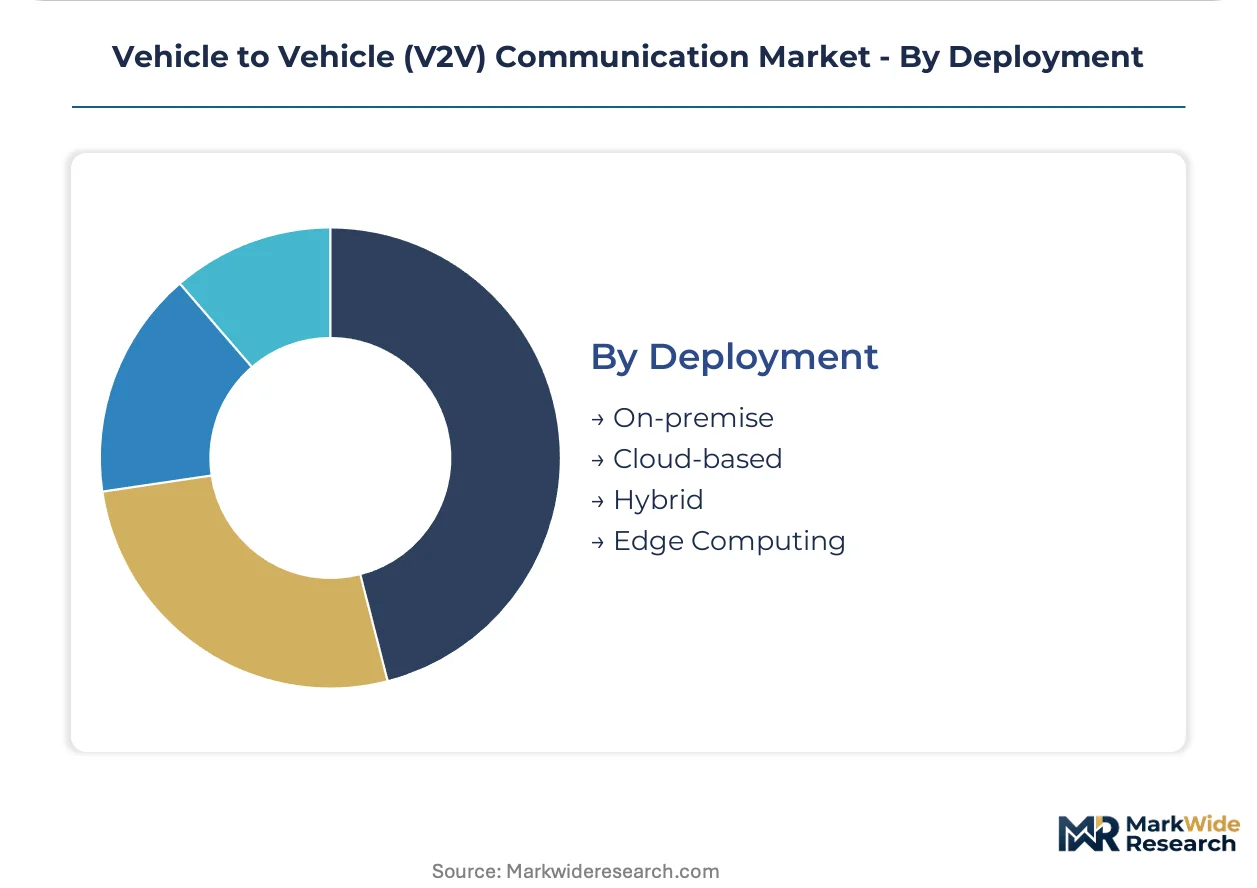
Deployment:
Deployment models for V2V systems vary based on infrastructure requirements, data processing needs, and scalability considerations.
- Cloud-based:Cloud-based deployments centralize V2V data processing and storage on remote servers, offering high scalability and accessibility. This model sees increasing demand from large-scale smart city projects requiring extensive data analytics capabilities.
- Edge Computing:Edge Computing processes V2V data closer to the source, reducing latency and bandwidth requirements for real-time applications. This architecture is critical for autonomous driving functions where immediate decision-making is paramount.
- On-premise:On-premise V2V deployments involve localized hardware and software installations, offering greater control over data security.
- Hybrid:Hybrid deployments combine on-premise and cloud resources, balancing data control with scalability and remote access.
Cloud-based solutions dominate current deployments. Edge Computing architectures are gaining share fastest for critical real-time V2V functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Vehicle to Vehicle (V2V) Communication Market sees varying regulatory landscapes influencing investment and technology adoption. Countries with clear mandates for C-V2X are attracting significant infrastructure development, creating an arbitrage opportunity. This dynamic environment shapes regional market concentrations and strategic priorities for automotive stakeholders.
China
China's V2V demand is driven by extensive government investment in intelligent transport systems and commercial fleet upgrades. The Ministry of Industry and Information Technology (MIIT) mandates C-V2X deployment, compelling automakers to integrate this technology. Major urban centers like Shanghai are key hubs for C-V2X network build-out and application testing.
United States
The United States market sees demand from automakers integrating V2V systems for improved safety ratings and advanced driver assistance. The US Federal Communications Commission (FCC) provides spectrum allocation for V2X services, supporting technological evolution. Detroit's automotive industry focuses on C-V2X integration into new vehicle platforms.
Germany
German demand for V2V technology stems from its leading premium automotive manufacturers and a focus on advanced traffic management. European Telecommunications Standards Institute (ETSI) standards and CE marking ensure interoperability for V2X systems. Automotive clusters in Bavaria actively integrate C-V2X into vehicle production for safety and efficiency.
Japan
Japanese automakers drive V2V demand through continuous innovation in vehicle safety features and smart infrastructure projects. Japan's Ministry of Economy, Trade and Industry (METI) promotes connected vehicle technologies and supports standardization efforts. Major cities like Tokyo are implementing V2X systems to enhance urban mobility and traffic management.
South Korea
South Korea's V2V market is propelled by significant 5G network expansion and government investment in intelligent transportation. The national government actively supports C-V2X deployment, aiming to position the country as a leader in future mobility solutions. Cities such as Seoul serve as testbeds for integrating V2X data with public transport and smart infrastructure.
Vehicle to Vehicle (V2V) Communication Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the V2V communication market. The market exhibits a tiered structure, with established automotive suppliers and technology providers forming the top echelon, alongside emerging software-centric firms. Strategic archetypes include integrated hardware-software solution providers, connectivity chipset specialists, and vehicle manufacturers. Companies are primarily engaging in strategic partnerships to expand their technological capabilities and geographic reach, alongside targeted portfolio diversification.
Within the technology provider segment, Qualcomm Technologies, Inc. anchors the C-V2X chipset space, representing a key enabler of advanced cellular communication for the automotive industry. Autotalks Ltd. occupies a position as a specialist offering hybrid DSRC and C-V2X solutions, providing deployment flexibility and catering to diverse infrastructure requirements. Meanwhile, General Motors Company, as an Original Equipment Manufacturer (OEM), exemplifies the integration of V2V systems directly into new vehicles, enhancing safety ratings and offering premium connectivity services to end-users globally.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| Autotalks Ltd. |
| BMW Group |
| General Motors Company |
| Toyota Motor Corporation |
| Harman International Industries |
| Continental AG |
| Volkswagen Group |
| DENSO Corporation |
Cost & Logistics Intelligence
Semiconductor chipset manufacturing costs significantly influence the overall pricing tiers for Vehicle to Vehicle (V2V) communication modules. These foundational component expenses cascade through Tier-1 suppliers and OEMs, shaping the final cost to end-users for embedded systems and aftermarket solutions. The ongoing transition to C-V2X technology further introduces new cost structures related to 5G integration and software development.
Pricing Analysis
OEM integration costs largely determine the final system price for V2V communication units. The dominant pricing model combines per-unit transactional sales for hardware with subscription-based licensing for software-defined features. Price differentiation stems from the complexity of the C-V2X solution and the level of regional regulatory certification. Pricing softness reflects intense competition among chipset providers and the push for mass market adoption. Commercial fleet operators exhibit the highest price sensitivity, balancing investment against operational savings.
Supply Chain Analysis
Regional distribution centers for automotive components manage the flow of V2V modules to manufacturing hubs worldwide. Supply concentration for critical components like semiconductor chipsets and specialized antenna modules centers in Taiwan, China, and South Korea. The supply chain draws heavily on embedded software from European and North American technology firms. Geopolitical tensions affecting semiconductor production represent a significant structural risk. Distribution runs primarily direct-to-OEM for new vehicle integration, with a smaller aftermarket channel for upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The V2V Communication Market presents a geographic-arbitrage opportunity, as China's mandated C-V2X deployment creates a different investment landscape compared to regions with DSRC legacy infrastructure.
For Market Incumbents: Cement strategic partnerships with telecommunications providers to ensure robust 5G network integration for C-V2X. Focus R&D investments on advanced software-defined features to counter emerging software-centric competitors. Secure long-term supply agreements for C-V2X chipsets to mitigate geopolitical supply chain risks. Invest in regional regulatory compliance certifications, such as CE marking in Europe, to maintain market access.
For New Entrants and Emerging Players: Online platforms for software-defined vehicle services offer a significant white-space opportunity. Target the development of edge computing solutions for real-time V2V data processing, particularly for autonomous driving applications. The most penetrable segment is emerging economies adopting C-V2X directly, bypassing legacy DSRC. An API-first integration strategy with smart city infrastructure can accelerate market entry.
For Investors and Strategic Acquirers: Asymmetric upside sits with software-centric firms specializing in V2V data analytics and cybersecurity solutions. Long-term viability hinges on companies that can monetize anonymized V2V data for diverse applications beyond basic safety. Acquisition targets should possess strong intellectual property in C-V2X software stacks or niche hardware components. The signal to watch is the global harmonization of V2X communication standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enhances recurring revenue models and differentiates offerings through customizable features. |
| C-V2X Chipset Supply Agreements | Ensures component availability and mitigates supply chain volatility for critical hardware. |
| Smart City Integration Partnerships | Expands V2V ecosystem applications and supports urban mobility management initiatives. |
| Data Monetization Platform Development | Unlocks new revenue streams from anonymized traffic and vehicle performance data. |
| Regulatory Compliance Certification | Secures market access and ensures interoperability across diverse regional transportation systems. |
Research Approach
Coverage spans China, United States, and Germany, with primary inputs from each region. The analysis combines in-depth primary interviews with OEM engineers, fleet managers, telecommunications regulators, and smart city planners. Secondary validation draws from MIIT reports, FCC filings, ETSI standards, and automotive industry association data. This approach ensures robust bottom-up and top-down triangulation of market insights.
Market sizing was modeled across technology, application, end-user, and deployment dimensions, providing granular insights over the projection horizon. The analytical framework incorporates V2V communication technology adoption rates, specific vehicle class integration, and regional regulatory mandates. Compound Annual Growth Rates (CAGRs) were derived through a comprehensive analysis of historical trends and projected future growth drivers. Key industry-specific forecast inputs include 5G network rollout pace and C-V2X penetration rates in new vehicles.
Regulatory shifts, technological obsolescence, and cybersecurity incidents are the dominant revision risks for market forecasts. All projections reflect assumptions documented within the analysis. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Automotive Personal Navigation Systems Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
India Connected Car Market
Telematics and Infotainment
India Fleet Management Software Market
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Roadside Assistance Software Market
Telematics and Infotainment
GCC Commercial Telematics Market