
 Europe Courier Market | 2026-2036
Europe Courier Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Courier Market Foresight
SMEs and marketplace sellers is bifurcating demand away from traditional corporate contract accounts. Deutsche Post DHL Group leverages its integrated European ground network to anchor next-day coverage across the continent. DPDgroup competes through dense pickup point infrastructure in France, Germany, and the United Kingdom. Evri specializes in low-cost, high-volume parcel streams for domestic e-commerce platforms.
Courier services encompass the collection, sorting, transport, and last-mile delivery of parcels and documents under time-definite or standard service commitments, typically operating through hub-and-spoke networks with automated sortation and GPS-tracked vehicles. The primary commercial purpose is bridging spatial and temporal gaps between sellers and buyers in business and consumer transactions. Express delivery commands premium pricing for time-critical shipments, while same-day delivery is expanding fastest in dense urban corridors where micro-fulfillment nodes shorten delivery radii. Business-to-consumer channels now generate the dominant volume flow, though business-to-business remains the margin pool for specialized freight and contract logistics.
The EU Green Deal and national low-emission zone mandates from regulators in Germany, France, and the United Kingdom are accelerating fleet electrification and carbon reporting requirements across courier operations. The EU AI Act introduces algorithmic transparency obligations for automated routing and dynamic pricing systems that carriers must integrate into compliance frameworks. Stakeholders must decide whether to absorb electrification costs through rate adjustments or operational restructuring before regulatory thresholds tighten further.
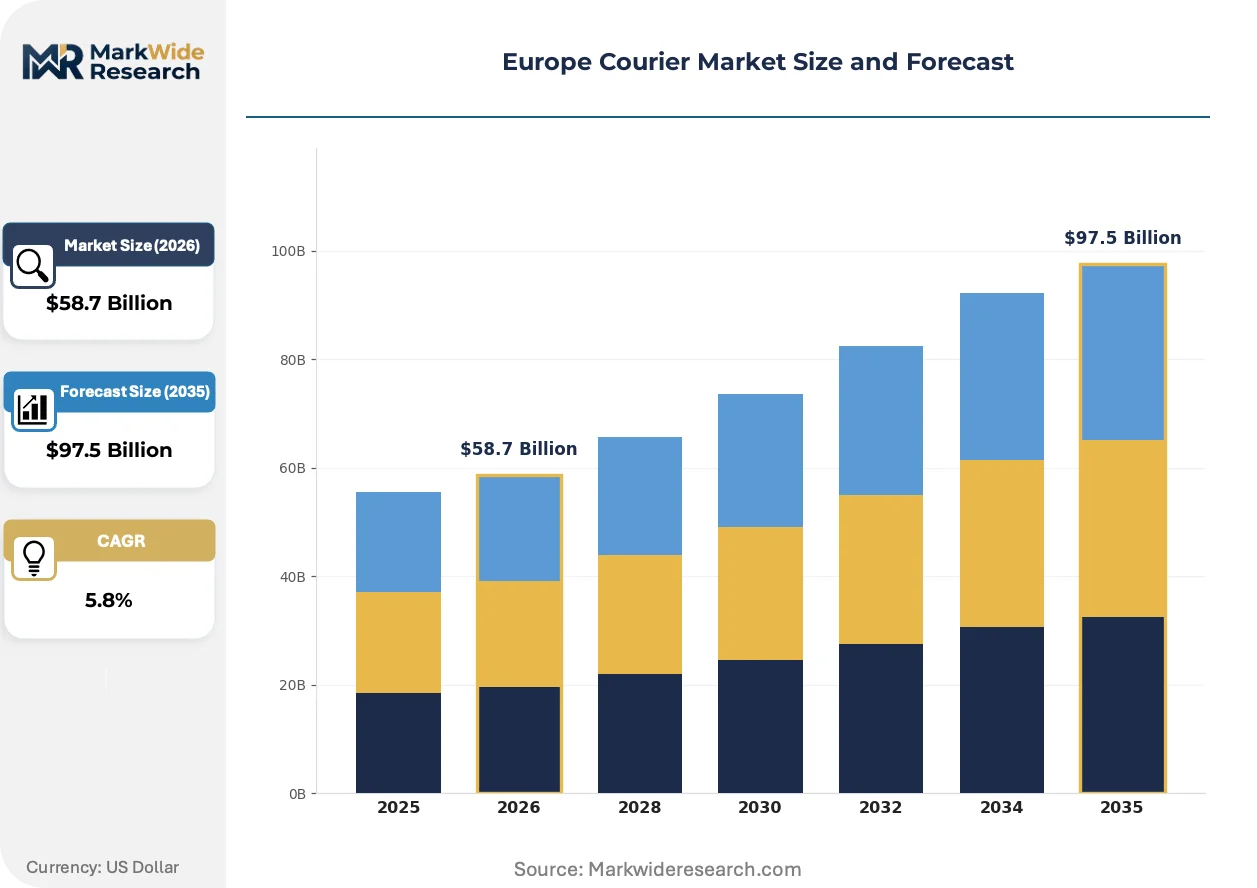
Market Dynamics
Parcel density in urban cores is forcing courier networks to abandon traditional hub-and-spoke models in favor of micro-fulfillment nodes and dynamic route optimization that compress last-mile delivery radii below five kilometers.
Growth Catalysts
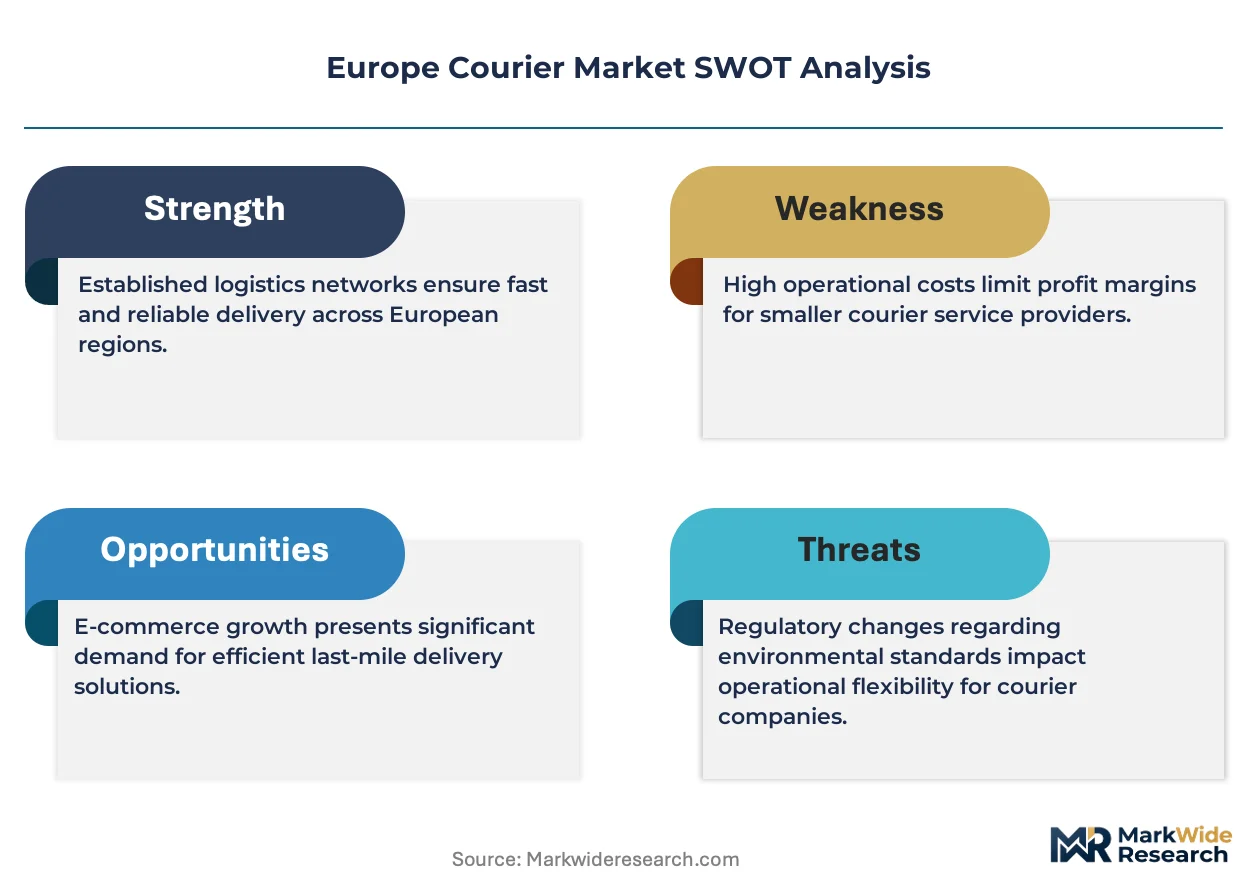
- EU Green Deal fleet mandates:Low-emission zone expansions in Germany, France, and the United Kingdom are compelling electrification investments that unlock preferential urban access and municipal contracts for compliant operators.
- E-commerce fulfillment surge:SME marketplace sellers now generate parcel volumes that rival traditional corporate accounts, diversifying revenue streams beyond B2B contract logistics.
- Cross-border corridor density:The Rhine-Alpine freight corridor connecting Rotterdam to Genoa concentrates intra-European parcel flows, enabling next-day coverage economics at scale.
Market Restraints
- Last-mile labor cost escalation:Driver shortages in France and Germany have pushed wage settlements above inflation, compressing margins on standard delivery services.
- Battery supply concentration:European courier electrification depends on Asian cell manufacturers, exposing fleet renewal timelines to geopolitical supply disruptions.
- Urban real estate scarcity:Micro-fulfillment node placement faces zoning restrictions and commercial rent spikes in London, Paris, and Berlin city centers.
Strategic Opportunities
- Polish and Romanian e-commerce penetration:These markets show parcel volume growth rates exceeding Western European averages, with infrastructure gaps that favor early-mover network investments.
- EU AI Act algorithmic transparency:Compliance requirements for automated routing systems create competitive differentiation for carriers with proprietary optimization engines.
- Reverse logistics integration:Returns processing for fashion and electronics marketplaces represents an underdeveloped service layer with premium pricing potential.
Industry Challenges
- Telematics and routing software integration:Legacy fleet management systems require costly API overhauls to interface with third-party dynamic pricing platforms.
- CSRD carbon reporting granularity:The Corporate Sustainability Reporting Directive mandates scope 3 emissions disclosure that many courier networks lack vendor data to satisfy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Courier Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Standard Delivery, Same-Day Delivery, International Shipping Delivery Model: Business-to-Business, Business-to-Consumer, Consumer-to-Consumer, On-Demand Package Size: Small Packages, Medium Packages, Large Packages, Pallets Vehicle Type: Vans, Bikes, Trucks, Drones |
| Companies Covered | Deutsche Post DHL Group, DPDgroup, FedEx Corporation, United Parcel Service, Royal Mail Group, Evri, General Logistics Systems, Hermes Group, Aramex International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Courier Market Shifts & Advancements
Courier operations are converging on autonomous sortation, predictive demand positioning, and electrified micro-fleets that collectively reconfigure cost structures and service level economics across European urban corridors.
Computer vision-enabled parcel dimensioning and automated sort induction is displacing manual handling at hub facilities. Deutsche Post DHL Group and DPDgroup have deployed these systems at their largest European gateways, reducing sort errors and labor headcount per throughput unit. The technology is displacing traditional fixed-conveyor infrastructure in favor of modular robotic cells that scale with volume seasonality.
The EU AI Act introduces mandatory algorithmic transparency for automated routing and dynamic pricing systems used in courier operations. Carriers must now document decision logic for load balancing and surge pricing, creating compliance overhead that favors larger operators with dedicated legal-technical teams. Express delivery segments face the steepest documentation requirements given their reliance on real-time algorithmic dispatch.
Buyer procurement of courier services is fragmenting from annual corporate contracts toward platform-integrated spot purchasing. SME marketplace sellers now select carriers through embedded APIs rather than negotiated agreements, compressing switching costs and amplifying price transparency. This pattern is most visible in the United Kingdom and Germany, where domestic e-commerce platforms have disintermediated traditional sales relationships.
Europe Courier Market Segmentation
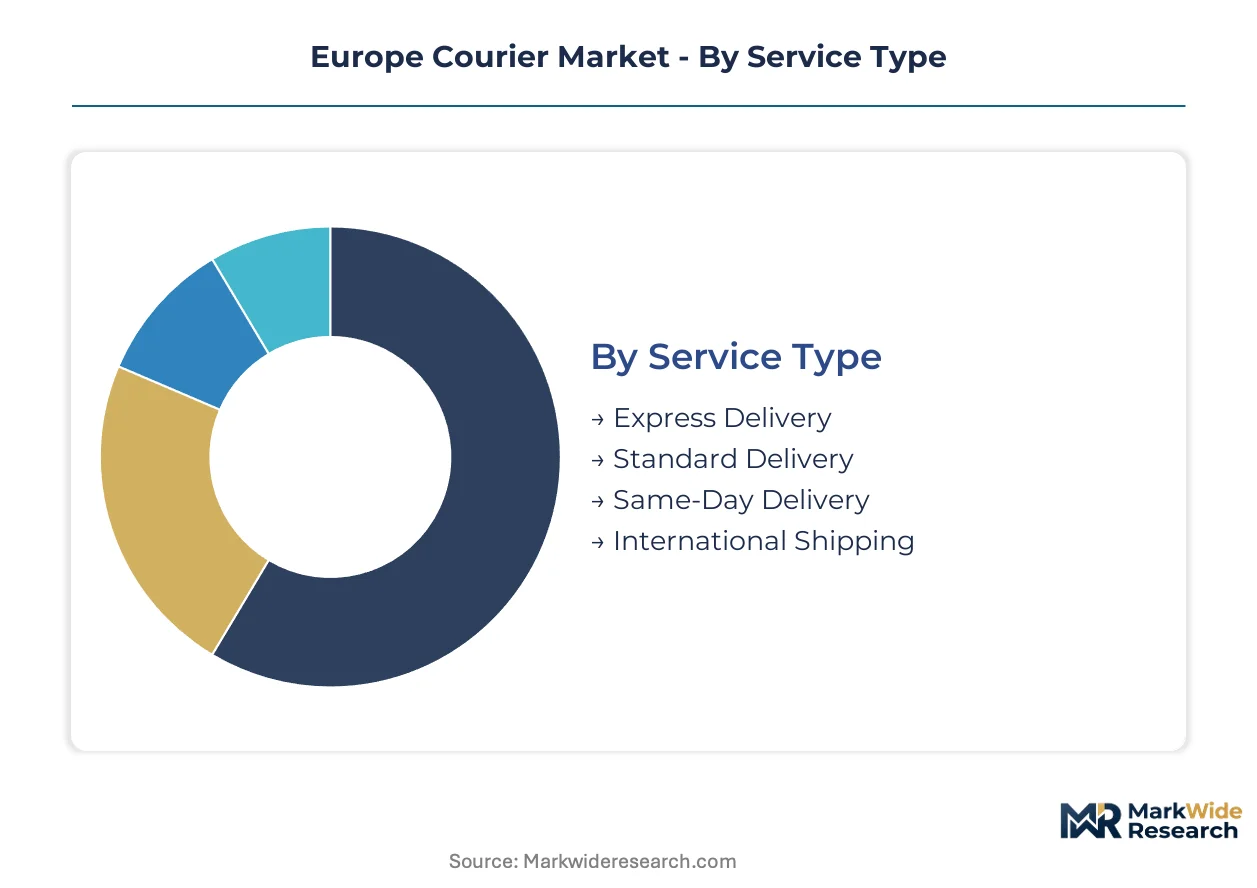
Courier segmentation in Europe reflects divergent cost structures and infrastructure requirements across service tiers. Each dimension carries distinct margin profiles and capital intensity that reshape competitive positioning.
Service Type:
Domestic express and standard delivery dominate intra-European flows, while international shipping concentrates on cross-border e-commerce corridors.
- Express Delivery:Time-definite shipments with guaranteed next-day or two-day windows command premium pricing and require dedicated air and ground network capacity. Demand concentrates in Germany, France, and the United Kingdom where corporate procurement and high-value e-commerce purchases justify cost premiums.
- Standard Delivery:Non-time-critical parcel movement through consolidated hub-and-spoke networks offers economy pricing for bulk shippers. SME marketplace sellers in Poland and Romania are driving volume expansion as e-commerce penetration deepens in these markets.
- Same-Day Delivery:Ultra-rapid fulfillment through urban micro-hubs serves dense metropolitan zones.
- International Shipping:Cross-border parcel movement across EU customs territory and external destinations.
Standard delivery commands the established base. The steepest expansion runs through same-day delivery.
Delivery Model:
Cost-to-serve varies dramatically by model, with B2C last-mile absorbing the highest per-unit operational expense.
- Business-to-Business:Scheduled collection and delivery between commercial entities leverages predictable routing and consolidated volumes. Manufacturing supply chains in the Rhine-Alpine corridor generate concentrated demand for time-definite freight services.
- Business-to-Consumer:Direct-to-home delivery from retailers and marketplaces now generates the dominant parcel volume flow across Europe. Residential dispersion in suburban France and exurban United Kingdom strains last-mile economics.
- Consumer-to-Consumer:Peer-to-peer parcel exchange through platform-mediated services.
- On-Demand:Immediate fulfillment triggered by real-time consumer request.
B2B commands the established base. The steepest expansion runs through B2C.
Package Size:
Handling infrastructure and vehicle utilization rates diverge sharply across dimensional tiers.
- Small Packages:Items under 2kg that fit standard letterbox or parcel locker dimensions dominate e-commerce apparel and electronics accessories. Fashion marketplace returns in the United Kingdom and Germany drive recurring volume.
- Medium Packages:Standard carton sizes between 2kg and 20kg represent the core parcel stream for general merchandise. Cross-border e-commerce from Dutch and Belgian fulfillment hubs concentrates demand for this tier.
- Large Packages:Bulky items requiring two-person handling or specialized equipment.
- Pallets:Unitized freight movement for B2B contract logistics.
Medium packages command the established base. The steepest expansion runs through small packages.
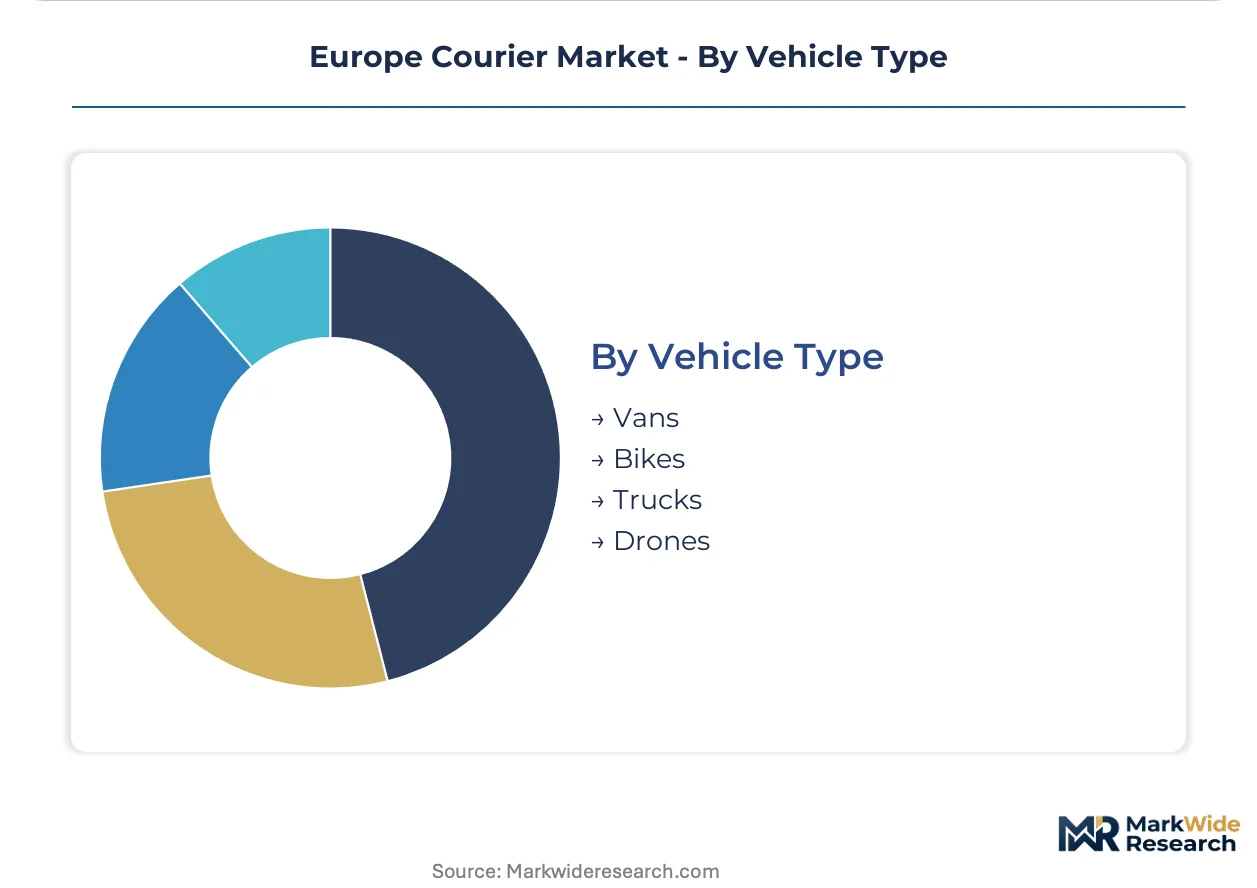
Vehicle Type:
Fleet composition is restructuring under EU Green Deal mandates and urban access regulations.
- Vans:Light commercial vehicles form the backbone of urban and suburban delivery networks. Low-emission zone expansions in London, Paris, and Berlin are accelerating electric van adoption.
- Bikes:Cargo bicycles and e-bikes enable zero-emission last-mile in dense city centers. Amsterdam and Copenhagen deployments demonstrate operational viability for sub-5km delivery radii.
- Trucks:Heavy goods vehicles handle line-haul and palletized freight between sortation hubs.
- Drones:Unmanned aerial systems for remote or urgent delivery applications.
Vans command the established base. The steepest expansion runs through bikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sortation hub concentration clusters along the Rhine-Alpine corridor, with Germany, France, and the United Kingdom absorbing the majority of cross-border parcel flows. Fleet electrification timelines diverge sharply across national regulatory regimes.
Germany
Industrial machinery exports and automotive component logistics sustain B2B express volumes through the Rhine-Ruhr and Stuttgart regions. The KBA enforces stringent low-emission zone standards that accelerate electric van deployment in Berlin, Munich, and Hamburg. Deutsche Post DHL Group operates Europe's densest automated sortation network from its Leipzig hub.
United Kingdom
Fashion marketplace returns and grocery e-commerce penetration drive parcel density in Greater London and the Midlands. The UK's net-zero transport strategy mandates phase-out dates for diesel commercial vehicles in urban centers. Evri processes high-volume domestic streams from automated hubs in Hinckley and Warrington.
France
Luxury goods exports and pharmaceutical cold chain requirements sustain premium express demand from Paris and Lyon. ANSM and CNIL oversight extends to logistics data handling under GDPR-aligned frameworks. DPDgroup maintains its densest European pickup point network across Île-de-France and Auvergne-Rhône-Alpes.
Netherlands
Rotterdam port throughput and Schiphol air cargo connectivity position the country as the primary Benelux distribution gateway. REACH compliance obligations affect packaging material specifications for cross-border shipments. Sortation facilities in Venlo and Amsterdam serve as consolidation points for EU-wide last-mile injection.
Poland
E-commerce penetration growth rates exceed Western European benchmarks as marketplace sellers expand fulfillment capacity near Warsaw and Kraków. EU cohesion fund infrastructure investments upgrade road corridors linking to German distribution networks. General Logistics Systems anchors Central European hub operations from its Poznań facility.
Europe Courier Market Competitive Landscape
Concentration sits with integrated pan-European networks and national specialists serving dense urban corridors. Three archetypes dominate: postal incumbents with legacy infrastructure, express specialists with time-definite air-ground networks, and low-cost parcel aggregators targeting SME marketplace sellers. Competitive moves center on automated sortation deployment and micro-fulfillment node placement in rent-constrained city centers.
Within the integrated network tier, Deutsche Post DHL Group and DPDgroup exemplify scale-driven operators with proprietary sortation assets. FedEx Corporation and United Parcel Service occupy positions as transatlantic express specialists leveraging air hub connectivity. Among domestic-focused aggregators, Evri represents the low-cost, high-volume archetype serving platform-integrated SME demand.
| Leading Market Players |
|---|
| Deutsche Post DHL Group |
| DPDgroup |
| FedEx Corporation |
| United Parcel Service |
| Royal Mail Group |
| Evri |
| General Logistics Systems |
| Hermes Group |
| Aramex International |
| Others |
Supply & Pricing Matrix
EU Green Deal fleet mandates gate both carrier qualification for urban contracts and the premium pricing tiers that compliant operators command in Berlin, Paris, and London low-emission zones. The regulation simultaneously raises supply-side compliance costs and creates price differentiation between electrified and legacy diesel fleets serving the same corridors.
Pricing Analysis
EU Green Deal mandates dictate the pricing tier structure across European courier operations. Three-tier pricing stratifies across premium express, standard deferred, and economy bulk levels, with electrification compliance costs embedded in the premium tier. Price differentiation rests on delivery speed guarantees and urban access certification under national low-emission zone regimes. Pricing pressure stems from SME marketplace sellers migrating toward platform-integrated spot purchasing that compresses contracted rate premiums. Fashion and electronics returns processors show least price sensitivity given integration complexity, while domestic standard parcel shippers exhibit highest elasticity.
Supply Chain Analysis
Battery cell supply from South Korea, China, and Japan underwrites European fleet electrification timelines and exposes renewal schedules to geopolitical disruption. Electric van production draws from Asian cell manufacturers, German chassis assembly, and French bodywork fabrication. Single-source vulnerability concentrates in lithium-ion cell supply where European courier operators lack qualified alternative sources. Distribution runs through manufacturer-direct fleet sales and captive leasing subsidiaries of major carrier groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reverse logistics integration for fashion and electronics marketplaces expands faster than core parcel delivery, creating a service-attach layer with premium pricing potential and recurring revenue characteristics.
For Market Incumbents: Fortify automated sortation capacity at Rhine-Alpine corridor hubs to defend throughput economics against low-cost parcel aggregators. Secure captive electric van supply agreements with battery cell allocation guarantees before 2025 regulatory thresholds tighten. Prioritize micro-fulfillment node placement in rent-constrained London and Paris centers through municipal partnership structures. For New Entrants and Emerging Players: Anchor in Polish and Romanian e-commerce corridors where parcel volume growth exceeds Western European benchmarks and infrastructure gaps favor early-mover network investments. Target SME marketplace sellers in these markets through platform-embedded API integration rather than direct sales relationships. Lead with returns processing capabilities as the differentiated service layer. For Investors and Strategic Acquirers: EU AI Act algorithmic transparency obligations reshape the acquisition landscape toward carriers with proprietary routing optimization engines and dedicated legal-technical compliance teams. Long-term viability favors integrated networks with dense European ground coverage and automated sortation assets over asset-light aggregators. Watch battery supply contract renegotiation cycles as inflection indicators for fleet renewal capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Node Expansion | Compresses last-mile delivery radii below five kilometers in Berlin, London, and Paris urban cores. |
| Electric Fleet Conversion | Unlocks preferential municipal contract access under KBA, TfL, and Paris low-emission zone mandates. |
| Reverse Logistics Integration | Captures premium pricing from fashion marketplace returns processing in United Kingdom and Germany. |
| Algorithmic Transparency Investment | Builds compliance differentiation under EU AI Act routing documentation requirements. |
| Polish-Romanian Network Buildout | Secures early-mover positioning in corridors showing fastest e-commerce penetration growth. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet operations directors, last-mile logistics managers, e-commerce platform integration leads, and municipal transport procurement officers. Secondary validation drew from EU transport regulator filings, national low-emission zone expansion schedules, carrier sustainability disclosures, and customs parcel flow data. Bottom-up volume modeling triangulated against top-down market sizing across service tiers.
Across the analysis window, projections integrate segment-level growth trajectories for express, standard, same-day, and international shipping tiers alongside vehicle type transition curves and urban density metrics. CAGRs were derived from parcel volume elasticity models against e-commerce penetration rates and fleet electrification investment schedules. Modeled inputs include SME marketplace seller growth curves and low-emission zone regulatory phase-in timelines.
Material uncertainties — battery supply disruption, labor settlement outcomes in France and Germany, and urban real estate cost spikes — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory enforcement consistency and e-commerce demand continuity. Practitioners should keep alternative scenarios live as EU Green Deal implementation pace and cross-border e-commerce tariff conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
South Korea International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
Colombia Cold Chain Logistics Market
Logistics and Shipping
Russia Freight and Logistics Market